
 Mexico Airbag Systems Market | 2026-2036
Mexico Airbag Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Airbag Systems Market Foresight
Asset-light leasing arrangements for inflator production lines is fragmenting the competitive landscape, allowing smaller tier-1 entrants to challenge established suppliers without full capital commitment. Autoliv Inc anchors North American airbag assembly through its Mexican manufacturing footprint. ZF Friedrichshafen AG leverages integrated sensor-to-deployment architectures to differentiate its portfolio. DENSO Corporation competes on pyrotechnic inflator specialization for compact vehicle platforms.
Mexico airbag systems are passive safety devices comprising fabric cushions, gas generators, and electronic control units that deploy within milliseconds of collision detection to reduce occupant kinetic energy transfer. Frontal airbags dominate installation volumes across light vehicle production, while curtain airbags represent the fastest-growing product category as side-impact protocols intensify. Gas inflator technology leads the technology segment due to thermal stability advantages, though hybrid inflators are gaining share where multi-stage deployment precision matters. OEMs capture the largest end-user value pool through long-term supply agreements tied to platform lifecycles.
Mexico's NOM-194-SCFI-2015 standard, enforced by the country's consumer protection agency, mandates frontal airbag inclusion in new vehicles and shapes product homologation requirements for all market participants. The IRA's North American content rules indirectly influence sourcing decisions by rewarding U.S.-Mexico-Canada regional supply chain integration. Stakeholders must monitor evolving U.S. NHTSA side-pole test protocols, as these frequently cascade into Mexican regulatory alignment through trade harmonization mechanisms.
Market Dynamics
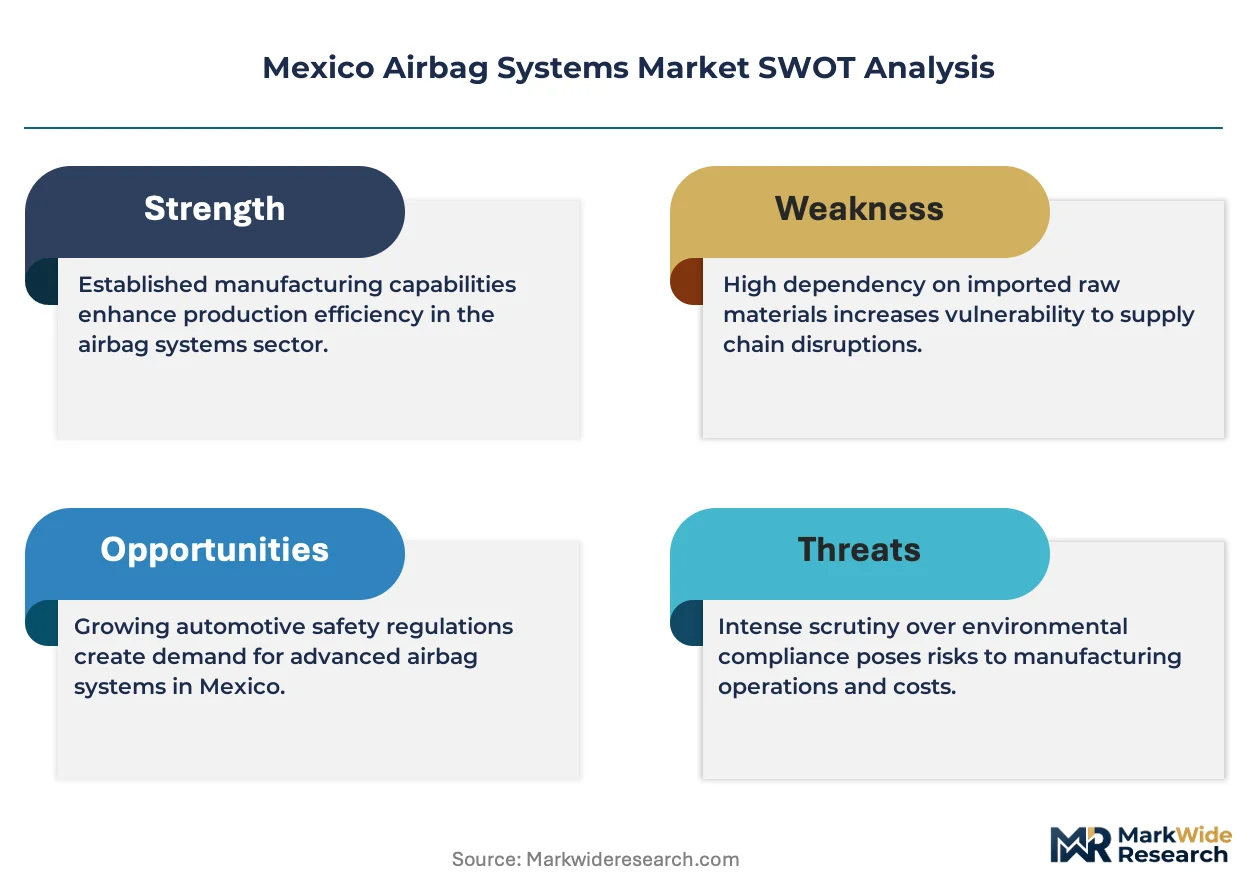
NOM-194-SCFI-2015 enforcement is tightening frontal airbag mandates across Mexican vehicle production, compressing homologation timelines and forcing tier-1 suppliers to accelerate inflator capacity deployment in the Bajío corridor.
Growth Catalysts
- Side-impact protocol expansion:Curtain airbag installation rates climb as Mexican regulators align with evolving U.S. NHTSA side-pole test standards through trade harmonization mechanisms.
- Hybrid inflator precision:Multi-stage deployment architectures gain traction in premium SUV platforms where occupant-position sensing requires variable force modulation.
- Guanajuato production clustering:OEM final assembly concentration in the Bajío automotive corridor creates localized demand pull for just-in-sequence airbag module delivery.
Market Restraints
- Sodium azide precursor volatility:Pyrotechnic inflator chemistry depends on azide compound supply chains concentrated in East Asian specialty chemical producers.
- Electronic control unit import dependence:Crash sensor and ECU fabrication remains concentrated in U.S. and German semiconductor fabs, exposing Mexican assembly to trans-border logistics friction.
- Homologation timeline compression:NOM-194-SCFI-2015 certification cycles for new inflator variants extend 14-18 months, freezing platform-specific innovation windows.
Strategic Opportunities
- Aguascalientes supplier park proximity:Greenfield inflator plants within 50 kilometers of Nissan and Mercedes-Benz assembly facilities capture logistics cost advantages.
- Knee airbag penetration:Lower limb protection modules remain optional in Mexican-market compact vehicles, creating white space as NOM-194 amendments expand.
- Recycled nylon 6,6 cushion fabrics:Circular material specifications in EU-originated OEM sustainability mandates are migrating into Mexican supply contracts.
Industry Challenges
- Pyrotechnic chemist talent scarcity:Specialized propellant formulation expertise concentrates in legacy U.S. and German defense-aerospace clusters, complicating Mexican R&D hiring.
- Legacy ECU architecture integration:12V electrical systems in existing vehicle platforms resist seamless integration with next-generation sensor fusion modules requiring higher bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Airbag Systems Market |
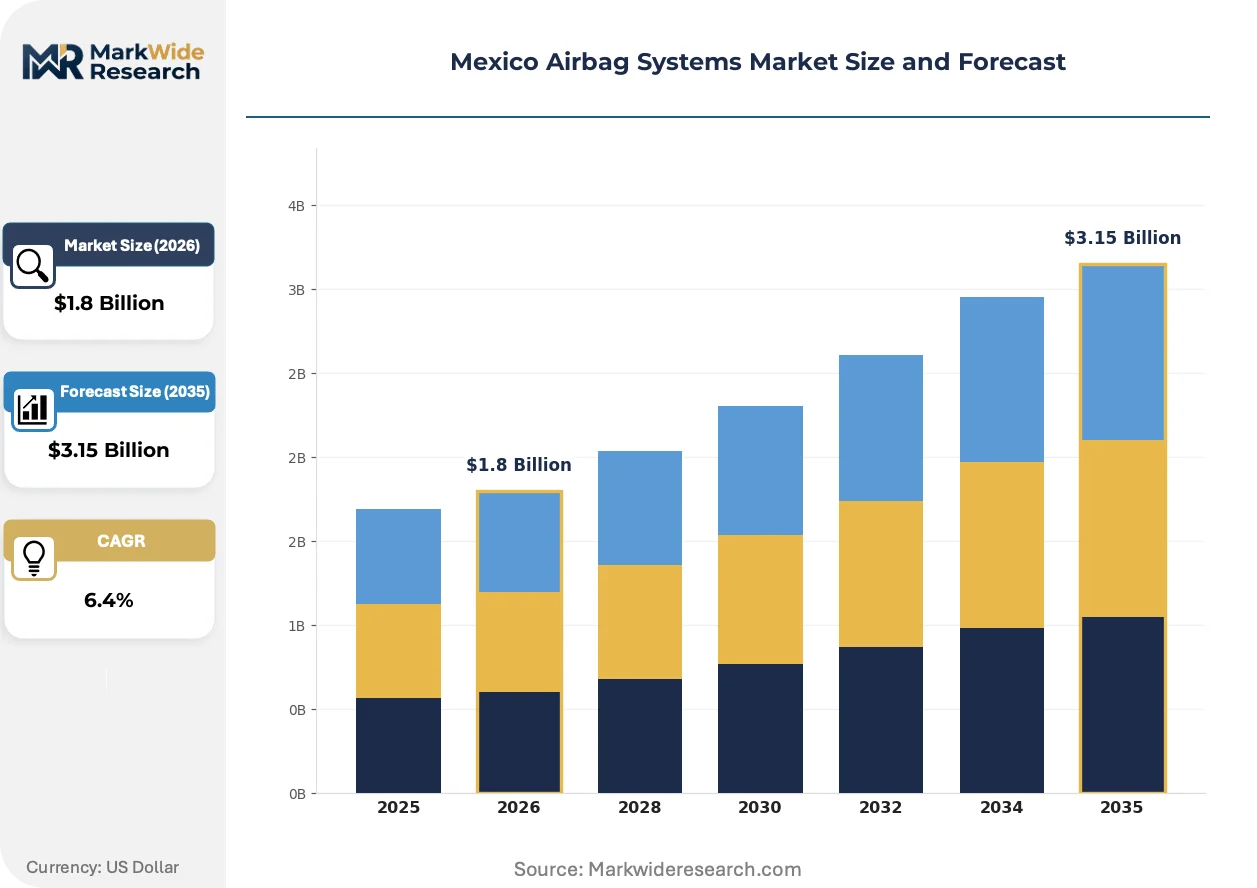
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frontal Airbags, Side Airbags, Curtain Airbags, Knee Airbags End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Gas Inflator, Pyrotechnic Inflator, Hybrid Inflator, Electric Inflator Installation Type: Built-in Airbags, Modular Airbags, Integrated Airbags, Add-on Airbags |
| Companies Covered | ZF Friedrichshafen AG, Autoliv Inc, DENSO Corporation, Continental AG, Robert Bosch GmbH, Hyundai Mobis, Key Safety Systems, Toshiba Corporation, Delphi Automotive PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Airbag Systems Market Shifts & Advancements
Deployment speed thresholds and occupant-classification precision are becoming the primary axes of supplier differentiation as Mexican OEMs benchmark against U.S. safety performance.
Hybrid inflator technology is collapsing the trade-off between thermal stability and multi-stage force modulation that previously forced platform engineers to choose between gas and pyrotechnic architectures. Premium SUV and light truck manufacturers in Puebla and Saltillo are adopting these systems at twice the rate of compact vehicle programs. The technology is collapsing development cycles for side-curtain and center-console airbag modules that must adapt to unbelted occupant scenarios.
NOM-194-SCFI-2015 amendments under review by Mexico's consumer protection agency are expected to mandate side airbag inclusion alongside existing frontal requirements. The regulatory expansion would force tier-2 fabricators to diversify cushion sewing capacity beyond driver-passenger modules. Compact crossover platforms assembled in Guanajuato face the steepest compliance cost escalation given their current minimal side-protection content.
Fleet procurement managers at Mexican rental and corporate leasing operators are unbundling airbag system warranties from comprehensive vehicle service contracts. Direct supplier relationships for inflator replacement and ECU recalibration are displacing OEM-dealer intermediation in high-mileage vehicle segments. This pattern concentrates in Mexico City and Monterrey metropolitan fleets where accident frequency drives higher replacement part consumption.
Mexico Airbag Systems Market Segmentation
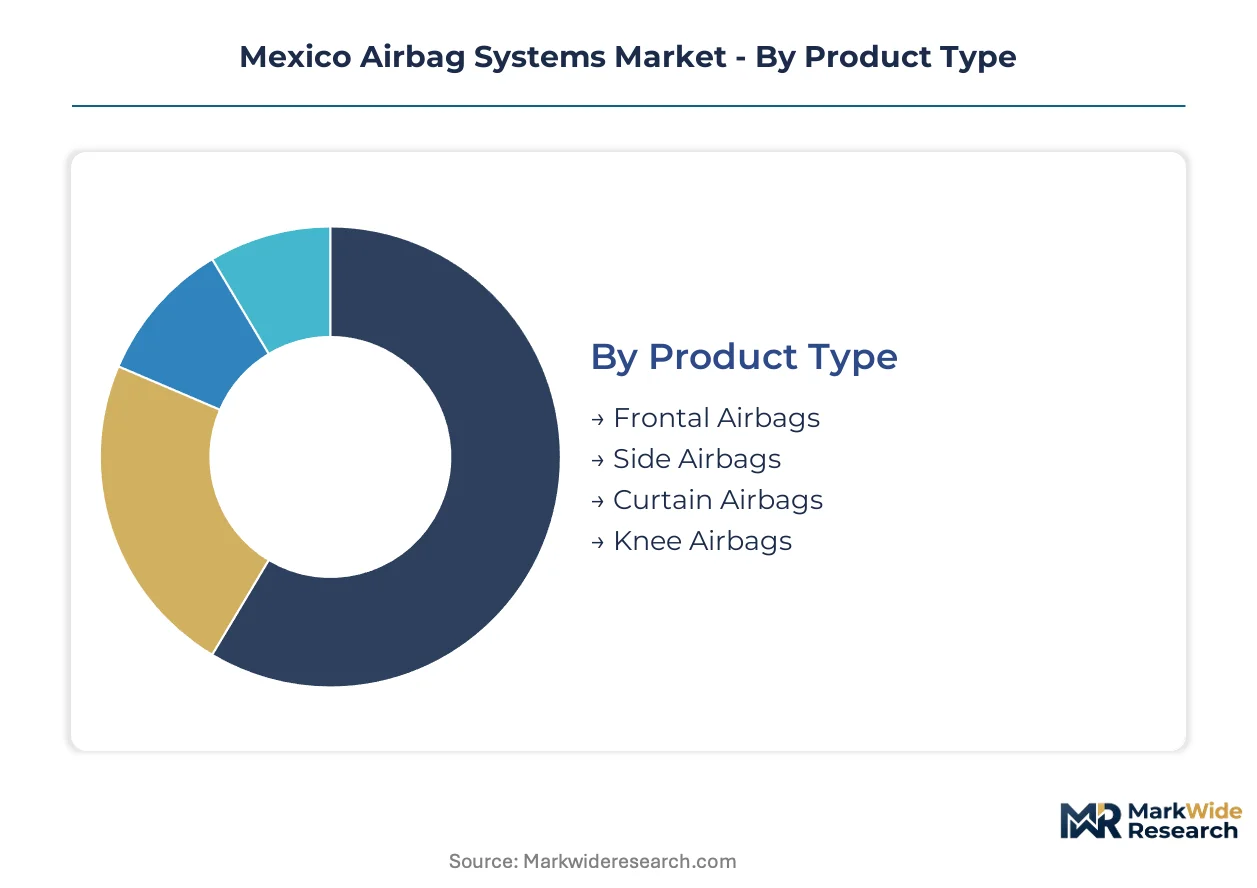
Airbag system segmentation in Mexico reflects divergent maturity curves across product generations and supply chain tiers. NOM-194-SCFI-2015 enforcement has compressed homologation cycles, forcing suppliers to prioritize segments with proven certification pathways while positioning for regulatory expansion.
Product Type:
Maturity spreads unevenly across protection zones, with frontal systems approaching commodity status while peripheral modules retain premium positioning.
- Frontal Airbags:Dual-stage driver and passenger modules deploy from steering wheel and dashboard housings using tethers to control cushion geometry. Bajío corridor OEMs source these in highest volumes for compact sedan platforms assembled in Guanajuato and Aguascalientes, though margin compression intensifies as NOM-194 mandates universal fitment.
- Curtain Airbags:Roof-rail mounted side-curtain systems extend protection across window apertures during rollover and side-impact events. Saltillo and Puebla light truck manufacturers are accelerating specification rates to align with anticipated NHTSA side-pole test harmonization, creating localized demand pull for extended-duration inflator variants.
- Side Airbags:Seat-mounted thorax protection modules deploy from seatback bolsters.
- Knee Airbags:Lower dashboard modules mitigate femur and pelvis loading in frontal impacts.
Frontal Airbags handles the majority of throughput; Curtain Airbags is the fastest mover on share.
End User:
Customer type stratification tracks vehicle lifecycle position and procurement authority concentration.
- OEMs:Original equipment manufacturers hold direct supplier relationships for platform-integrated safety systems, negotiating multi-year supply agreements tied to vehicle production schedules. Their procurement specifications cascade through tier-1 suppliers and determine inflator technology selection for each nameplate.
- Tier-1 Suppliers:Module integrators manage inflator-to-cushion assembly and just-in-sequence delivery to assembly plants.
- Vehicle Assemblers:Contract manufacturers operating in Mexican export zones coordinate airbag fitment within final assembly sequences.
- Aftermarket Providers:Independent distributors serve collision repair and fleet refurbishment channels.
OEMs dominate procurement volume; Tier-1 Suppliers are expanding most quickly as modular outsourcing accelerates.
Technology:
Inflator chemistry and energy storage architectures define the competitive technology frontier.
- Gas Inflator:Compressed argon or helium systems stored in high-pressure vessels deliver deployment through burst-disk release mechanisms. Their thermal stability under extreme cabin temperatures suits Guanajuato's high-altitude assembly environment where diurnal temperature swings stress pyrotechnic alternatives.
- Hybrid Inflator:Combined stored-gas and pyrotechnic architectures enable multi-stage force modulation for occupant-position sensing.
- Pyrotechnic Inflator:Solid propellant combustion generates inflation gas through sodium azide or nitrocellulose-based formulations.
- Electric Inflator:Electro-mechanical compression systems eliminate chemical propellants entirely.
Gas Inflator commands the installed base; Hybrid Inflator is climbing the fastest on specification rates.
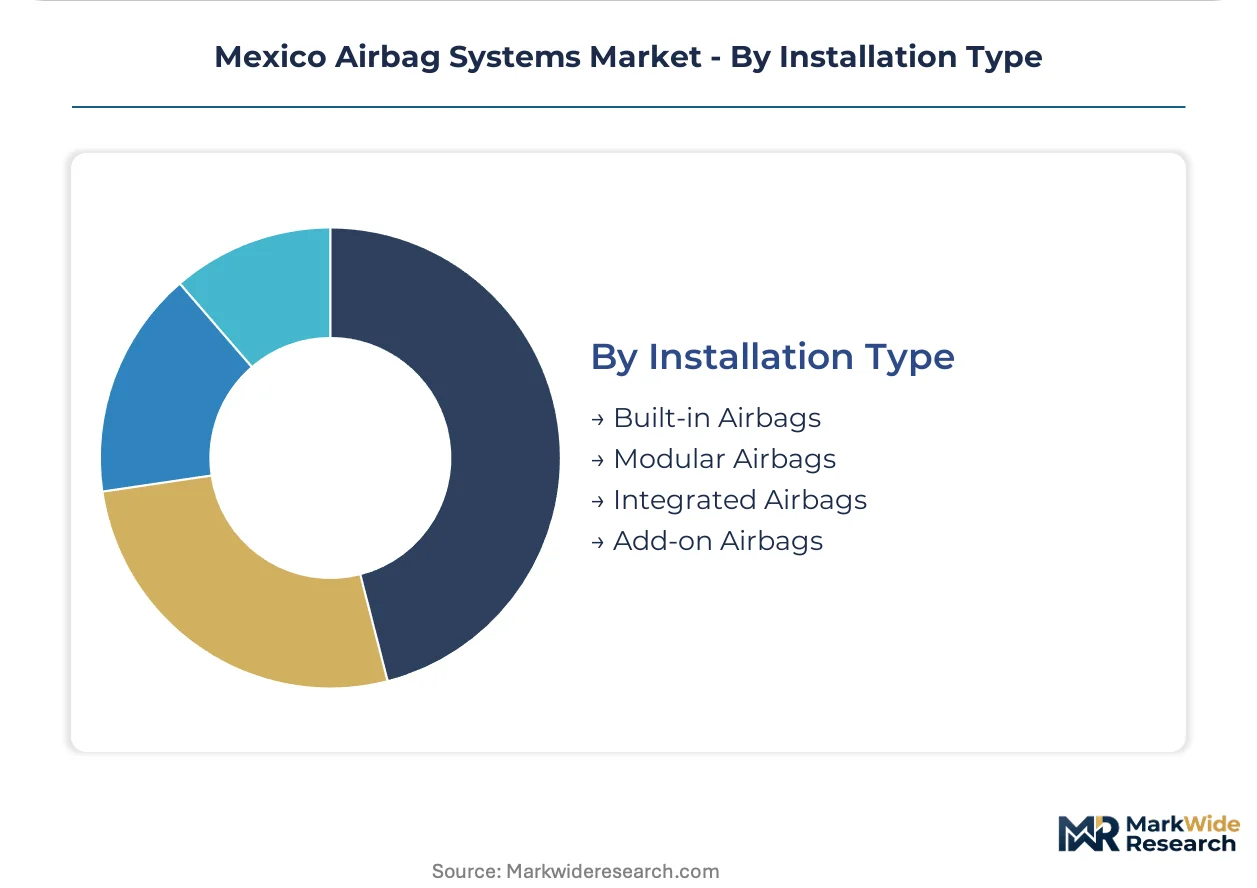
Installation Type:
Physical integration depth with vehicle architecture determines logistics complexity and engineering responsibility allocation.
- Built-in Airbags:Factory-integrated modules sewn into steering wheel, dashboard, and pillar trim during vehicle assembly require no post-assembly handling. Nissan's Aguascalientes plant and Mercedes-Benz's nearby facility specify these exclusively to eliminate line-side complexity.
- Modular Airbags:Self-contained units with standardized mounting interfaces enable supplier-managed pre-assembly.
- Integrated Airbags:Seamlessly embedded within seat structures or headliners during component manufacturing.
- Add-on Airbags:Retrofit kits for specialty vehicle modifications and armored vehicle conversions.
Built-in Airbags carries the production volume; Modular Airbags is gaining share fastest through supplier park proximity advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Guanajuato's supplier parks while logistics premiums erode margins in distant northern assembly zones. The Bajío corridor commands inflator module premiums through just-in-sequence proximity. Peripheral states absorb trans-border semiconductor transit costs that compress tier-2 margins.
Bajío Region
Dual-stage frontal module demand from Nissan Aguascalientes and Mercedes-Benz assembly anchors regional volume. NOM-194-SCFI-2015 enforcement accelerates homologation cycles for tier-1 suppliers clustered in Guanajuato. Inflator fabricators within 50 kilometers of final assembly capture logistics cost advantages unavailable to distant competitors.
Nuevo León
Light truck manufacturers in Saltillo drive curtain airbag specification rates for anticipated NHTSA side-pole test harmonization. Mexico's consumer protection agency coordinates regulatory alignment with U.S. protocols through trade integration mechanisms. Extended-duration inflator variants command localized demand pull from pickup and SUV platforms.
Mexico City Metro
Fleet procurement managers unbundle airbag warranties from comprehensive service contracts in high-mileage rental segments. NOM-194 mandates shape direct supplier relationships for inflator replacement and ECU recalibration. Collision repair channels concentrate replacement part consumption in the metropolitan zone.
Jalisco
Compact crossover platforms face compliance cost escalation as side airbag amendments advance through regulatory review. Guadalajara-area suppliers diversify cushion sewing capacity beyond driver-passenger modules. Regional fabricators position for NOM-194 expansion into thorax protection requirements.
Northern Border States
Export-oriented assembly in Tijuana and Matamoros ties sourcing decisions to IRA North American content rules rewarding regional supply chain integration. ECU import dependence from U.S. semiconductor fabs exposes trans-border logistics friction. Pyrotechnic precursor volatility from East Asian specialty chemical producers concentrates risk in distant supply lines.
Mexico Airbag Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in inflator chemistry and sensor fusion. The supplier base organizes around three archetypes: multi-national module integrators with Mexican manufacturing footprints, regional tier-1 assemblers leveraging supplier park proximity, and specialty chemical formulators focused on pyrotechnic propellants. Competitive moves center on asset-light leasing arrangements for inflator production lines and backward integration into crash sensor semiconductor sourcing.
Among the integrated module suppliers, Autoliv Inc, ZF Friedrichshafen AG, and DENSO Corporation exemplify divergent strategic positioning within the Mexican market. Autoliv anchors North American assembly through established Mexican manufacturing presence. ZF occupies a position emphasizing sensor-to-deployment architecture integration. DENSO represents specialization in pyrotechnic inflator systems for compact vehicle platforms. These three entities collectively illustrate the competitive spectrum from full-system integration to component-level focus.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Autoliv Inc |
| DENSO Corporation |
| Continental AG |
| Robert Bosch GmbH |
| Hyundai Mobis |
| Key Safety Systems |
| Toshiba Corporation |
| Delphi Automotive PLC |
| Others |
Supply & Pricing Matrix
The Laredo-Nuevo Laredo freight corridor's cross-border logistics costs cascade through Mexican airbag system pricing, concentrating margin power among Guanajuato suppliers within 50 kilometers of Nissan and Mercedes-Benz assembly while forcing distant tier-2 fabricators to absorb semiconductor transit premiums that compress their competitive position.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock inflator module pricing across platform lifecycles. Price differentiation separates NOM-194-certified frontal systems from optional knee and side-curtain modules awaiting regulatory mandate. Cost compression in compact vehicle segments intensifies as universal frontal fitment erodes supplier leverage. Fleet procurement managers in Mexico City exhibit highest price sensitivity through unbundled warranty negotiations, while premium SUV assemblers in Puebla tolerate premium hybrid inflator specifications.
Supply Chain Analysis
Export controls on crash sensor semiconductors limit fabrication concentration in U.S. and German fabs, constraining ECU availability for Mexican assembly. Pyrotechnic precursor supply draws from East Asian specialty chemical producers, creating single-source vulnerability for sodium azide compounds. Distribution runs through tier-1 module integrators clustered in Bajío supplier parks, with just-in-sequence delivery obligations compressing inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's airbag systems market operates as a substitution defense against active safety technologies—ADAS collision avoidance systems threaten to compress passive safety content per vehicle if regulatory mandates fail to expand protection zones.
For Market Incumbents: Pre-empt hybrid inflator commoditization by capturing sensor-to-deployment architecture integration that locks OEMs into proprietary ECU protocols. Backward integration into pyrotechnic chemistry insulates against East Asian precursor volatility. Defend Guanajuato supplier park positioning against asset-light entrants leasing inflator capacity without full capital commitment. For New Entrants and Emerging Players: Establish a beachhead in knee airbag modules where NOM-194 amendments have not yet mandated fitment, creating first-mover certification advantages before regulatory expansion. Target Jalisco's compact crossover platforms facing steepest compliance cost escalation. Pursue direct fleet relationships in Mexico City and Monterrey where warranty unbundling displaces OEM-dealer intermediation. For Investors and Strategic Acquirers: Regional tier-1 assemblers with supplier park proximity rights offer the most defensible acquisition profile, capturing logistics premiums unavailable to distant competitors. Monitor NOM-194 amendment progression through Mexico's consumer protection agency as the primary inflection signal—side airbag mandate timing determines cushion sewing capacity valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Inflator Production Line Leasing | Asset-light arrangements fragment competitive landscape by lowering tier-1 entry barriers. |
| Sensor-to-Deployment Architecture Integration | ZF's approach locks OEMs into proprietary ECU protocols that resist supplier switching. |
| Supplier Park Proximity Expansion | Aguascalientes greenfield sites capture just-in-sequence logistics cost advantages. |
| Pyrotechnic Chemistry Backward Integration | In-house propellant formulation mitigates East Asian precursor supply volatility. |
| Recycled Nylon 6,6 Cushion Development | Circular material specifications respond to EU-originated OEM sustainability mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet procurement managers. Secondary validation drew from NOM-194 regulatory filings, vehicle production databases, IHS Markit registration data, and SEC disclosures from listed safety system suppliers. Bottom-up segment sizing triangulated against top-down market value estimates.
Calibration anchored volume projections to named OEM production schedules and platform lifecycle commitments across the analysis window. Segmentation dimensions modeled include airbag product type, inflator technology chemistry, installation integration depth, and regional production cluster. CAGRs derived from slope analysis of historical fitment rates applied to announced capacity expansions, with hybrid inflator specification velocity and NOM-194 amendment timing as key sensitivity inputs.
Sensitivities concentrate around NHTSA side-pole test protocol harmonization timing and IRA North American content rule enforcement. Forecasts reflect documented assumptions on regulatory alignment mechanisms and semiconductor fab capacity allocation. Material shifts in NOM-194 amendment scope or pyrotechnic precursor trade flows would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Stolen Vehicle Tracking System Market
Automotive Safety and Security Systems
Car Safety Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market
Automotive Safety and Security Systems
Wearable Motorcycle Airbags Market
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market