
 Global Automotive Defogger System Market | 2026-2036
Global Automotive Defogger System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Defogger System Market Intelligence
Tier-1 automotive supplier consolidation is rebalancing the competitive landscape for defogger system components. Continental AG leverages its extensive electronics portfolio to integrate defogger controls with broader vehicle climate systems. Denso Corporation specializes in high-efficiency electrothermal elements for Japanese and North American OEMs. Valeo SA competes on advanced infrared systems for premium vehicle segments.
An automotive defogger system is an assembly designed to remove condensation, frost, and ice from a vehicle's windshields and rear windows. These systems typically function by passing an electric current through a resistive heating grid embedded in the glass, rapidly raising the surface temperature. While passenger vehicles constitute the largest application segment, commercial vehicles are a fast-growing area due to enhanced safety regulations. Within product types, traditional electric defoggers maintain a dominant share, but infrared systems gain traction in premium vehicles.
Vehicle safety mandates from bodies like the US National Highway Traffic Safety Administration (NHTSA) and China's GB standards set baseline performance requirements for visibility. In Europe, compliance with CE marking for automotive components ensures that defogger systems meet stringent safety and electromagnetic compatibility directives. For OEMs, the key decision revolves around balancing the cost of traditional resistive systems against the performance benefits of newer technologies like conductive coatings.
Market Dynamics
The market's core dynamic is the technological pivot from resistive heating grids to advanced conductive films. This shift is driven by vehicle electrification demanding energy efficiency and the proliferation of Advanced Driver-Assistance Systems requiring unobstructed sensor visibility for safe operation.
Growth Catalysts
- Safety Mandates:Vehicle safety regulations, including US NHTSA rules and China's GB standards, establish minimum performance requirements for windshield visibility, compelling the adoption of faster and more effective defogger systems across all vehicle classes.
- ADAS Integration:The expansion of Advanced Driver-Assistance Systems (ADAS) necessitates clear, unobstructed views for cameras and LiDAR sensors, creating direct demand for defogger systems that can guarantee ice-free and condensation-free sensor zones.
- Commercial Fleet Requirements:Demand within the commercial vehicle segment is accelerating, driven by fleet operators in Europe and North America prioritizing driver safety and vehicle uptime, which are directly improved by reliable all-weather visibility systems.
Market Restraints
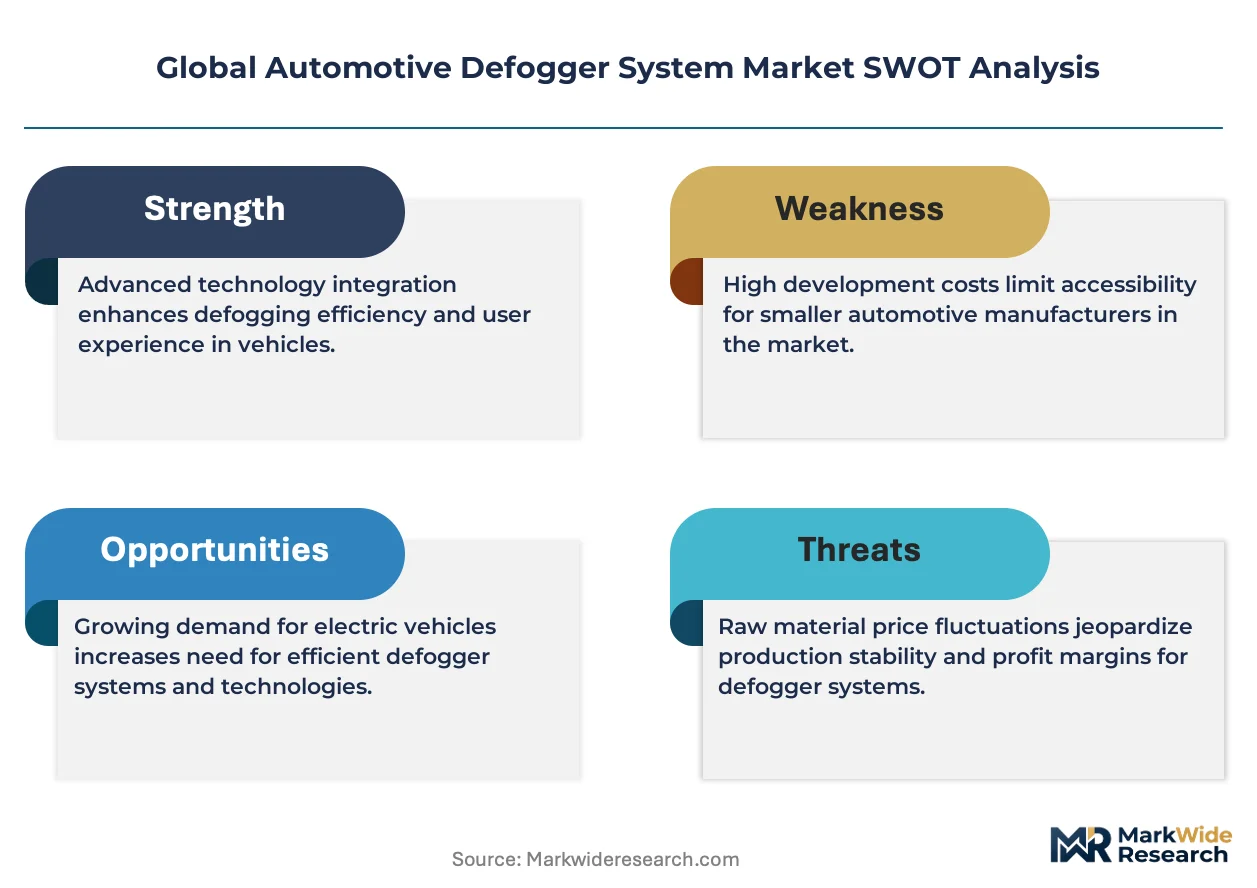
- System Cost:The bill-of-materials for newer technologies like conductive coatings and infrared systems remains significantly higher than for mature, mass-produced resistive wire grids, slowing adoption in economy vehicle segments.
- Integration Complexity:Engineering challenges in integrating advanced defogger power and control electronics with increasingly centralized vehicle architectures can extend development timelines and increase validation costs for automotive OEMs.
- Material Sourcing:The supply chain for key materials, particularly the silver paste used in resistive grids, is subject to commodity price fluctuations, creating cost volatility for component manufacturers and pressuring margins.
Strategic Opportunities
- Smart Glass Convergence:An opportunity exists to integrate defogger heating functions into multi-functional smart glass, combining visibility management with features like user-controlled tinting, embedded antennas, or integrated display capabilities for premium vehicles.
- Electric Vehicle Subsystems:Development of specialized small-scale defogger or de-icing systems for critical EV components, such as charging port covers and battery pack vents, presents a new application area to ensure operational reliability in cold climates. *Aftermarket Solutions: There is an opportunity to develop advanced, easy-to-install aftermarket defogger kits for commercial trucks and off-highway vehicles in regions like Southeast Asia and South America, where high humidity is a constant issue.
Industry Challenges
- Power Consumption Management:A key challenge for systems in electric vehicles is managing the high-power draw of rapid-heating defoggers without negatively impacting the vehicle's primary battery charge and overall driving range.
- Long-Term Durability:Component suppliers face the challenge of ensuring the long-term reliability and performance of thin-film conductive coatings against degradation from UV exposure, thermal cycling, and physical abrasion over a vehicle's lifespan.
- Software Standardization:The lack of a universal communication protocol for integrating defogger controls into varied OEM domain controllers complicates software development and limits the portability of control solutions across different vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Defogger System Market |
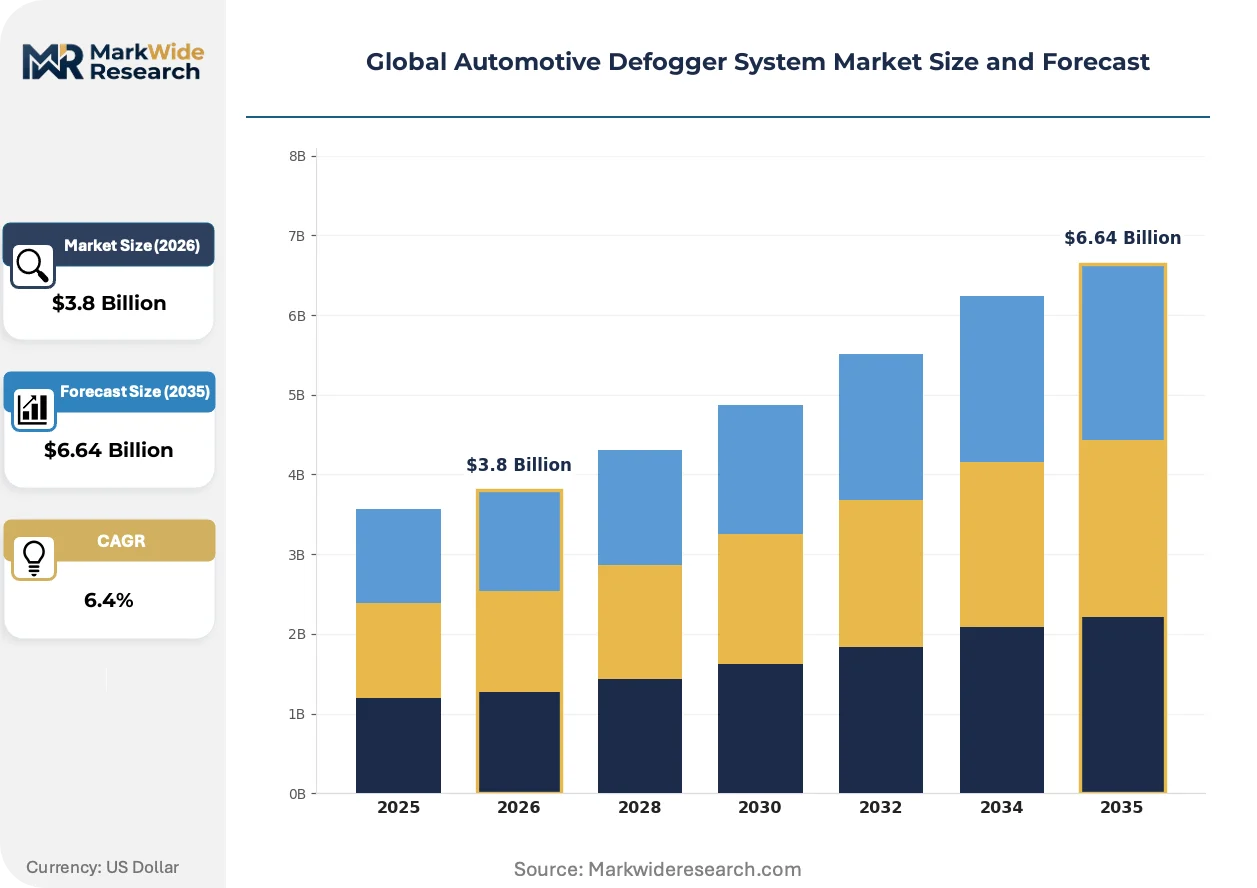
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Defoggers, Chemical Coatings, Hydrophobic Films, Infrared Systems Technology: Resistive Heating, Capacitive Heating, Conductive Coating, Electrothermal Elements Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-Road Vehicles End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Automotive Workshops |
| Companies Covered | Denso Corporation, Valeo SA, Robert Bosch GmbH, Continental AG, Mahle GmbH, Gentherm Incorporated, DuPont, NXP Semiconductors, Toyoda Gosei Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Defogger System Market Strategic Shifts & Innovations
Vehicle electrification and the operational needs of autonomous systems are transforming defoggers from a comfort feature into a mission-critical safety system. This evolution prioritizes energy efficiency, rapid heating speed, and optical clarity over simple component cost, reshaping system design and material selection.
Transparent conductive coatings offer uniform heating across a glass surface without the fine wires characteristic of traditional defoggers. Premium and electric vehicle segments are the primary adopters of this technology due to its aesthetic and functional benefits. In applications requiring flawless visibility for head-up displays and ADAS sensors, this advanced material solution is overtaking conventional resistive wire grids.
Regulations such as China's GB standards are setting more rigorous benchmarks for automotive safety components. These rules mandate specific time-to-clear performance for windshields, directly influencing OEM technology choices toward more powerful and efficient defogger systems. All vehicle categories sold in the Chinese market are affected, which pressures suppliers to innovate beyond legacy system capabilities.
Automotive OEMs are altering their sourcing strategies, moving from buying individual defogger components to procuring fully integrated smart-glass modules from Tier-1 suppliers. This trend disrupts the business model for standalone component makers, who must now form deep partnerships with glass manufacturers to remain specified in new vehicle programs. This procurement model is most visible among European automakers seeking to simplify their supply chains.
Global Automotive Defogger System Market Segmentation
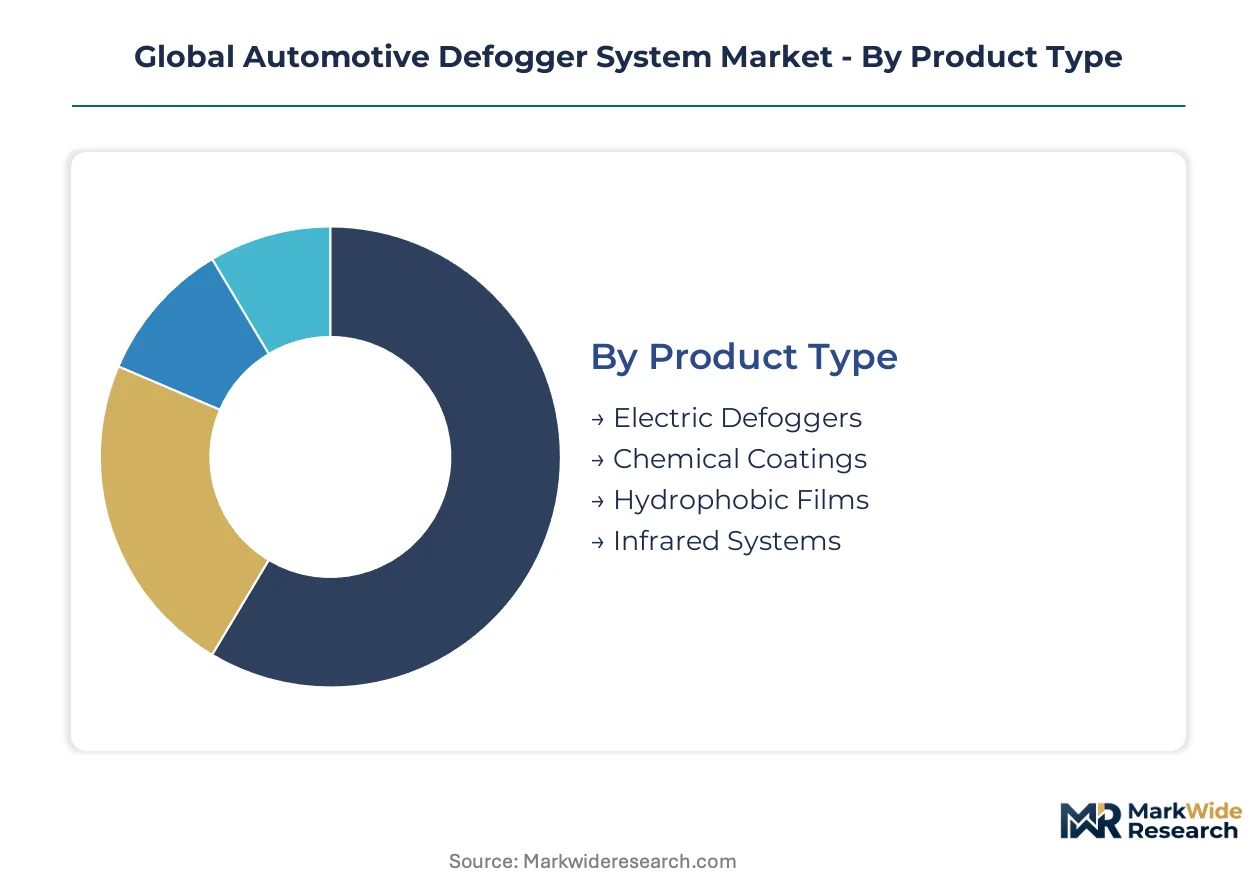
The global automotive defogger system market is dissected across several dimensions, reflecting the diverse technological maturity and application needs within the automotive industry. Understanding these segments clarifies where innovation is concentrating and where established solutions maintain their market presence.
Product Type:
Buyer preferences in defogger product types are often differentiated by desired performance characteristics and aesthetic integration within the vehicle cabin.
- Electric Defoggers:These systems utilize fine resistive wires embedded within glass to generate heat, effectively clearing condensation and ice. Demand remains strong in China and India, driven by high vehicle production volumes and baseline safety feature requirements.
- Infrared Systems:Advanced infrared defoggers project invisible heat onto the glass surface, offering rapid, wire-free clearing and superior optical clarity. Premium vehicle segments and electric vehicle manufacturers adopt this technology for its aesthetic benefits and energy efficiency.
- Chemical Coatings:These treatments apply a hydrophilic layer to glass surfaces, reducing surface tension to prevent fog formation.
- Hydrophobic Films:These films repel water, causing it to bead up and roll off, thereby maintaining visibility in wet conditions.
Volume sits with Electric Defoggers; growth tilts toward Infrared Systems.
Technology:
The underlying technological approaches define the efficiency and integration possibilities for defogger systems, influencing cost and performance trade-offs for OEMs.
- Resistive Heating:This conventional technology passes an electric current through embedded metallic wires or traces to generate heat. Mass-market vehicle segments in Europe and North America widely employ resistive heating due to its proven reliability and cost-effectiveness.
- Conductive Coating:Transparent conductive films applied directly to glass provide uniform heating without visual obstruction, enhancing aesthetic appeal and optical clarity. Electric vehicle platforms increasingly integrate conductive coatings to optimize energy use and support ADAS sensor performance.
- Capacitive Heating:This method uses an oscillating electric field to generate heat within a conductive material, offering precise temperature control.
- Electrothermal Elements:These components convert electrical energy directly into heat, often used in targeted applications like mirror defogging or specific window sections.
Traditional resistive heating remains foundational, while conductive coating technologies are gaining share fastest.
Application:
Defogger system applications span various vehicle categories, each with distinct operational requirements and regulatory drivers for visibility solutions.
- Passenger Vehicles:This segment encompasses sedans, SUVs, and hatchbacks, where defogger systems enhance driver comfort and safety. Regulatory bodies like the US NHTSA and European CE marking ensure minimum visibility standards for these vehicles, driving adoption.
- Commercial Vehicles:Trucks, buses, and vans constitute this segment, where defoggers are critical for fleet safety and operational uptime, especially in regions with diverse weather conditions like North America and Europe. Safety mandates from various national bodies compel robust system integration.
- Two-Wheelers:Defogger solutions for motorcycles and scooters primarily focus on helmet visors and small windshields for rider safety.
- Off-Road Vehicles:These vehicles, including construction and agricultural machinery, require durable defogging systems to maintain visibility in harsh environments.
Passenger vehicles represent the largest segment, with commercial vehicles showing significant expansion.
End User:
The end-user ecosystem for automotive defogger systems includes both direct manufacturing and post-sale service channels, each with specific procurement needs.
- OEMs:Original Equipment Manufacturers integrate defogger systems directly into new vehicles during the assembly process. Major global OEMs like Volkswagen, Toyota, and General Motors drive demand for advanced, fully integrated solutions from Tier-1 suppliers.
- Aftermarket Suppliers:These entities provide defogger components and kits for installation in vehicles after their initial sale. Demand from aftermarket suppliers is strong in regions like Southeast Asia and South America, where older vehicles may require upgrades or replacements.
- Vehicle Assemblers:These companies focus on the final assembly of vehicles, often relying on pre-integrated modules from Tier-1 suppliers for defogger systems.
- Automotive Workshops:Independent repair shops and dealerships offer installation, maintenance, and repair services for defogger systems, catering to individual vehicle owners.
OEMs drive initial system integration, while aftermarket suppliers address replacement and upgrade requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive vehicle manufacturing capacity and significant material sourcing for components like silver paste define a key production and demand center for automotive defogger systems. This region's rapid integration of advanced safety features influences global market dynamics. The widespread adoption of these systems ensures clear visibility for drivers across diverse climatic conditions.
China
China's robust automotive production volumes fuel substantial demand for defogger systems, integrating new safety features. Stringent GB standards mandate specific time-to-clear performance, compelling OEMs to adopt efficient solutions. Shanghai's manufacturing hubs witness increased investment in conductive coating technologies to meet rigorous domestic requirements.
United States
Demand for automotive defogger systems in the United States is driven by passenger vehicle safety and commercial fleet requirements. US National Highway Traffic Administration (NHTSA) regulations establish baseline performance for visibility. The Detroit automotive cluster actively integrates advanced defogger controls with broader climate systems for major domestic OEMs.
Germany
German premium vehicle manufacturers prioritize advanced defogger technologies for enhanced driver comfort and ADAS sensor performance. Compliance with CE marking ensures systems meet stringent safety and electromagnetic compatibility directives. Bavaria's automotive suppliers develop specialized infrared systems for high-end electric vehicles, focusing on energy efficiency.
Japan
Japanese automotive OEMs focus on high-efficiency electrothermal elements and conductive coatings, meeting evolving consumer expectations for vehicle safety. METI initiatives support research into advanced materials for automotive applications. The Nagoya region, home to major automotive players, sees concentrated efforts in developing integrated smart glass modules.
India
India's expanding automotive market, particularly for passenger and commercial vehicles, generates strong demand for cost-effective defogger solutions. BIS standards for automotive components ensure minimum quality and safety requirements. The Chennai automotive corridor experiences growth in electric defogger production for mass-market vehicles, balancing performance and affordability.
Global Automotive Defogger System Market Key Industry Players
Global majors compete with regional champions across technological innovation and supply chain integration within the automotive defogger system market. The competitive landscape shows a tiered structure, with established Tier-1 suppliers dominating integrated solutions. Strategic archetypes include diversified electronics conglomerates, specialized electrothermal element providers, and advanced material science companies. Key competitive moves involve strategic partnerships with glass manufacturers and portfolio diversification into smart glass functionalities.
On the premium-tier vector, Denso Corporation, a Japanese-headquartered automotive supplier, exemplifies specialization in high-efficiency electrothermal elements for global OEMs, particularly in Japanese and North American markets. Continental AG, a German-based technology company, anchors the market for integrated defogger controls within broader vehicle climate systems, leveraging its extensive electronics portfolio for comprehensive solutions. Valeo SA, a French automotive supplier, represents providers of advanced infrared systems, particularly for premium vehicle segments, focusing on wire-free optical clarity and aesthetic benefits across European automakers.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo SA |
| Robert Bosch GmbH |
| Continental AG |
| Mahle GmbH |
| Gentherm Incorporated |
| DuPont |
| NXP Semiconductors |
| Toyoda Gosei Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Vehicle electrification and the proliferation of ADAS systems compel automotive suppliers to innovate, driving investment in advanced defogger technologies and influencing pricing structures across the market.
Pricing Analysis
Warranty and service bundling often define the total cost of ownership for advanced defogger systems, influencing OEM procurement decisions. Per-unit transactional pricing dominates for traditional electric defoggers, while long-term contract-based arrangements are common for advanced conductive coating and infrared systems supplied to OEMs. Price differentiation stems from performance benefits like rapid clearing and optical clarity, alongside energy efficiency and aesthetic integration. Pricing pressure intensifies in economy vehicle segments due to bill-of-materials costs for newer technologies. Premium and electric vehicle segments exhibit lower price sensitivity, prioritizing technological benefits over initial component cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized material suppliers for conductive coatings, posing a risk to the broader supply chain. China remains a significant hub for manufacturing components like silver paste used in resistive grids, alongside Japan for high-efficiency electrothermal elements. Raw material dependencies include specialized conductive polymers and infrared emitter components. Commodity price volatility, particularly for silver paste, represents a key structural risk for component manufacturers. Distribution primarily runs through direct supply channels from Tier-1 automotive suppliers to OEMs for new vehicle integration, with aftermarket channels addressing replacement and upgrade requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story, where stringent safety mandates like China's GB standards establish a barrier to entry for non-compliant or less effective defogger solutions.
For Market Incumbents: Acquire specialized materials science firms to secure intellectual property in transparent conductive coatings and advanced heating elements. This protects against rapid technological shifts from agile startups. Invest heavily in R&D for next-generation energy-efficient systems that integrate seamlessly with smart glass modules. Deepen partnerships with automotive glass manufacturers to offer fully integrated, pre-certified solutions to OEMs, reinforcing market position against emerging component specialists.
For New Entrants and Emerging Players: Aftermarket distributors can target commercial vehicle fleets in high-humidity regions like Southeast Asia and South America. This segment offers a penetrable pathway for robust, easy-to-install defogger kits that address specific regional visibility challenges. Partner with electric vehicle subsystem integrators to develop niche defogging solutions for critical EV components, such as charging ports or battery thermal management vents, leveraging specialized expertise to enter the market.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized conductive coating developers and integrated smart glass module providers given the accelerating vehicle electrification and ADAS proliferation. Long-term viability is strong for companies offering energy-efficient, optically clear defogger solutions over the next decade. The signal to watch for inflection is the widespread adoption of conductive coatings in mass-market electric vehicle platforms by major global OEMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Conductive Coating R&D | Secures future market share by developing energy-efficient, aesthetically superior defogging solutions for EVs and premium vehicles. |
| Form Smart Glass Partnerships | Offers integrated visibility solutions to OEMs, simplifying procurement and enabling advanced multi-functional vehicle interiors. |
| Expand Commercial Vehicle Aftermarket | Captures unmet demand for robust, easy-to-install defogger systems in regions prioritizing fleet safety and uptime. |
| Develop EV Subsystem Defoggers | Creates new application areas for specialized heating elements, ensuring operational reliability of critical electric vehicle components. |
| Standardize Communication Protocols | Reduces integration complexity for OEMs, accelerating adoption of advanced defogger controls across diverse vehicle architectures. |
Research Approach
Multi-period observation of vehicle production volumes, technology adoption rates, and regulatory compliance benchmarks anchored the trend analysis, supplemented by interviews with Tier-1 supplier R&D heads, OEM procurement managers, and automotive glass manufacturers. Secondary validation involved reviewing automotive industry association reports, national safety administration publications like US NHTSA and China GB standards, and financial filings of leading market participants. Bottom-up analysis of component sales was triangulated with top-down validation against vehicle production data.
An input-output matrix integrated demand-side drivers with supply-side capabilities across the analysis window. Segmentation dimensions modeled included product type (electric, infrared), technology (resistive, conductive coating), application (passenger, commercial), end-user (OEM, aftermarket), and regional vehicle production forecasts. Compound annual growth rates were derived from historical trends, technology adoption curves, and projected regulatory impacts. Key forecast inputs included electric vehicle sales projections and Advanced Driver-Assistance Systems penetration rates.
Caveats apply where unforeseen macroeconomic shifts or accelerated technological breakthroughs could materially shift the outlook. Forecasts reflect current market conditions and anticipated developments within the automotive sector. Deviation in automotive production volumes or material commodity prices would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
South Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Automotive Speed Limiter Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Lane Departure Warning (LDW) Market
Automotive Safety and Security Systems
Asia Pacific Lane Departure Warning Systems Market
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
ICE Start and Stop System Market