
 Automotive Biometric Access System Market | 2026-2036
Automotive Biometric Access System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Biometric Access System Market Outlook
EU cybersecurity type-approval rules under UNECE R155 are rebalancing engineering budgets toward hardened authentication architectures. Robert Bosch GmbH leverages its Tier-1 supplier scale to embed fingerprint modules directly into steering-column electronics. Continental AG anchors European OEM programs with iris-scanning prototypes for premium EV lineups. Synaptics Incorporated differentiates through capacitive sensor arrays that operate across temperature extremes in exterior door handles.
An automotive biometric access system integrates physiological or behavioral sensors—fingerprint capacitive arrays, near-infrared facial imagers, voiceprint microphones, or iris cameras—with vehicle domain controllers to verify occupant identity before enabling ignition, personalization, or entry functions. These systems typically operate at false-accept rates below 0.001% and integrate with immobilizer gateways via encrypted CAN-FD or Ethernet backbones. Fingerprint scanners currently dominate unit shipments due to mature semiconductor supply chains and minimal power budgets, while facial recognition captures expanding share as 3D time-of-flight modules decline in cost. Multi-factor authentication configurations command premium positioning among fleet operators managing shared mobility pools where single-modality spoofing risks prove unacceptable.
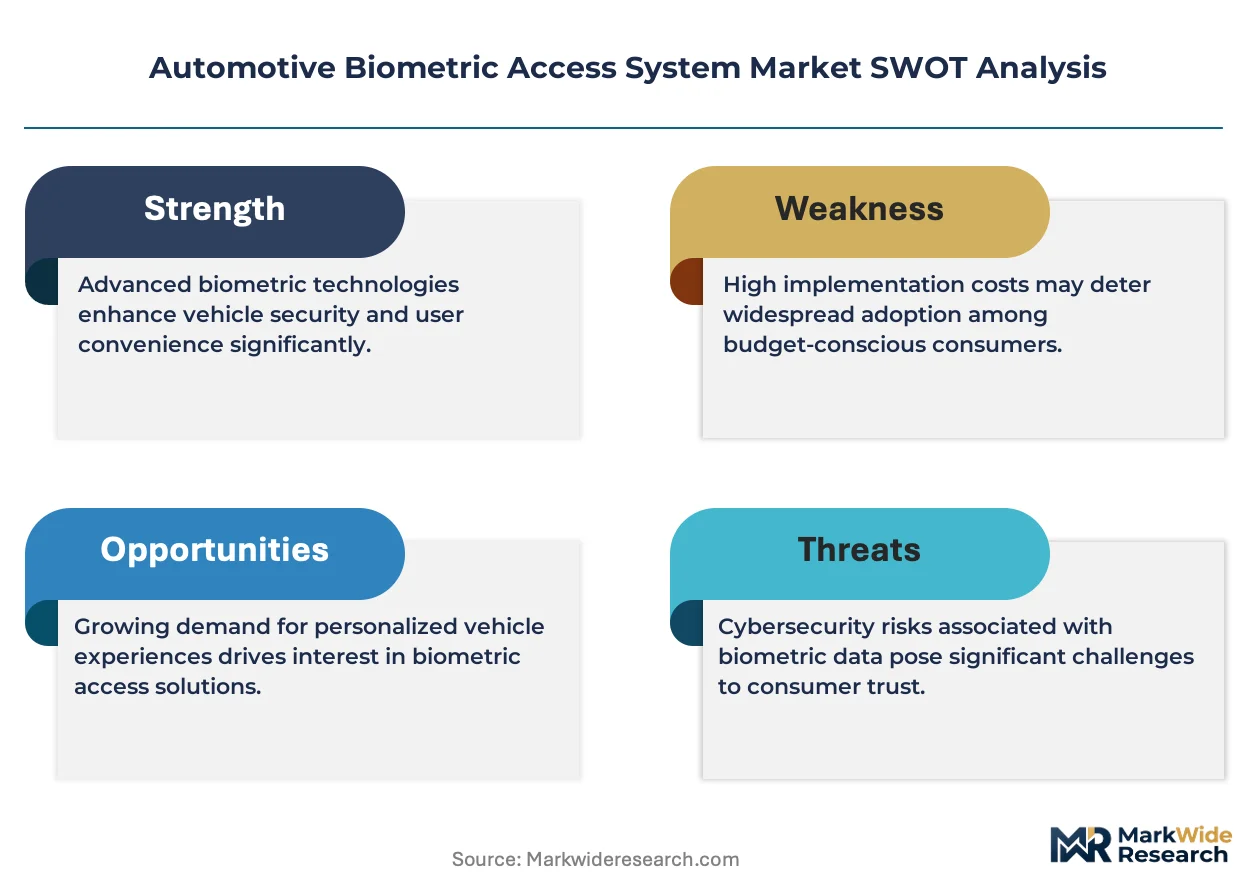
FDA does not regulate automotive biometrics, yet NHTSA references ISO 26262 functional-safety grades for driver-monitoring adjacent systems, while the EU AI Act imposes risk-classification obligations on biometric identification in vehicles. OEMs navigating these overlapping frameworks face divergent test-documentation burdens between North American and European homologation paths. Stakeholders must decide whether to architect modular authentication platforms that isolate region-specific compliance layers or absorb redundant certification costs across every vehicle program.
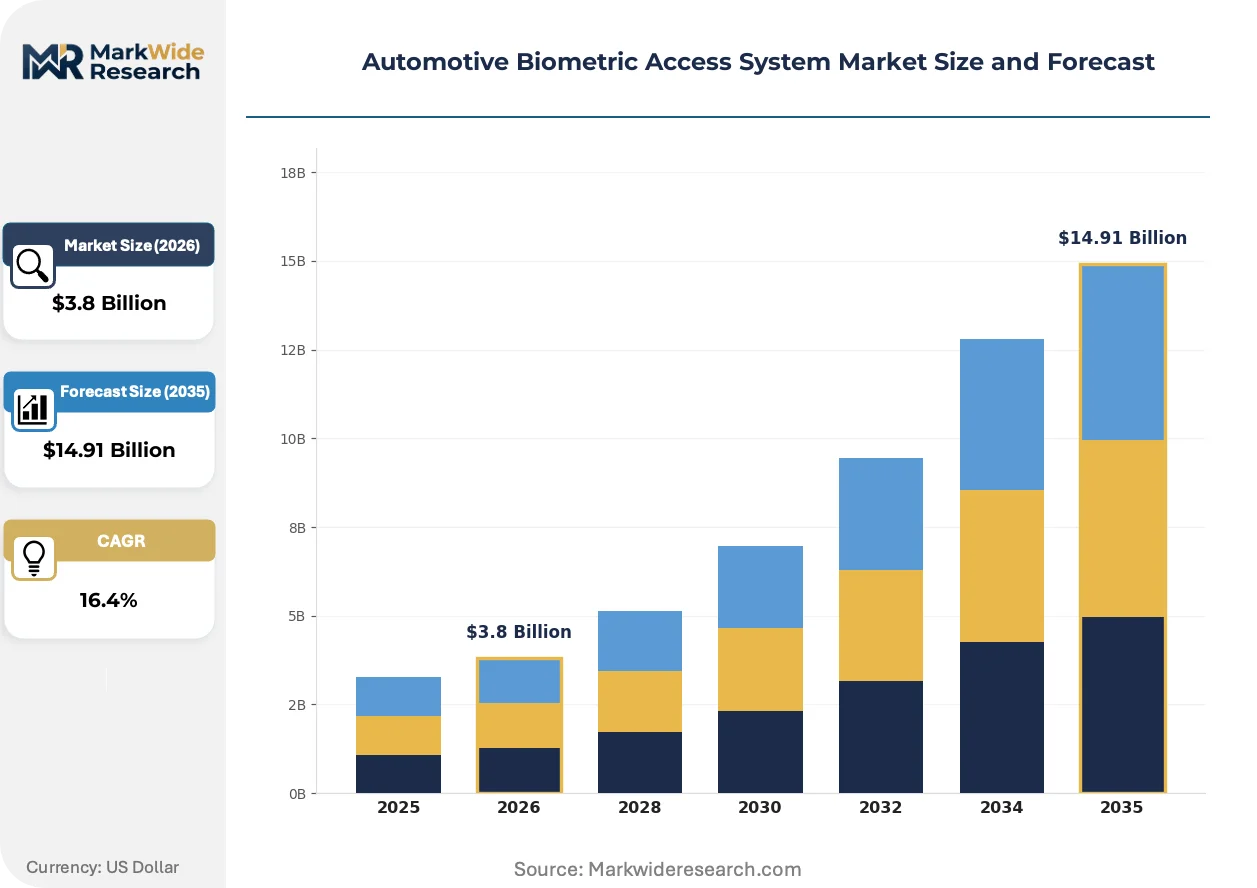
Market Dynamics
UNECE R155 cybersecurity type-approval rules are forcing OEMs to reallocate engineering budgets toward hardened authentication architectures, compressing development timelines for biometric integration programs across premium and mass-market vehicle lineups.
Growth Catalysts
- NHTSA driver-monitoring guidance:ISO 26262 functional-safety grades for adjacent systems are accelerating biometric adoption as OEMs seek compliance-ready authentication pathways.
- Fleet operator demand:Shared mobility pools require multi-factor configurations to mitigate single-modality spoofing risks in high-turnover vehicle environments.
- Capacitive sensor maturation:Fingerprint semiconductor supply chains now deliver modules that operate reliably across exterior temperature extremes.
Market Restraints
- Near-infrared imager cost concentration:3D time-of-flight module supply remains concentrated among a limited set of optical component specialists, constraining facial recognition scaling.
- EU AI Act risk classification:Biometric identification in vehicles faces heightened documentation burdens that lengthen homologation timelines.
- Encrypted backbone complexity:CAN-FD and Ethernet immobilizer integration demands specialized cybersecurity engineering that inflates per-unit authentication costs.
Strategic Opportunities
- Domestic OEM acceleration in China:Local manufacturers are rapidly adopting multi-factor entry systems, creating white space for sensor module suppliers.
- Iris-scanning convergence:Integration with premium EV steering-column electronics offers differentiation where fingerprint saturation is occurring.
- Voiceprint authentication:Behavioral biometrics for hands-free ignition enablement represent an underexploited modality in luxury segments.
Industry Challenges
- Cross-regional certification redundancy:Divergent NHTSA and EU AI Act documentation requirements force parallel test-track investments.
- Legacy immobilizer gateway integration:Encrypted CAN-FD retrofitting into existing vehicle architectures demands specialized firmware engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Biometric Access System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Scanner, Facial Recognition, Iris Scanner, Voice Recognition Technology: Passive Authentication, Active Authentication, Multi-Factor Authentication, Cloud-Based Solutions Application: Vehicle Security, User Identification, Access Control, Keyless Entry End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships |
| Companies Covered | Continental AG, Robert Bosch GmbH, Synaptics Incorporated, Fujitsu Limited, VOXX International Corporation, Methode Electronics, Fingerprint Cards AB, Valeo SA, HID Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Biometric Access System Market Strategic Shifts
Time-of-flight depth sensing is collapsing cost curves for facial recognition modules, while regulatory fragmentation between Washington and Brussels forces modular platform architectures that isolate compliance layers by geography.
Capacitive fingerprint arrays with enhanced thermal compensation are electrifying exterior door-handle applications. Tier-1 suppliers are embedding these modules directly into steering-column electronics for ignition-gating functions. The structural consequence is compressing power budgets while maintaining false-accept rates below biometric security thresholds.
EU AI Act risk-classification obligations are rebalancing engineering documentation toward algorithmic transparency. OEMs must now maintain audit trails for biometric identification decision pathways. Premium EV lineups face the steepest compliance burden, with manufacturers deploying dedicated compliance officers for European homologation.
Fleet procurement of authentication systems is consolidating around multi-factor specifications. Shared mobility operators are displacing single-modality contracts with bundled fingerprint-plus-facial configurations. South Korea represents the most visible geography for this shift, where domestic fleet operators pilot iris-scanning as a third authentication layer.
Automotive Biometric Access System Market Segmentation
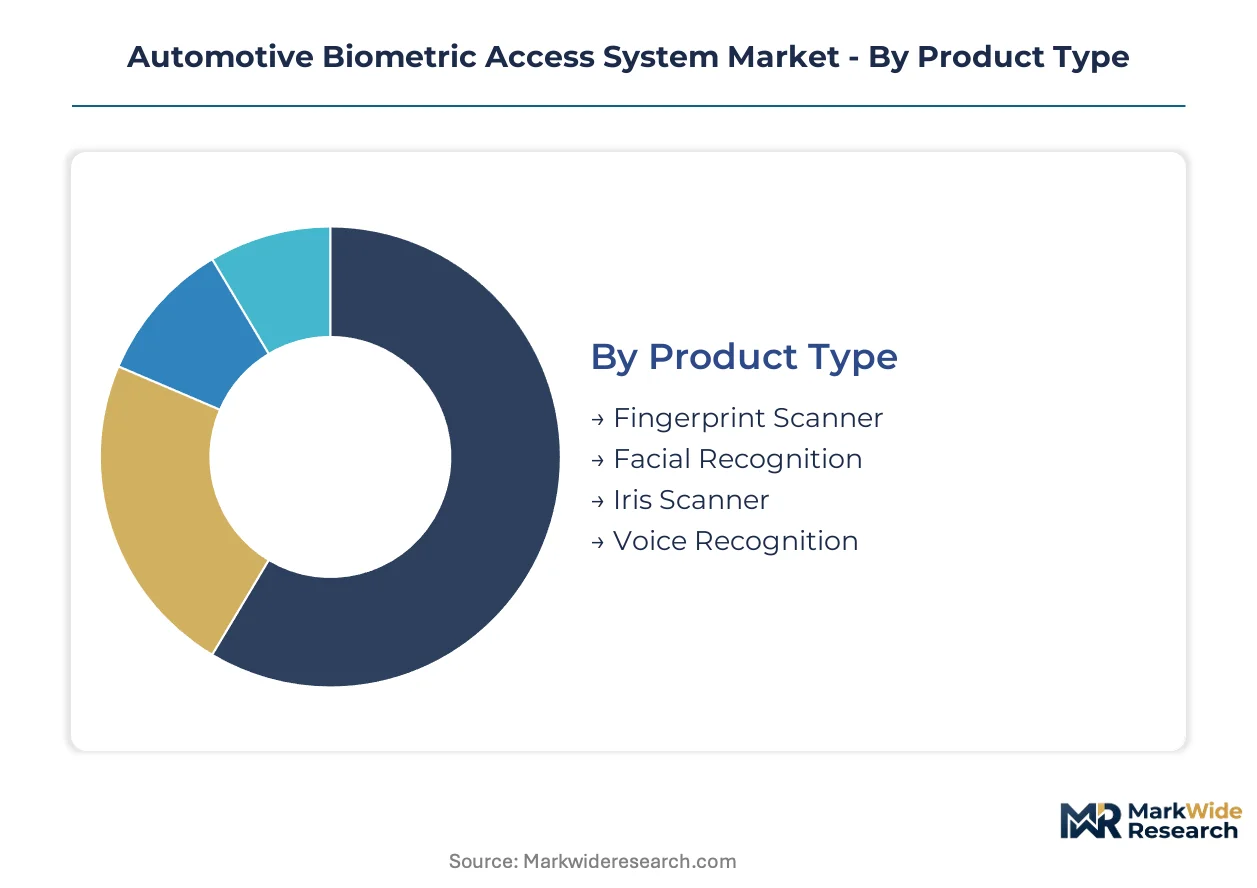
Biometric access architectures diverge sharply across vehicle programs. OEMs balance hardware standardization for scale against software customization for brand differentiation. The report maps four segmentation axes that shape procurement patterns and supplier positioning.
Product Type:
Standardized sensor modules compete against configurable multi-modality platforms across this category. Tier-1 suppliers optimize for thermal stability and false-accept thresholds rather than radical form-factor innovation.
- Fingerprint Scanner:Capacitive arrays with enhanced thermal compensation operate reliably across exterior temperature extremes. German and Japanese luxury automakers embed these directly into steering-column electronics for ignition-gating functions. Mature semiconductor supply chains compress unit economics.
- Facial Recognition:Near-infrared 3D time-of-flight modules verify occupant identity through depth-sensing imagers. South Korean domestic OEMs pilot these for driver personalization in premium EV lineups. Cost curves are collapsing as optical component specialists expand production capacity.
- Iris Scanner:High-resolution cameras capture unique patterns for ultra-low false-accept applications. Continental AG prototypes anchor European premium programs.
- Voice Recognition:Behavioral biometrics enable hands-free ignition without physical contact. Underexploited in luxury segments.
Most installed capacity flows through fingerprint scanners. Expansion is steepest in facial recognition modules.
Technology:
Authentication intensity determines power budgets, cybersecurity engineering overhead, and fleet operator willingness to pay premium positioning.
- Multi-Factor Authentication:Bundled fingerprint-plus-facial configurations mitigate single-modality spoofing risks. Shared mobility pools in South Korea displace single-modality contracts with these specifications. Command premium positioning where turnover frequency demands hardened security.
- Cloud-Based Solutions:Over-the-air biometric template updates enable fleet-wide credential synchronization. China domestic OEMs accelerate adoption for multi-vehicle household access management. Demand concentrates where cellular connectivity infrastructure is densest.
- Active Authentication:Continuous driver monitoring during vehicle operation. NHTSA driver-monitoring guidance accelerates integration adjacent to ISO 26262-compliant systems.
- Passive Authentication:Single-point verification at entry or ignition. Lowest per-unit cost for mass-market deployment.
Most engineering investment targets multi-factor architectures. Cloud-based solutions are climbing the fastest among technology tiers.
Application:
Functional criticality shapes hardware redundancy requirements and encrypted backbone specifications across use cases.
- Vehicle Security:Immobilizer gateway integration via encrypted CAN-FD prevents unauthorized engine start. EU cybersecurity type-approval rules under UNECE R155 mandate hardened authentication for this application. Specialized firmware engineering inflates development timelines.
- Keyless Entry:Exterior door-handle modules replace physical fobs with biometric verification. Synaptics capacitive sensor arrays operate across temperature extremes in this exposed mounting location.
- User Identification:Seat position, mirror angle, and infotainment preference recall upon driver verification.
- Access Control:Cabin compartment and cargo area authorization for authorized passengers.
Most regulatory pressure concentrates on vehicle security. Keyless entry is gaining share fastest as exterior sensor reliability improves.
End User:
Procurement scale and customization tolerance diverge between factory-installed programs and retrofit channels.
- OEMs:Factory-integrated biometric systems specified during vehicle architecture design. Robert Bosch GmbH leverages Tier-1 scale to embed modules directly into domain controller electronics. Long development cycles demand roadmap alignment three to four years ahead of production.
- Fleet Operators:Shared mobility pools require multi-factor configurations with centralized credential management. South Korean operators pilot iris-scanning as a third authentication layer. Displace single-modality contracts through consolidated procurement.
- Aftermarket Providers:Retrofit kits for installed base vehicles without factory biometric capability.
- Dealerships:Dealer-installed options for premium trim upgrades on existing inventory.
Most volume flows through OEM channels. Fleet operators are expanding most quickly as shared mobility pools scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems engineers and automotive cybersecurity specialists cluster in Germany's Stuttgart-Munich corridor, China's Shenzhen-Beijing axis, and South Korea's Seoul-Daejeon belt, anchoring biometric access development across three continents.
United States
NHTSA driver-monitoring guidance and fleet operator procurement from shared mobility pools drive authentication system demand. The agency references ISO 26262 functional-safety grades for adjacent biometric systems. Detroit's Tier-1 supplier ecosystem integrates fingerprint modules into steering-column electronics for ignition-gating functions.
Germany
Luxury automakers specify multi-factor configurations for driver personalization and theft prevention programs. EU cybersecurity type-approval rules under UNECE R155 mandate hardened authentication architectures for connected vehicles. Stuttgart-based Robert Bosch GmbH embeds fingerprint modules directly into domain controller electronics.
China
Domestic OEMs accelerate multi-factor entry system adoption for multi-vehicle household access management. The country's national automotive regulator enforces cybersecurity standards aligned with connected vehicle mandates. Shenzhen's sensor module suppliers capture white space as local manufacturers scale biometric integration.
South Korea
Fleet operators pilot iris-scanning as a third authentication layer in high-turnover shared mobility environments. The national automotive safety authority implements cybersecurity frameworks for biometric identification systems. Seoul-Daejeon corridor domestic OEMs deploy facial recognition for driver personalization in premium EV lineups.
Japan
Luxury automakers expand fingerprint and facial recognition integration for theft prevention and cabin personalization. METI guidelines shape functional-safety expectations for driver-monitoring adjacent biometric systems. Nagoya-based supplier networks prototype near-infrared 3D time-of-flight modules for depth-sensing applications.
Automotive Biometric Access System Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across fragmented authentication hardware tiers. Tier-1 automotive suppliers leverage steering-column and door-handle integration relationships to embed biometric modules, while semiconductor specialists optimize capacitive sensor arrays for temperature-extreme operation. Three archetypes dominate: diversified automotive electronics conglomerates with domain controller integration capabilities, biometric sensor pure-plays with semiconductor fabrication scale, and fleet-focused platform vendors with cloud credential management. Competitive moves concentrate on strategic partnerships for encrypted backbone integration and portfolio diversification into multi-factor authentication bundles.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG exemplify domain controller integration capabilities, while Synaptics Incorporated occupies a position among sensor pure-plays with capacitive array specialization. These three anchors represent distinct strategic positions: Stuttgart-based Bosch leverages Tier-1 scale for embedded steering-column electronics, Hanover-based Continental prototypes iris-scanning systems for premium EV programs, and San Jose-based Synaptics supplies temperature-compensated modules for exterior door-handle mounting.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Synaptics Incorporated |
| Fujitsu Limited |
| VOXX International Corporation |
| Methode Electronics |
| Fingerprint Cards AB |
| Valeo SA |
| HID Global Corporation |
| Others |
Value Chain & Pricing Dynamics
Fleet operator procurement of multi-factor authentication bundles is compressing unit economics for single-modality suppliers and forcing sensor module vendors toward integrated platform pricing. NHTSA driver-monitoring guidance and EU AI Act compliance documentation are adding certification-cost layers that tier-1 suppliers must absorb or pass through.
Pricing Analysis
Bundled multi-factor configurations against unbundled single-modality modules define the pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates OEM factory-integrated systems from fleet operator procurement bundles and aftermarket retrofit kits. Price differentiation rests on ISO 26262 functional-safety certification grades and thermal-compensation specifications for exterior mounting. Pricing pressure stems from collapsing cost curves in 3D time-of-flight optical components. Fleet operators exhibit highest price sensitivity due to volume procurement and centralized credential management requirements.
Supply Chain Analysis
Reverse-logistics flows for defective exterior door-handle modules and steering-column electronics are creating regional refurbishment hubs in Germany and South Korea. Semiconductor fabrication for capacitive sensor arrays concentrates in Taiwan, South Korea, and China. Near-infrared imager components draw from specialized optical component suppliers in Japan and Germany. Single-source vulnerability in 3D time-of-flight module supply is elevating procurement risk for facial recognition scaling. Distribution runs through Tier-1 automotive supplier networks with direct OEM integration relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive biometric access system market compounds steadily as regulatory mandates for connected vehicle cybersecurity harden authentication requirements across every vehicle program.
For Market Incumbents: Cement domain controller integration relationships by embedding fingerprint modules directly into steering-column electronics ahead of UNECE R155 enforcement waves. Acquire specialized firmware engineering capabilities for encrypted CAN-FD immobilizer gateway retrofitting to defend against cloud-native authentication platform entrants. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels offer the most penetrable route into shared mobility procurement workflows. Target South Korean and Chinese domestic OEMs with white-label iris-scanning modules for premium EV lineups. Pursue voiceprint authentication partnerships with luxury audio system suppliers for hands-free ignition enablement. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor fabrication specialists possessing capacitive sensor array scale and thermal-compensation IP. Long-term viability favors vendors with modular platform architectures that isolate region-specific compliance layers. Monitor EU AI Act algorithmic transparency audit trail requirements as the signal for compliance-cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Factor Platform Standardization | Bundled fingerprint-plus-facial configurations displace single-modality contracts in South Korean fleet procurement. |
| Domain Controller Integration Partnership | Robert Bosch GmbH leverages Tier-1 scale to embed modules directly into steering-column electronics for ignition gating. |
| EU AI Act Compliance Layer Investment | Algorithmic transparency documentation capabilities determine European homologation timeline competitiveness. |
| Cloud-Based Credential Management Launch | Over-the-air biometric template updates enable China domestic OEM multi-vehicle household access management. |
| Voiceprint Authentication R&D Program | Behavioral biometrics for hands-free ignition remain underexploited in luxury segments. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operator technology directors informed demand-side assumptions. Secondary sources include vehicle production databases, IHS Markit registration data, UNECE regulatory filings, and SEC disclosures from automotive electronics suppliers. Bottom-up sensor module shipment estimates triangulate against top-down vehicle production forecasts.
Granularity-level modeling disaggregates volume and value across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from segmented growth rate analysis applied across the projection horizon. Industry-specific forecast inputs include NHTSA driver-monitoring guidance implementation timelines and EU AI Act risk-classification enforcement patterns.
The model assumes a particular technology adoption path; alternative pathways for iris-scanning convergence would alter the outlook if cost curves collapse faster than projected. Forecasts reflect assumptions about UNECE R155 cybersecurity type-approval enforcement intensity and fleet operator multi-factor procurement consolidation. Practitioners should monitor 3D time-of-flight module production capacity expansion and EU algorithmic transparency audit trail requirements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Global Highway Driving Assist Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
China Airbag Systems Market
Automotive Safety and Security Systems
Active Spoiler Market