
 Off-Highway Wheels Market | 2026-2036
Off-Highway Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Highway Wheels Market Analytics
Original equipment distribution is reconfiguring as OEMs consolidate supplier panels and direct procurement contracts. Titan International leverages captive foundry capacity to anchor North American agricultural OEM programs. Maxion Wheels competes through modular rim platforms that span construction and mining specifications. CITIC Dicastal dominates aluminum flow-forming output for Asian machinery builders seeking weight reduction.
Off-highway wheels are load-bearing rim-and-tire assemblies engineered for vehicles operating on unpaved surfaces, typically constructed from stamped or rolled steel with bead seats rated to specific PSI ranges and dynamic load thresholds. Pneumatic wheels lead volume across agricultural equipment due to soil compaction sensitivity, while solid wheels command premium pricing in underground mining where puncture resistance eliminates downtime. Steel retains share in heavy construction machinery, though composite-reinforced aluminum is displacing conventional rims in mid-size industrial trucks where fuel efficiency regulations tighten.
EPA Tier 4 Final emission rules pressure OEMs to reduce unsprung mass, while ISO 4250-1 dimensional standards govern mining wheel interchangeability across international fleets. OSHA workplace safety directives on industrial truck stability influence dual-wheel specification in warehouse and port applications. Stakeholders must monitor how carbon border adjustments and scrap steel traceability requirements reshape material sourcing decisions for rim producers serving regulated end-use markets.
Market Dynamics
EPA Tier 4 Final emission standards are compressing replacement cycles for heavy construction and mining equipment, forcing wheel suppliers to accelerate lightweight material qualification while maintaining load ratings.
Growth Catalysts
- Aluminum flow-forming adoption:Asian machinery builders are specifying flow-formed aluminum rims to shed unsprung mass and meet fuel efficiency mandates without sacrificing dynamic load thresholds.
- Mining fleet expansion:Australian and Chilean surface mining operations are extending equipment utilization hours, driving accelerated wheel replacement schedules and aftermarket volume.
- ISO 4250-1 standardization:Global mining wheel dimensional harmonization is enabling cross-border fleet interchangeability, reducing inventory complexity for international operators.
Market Restraints
- Scrap steel traceability costs:Carbon border adjustment mechanisms in regulated end-use markets are forcing rim producers to document material provenance, adding compliance overhead to steel wheel production.
- Composite material qualification timelines:Reinforced aluminum and polymer matrix composites face extended OEM validation cycles, delaying commercial deployment in heavy construction segments.
- Underground mining concentration:Solid wheel demand clusters in geographically concentrated hard-rock mining districts, creating volume volatility when commodity prices shift.
Strategic Opportunities
- Brazilian soybean mechanization:Agricultural equipment fleets in Mato Grosso and Goiás are expanding, creating demand for soil-compaction-sensitive pneumatic wheel configurations.
- Dual-wheel specification growth:OSHA industrial truck stability directives are expanding dual-wheel adoption in warehouse and port material handling applications.
- Remanufacturing channel development:Direct procurement consolidation by OEMs is opening aftermarket service contracts for wheel refurbishment and rim reconditioning.
Industry Challenges
- Welding automation skill gaps:Steel rim production lines require certified robotic welding technicians, a scarce labor category in North American manufacturing regions.
- Cross-material fatigue testing:Validating aluminum-steel hybrid wheel designs demands extended test protocols that compress product development calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Highway Wheels Market |
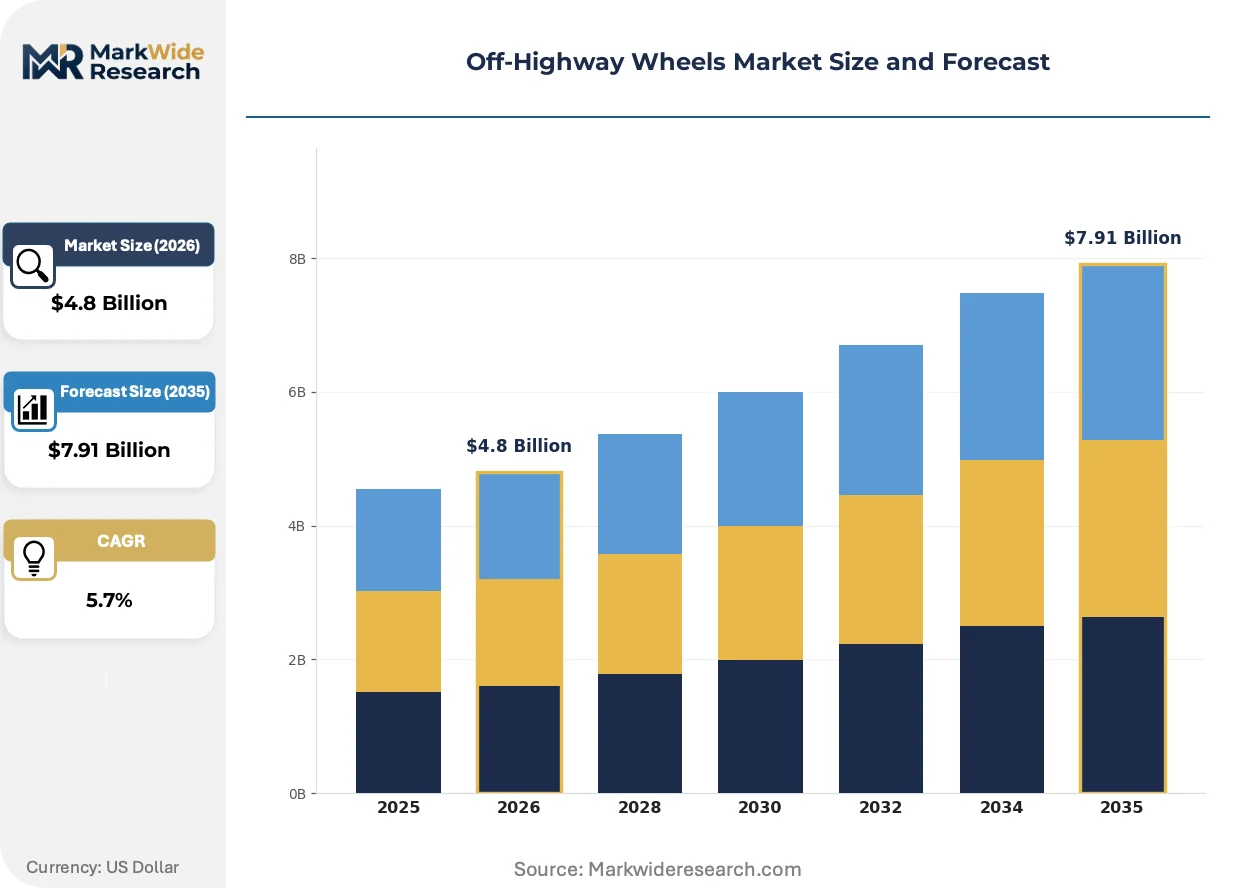
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Wheels, Pneumatic Wheels, Solid Wheels, Dual Wheels End User: Agricultural Equipment, Construction Machinery, Mining Vehicles, Industrial Trucks Material: Steel, Aluminum, Composite, Rubber Size: Small, Medium, Large, Extra Large |
| Companies Covered | Titan International, Accuride Corporation, Maxion Wheels, Topy Industries, CITIC Dicastal, Camso Wheels, Enkei Corporation, Rimex, OTR Wheel Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Highway Wheels Market Evolving Landscape
Material substitution and regulatory compression are redefining wheel architecture across off-highway segments, with weight reduction emerging as the dominant design priority.
Composite-reinforced aluminum rims are rendering obsolete conventional stamped steel designs in mid-size industrial trucks. Construction equipment OEMs in Germany and Japan are qualifying these hybrid configurations for loader and excavator lines. The technology is rendering obsolete legacy rim specifications that cannot satisfy simultaneous payload and emission targets.
REACH substance restrictions on hexavalent chromium plating are forcing European rim producers to convert coating lines to trivalent alternatives or plasma-deposited ceramic barriers. The regulation adds capital intensity to corrosion protection processes. Mining wheel suppliers serving EU-registered fleets are absorbing compliance costs while maintaining ISO 4250-1 dimensional interchangeability.
Fleet operators are unbundling wheel replacement from full-vehicle service contracts, creating direct procurement relationships with rim specialists. Agricultural cooperatives in Iowa and Illinois are negotiating seasonal volume commitments with foundries. Brazil and Australia show similar disintermediation patterns as mining and farm equipment owners seek parts-cost transparency.
Off-Highway Wheels Market Segmentation
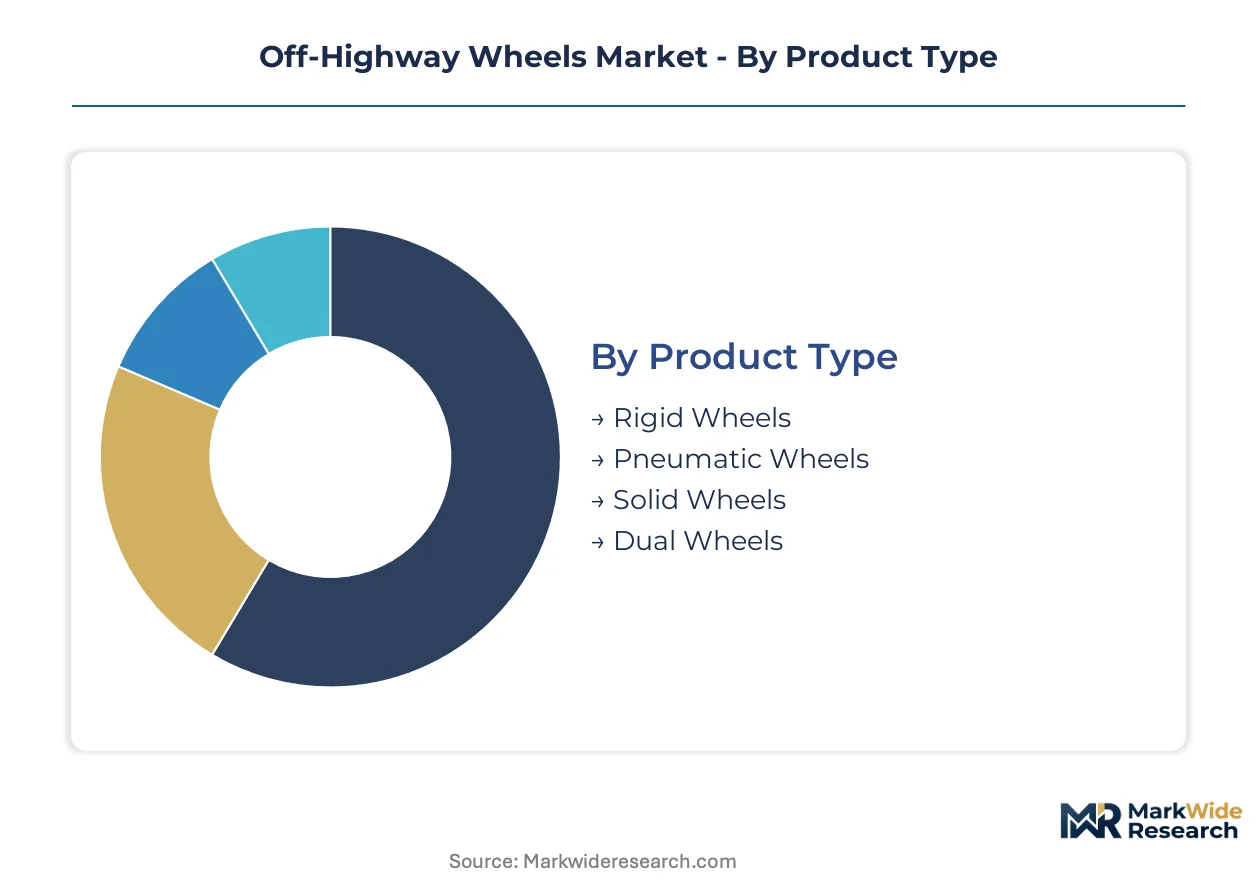
Off-highway wheel specifications diverge sharply by duty cycle intensity and regulatory exposure. Replacement intervals stretch from months in abrasive mining conditions to years in light agricultural service, creating distinct aftermarket revenue profiles across each segment boundary.
Product Type:
Pneumatic wheels turn over fastest in high-hour agricultural fleets, while solid wheels in underground mining run longest between replacements despite harshest operating conditions.
- Pneumatic Wheels:Air-filled assemblies with flexible sidewalls engineered for soil compaction sensitivity in row-crop farming. Demand clusters in Iowa and Illinois agricultural cooperatives where seasonal field pressure drives annual replacement schedules. Soil preservation mandates accelerate specification upgrades.
- Solid Wheels:Rubber-filled or cast constructions eliminating puncture risk in debris-laden environments. Australian and Chilean surface mining operations absorb premium pricing to eliminate downtime from rock penetration failures. Commodity price volatility concentrates volume swings in hard-rock districts.
- Rigid Wheels:Fixed-disc designs for light-duty material handling with minimal shock absorption requirements. Warehouse fleet operators specify these for indoor concrete surfaces where ride quality matters less than acquisition cost.
- Dual Wheels:Paired rim configurations mounted in tandem to distribute axle loads across wider footprints. OSHA industrial truck stability directives are expanding adoption in port container handling and distribution center applications.
Pneumatic wheels dominate installed base. Solid wheels are where expansion concentrates.
End User:
Customer procurement sophistication varies from consolidated OEM direct contracts to fragmented owner-operator spot purchasing.
- Mining Vehicles:Ultra-heavy-duty rim specifications rated for dynamic load thresholds exceeding standard construction ratings. Australian fleet operators unbundle wheel replacement from full-vehicle service contracts to capture parts-cost transparency.
- Agricultural Equipment:Soil-compaction-sensitive configurations prioritizing flotation over absolute load capacity. Brazilian soybean mechanization in Mato Grosso and Goiás is expanding fleet scale and seasonal volume commitments with foundries.
- Construction Machinery:Steel-retaining demand in heavy loaders and excavators where impact resistance trumps weight reduction. EPA Tier 4 Final emission rules pressure OEMs to qualify lighter alternatives without sacrificing durability ratings.
- Industrial Trucks:Mid-size equipment where composite-reinforced aluminum is displacing conventional rims under fuel efficiency tightening. German and Japanese OEMs lead hybrid configuration qualification for loader product lines.
Agricultural equipment anchors volume throughput. Mining vehicles command the steepest expansion trajectory.
Material:
Material selection trade-offs center on unsprung mass reduction versus impact fatigue resistance across duty cycles.
- Steel:Conventional stamped or rolled rim construction retaining dominance in heavy construction where weld integrity under shock loading remains critical. Scrap steel traceability requirements under carbon border adjustment mechanisms are adding compliance overhead to production economics.
- Aluminum:Flow-formed and cast variants specified for weight-sensitive applications. Asian machinery builders dominate adoption to meet fuel efficiency mandates without sacrificing dynamic load thresholds.
- Composite:Polymer matrix and fiber-reinforced hybrids facing extended OEM validation timelines. Heavy construction segment deployment delays persist due to cross-material fatigue testing protocol complexity.
- Rubber:Solid tire constructions bonded to metal rims for underground mining puncture elimination. REACH substance restrictions on hexavalent chromium plating force European producers to convert coating lines.
Steel retains installed base dominance. Aluminum is gaining share fastest.
Size:
Dimensional scaling follows equipment horsepower classes and axle load regulations across end-use categories.
- Large:Mining and heavy construction rim diameters governed by ISO 4250-1 interchangeability standards. Cross-border fleet harmonization reduces inventory complexity for international operators.
- Medium:Agricultural tractor and combine specifications where soil flotation requirements drive width-to-diameter ratios. North American agricultural belt demand concentrates replacement volume.
- Extra Large:Ultra-class mining truck rims requiring specialized foundry capacity and heat treatment protocols. Limited supplier base creates procurement concentration risk for fleet operators.
- Small:Compact utility equipment and light industrial truck configurations. Standardized bolt patterns enable aftermarket commoditization and price compression.
Medium sizes anchor replacement volume frequency. Extra large is where supplier capability scarcity sits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in machinery exports, while Australian iron ore rail corridors and Brazilian soy export terminals anchor regional demand clusters for heavy-duty wheel specifications.
United States
EPA Tier 4 Final emission standards compress replacement cycles for construction and mining fleets across the Midwest and Mountain West. OSHA workplace safety directives expand dual-wheel specification in Chicago and Houston port logistics hubs. Iowa and Illinois agricultural cooperatives negotiate seasonal volume commitments directly with rim foundries.
Australia
Pilbara iron ore rail networks and Queensland coal corridors drive accelerated wheel replacement in surface mining operations. The country's national mining safety regulator mandates ISO 4250-1 dimensional compliance for cross-border fleet interchangeability. Perth-based fleet operators unbundle wheel procurement from full-vehicle service contracts.
China
MIIT fuel efficiency mandates push machinery builders toward aluminum flow-forming for unsprung mass reduction. The Yangtze River Delta and Pearl River Delta concentrate foundry capacity serving domestic OEMs. GB standards for off-road equipment emissions tighten material qualification timelines.
Germany
REACH substance restrictions on hexavalent chromium plating force coating line conversions at rim producers serving EU-registered mining fleets. Baden-Württemberg and Bavaria host construction equipment OEMs qualifying composite-reinforced aluminum configurations. KBA technical standards influence brake system integration requirements.
Brazil
Mato Grosso and Goiás soybean mechanization expands agricultural equipment fleets requiring soil-compaction-sensitive pneumatic wheels. ANVISA industrial safety regulations intersect with agricultural machinery certification. Santos port grain terminals concentrate export logistics demand for heavy-axle configurations.
Off-Highway Wheels Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in rim fabrication and heat treatment. The supplier base stratifies between captive foundry operators serving OEM direct procurement and independent aftermarket distributors. Three archetypes dominate: steel stampers with welding automation, aluminum flow-forming specialists, and composite material innovators. Consolidation pressure favors backward integration into foundry capacity and geographic expansion into Brazilian and Australian mining districts.
Among North American steel wheel fabricators, Titan International and Accuride Corporation exemplify the captive foundry archetype, while Maxion Wheels occupies a position within modular rim platform specialists. These three represent divergent strategic postures on material substitution timelines and OEM direct contracting intensity.
| Leading Market Players |
|---|
| Titan International |
| Accuride Corporation |
| Maxion Wheels |
| Topy Industries |
| CITIC Dicastal |
| Camso Wheels |
| Enkei Corporation |
| Rimex |
| OTR Wheel Engineering |
| Others |
Value Network & Pricing Analysis
Foundry undercapacity in the North American agricultural belt compresses lead times for steel rim procurement while simultaneously hardening supplier pricing power against seasonal buyers. This utilization squeeze rewards backward-integrated producers with captive melt capacity, while forcing independent fabricators into premium spot markets for scrap steel feedstock.
Pricing Analysis
Volume-discount tiering structures separate OEM direct-contract volumes from aftermarket spot purchases, with agricultural cooperatives in Iowa and Illinois capturing 15-20 point spreads through seasonal commitment pooling. Price differentiation hinges on ISO 4250-1 certification grade for mining interchangeability and scrap steel traceability documentation for carbon-adjusted markets. Cost compression in standard-grade steel rims intensifies as Chinese flow-formed aluminum displaces mid-duty specifications. Fleet operators unbundling service contracts exhibit highest price sensitivity; ultra-class mining trucks show lowest due to downtime cost structures.
Supply Chain Analysis
Contract-manufacturing concentration sits with Yangtze River Delta foundries serving Asian machinery builders and captive operations at Titan International and Accuride Corporation anchoring North American OEM programs. Geographic supply draws from China for aluminum flow-forming, the United States for stamped steel agricultural rims, and Germany for REACH-compliant coating systems. Raw material feeds from Australian iron ore, Chilean copper for electrical conductivity in welding systems, and scrap steel streams subject to carbon border documentation. Single-source vulnerability concentrates in extra-large mining rim heat treatment. Distribution runs through OEM direct procurement consolidating supplier panels and independent aftermarket distributors serving owner-operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remanufacturing and rim reconditioning service layers are expanding faster than new-wheel hardware as fleet operators unbundle maintenance contracts and seek parts-cost transparency. This service-attach dynamic revalues supplier relationships toward lifecycle revenue capture.
For Market Incumbents: Pre-empt aluminum flow-forming displacement by qualifying hybrid steel-aluminum configurations for EPA Tier 4 Final compliance before composite materials complete extended OEM validation cycles. Capture backward integration into scrap steel sorting and traceability systems to neutralize carbon border adjustment overhead. Defensive consolidation of welding automation technician pipelines addresses acute labor scarcity in North American production regions. For New Entrants and Emerging Players: Build out Brazilian aftermarket distribution in Mato Grosso and Goiás soybean districts where agricultural mechanization outruns established service infrastructure. Target solid wheel reconditioning for Australian surface mining fleets unbundling procurement from full-vehicle contracts. Anchor go-to-market through direct seasonal volume commitments with agricultural cooperatives, bypassing consolidated OEM supplier panels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aluminum flow-forming capacity as Asian machinery builders accelerate fuel efficiency mandates. Long-term viability favors foundry-integrated rim fabricators with demonstrated ISO 4250-1 qualification history and captive technical welding labor pools. Acquisition screening should prioritize targets with remanufacturing channel relationships. The signal to watch is OEM direct-contract renewal rates as procurement consolidation matures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Steel Traceability | Neutralizes carbon border compliance costs for EU and North American regulated end-use markets. |
| Aluminum Flow-Forming Capacity Expansion | Captures MIIT fuel efficiency mandate-driven specification shifts among Asian machinery builders. |
| Remanufacturing Channel Development | Monetizes fleet unbundling trends through direct aftermarket service contracts with mining operators. |
| Welding Automation Technician Pipeline Investment | Secures scarce certified labor for robotic rim production lines in North American manufacturing regions. |
| REACH-Compliant Coating Line Conversion | Maintains EU mining fleet access as hexavalent chromium restrictions force process capital intensity. |
Research Methodology
A spread of perspectives from OEM procurement directors, aftermarket service managers, foundry operations heads, and fleet maintenance supervisors converged on the working assumptions driving segment-level volume estimates. Primary fieldwork combined structured interviews across these stakeholder categories with secondary validation drawing from EPA Tier 4 Final filings, ISO 4250-1 technical documentation, SEC 10-K disclosures from listed wheel manufacturers, and customs trade data for steel and aluminum rim imports. Bottom-up build-ups from equipment fleet counts and replacement cycle frequencies were triangulated against top-down market sizing from foundry capacity utilization reports.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, end-use equipment category, material composition, and dimensional size class. CAGRs were derived from equipment fleet expansion trajectories in Australian mining and Brazilian agriculture, overlaid with regulatory compression effects from EPA emission standards and REACH substance restrictions. Industry-specific forecast inputs included OEM direct procurement consolidation rates and aluminum-steel substitution elasticities under fuel efficiency mandates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese flow-forming specialists or accelerated composite material qualification by German construction equipment OEMs would shift outcomes beyond modeled ranges. Quarterly review of OEM supplier panel consolidation announcements, carbon border adjustment implementation timelines, and mining commodity price volatility indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market
Off Road Vehicles
Small Off-Road Engines Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Four-Wheel Drive Vehicles Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Off-Highway Vehicle Market