
 HD Map for Autonomous Vehicle Market | 2026-2036
HD Map for Autonomous Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
HD Map for Autonomous Vehicle Market Analysis
Geospatial engineering talent scarcity is unwinding deployment timelines for Level 4 autonomous programs across multiple continents. HERE Technologies anchors European highway coverage through its own fleet-based data collection infrastructure. Waymo leverages its proprietary sensor-fusion stack to maintain centimeter-level accuracy in dense urban corridors. NVIDIA Corporation competes by supplying GPU-accelerated map processing platforms to automakers lacking in-house rendering pipelines.
HD maps for autonomous vehicles constitute multi-layered spatial databases encoding lane geometry, traffic control semantics, and surface topology with sub-decimeter precision, typically generated through mobile mapping vans equipped with lidar, cameras, and inertial measurement units. These datasets enable machine-localization against pre-mapped features when GPS signals degrade. Real-time map updates now represent the fastest-expanding technology layer, as fleet learning pipelines compress refresh cycles from quarterly to near-daily intervals. Automaker end users currently dominate procurement volumes, though fleet operators are closing the gap as robotaxi services exit geofenced pilots.
The U.S. Department of Transportation's AV guidance and China's MIIT mapping qualification framework jointly shape market access by restricting cross-border data flows and mandating in-country processing infrastructure. Europe's GDPR and the EU AI Act add compliance layers for training datasets derived from street-level imagery. Stakeholders must decide whether to build captive map operations or accept dependency on specialized suppliers whose data licensing terms increasingly bundle hardware and software commitments.
Market Dynamics
Fleet-based map update pipelines are compressing refresh cycles from quarterly to near-daily intervals, forcing suppliers to rebuild data infrastructure around real-time ingestion rather than batch processing. This velocity shift is reshaping capital allocation across the value chain.
Growth Catalysts
- Robotaxi commercialization:Waymo and Cruise deployments in San Francisco, Phoenix, and Austin generate recurring demand for lane-level precision layers as operators exit geofenced pilots.
- China's MIIT mapping framework:Mandatory data localization creates captive partnership structures that accelerate domestic provider consolidation and infrastructure investment.
- Sensor-fusion localization:Lidar-camera-IMU integration enables machine-localization against pre-mapped features when GPS signals degrade in urban canyons.
Market Restraints
- Geospatial talent scarcity:Shortage of photogrammetrists and SLAM engineers extends Level 4 program timelines across North America and Europe.
- Cross-border data friction:GDPR and China's data sovereignty rules block training dataset portability, fragmenting model development.
- Mobile mapping capex intensity:Lidar-equipped survey vans cost $500K-$800K per unit, concentrating collection capacity among well-capitalized players.
Strategic Opportunities
- Germany's KBA type-approval pathway:Regulatory clarity for Level 3 systems creates first-mover advantage for HD map providers supporting Mercedes-Benz and BMW highway programs.
- Edge-based map caching:On-vehicle storage of hyperlocal tiles reduces latency for predictive path planning in connectivity dead zones.
- Fleet learning networks:Aggregated anonymized drive data from production vehicles enables crowd-sourced feature validation without dedicated survey operations.
Industry Challenges
- Sub-decimeter certification standards:Absence of unified accuracy benchmarks across NHTSA, KBA, and MIIT regimes forces redundant validation workflows.
- Legacy map format interoperability:Automaker-specific data schemas complicate supplier scaling and increase integration engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HD Map for Autonomous Vehicle Market |
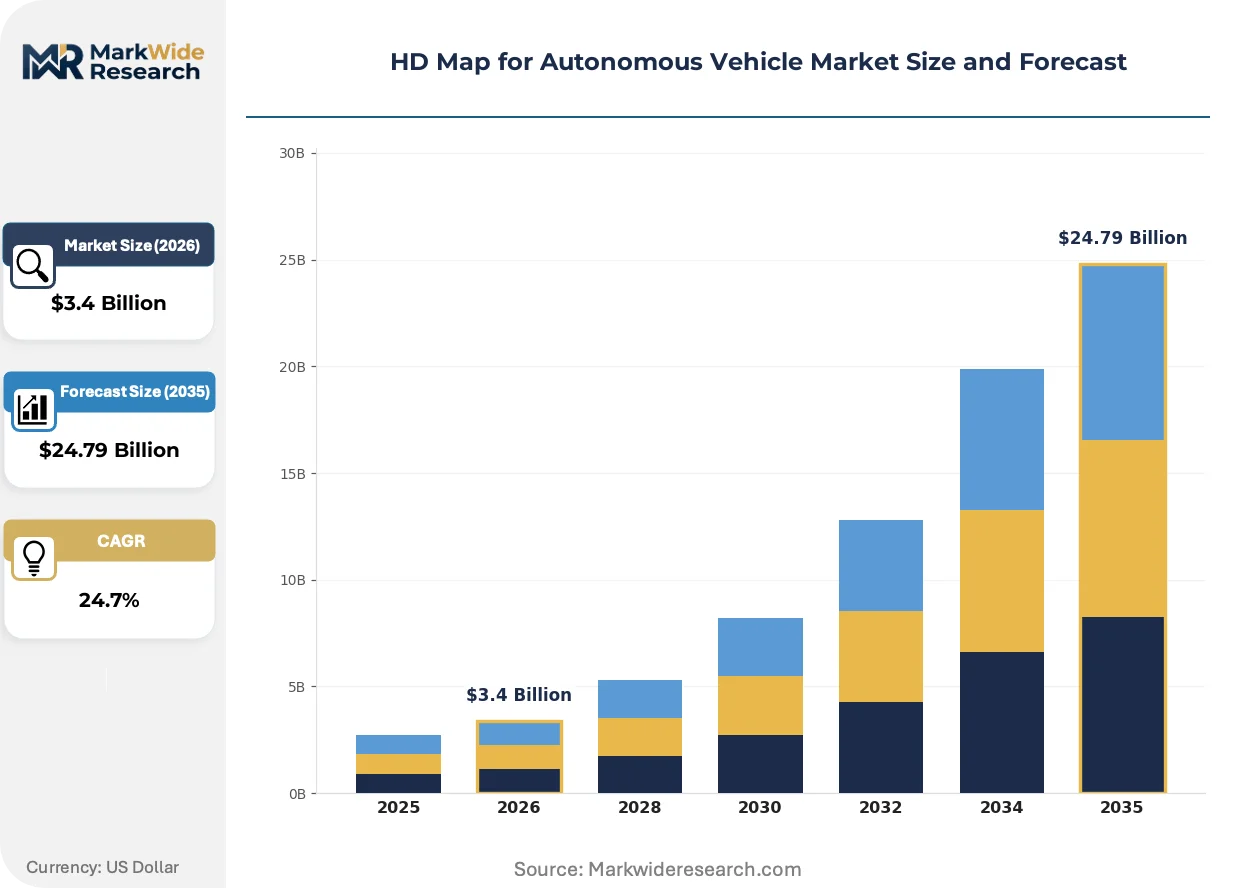
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $24.79 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Maps, 3D Maps, Real-Time Maps, High-Definition Vector Maps Technology: GPS, Lidar, Camera Sensors, IMU End User: Automakers, Tech Companies, Fleet Operators, Research Institutions Application: Navigation, Localization, Path Planning, Collision Avoidance |
| Companies Covered | NVIDIA Corporation, Waymo, HERE Technologies, NavInfo, Mapbox, TomTom, Mobileye, Woven by Toyota, Baidu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HD Map for Autonomous Vehicle Market Emerging Trajectories
Real-time map layer generation is supplanting static quarterly releases as the dominant operational paradigm. Three concurrent developments are accelerating this transition across hardware, policy, and procurement dimensions.
Vision-only mapping pipelines are supplanting lidar-dependent collection for certain feature classes. Tesla and Mobileye deploy production vehicle fleets to extract lane geometry from camera feeds at marginal incremental cost. This compression of data acquisition economics is forcing incumbent lidar-based providers to defend premium positioning on accuracy-critical layers.
Europe's EU AI Act imposes training data documentation requirements on machine learning models used in safety-critical automotive functions. HD map providers must now maintain provenance records for street-level imagery and point clouds used in feature extraction. German automakers and their Tier 1 suppliers are responding by auditing supplier data pipelines and inserting contractual liability clauses for non-compliance.
Automakers are unbundling map procurement from bundled navigation packages. Ford, Volkswagen, and Hyundai have separated HD map subscriptions from infotainment system contracts, enabling direct supplier relationships for autonomous driving divisions. This channel restructuring is most visible in California and Bavaria, where OEM engineering centers negotiate directly with HERE, TomTom, and specialized mapping startups rather than routing through traditional Tier 1 integrators.
HD Map for Autonomous Vehicle Market Segmentation
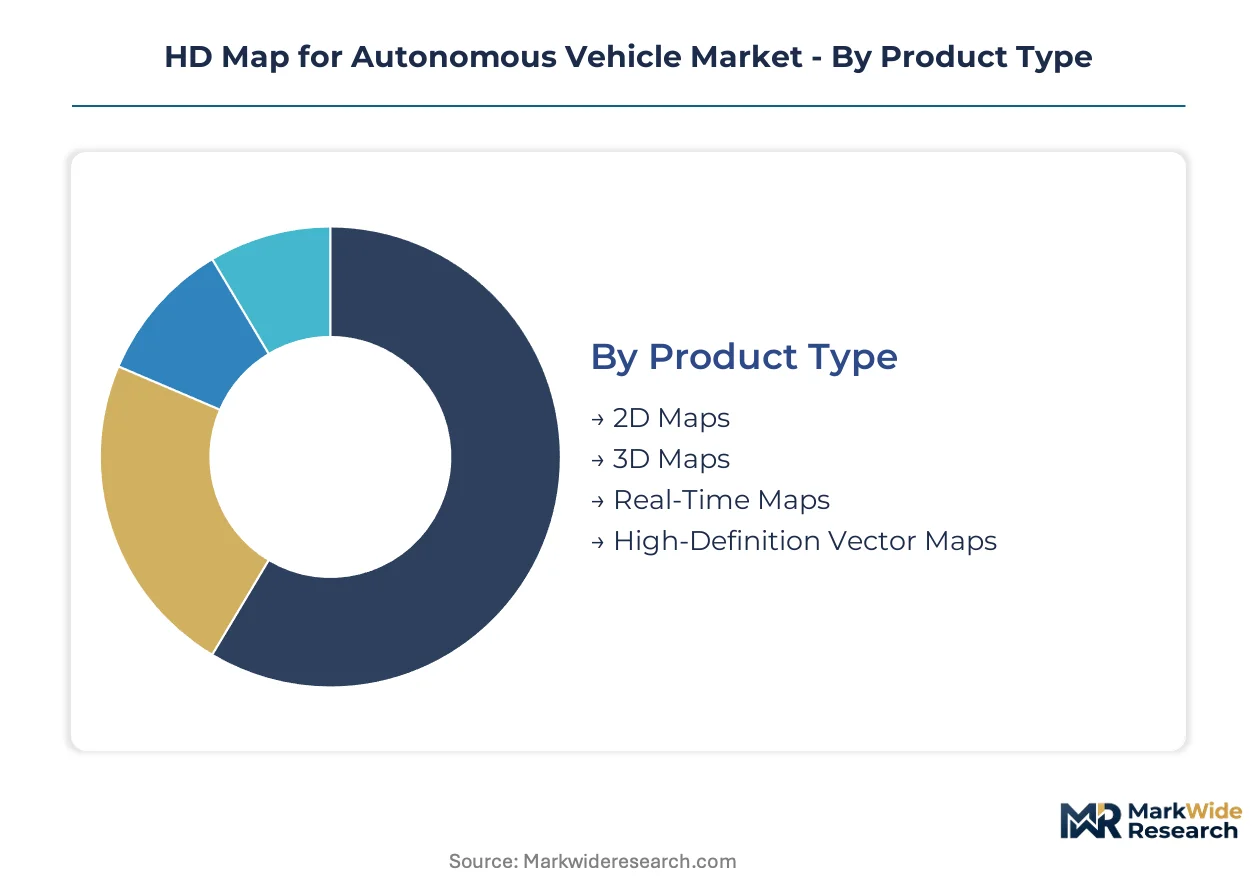
HD map procurement patterns diverge sharply across product formats and sensor dependencies, with substitution pressures from vision-only pipelines forcing lidar-based providers to defend premium positioning on accuracy-critical layers. Technology choices cascade through end-user requirements, as robotaxi operators prioritize real-time refresh capabilities while highway-focused automakers accept quarterly update cycles.
Product Type:
Vision-only localization systems threaten 2D and basic 3D map layers most directly, while sub-decimeter precision requirements protect premium vector formats from displacement.
- 3D Maps:Dense point clouds encoding elevation, curb geometry, and overhead structures with centimeter-grade vertical accuracy. Demand concentrates among robotaxi developers in California and Arizona, where NHTSA-guided testing regimes mandate redundant spatial validation for unsupervised operation.
- Real-Time Maps:Dynamic tile services refreshed through fleet telemetry pipelines, compressing update latency from months to hours. Procurement is accelerating among commercial fleet operators exiting geofenced pilots in Texas and Nevada, where connectivity infrastructure supports continuous data ingestion.
- 2D Maps:Planar road network representations sufficient for Level 2+ assisted driving systems. Legacy automakers in Michigan and South Carolina embed these into bundled navigation packages with marginal incremental cost.
- High-Definition Vector Maps:Semantic lane graphs with traffic rule encoding and predictive path primitives. German KBA type-approval pathways for Level 3 highway systems specify these layers as mandatory for Mercedes-Benz and BMW programs.
3D Maps retain volume leadership; Real-Time Maps hold the steepest expansion curve.
Technology:
Cost tiers separate sensor modalities, with camera-based extraction undercutting lidar collection economics by an order of magnitude for certain feature classes.
- Lidar:Time-of-flight ranging generates absolute-scale point clouds immune to lighting variation. Mobile mapping vans equipped with 64-beam units cost $500K-$800K per vehicle, concentrating collection capacity among well-capitalized providers in California and Bavaria.
- Camera Sensors:Production vehicle fleets extract lane markings and traffic signage at marginal incremental cost. Tesla and Mobileye deployments demonstrate scalable coverage expansion without dedicated survey operations.
- IMU:Inertial measurement units provide dead-reckoning continuity during GPS signal degradation in urban canyons and tunnels. These sensors anchor localization confidence in downtown San Francisco and Manhattan test corridors.
- GPS:Satellite positioning establishes global coordinate reference frames for map alignment. RTK-corrected signals deliver decimeter accuracy in open-sky conditions across Arizona and Florida testing grounds.
Lidar dominates current procurement value; Camera Sensors are climbing the fastest as vision-only pipelines mature.
End User:
Customer type determines refresh frequency requirements and integration complexity, with fleet operators demanding API-native architectures that automakers historically lacked.
- Automakers:Integrated vehicle programs specify map layers as embedded subsystems with 10-15 year lifecycle commitments. Procurement in Stuttgart, Wolfsburg, and Detroit favors suppliers with ISO 26262 functional safety certification.
- Fleet Operators:Robotaxi and logistics fleets require continuous map freshness for operational safety cases. Waymo and Cruise direct technical specifications in San Francisco and Phoenix, unbundling from traditional Tier 1 navigation contracts.
- Tech Companies:Cloud-native developers consume map APIs for simulation and validation pipelines. These users prioritize coverage breadth over absolute accuracy in initial procurement phases.
- Research Institutions:Academic and government labs license historical map snapshots for algorithm development. Funding from the U.S. Department of Transportation supports corridor-specific studies in Pennsylvania and Michigan.
Automakers retain volume leadership; Fleet Operators hold the steepest expansion curve.
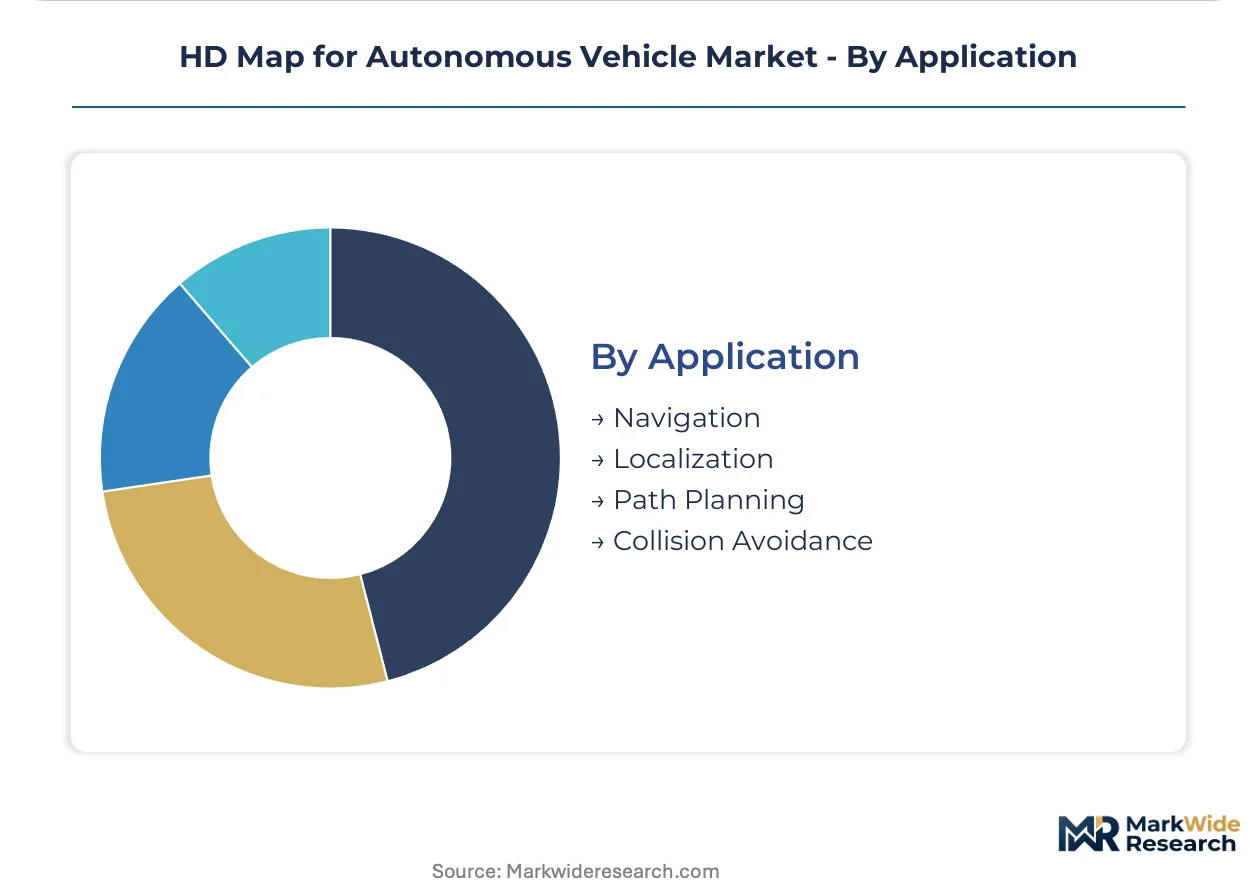
Application:
Maturity gradients separate navigation and localization functions—proven in production—from emerging path planning and collision avoidance layers requiring real-time semantic enrichment.
- Localization:Machine pose estimation against pre-mapped features enables GPS-denied operation. This function anchors deployment in downtown Austin and Miami, where urban canyon effects degrade satellite signals.
- Path Planning:Predictive trajectory generation using lane connectivity graphs and traffic rule semantics. Robotaxi operators in San Francisco specify these layers for unprotected left-turn handling and merge negotiation.
- Navigation:Route selection and turn-by-turn guidance represent the most mature application with lowest incremental hardware requirements. Embedded deployments dominate in mass-market vehicles from South Carolina and Alabama assembly plants.
- Collision Avoidance:Real-time obstacle mapping and occupancy grid updates for emergency maneuvering. These layers require sub-100ms latency, driving edge-computing investments in Nevada and Arizona test beds.
Localization retains volume leadership; Path Planning holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA's guidance framework anchors the United States as the dominant geography, though MIIT's data localization mandate in China and KBA's type-approval pathway in Germany jointly fragment procurement patterns across three regulatory jurisdictions.
United States
Waymo and Cruise commercial deployments in San Francisco and Phoenix generate concentrated demand for lane-level precision layers. NHTSA's AV guidance shapes testing protocols and safety case documentation requirements. California's Bay Area hosts overlapping engineering centers where multiple developers negotiate directly with map suppliers rather than routing through Tier 1 integrators.
China
Domestic robotaxi operators including Baidu's Apollo Go scale fleet deployments in Beijing and Shanghai under strict data sovereignty constraints. MIIT's mapping qualification framework mandates in-country processing infrastructure and forces foreign providers into captive partnership structures. The Yangtze River Delta concentrates domestic provider consolidation as local licensees absorb infrastructure investment flows.
Germany
Mercedes-Benz and BMW highway programs for Level 3 systems specify high-definition vector layers as mandatory under KBA type-approval pathways. The EU AI Act imposes training data documentation requirements that German automakers enforce through supplier audit clauses. Bavaria anchors European engineering activity with Munich-based OEM centers negotiating directly with specialized mapping providers.
Japan
METI's regulatory clarity for automated driving systems supports Toyota's Woven Planet subsidiary in developing proprietary map layers. Domestic automakers prioritize ISO 26262 functional safety certification in procurement decisions. The Kanto region around Tokyo concentrates R&D investment as OEMs integrate HD maps into next-generation highway pilot systems.
South Korea
Hyundai Motor Group's autonomous driving division unbundles map procurement from traditional navigation contracts to secure direct supplier relationships. The country's national mapping regulator enforces accuracy benchmarks for commercial deployment permits. The Seoul Capital Area hosts concentrated testing corridors where fleet operators validate real-time update pipelines.
HD Map for Autonomous Vehicle Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with technology conglomerates and automotive Tier 1s competing against pure-play mapping providers. The upper tier combines proprietary sensor-fusion stacks with captive data collection infrastructure, while specialists defend positioning on accuracy-critical layers and regional coverage depth. Three archetypes dominate: vertically integrated technology platforms, automotive-captive mapping divisions, and independent geospatial data providers. Competitive moves concentrate on strategic partnerships for data sharing and geographic licensing expansion to secure market access under fragmented regulatory regimes.
Within the integrated technology tier, NVIDIA Corporation and Waymo exemplify platform-centric strategies that bundle hardware acceleration with map processing capabilities. HERE Technologies anchors the independent geospatial tier as a European provider with fleet-based data collection infrastructure spanning highway networks. These three companies occupy positions that reflect divergent bets on whether automakers will build captive map operations or accept dependency on specialized suppliers whose licensing terms increasingly bundle hardware and software commitments.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Waymo |
| HERE Technologies |
| NavInfo |
| Mapbox |
| TomTom |
| Mobileye |
| Woven by Toyota |
| Baidu |
| Others |
Supply Flow & Price Mechanics
KBA type-approval pathways in Germany simultaneously gate supplier qualification and stratify pricing tiers across the European HD map procurement landscape. This dual-gating mechanism concentrates price-setting power among certified providers while forcing uncertified competitors into lower-margin data-licensing arrangements.
Pricing Analysis
California commands premium pricing for real-time map layers compared to Michigan and South Carolina, where legacy 2D formats dominate bundled navigation contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and refresh frequency differentiation. Cost compression in standard-tier subscriptions is intensifying because vision-only pipelines from Tesla and Mobileye undercut lidar-based collection economics. Fleet operators exhibit the least price sensitivity due to operational safety case requirements, while mass-market automakers in legacy manufacturing states resist unbundled HD map subscriptions.
Supply Chain Analysis
Strategic stockpiling of lidar sensor inventory prevails among California and Bavaria-based collection fleet operators facing 12-18 month lead times for 64-beam units. Mobile mapping van manufacturing concentrates in Germany, the United States, and Japan, with component sourcing drawing from Taiwanese semiconductor foundries, South Korean IMU suppliers, and Chinese optical component vendors. Single-source vulnerability in solid-state lidar emitters threatens fleet expansion timelines for specialized mapping providers. Distribution runs through direct OEM engineering center relationships in Stuttgart, Wolfsburg, and Detroit, bypassing traditional Tier 1 navigation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable incumbent advantages. Data localization mandates and certification requirements erect structural barriers that compound with fleet-scale network effects.
For Market Incumbents: Consolidate collection capacity through captive infrastructure investments in California and Bavaria to defend against vision-only substitution threats from Tesla and Mobileye. Deepen backward integration into lidar sensor supply chains to secure component allocation priority during capacity constraints. Prioritize KBA and MIIT certification maintenance as renewal gates for premium pricing tiers. For New Entrants and Emerging Players: ISO 26262 functional safety fast-tracks offer the most viable entry pathway for specialized providers targeting German automaker highway programs. White-space opportunities concentrate in edge-based map caching for connectivity dead zones and crowd-sourced feature validation networks for secondary road coverage. The most penetrable segment remains research institution licensing for historical map snapshots, where procurement cycles favor agile API-native architectures over embedded subsystem commitments. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive Tier 1 navigation divisions whose map procurement unbundling has stranded legacy bundled-service assets. Long-term viability hinges on regulatory compliance infrastructure rather than raw collection scale, favoring targets with established KBA, MIIT, and NHTSA engagement histories. Watch for inflection when robotaxi operators in Texas and Nevada shift from pilot-phase quarterly updates to commercial-duty near-daily refresh requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet-Based Data Collection Infrastructure | Waymo and HERE Technologies anchor competitive positioning through proprietary mobile mapping van networks. |
| Regulatory Certification Investment | KBA and MIIT qualification pathways protect premium pricing tiers from uncertified competitors. |
| Vision-Only Pipeline Development | Tesla and Mobileye demonstrate scalable lane geometry extraction without dedicated survey operations. |
| Real-Time Update Architecture | Fleet learning networks compress refresh cycles from quarterly to near-daily intervals for commercial deployment. |
| Direct OEM Engineering Relationships | Ford and Hyundai bypass Tier 1 integrators to negotiate HD map subscriptions with specialized providers. |
Methodological Framework
A standing panel of autonomous vehicle platform engineers, geospatial data scientists, regulatory affairs specialists at OEMs, and fleet operations directors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against NHTSA AV guidance documentation, MIIT mapping qualification frameworks, KBA type-approval pathways, and EU AI Act training data requirements. Bottom-up segment modeling triangulated against top-down market sizing from vehicle production databases and robotaxi fleet deployment disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product format, sensor modality dependency, end-user archetype, and application function, with additional granularity on regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to fleet deployment trajectories and update frequency adoption patterns. Industry-specific forecast inputs encompassed lidar sensor cost decline curves and vision-only pipeline maturity timelines.
Underlying assumptions cover regulatory regime stability, sensor cost trajectories, and fleet learning network penetration rates, with deviation risk concentrated in cross-border data friction and geospatial talent scarcity. Forecasts reflect these assumptions with explicit documentation of sensitivity ranges. Revision becomes warranted when vision-only localization accuracy crosses sub-decimeter thresholds in urban canyon environments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Autonomous Vehicle Management Services Market
Autonomous Vehicles
Africa Autonomous Navigation Market
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
North America Autonomous Navigation Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Global Driverless Car Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Luxury Autonomous Vehicle Market
Autonomous Vehicles
Self-Driving Bus Market