
 Engine Braking System Market | 2026-2036
Engine Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Braking System Market Foresight
Aftermarket distribution channels is reshaping competitive dynamics in engine braking components. Robert Bosch GmbH leverages its global service network to sustain replacement part availability across commercial vehicle segments. Continental AG anchors its position through integrated braking system architectures that bundle engine braking with electronic controls. Knorr-Bremse AG dominates air brake-adjacent channels where pneumatic engine braking modules command premium positioning.
An engine braking system converts kinetic energy into thermal or mechanical resistance through exhaust restriction, compression release, or driveline retardation, typically achieving braking power equivalent to 70-90% of engine rated output for heavy-duty applications. These systems primarily reduce service brake wear and prevent thermal fade during sustained downhill operation in commercial transportation. Electric retarders now lead technology investment among product type segments as electrified powertrains demand compatible deceleration architectures. Heavy-duty trucks concentrate margin pools within vehicle type segmentation due to regulatory mandates and fleet total-cost-of-ownership calculations. ABS-integrated engine braking modules within technology segments show fastest specification growth as stability control requirements tighten.
FMVSS standards enforced by NHTSA mandate minimum braking performance and thermal capacity for commercial vehicles operating on US highways. EPA emission regulations indirectly shape engine braking demand by restricting exhaust backpressure architectures that historically served dual braking-emissions functions. ISO 26262 functional safety requirements impose design validation costs that filter supplier participation in electronic engine braking controls. Stakeholders must monitor how powertrain electrification timelines alter the technical and economic rationale for traditional engine braking architectures.
Market Dynamics
Powertrain electrification timelines are compressing the addressable window for traditional engine braking architectures as commercial vehicle OEMs redesign deceleration systems around electric motor regeneration. This structural pressure forces incumbent suppliers to pivot toward hybrid-compatible retarder modules while defending installed base in diesel-heavy segments.
Growth Catalysts
- FMVSS 121 mandates:NHTSA enforcement of enhanced braking performance standards for heavy-duty trucks drives specification upgrades across US commercial fleets, particularly for downhill thermal capacity requirements in mountainous corridors.
- Compression release brake innovation:Advanced engine brake designs integrated with electronic control units achieve finer modulation of braking torque, reducing driveline shock and expanding adoption in sensitive cargo applications.
- German commercial vehicle manufacturing:OEM integration requirements from MAN Truck and Bus and Daimler Truck AG concentrate demand for certified engine braking modules within Baden-Württemberg and Bavaria production clusters.
Market Restraints
- Raw material cost volatility:Cast iron and high-grade steel input prices fluctuate with energy-intensive foundry operations, compressing margin stability for mechanical retarder component suppliers.
- Exhaust backpressure regulatory friction:EPA emission restrictions on diesel particulate accumulation limit traditional Jake brake architectures that relied on restricted exhaust flow for dual-function braking.
- Electric powertrain substitution:Battery-electric and fuel-cell commercial vehicles eliminate mechanical engine braking entirely, substituting regenerative deceleration systems with 90%+ energy recovery efficiency.
Strategic Opportunities
- India commercial vehicle expansion:Bharat Stage VI emission compliance and growing domestic truck production create specification windows for integrated engine braking-retarder systems in medium and heavy-duty segments.
- Retrofit channel development:Independent service networks in Brazil and Mexico offer aftermarket installation pathways for engine braking kits on legacy truck populations lacking factory-equipped retarders.
- ISO 26262 certification leverage:Functional safety validation investments position qualified suppliers for electronic braking control modules as ABS-integrated architectures become mandatory in EU and US markets.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineering and brake-by-wire calibration expertise concentrates within automotive electronics hubs, constraining supplier scaling for mechatronic retarder development.
- Legacy fleet integration complexity:Older commercial vehicle CAN bus architectures lack bandwidth for modern engine braking control signals, requiring costly gateway module development for retrofit applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Braking System Market |
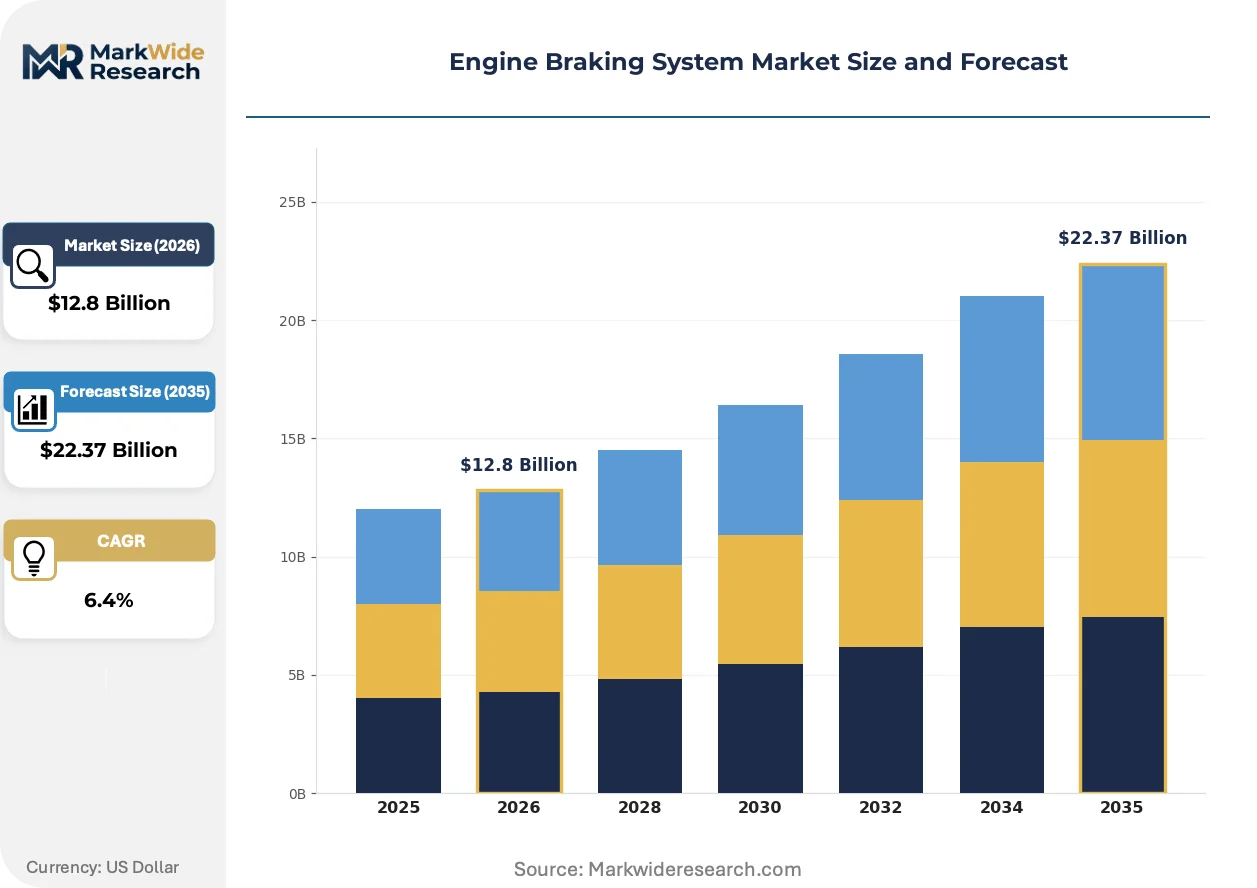
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Pneumatic, Hydraulic, Electric Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Application: On-Road, Off-Road, Racing, Transportation Technology: ABS, EBD, ESC, VDC |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Knorr-Bremse AG, AISIN Corporation, Brembo S.p.A, Akebono Brake Industry Co., Ltd, Hitachi Astemo Ltd., Nissin Kogyo Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Braking System Market Shifts & Advancements
Electrification imperatives are fragmenting the traditional engine braking value chain as suppliers bifurcate between defending diesel-era architectures and developing hybrid-compatible deceleration technologies. This tension accelerates R&D resource allocation toward dual-product portfolios.
Electric retarder technology is collapsing the historical distinction between engine braking and driveline retardation. Eddy-current and permanent-magnet retarder designs integrated with electric axle architectures deliver seamless deceleration torque without mechanical wear. European bus manufacturers and Chinese electric truck OEMs are specifying these systems at accelerating rates. The technology is collapsing aftermarket service revenue pools previously sustained by brake lining replacement cycles.
EPA emission regulations are reshaping permissible engine braking architectures by restricting exhaust manifold designs that historically enabled compression-release braking. The agency's tightened particulate matter standards force suppliers toward valve-train-based solutions decoupled from exhaust backpressure. Heavy-duty diesel engine platforms serving North American long-haul routes face the steepest redesign requirements, with Cummins and PACCAR accelerating development of cam-profiled engine brake variants.
Fleet procurement patterns are fragmenting across ownership models as full-service leasing companies unbundle braking system maintenance from vehicle acquisition contracts. Large logistics operators now specify component-level service intervals and performance guarantees separately from chassis procurement. This unbundling shifts margin capture toward independent service networks and away from OEM captive distribution. The pattern is most visible in German and Dutch fleet markets where total-cost-of-ownership contracting dominates heavy-duty vehicle sourcing.
Engine Braking System Market Segmentation
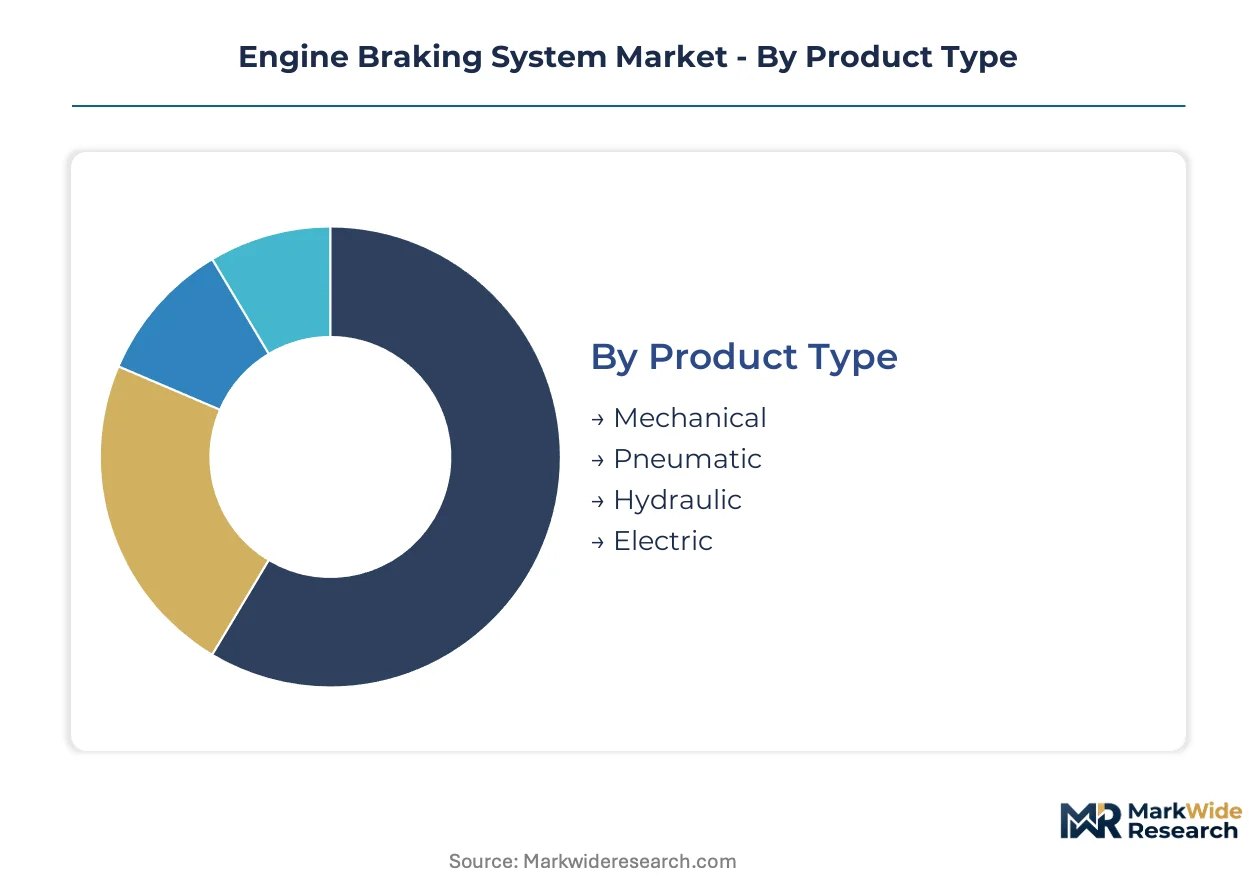
Engine braking architectures vary dramatically in replacement frequency and specification intensity across product categories. Fleet operators calibrate procurement cycles differently for mechanical versus electric retarder systems, creating distinct margin and service revenue profiles for suppliers.
Product Type:
Replacement cycles span from continuous electrical operation to periodic mechanical overhaul intervals, reshaping aftermarket revenue predictability for each technology class.
- Electric:Eddy-current and permanent-magnet designs deliver frictionless deceleration torque through electromagnetic resistance. Chinese electric truck OEMs and European bus manufacturers concentrate procurement in this segment as battery-electric powertrains demand compatible regeneration architectures. The technology eliminates wear-component replacement cycles that sustain traditional aftermarket revenue pools.
- Mechanical:Compression-release and exhaust brake systems rely on valve-train and manifold hardware subject to thermal cycling fatigue. North American long-haul fleets specify these systems for diesel-heavy routes where Jake brake heritage maintains specification preference despite EPA emission constraints on exhaust backpressure designs.
- Pneumatic:Air-actuated retarder modules integrate with existing commercial vehicle compressed air systems.
- Hydraulic:Fluid-coupled retarder designs serve medium-duty applications requiring driveline-mounted deceleration torque.
Mechanical systems anchor the volume base while electric retarders gain share at the steepest rate.
Vehicle Type:
Specification intensity scales directly with gross vehicle weight rating and duty cycle severity across transportation modes.
- Heavy-Duty Trucks:Class 8 commercial vehicles mandate engine braking for FMVSS 121 downhill thermal compliance in mountainous US corridors. Fleet total-cost-of-ownership calculations prioritize integrated retarder specifications for brake wear reduction and elimination of thermal fade risk during sustained grade operation.
- Commercial Vehicles:Medium-duty delivery and vocational trucks balance payload sensitivity with braking performance requirements. German OEM integration standards from MAN Truck and Bus and Daimler Truck AG concentrate demand for certified modules within Baden-Württemberg and Bavaria production clusters.
- Passenger Cars:Downsized turbocharged gasoline engines incorporate mild engine braking through variable valve timing.
- Motorcycles:Large-displacement touring bikes specify compression braking for downhill control on canyon roads.
Heavy-duty trucks command the premium tier while commercial vehicles deliver the broadest unit volume.
Application:
Duty cycle differentiation separates continuous braking environments from intermittent deceleration use cases.
- Transportation:Long-haul freight corridors and urban bus routes impose sustained braking thermal loads that mandate retarder specification. Fleet procurement contracts in German and Dutch markets unbundle braking maintenance from vehicle acquisition, shifting margin toward independent service networks.
- On-Road:Highway and arterial road operation subjects braking systems to predictable thermal cycling patterns.
- Off-Road:Mining and construction equipment operates in low-speed, high-torque deceleration environments.
- Racing:Motorsport applications exploit engine braking for corner entry speed control and traction management.
Transportation applications concentrate specification value while on-road deployment spans the widest geographic footprint.
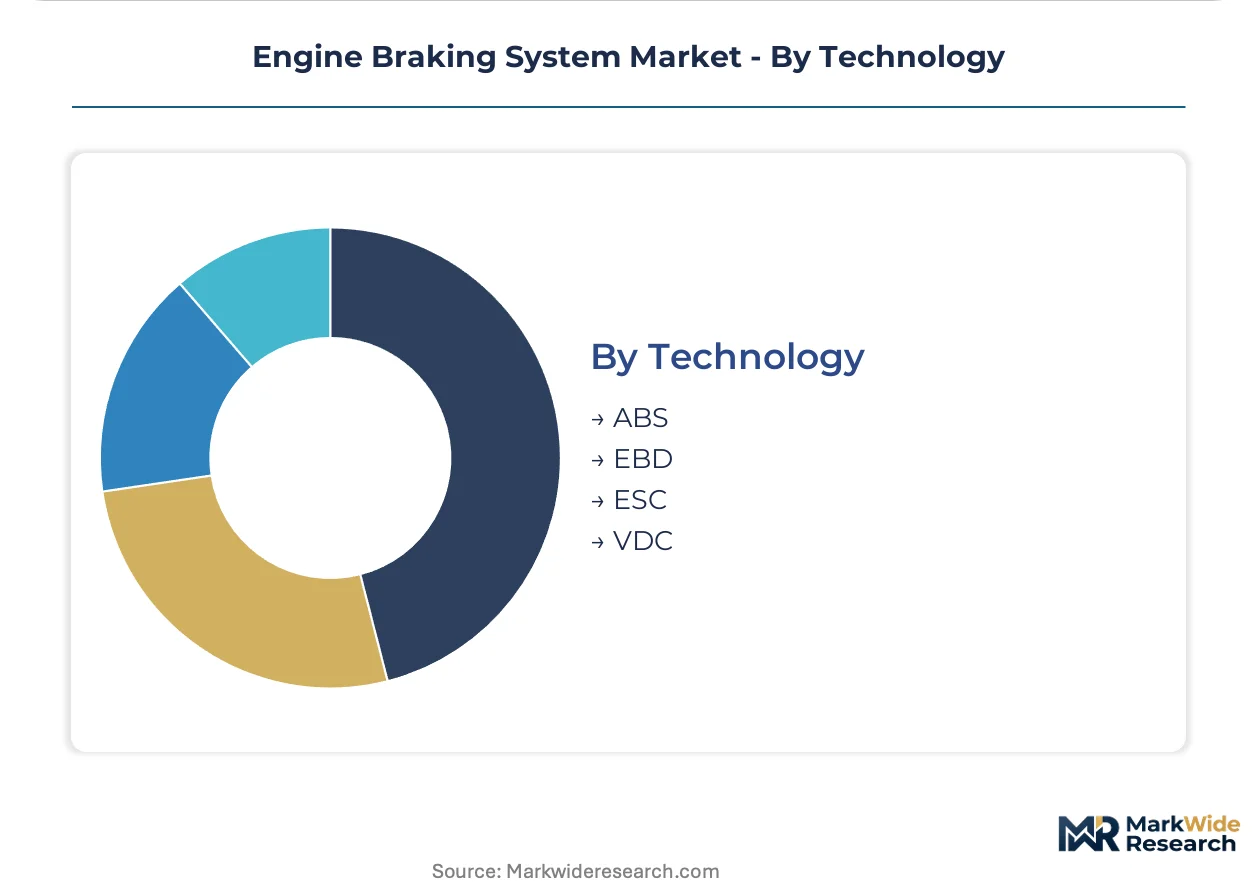
Technology:
Electronic control integration levels determine functional safety certification requirements and supplier qualification barriers.
- ABS:Anti-lock braking system integration with engine braking modules achieves fastest specification growth as NHTSA and EU stability mandates tighten. ISO 26262 functional safety validation imposes design costs that filter supplier participation in electronic control development.
- EBD:Electronic brake-force distribution optimizes retarder torque application across axle loads.
- ESC:Electronic stability control coordination with engine braking prevents trailer swing and jackknife incidents.
- VDC:Vehicle dynamics control systems manage integrated deceleration across powertrain and service brakes.
ABS-integrated architectures lead specification adoption while VDC systems climb fastest among emerging safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA's FMVSS 121 enforcement anchors North American specification intensity, while German OEM integration standards and Chinese electric truck production reshape procurement geography across three continents.
United States
Class 8 fleet operators specify integrated retarder systems for FMVSS 121 downhill thermal compliance across Rocky Mountain and Appalachian freight corridors. NHTSA mandates drive replacement cycles for legacy mechanical brake architectures in commercial vehicle populations. Detroit and Columbus manufacturing clusters concentrate supplier engineering resources for ABS-integrated engine braking modules.
Germany
MAN Truck and Bus and Daimler Truck AG procurement contracts require certified engine braking modules with ISO 26262 functional safety validation. KBA type-approval processes filter supplier participation in electronic control development for EU market access. Baden-Württemberg and Bavaria production clusters anchor OEM integration requirements for heavy-duty commercial vehicle specifications.
China
Battery-electric truck OEMs concentrate procurement in electric retarder architectures compatible with regenerative deceleration systems. MIIT new energy vehicle mandates accelerate displacement of traditional mechanical engine braking in urban freight applications. Yangtze River Delta manufacturing bases supply eddy-current retarder modules for domestic electric bus and truck production.
India
Bharat Stage VI emission compliance creates specification windows for integrated engine braking-retarder systems in medium and heavy-duty domestic truck production. BIS certification requirements shape supplier qualification for commercial vehicle brake component sourcing. Maharashtra and Gujarat automotive corridors concentrate OEM assembly capacity driving component demand.
Brazil
Independent service networks develop aftermarket installation pathways for engine braking kits on legacy truck populations lacking factory-equipped retarders. ANVISA automotive safety regulations indirectly influence brake system specification through commercial vehicle type-approval processes. São Paulo state logistics operators drive retrofit demand for downhill thermal capacity upgrades in mountainous southeastern freight routes.
Engine Braking System Market Competitive Landscape
Integrated system architects and component specialists split the market along technology integration depth. Supplier tiers concentrate around electronic control capability, with functional safety certification creating qualification barriers that filter participation in ABS-integrated architectures. Strategic moves center on hybrid-compatible retarder development and aftermarket channel expansion into legacy fleet retrofit applications.
Among German-based integrated suppliers, Robert Bosch GmbH, Continental AG, and Knorr-Bremse AG occupy positions spanning electronic control development and pneumatic brake-adjacent channels. These entities exemplify the integrated-system archetype through bundled braking architectures and global service network coverage. Their positioning reflects the structural premium commanded by functional safety-validated electronic engine braking modules in EU and US regulatory environments.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Knorr-Bremse AG |
| AISIN Corporation |
| Brembo S.p.A |
| Akebono Brake Industry Co., Ltd |
| Hitachi Astemo Ltd. |
| Nissin Kogyo Co., Ltd |
| Others |
Supply & Pricing Matrix
Rocky Mountain freight corridors concentrate cost dynamics where supply concentration in Baden-Württemberg manufacturing clusters and downstream fleet procurement unbundling reshape price differentiation across configured-to-order and standard retarder specifications.
Pricing Analysis
The customization-premium spread separates ISO 26262-certified ABS-integrated modules from standard mechanical retarder configurations, with certification grade and volume scale driving price differentiation. Pricing pressure stems from raw material volatility in cast iron and high-grade steel foundry inputs. Fleet operators show highest price sensitivity in retrofit channel procurement, while OEM captive buyers absorb premium positioning for functional safety-validated electronic controls.
Supply Chain Analysis
Contract manufacturing concentration rests on Robert Bosch GmbH and Continental AG captive production networks, supplemented by independent foundries serving pneumatic retarder component demand. Component sourcing draws from German precision machining, Chinese electromagnetic component fabrication, and Mexican assembly integration. Supply chain risk centers on single-source vulnerability for high-grade steel valve-train castings. Distribution runs through OEM captive channels for new vehicle fitment and independent service networks for aftermarket retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional safety engineering talent scarcity constrains supplier scaling for mechatronic retarder development, compressing the qualified vendor pool for ABS-integrated architectures as electrification timelines accelerate.
For Market Incumbents: Build certification moats around ISO 26262 validation investments to defend against emerging electronics specialists from automotive semiconductor adjacencies. Deepen backward integration into electromagnetic component production to secure supply continuity for electric retarder modules. Channel control through captive service networks protects margin capture as fleet procurement unbundling shifts maintenance contracts toward independent distributors.
For New Entrants and Emerging Players: Establish a beachhead in Brazil and Mexico aftermarket retrofit channels where legacy truck populations lack factory-equipped retarders and independent installation pathways remain underdeveloped. Target medium-duty commercial vehicle segments in India where Bharat Stage VI compliance creates specification windows without entrenched incumbent relationships. Pursue white-label manufacturing partnerships with Yangtze River Delta electric axle suppliers to bypass captive OEM supply agreements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming brake component divisions lacking electrification roadmaps. Long-term viability hinges on hybrid-compatible retarder development capability bridging diesel-era installed base defense and electric powertrain integration. Monitor MIIT new energy vehicle mandate acceleration as inflection signal for traditional mechanical engine braking displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Compatible Retarder Development | Dual-product portfolios bridge diesel defense and electric powertrain integration demanded by MAN Truck and Bus procurement. |
| ISO 26262 Certification Investment | Functional safety validation filters supplier participation in NHTSA-mandated ABS-integrated engine braking modules. |
| Aftermarket Channel Expansion | Independent service network partnerships capture margin shift from OEM captive distribution in German and Dutch fleet markets. |
| Electric Axle Integration Partnership | Collaboration with Chinese electric truck OEMs secures positioning in MIIT-mandated new energy vehicle production. |
| Retrofit Kit Development | Legacy fleet CAN bus gateway modules unlock Brazilian and Mexican independent installation pathways for thermal capacity upgrades. |
Research Methodology
Desk research of NHTSA FMVSS enforcement records, EPA emission regulation filings, and commercial vehicle production databases preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket service network operators, and fleet maintenance directors. Primary fieldwork across Baden-Württemberg and Bavaria production clusters, Yangtze River Delta electric vehicle manufacturing bases, and São Paulo state logistics corridors validated secondary trade flow and regulatory compliance data. Bottom-up unit shipment modeling and top-down value aggregation triangulated market size estimates across product type, vehicle class, and technology integration segments.
Assumptions held powertrain electrification timelines and FMVSS enforcement intensity constant across the analysis window, while varying raw material cost trajectories and regional fleet procurement unbundling velocity. Segmentation modeling spanned propulsion architecture, vehicle weight class, electronic control integration level, and regional regulatory cluster. CAGRs derived from logistic adoption curve fitting and replacement cycle analysis incorporated fleet total-cost-of-ownership calculations and thermal compliance mandate phase-in schedules.
Sensitivities concentrate around MIIT mandate acceleration, EPA particulate matter standard tightening, and foundry energy cost volatility. Forecasts reflect documented assumptions regarding hybrid powertrain penetration and aftermarket channel development velocity. Quarterly review of commercial vehicle registration data, OEM platform engineering job postings, and independent service network expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Motorcycle Start Stop Systems Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Automotive Front-End Collision Warning System Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Germany Airbag Systems Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Global Automotive Intelligent Door System Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Europe Airbag Systems Market
Automotive Safety and Security Systems
Automotive Speed Limiter Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Automotive Radar Market