
 Automation-As-A-Service Market | 2026-2036
Automation-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Automation-As-A-Service Market Intelligence
The EU AI Act is expanding compliance requirements for algorithmic decision systems across European enterprises, pushing buyers toward transparent, governable automation architectures. UiPath Inc. leverages its integrated discovery-to-deployment platform to anchor large-scale transformation programs. Automation Anywhere, Inc. competes through its cloud-native architecture designed for distributed workforce orchestration. International Business Machines Corporation differentiates via deep vertical expertise in regulated industries requiring audit trails.
Automation-As-A-Service denotes the delivery of robotic process automation, intelligent process automation, and cognitive automation capabilities through cloud subscription models, typically orchestrated via containerized microservices with API-first integration protocols. The primary purpose is to eliminate capital-intensive infrastructure deployment while enabling elastic scaling of digital workers against transactional workloads. Public cloud deployment dominates volume due to faster provisioning and lower entry barriers, though hybrid cloud configurations are capturing margin pools from enterprises with data residency constraints. Robotic process automation remains the foundational solution offering, while intelligent process automation represents the fastest-expanding category as natural language processing and computer vision capabilities mature.
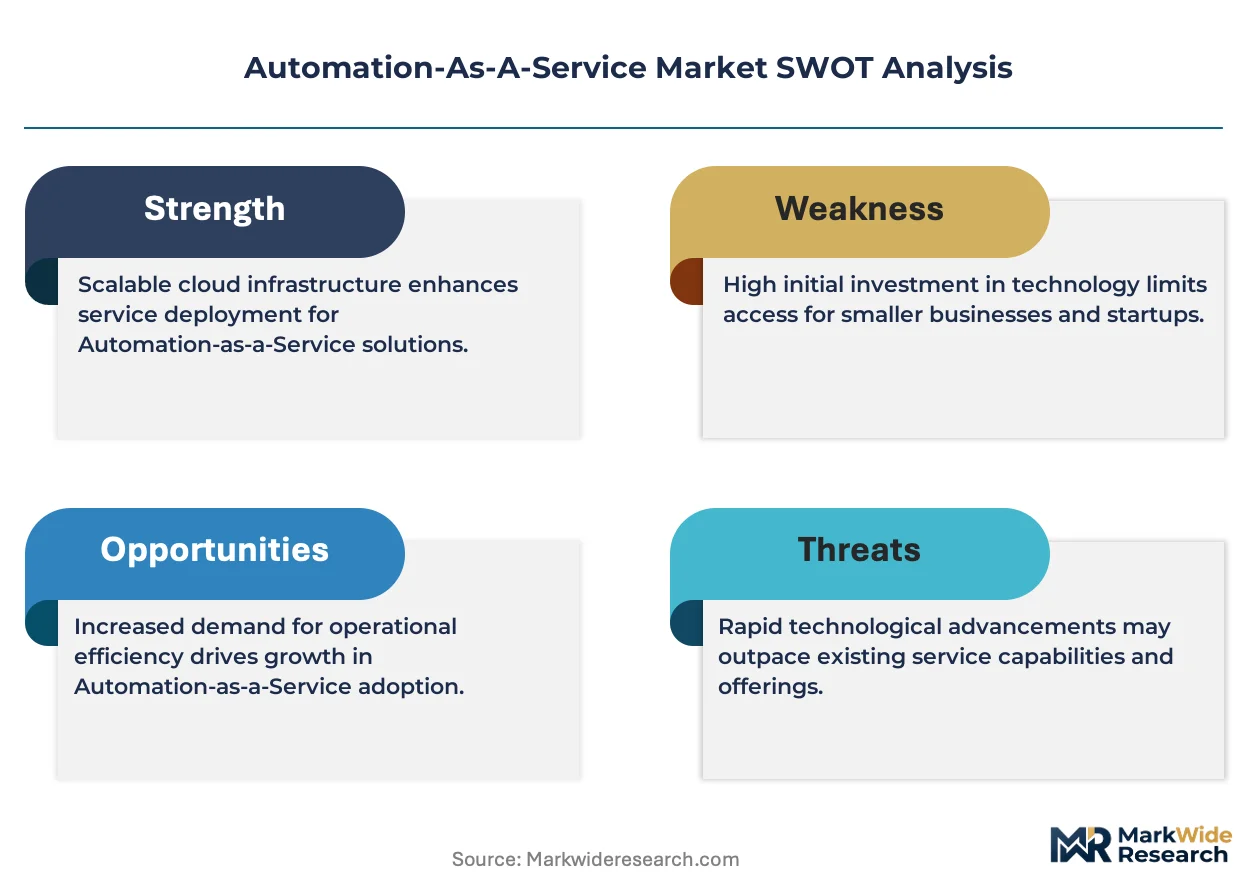
FDA guidelines on software-as-a-medical-device intersect with HIPAA requirements when automation platforms process protected health information, creating dual compliance obligations for healthcare deployments. The EU AI Act and GDPR jointly shape product standards around explainability and data minimization, directly influencing platform design priorities. EMA documentation standards further constrain automation in pharmaceutical quality assurance workflows. Stakeholders must monitor evolving regulatory divergence between jurisdictions to avoid architectural lock-in that complicates future compliance adaptation.
Market Dynamics
Cloud-native orchestration platforms are compressing deployment timelines from months to weeks, forcing incumbent vendors to rearchitect delivery models around containerized microservices and API-first integration protocols.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises face mandatory algorithmic audit requirements, driving procurement of transparent automation platforms with built-in governance tooling.
- Computer vision maturation:Manufacturing quality assurance teams deploy visual inspection bots at scale, expanding intelligent process automation beyond rules-based workflows.
- German industrial clustering:Factory digitization initiatives in Bavaria and Baden-Württemberg concentrate demand for cloud-hosted robotic process automation.
Market Restraints
- Data residency constraints:HIPAA and GDPR jurisdictional conflicts force hybrid cloud architectures that increase operational complexity and infrastructure overhead.
- Specialized talent scarcity:Shortages of automation engineers with both domain expertise and cloud-native skills constrain deployment velocity across mid-market buyers.
- Legacy system entrenchment:Core banking and ERP platforms from the 1990s resist API integration, requiring costly middleware layers.
Strategic Opportunities
- Process mining convergence:Combining task capture with automated bot generation creates self-healing workflow loops that reduce manual discovery overhead.
- Healthcare administrative automation:Prior authorization and claims processing present underpenetrated use cases where HIPAA-compliant platforms capture recurring revenue.
- India's PLI scheme:Manufacturing incentives in Gujarat and Tamil Nadu accelerate factory digitization, creating demand for localized cloud automation infrastructure.
Industry Challenges
- Bot maintenance debt:Digital worker fleets require continuous retraining as target applications update, consuming operational bandwidth.
- Cross-border data friction:Divergent EMA documentation standards and FDA software-as-a-medical-device guidelines complicate pharmaceutical automation deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automation-As-A-Service Market |
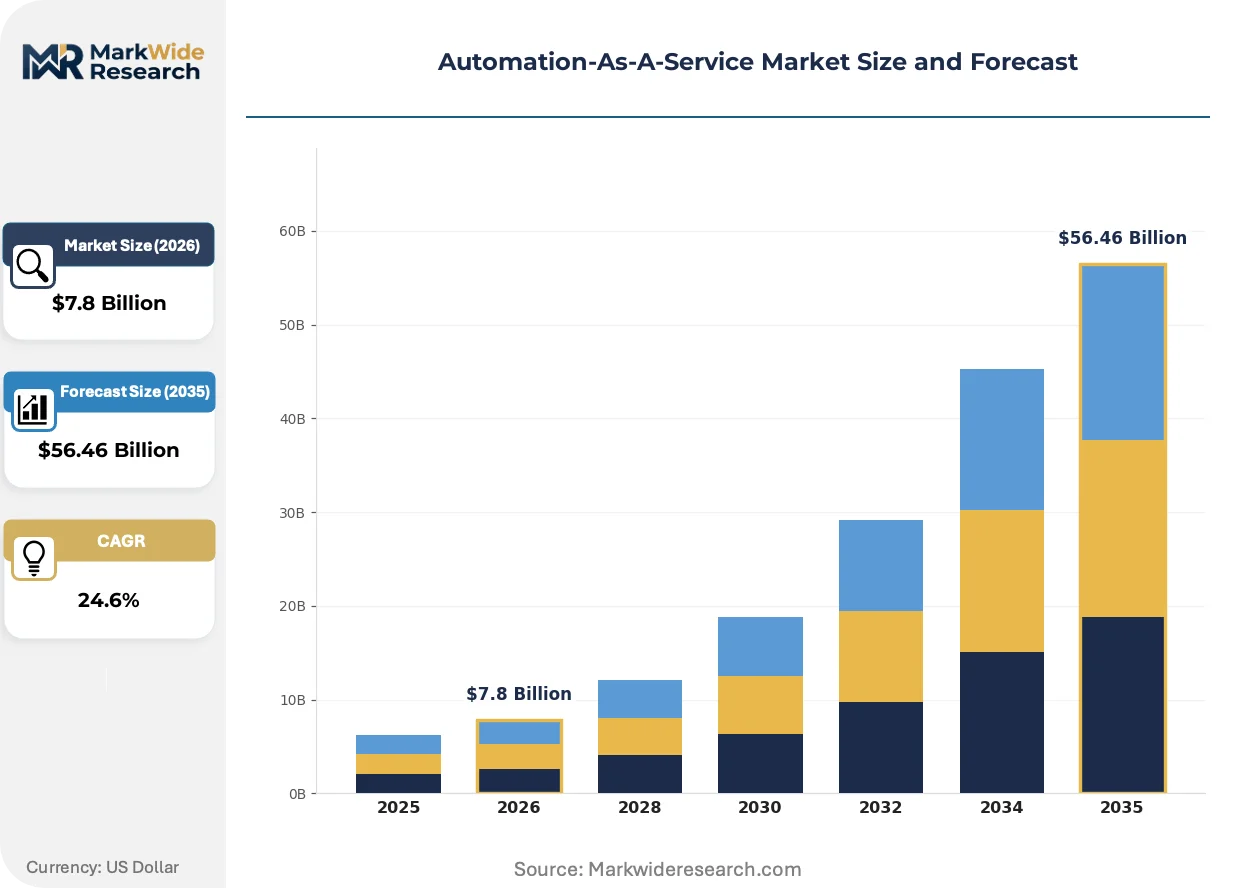
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $56.46 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Offering: Robotic Process Automation, Intelligent Process Automation, Cognitive Automation, API Automation, Digital Workforce Management Use Case: Invoice Processing, Customer Support, Supply Chain Optimization, Compliance Management, Data Entry Automation End User Industry: Banking, Manufacturing, Telecommunications, Insurance, Hospitality |
| Companies Covered | Microsoft Corporation, UiPath Inc., Automation Anywhere, Inc., Blue Prism Group plc, International Business Machines Corporation, HCL Technologies Limited, Hewlett Packard Enterprise Development LP, Kofax Inc., Pegasystems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automation-As-A-Service Market Strategic Shifts & Innovations
Agentic AI architectures are displacing deterministic workflows, enabling automation systems to handle exception paths without human intervention. This shift demands new governance frameworks and redefines platform competitive advantage.
Low-code orchestration layers are decentralizing bot development from centralized IT teams to business units. Manufacturing operations managers in Stuttgart and Munich now configure visual workflows without engineering support. This democratization compresses time-to-value but fragments governance standards across enterprise divisions.
The EU AI Act's risk classification system is forcing platform vendors to embed explainability modules and human-in-the-loop checkpoints. High-risk automation in credit decisions and hiring now requires conformity assessments before deployment. German automotive suppliers and French banking groups are prioritizing vendors with pre-certified governance tooling to accelerate procurement cycles.
Consumption-based pricing models are displacing seat-based subscriptions across mid-market buyers. IT procurement teams in healthcare and logistics now meter digital worker hours against transaction volumes rather than licensing fixed bot counts. This shift is most visible in Netherlands and Nordic markets where CFOs demand granular cost attribution for automation programs.
Automation-As-A-Service Market Segmentation
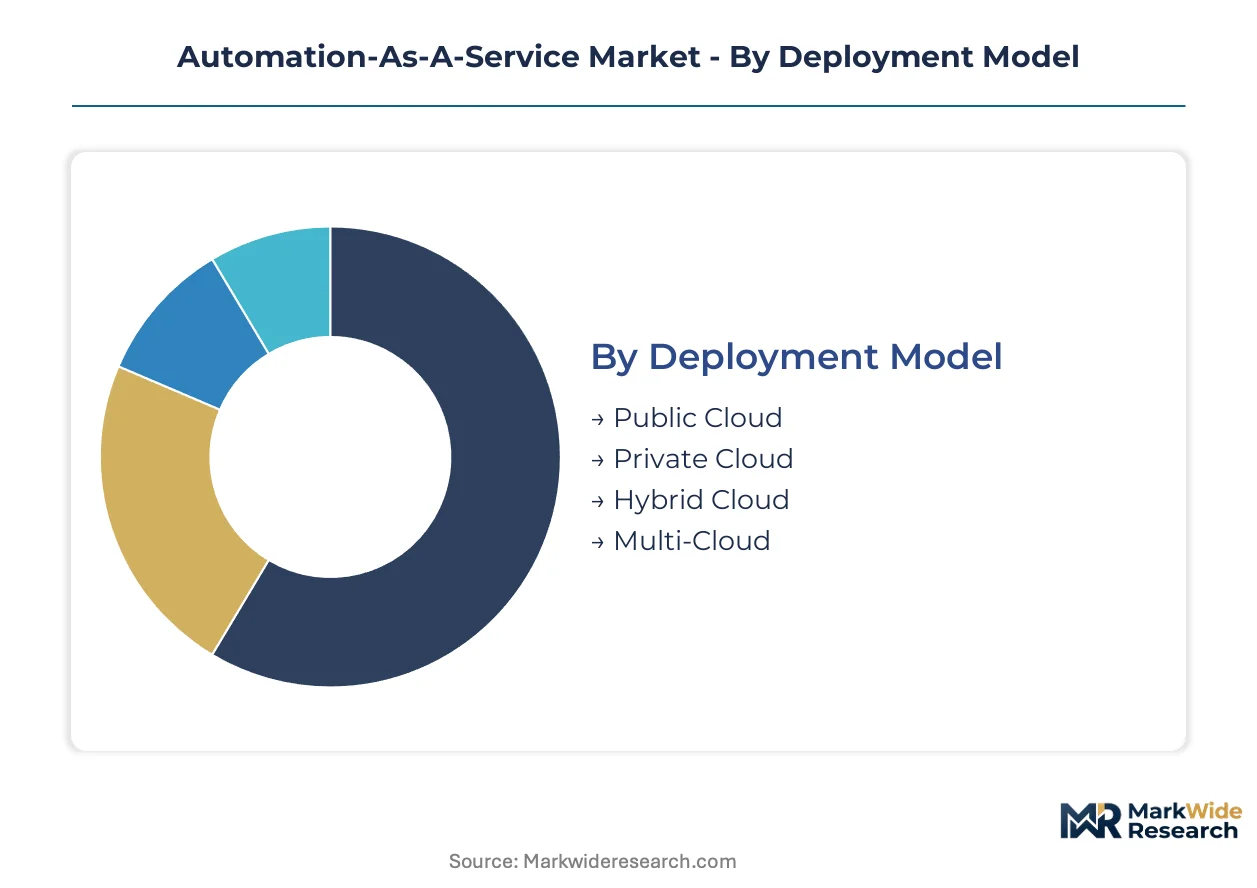
Automation-As-A-Service platforms fragment across deployment architectures, solution maturity tiers, and functional applications. Each segmentation axis carries distinct margin profiles, compliance obligations, and competitive dynamics that shape vendor positioning.
Deployment Model:
Public cloud infrastructure concentrates supply-side investment from hyperscalers, while hybrid configurations capture premium pricing from regulated verticals.
- Public Cloud:Containerized microservices orchestrated through hyperscaler marketplaces deliver elastic scaling without capital deployment. Demand concentrates among mid-market manufacturers in Stuttgart and Munich seeking rapid bot provisioning without on-premise overhead.
- Private Cloud:Single-tenant architectures with dedicated compute isolation serve banking groups in Frankfurt and insurance carriers in Munich confronting GDPR data residency mandates and BaFin audit requirements.
- Hybrid Cloud:Workload portability between on-premise and cloud environments accommodates pharmaceutical quality assurance teams processing EMA documentation alongside cloud-based analytics. This architecture commands implementation premiums due to integration complexity.
- Multi-Cloud:Orchestration layers abstracting AWS, Azure, and Google Cloud prevent vendor lock-in for logistics operators in Rotterdam managing cross-border data flows under divergent national implementations of EU AI Act risk classifications.
Today's leader: Public Cloud. Tomorrow's challenger: Hybrid Cloud.
Solution Offering:
Solution tiers stratify by cognitive sophistication, with rules-based automation anchoring volume and AI-augmented platforms capturing expansion budgets.
- Robotic Process Automation:Deterministic bots executing structured workflow sequences through UI interaction layers. German automotive suppliers in Baden-Württemberg deploy these for invoice reconciliation and ERP data entry at scale.
- Intelligent Process Automation:Computer vision and natural language processing capabilities enable exception handling in unstructured document workflows. This tier expands most quickly as computer vision maturation drives visual inspection bot deployment across Bavarian factory floors.
- Cognitive Automation:Machine learning models learning from historical decision patterns to handle ambiguous inputs. Healthcare administrative teams in Netherlands apply these for prior authorization processing requiring clinical context interpretation.
- API Automation:Direct system-to-system integration bypassing UI layers for latency-sensitive transaction flows. Fintech operators in London and Singapore favor this approach for real-time payment orchestration.
- Digital Workforce Management:Centralized governance consoles for bot scheduling, credential rotation, and performance monitoring. Enterprise automation programs in Paris and Frankfurt prioritize these platforms for compliance audit trail generation under EU AI Act high-risk system requirements.
Robotic Process Automation anchors current revenue. Intelligent Process Automation climbs the fastest as manufacturing quality teams expand beyond rules-based workflows.
Use Case:
Functional applications concentrate in administrative workflows with document-heavy inputs and repetitive decision structures.
- Invoice Processing:Three-way matching automation between purchase orders, receipts, and supplier invoices. Shared service centers in Poland and Hungary deploy these at volume for Western European parent companies.
- Customer Support:Chatbot and ticket routing automation with escalation protocols for complex inquiries. Telecommunications carriers in Nordic markets meter these solutions against call deflection rates.
- Supply Chain Optimization:Demand forecasting and inventory repositioning bots integrating ERP with logistics platforms. This use case is gaining share fastest as disruptions drive predictive automation investment among Rotterdam port operators.
- Compliance Management:Regulatory report generation and control testing automation. Banking compliance officers in Frankfurt and Paris prioritize these for ECB and ACPR submission workflows.
- Data Entry Automation:Form population and system migration bots eliminating manual transcription. Healthcare administrative teams in Germany apply these for patient record digitization under strict BSI technical guideline adherence.
Invoice Processing dominates transaction volume. Supply Chain Optimization shows steepest expansion trajectory as resilience planning accelerates.
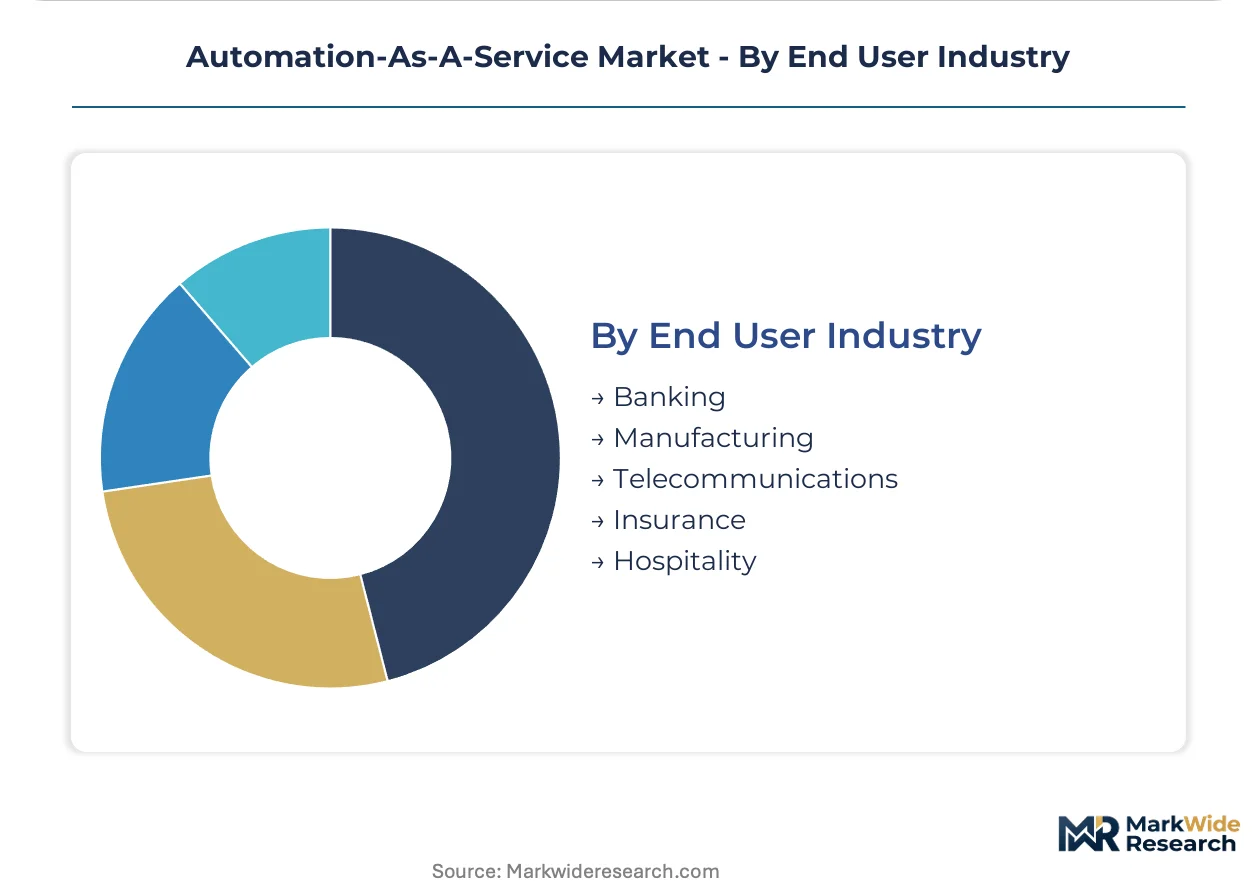
End User Industry:
Industry verticals exhibit divergent automation maturity, with manufacturing and banking leading deployment depth while hospitality lags.
- Banking:Core banking modernization, anti-money laundering screening, and mortgage processing automation. German and French banking groups drive procurement of explainable automation platforms for credit decision audit trails under EU AI Act high-risk classification.
- Manufacturing:Quality assurance visual inspection, predictive maintenance, and shop floor inventory tracking. Bavarian and Baden-Württemberg industrial clusters concentrate demand for cloud-hosted robotic process automation integrated with MES layers.
- Telecommunications:Network fault correlation, customer churn prediction, and billing dispute resolution. Nordic operators lead consumption-based pricing adoption for these workloads.
- Insurance:Claims triage, fraud detection, and policy administration automation. Munich and Zurich carriers prioritize platforms with pre-certified governance tooling for Solvency II documentation.
- Hospitality:Revenue management, reservation optimization, and guest service automation. This vertical remains underpenetrated due to fragmented property management system landscapes and limited IT capital allocation.
Banking commands premium pricing for compliance-integrated platforms. Manufacturing scales fastest as factory digitization programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud-native automation engineers cluster in Stuttgart, Munich, and Frankfurt, anchoring European demand for factory digitization and financial services automation. German industrial clusters drive procurement volume, while regulatory pressure from Brussels reshapes platform requirements across the continent.
Germany
Baden-Württemberg automotive suppliers deploy visual inspection bots at scale, compressing quality assurance cycles. The EU AI Act mandates algorithmic audit trails for high-risk credit decisions, forcing Frankfurt banking groups toward pre-certified governance platforms. Bavarian manufacturers in Munich and Nuremberg integrate cloud-hosted RPA with MES layers for predictive maintenance.
United States
HIPAA-covered entities in Boston and New York Metro automate prior authorization workflows, creating demand for compliant healthcare platforms. FDA software-as-a-medical-device guidelines intersect with HIPAA when automation processes protected health information, imposing dual compliance burdens. Healthcare administrative teams in California apply cognitive automation for clinical context interpretation in claims processing.
India
The PLI scheme accelerates factory digitization in Gujarat and Tamil Nadu, generating localized cloud automation infrastructure demand. BIS technical guidelines shape data residency requirements for manufacturing automation deployments. Shared service centers in Bangalore and Hyderabad deliver invoice processing bots for Western European parent companies at volume.
United Kingdom
London fintech operators favor API automation for real-time payment orchestration, bypassing UI-layer latency. The Information Commissioner's Office enforces GDPR data minimization standards that constrain cross-border bot training data flows. Edinburgh and Manchester banking compliance teams prioritize platforms with built-in audit trail generation for FCA submission workflows.
Netherlands
Rotterdam port operators invest in supply chain optimization bots as resilience planning accelerates post-disruption. Consumption-based pricing models displace seat-based subscriptions among Dutch CFOs demanding granular cost attribution. Eindhoven manufacturing clusters deploy intelligent process automation for demand forecasting and inventory repositioning.
Automation-As-A-Service Market Key Industry Players
Capital-heavy hyperscale cloud providers compete with asset-light pure-play automation vendors for enterprise wallet share. The vendor base stratifies across three tiers: integrated platform suites, specialized RPA tools, and vertical-specific workflow engines. Strategic archetypes include cloud-native orchestrators, legacy system integrators with automation divisions, and emerging agentic AI specialists. Dominant competitive moves encompass API-first architecture investments and process mining acquisition activity.
Within the integrated platform tier, Microsoft Corporation and UiPath Inc. occupy positions spanning discovery-to-deployment workflows, while Automation Anywhere, Inc. exemplifies cloud-native architecture designed for distributed workforce orchestration. International Business Machines Corporation anchors the legacy integrator archetype through vertical expertise in regulated industries requiring audit trails. These three entities represent contrasting approaches to governance tooling, deployment velocity, and compliance certification depth.
| Leading Market Players |
|---|
| Microsoft Corporation |
| UiPath Inc. |
| Automation Anywhere, Inc. |
| Blue Prism Group plc |
| International Business Machines Corporation |
| HCL Technologies Limited |
| Hewlett Packard Enterprise Development LP |
| Kofax Inc. |
| Pegasystems Inc. |
| Others |
Cost & Logistics Intelligence
German automotive suppliers and Frankfurt banking groups concentrate procurement volume for cloud-hosted automation platforms, anchoring subscription-based pricing models that meter digital worker hours against transactional throughput rather than fixed licensing.
Pricing Analysis
Consumption-based SaaS pricing stratifies across premium, standard, and economy tiers based on governance certification depth and API integration complexity. Price differentiation hinges on EU AI Act pre-certification status and vertical-specific compliance modules for HIPAA or GDPR environments. Cost compression in the standard tier intensifies as hyperscalers bundle automation capabilities into broader cloud contracts. Mid-market manufacturers in Bavaria exhibit highest price sensitivity, while Frankfurt banking groups accept premium positioning for audit-ready governance tooling.
Supply Chain Analysis
Direct-to-enterprise channels handle demand from large manufacturing and financial services buyers, while hyperscaler marketplaces capture mid-market volume. Supply concentration rests on Ireland and Netherlands for European data center infrastructure, with India anchoring delivery engineering capacity. Raw material dependencies span specialized GPUs for computer vision workloads, enterprise-grade storage arrays, and API gateway software licenses. Single-source vulnerability in GPU supply chains creates exposure to semiconductor allocation constraints. Distribution runs through vendor-direct sales for complex implementations and self-service portals for standardized RPA deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification functions as a regulatory compounder, mandating algorithmic audit capabilities that reshape procurement criteria and platform development priorities across European enterprises.
For Market Incumbents: Lock in compliance certification depth as the primary defensive moat against hyperscaler bundling. Invest in pre-certified governance modules for credit decisions and hiring workflows to accelerate Frankfurt and Paris procurement cycles. Acquire process mining specialists to close discovery-to-deployment loops before cloud-native challengers capture manufacturing accounts in Stuttgart and Munich. For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for specialized compliance-first platforms targeting high-risk automation categories underserved by generalist vendors. White-space targets include pharmaceutical quality assurance workflows constrained by EMA documentation standards and healthcare prior authorization automation requiring HIPAA dual compliance. A vertical-specific go-to-market anchored in pre-certified audit tooling bypasses incumbent scale advantages. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, seeking governance-layer capabilities to differentiate bundled automation offerings. Long-term viability favors platforms with embedded explainability modules and human-in-the-loop architectures that align with tightening regulatory trajectories. Monitor EU AI Act enforcement patterns in France and Germany as the critical inflection signal for compliance-premium pricing durability.| Strategic Initiative | Industry Significance |
|---|---|
| Process Mining Acquisition | Self-healing workflow loops reduce discovery overhead for Baden-Württemberg automotive suppliers. |
| EU AI Act Pre-Certification | Accelerated procurement cycles among Frankfurt banking groups facing high-risk system mandates. |
| API-First Architecture Investment | Latency-sensitive fintech orchestration in London demands direct system-to-system integration. |
| Healthcare Compliance Module Development | Dual HIPAA-FDA obligations create recurring revenue from Boston prior authorization automation. |
| India PLI Localization Partnership | Gujarat and Tamil Nadu factory digitization requires localized cloud infrastructure and support. |
Research Approach
Direct dialogue with automation platform engineers, IT procurement officers at German manufacturing enterprises, compliance leads at Frankfurt banking groups, and cloud infrastructure specialists anchored the qualitative foundation. Secondary validation drew from SEC filings of publicly traded automation vendors, hyperscaler capex disclosures, EU AI Act implementation guidance, and GDPR enforcement case databases. Bottom-up deployment estimates triangulated against top-down market sizing from cloud subscription revenue disclosures.
Bottom-up modeling segmented the market across deployment architectures, solution maturity tiers, and functional applications, with cross-validation against regional adoption patterns. The analysis window spans the full projection horizon without annual disaggregation. CAGRs were derived from elasticity-adjusted demand curves incorporating computer vision maturation trajectories and regulatory compliance cost premiums. Industry-specific inputs included German industrial cluster digitization budgets and healthcare administrative automation penetration rates.
Revisions become necessary when EU AI Act enforcement intensity shifts, hyperscaler bundling strategies accelerate, or GPU supply constraints disrupt computer vision deployment timelines. Forecasts reflect assumptions about regulatory stability and cloud infrastructure availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Retail Automation Market
Automation
Global Smart Vending Machines Market
Automation
Process Automation Market
Automation
Playout Automation Market
Automation
Laboratory Benchtop Automation Market
Automation
Global Remote Monitoring and Control Market
Automation
Data Center Automation Market
Automation
Global Cloud Automation Market
Automation
Italy Marketing Automation Software Market
Automation
North America Data Center Automation Market
Automation
Laboratory Automation Market
Automation
Global Field Force Automation Market
Automation
Global Process Automation and Instrumentation Market
Automation
Europe Marketing Automation Software Market
Automation
Automated Cell Block Systems Market
Automation
Europe Laboratory Automation Market