
 Retail Automation Market | 2026-2036
Retail Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Automation Market Intelligence
The gap between premium integrated platforms and commodity point solutions is recalibrating procurement patterns across retail chains. Manhattan Associates leverages its warehouse management heritage to anchor enterprise-grade automation stacks. Hai Robotics competes through dense storage robotics specialization in Asia-Pacific fulfillment networks. Simbe Robotics differentiates via autonomous inventory scanning that extends visibility into shelf-level conditions without infrastructure overhaul.
Retail automation encompasses hardware and software systems that execute merchandising, transaction processing, and supply chain operations with minimal human intervention, typically integrating barcode scanning, weight verification, and machine vision at throughput rates exceeding thirty items per minute. Its primary commercial purpose centers on labor cost containment, inventory accuracy improvement, and checkout velocity in high-traffic retail environments. POS terminals and self-checkout systems occupy the mature core where replacement cycles and retrofit demand sustain baseline revenue. AI-based predictive analytics and robotics represent the fastest-expanding margin pools as retailers prioritize demand forecasting precision and warehouse labor substitution. Digital shelf labels sit at an inflection point where wireless power and e-ink durability improvements unlock grocery and convenience outlet adoption beyond early electronics retailers.
FDA guidelines on food traceability, FCC rulings on unlicensed spectrum for IoT sensor networks, and EU GDPR constraints on customer analytics data processing collectively shape product architecture and market access requirements for automation vendors. The EU AI Act adds conformity assessment obligations for algorithmic decision systems used in checkout optimization and loss prevention applications. Stakeholders must monitor evolving interoperability standards between robotics platforms and legacy enterprise resource planning systems to avoid stranded technology investments.
Market Dynamics
The EU AI Act conformity assessment obligations for algorithmic checkout and loss prevention systems are forcing vendors to rearchitect product certification paths, compressing time-to-market for AI-enabled retail automation stacks.
Growth Catalysts
- Labor Cost Containment Mandates:Grocery chains in the United States, China, and Germany are deploying self-checkout and robotics at scale to offset wage inflation and workforce shortages in fulfillment operations.
- FCC Unlicensed Spectrum Rulings:The FCC's expansion of unlicensed spectrum for IoT sensor networks enables wireless digital shelf label deployments without proprietary infrastructure investments.
- GDPR-Compliant Analytics:Retailers are prioritizing demand forecasting precision through privacy-preserving machine learning that satisfies EU data processing constraints.
Market Restraints
- Silicon Supply Concentration:Robotics and edge AI hardware remain exposed to Taiwan and South Korea semiconductor foundry bottlenecks.
- EU Conformity Assessment Costs:The EU AI Act adds third-party auditing expenses for algorithmic decision systems, elevating barriers for mid-tier automation vendors.
- Legacy ERP Integration Friction:Interoperability gaps between robotics platforms and enterprise resource planning systems create stranded technology risks.
Strategic Opportunities
- Convenience Store Digital Shelf Labels:Wireless power and e-ink durability improvements unlock grocery and convenience outlet adoption beyond early electronics retailers.
- India Modernization Wave:The country's PLI scheme incentives for electronics manufacturing are attracting fulfillment automation vendors to establish local assembly.
- Machine Vision-Weight Convergence:Integration of computer vision with weight verification at self-checkout is reducing shrinkage without additional hardware layers.
Industry Challenges
- Algorithmic Bias Certification:Retailers must demonstrate fairness in loss prevention AI to satisfy EU AI Act audit requirements, extending deployment timelines.
- Interoperability Standard Delays:Fragmented robotics middleware protocols complicate multi-vendor warehouse automation deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Automation Market |
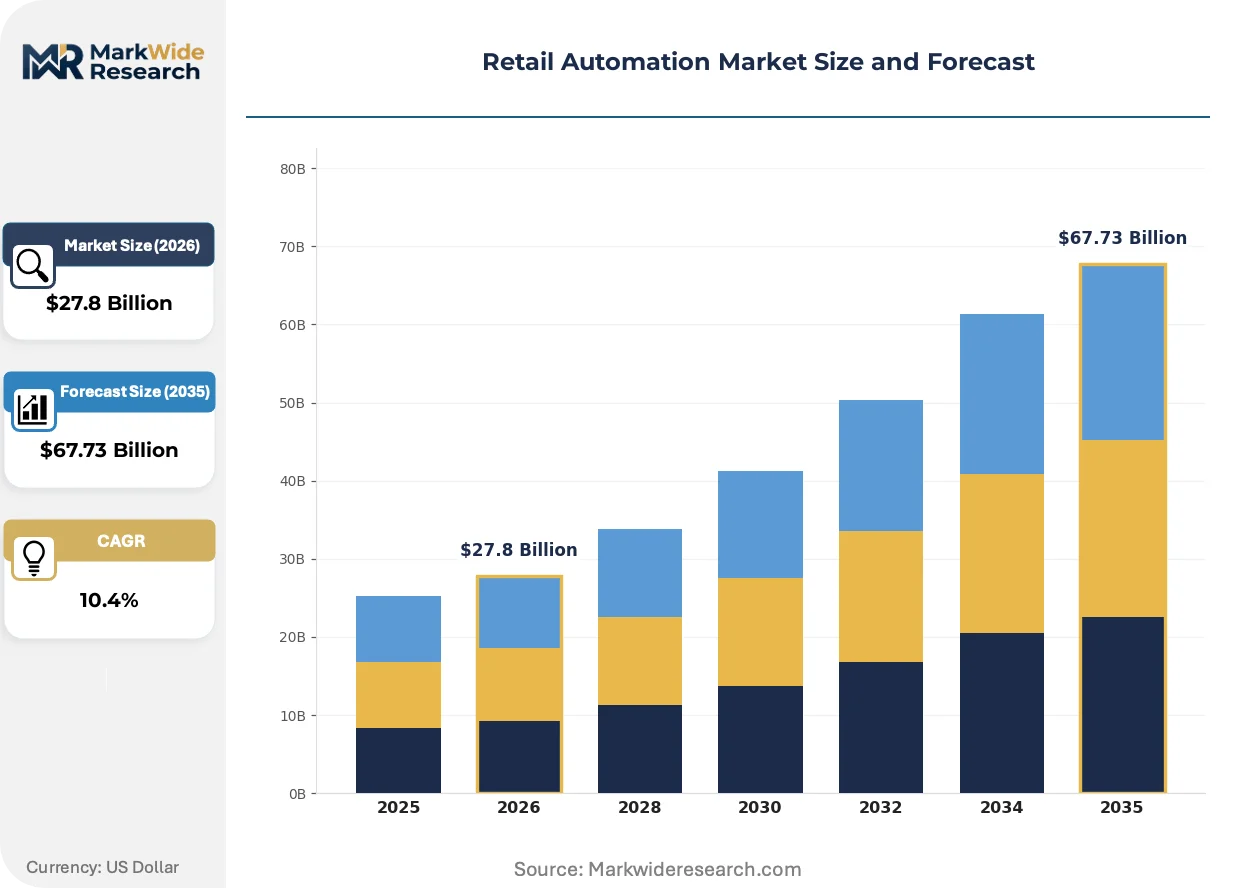
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $67.73 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Self-Checkout Systems, Inventory Management Software, POS Terminals, Customer Analytics Platforms, Digital Shelf Labels Technology: RFID, Computer Vision, AI-Based Predictive Analytics, IoT Sensors, Robotics Application: Checkout Optimization, Stock Replenishment, Loss Prevention, Customer Engagement, Supply Chain Monitoring End User Type: Supermarkets, Specialty Stores, Convenience Outlets, Department Stores, E-commerce Fulfillment Centers |
| Companies Covered | Blue Yonder, Tompkins Robotics, Badger Technologies, Yoobic, Wiser, Hai Robotics, Manhattan Associates, Zipline, Simbe Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Automation Market Strategic Shifts & Innovations
Retail automation is experiencing a convergence of edge AI, wireless sensing, and regulatory compliance architecture that is compressing product development cycles and elevating certification to a competitive differentiator.
Computer vision-based loss prevention is rewriting checkout security economics. Major grocery chains are deploying camera-integrated self-checkout terminals that identify unscanned items without human attendant intervention. This technology is compressing labor requirements while satisfying EU AI Act transparency mandates through explainable algorithmic outputs.
The EU AI Act's risk-based classification system for algorithmic decision systems is mandating conformity assessments for automated checkout optimization and dynamic pricing engines. Retailers operating in Germany, France, and the Netherlands must maintain technical documentation and human oversight protocols. Vendors are responding by embedding audit trails and model interpretability features into their platform architectures.
Buyer concentration among top-ten grocery chains is consolidating procurement leverage and compressing vendor evaluation cycles. Tier-one retailers are unbundling hardware, software, and maintenance contracts to optimize total cost of ownership. This pattern is most pronounced in the United States, where Kroger, Walmart, and Target are standardizing on API-first automation platforms that enable component substitution.
Retail Automation Market Segmentation
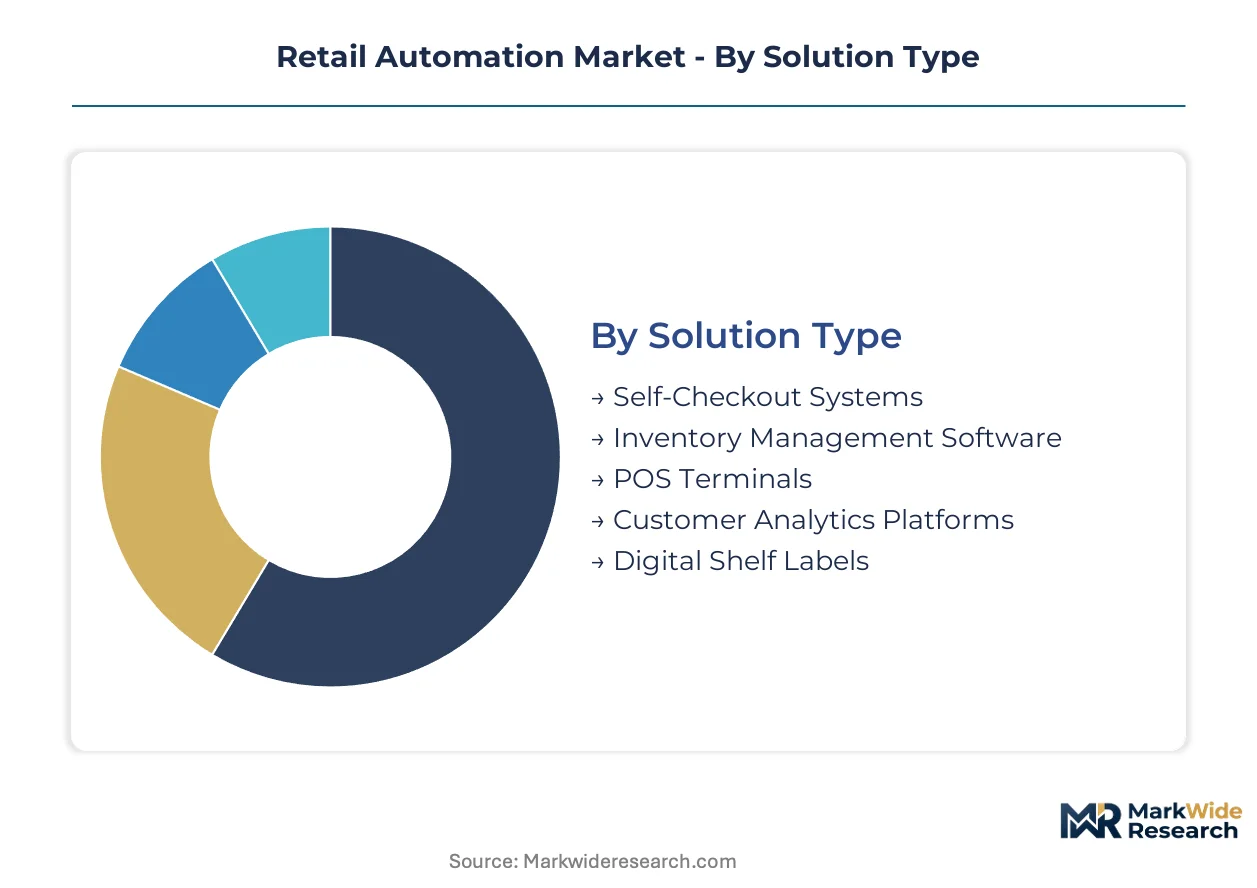
Retail automation procurement splits between mature hardware replacement cycles and emerging software-driven intelligence layers. Understanding where volume concentrates versus where margins expand reveals vendor positioning strategies and buyer negotiation leverage across grocery, specialty, and fulfillment channels.
Solution Type:
Volume dominance sits with transaction hardware, while premium expansion concentrates in analytics and connected shelf infrastructure.
- Self-Checkout Systems:These terminals integrate barcode scanning, weight verification, and payment processing at throughput rates exceeding thirty items per minute. Kroger, Walmart, and Target in the United States are standardizing deployments to offset wage inflation and attendant labor requirements.
- Digital Shelf Labels:Wireless power and e-ink durability improvements now enable grocery and convenience outlet adoption beyond early electronics retailers. FCC unlicensed spectrum rulings eliminate proprietary infrastructure investments, accelerating rollout timelines.
- Inventory Management Software:Warehouse management systems anchor enterprise-grade automation stacks for fulfillment network visibility.
- POS Terminals:Mature replacement cycles sustain baseline revenue across retail chains completing hardware refresh programs.
- Customer Analytics Platforms:GDPR-compliant machine learning architectures satisfy EU data processing constraints while enabling demand forecasting precision.
Today's leader: Self-Checkout Systems. Tomorrow's challenger: Digital Shelf Labels.
Technology:
Deployment economics favor sensor networks at scale, while algorithmic layers capture expanding margin pools.
- Computer Vision:Camera-integrated terminals identify unscanned items without human intervention, compressing labor requirements while satisfying EU AI Act transparency mandates through explainable outputs. Major grocery chains in Germany and France are mandating audit trail capabilities.
- AI-Based Predictive Analytics:Demand forecasting engines process transaction patterns and external signals to optimize replenishment timing and assortment decisions. Retailers prioritize privacy-preserving architectures that satisfy GDPR constraints on customer data processing.
- Robotics:Dense storage automation dominates Asia-Pacific fulfillment networks for labor substitution in high-SKU environments.
- RFID:Item-level tracking enables real-time inventory accuracy without line-of-sight scanning constraints.
- IoT Sensors:Environmental and occupancy monitoring extend visibility into shelf-level conditions and store traffic patterns.
Computer Vision anchors current security economics. AI-Based Predictive Analytics offers the steepest expansion trajectory as retailers prioritize forecasting precision.
Application:
Operational priority shifts from transaction velocity toward inventory intelligence and shrinkage containment.
- Loss Prevention:Algorithmic systems flag anomalous scanning behaviors and unscanned item detection. EU AI Act conformity assessments now mandate fairness documentation and human oversight protocols, extending deployment timelines for vendors serving Germany, France, and Netherlands retailers.
- Checkout Optimization:Dynamic lane assignment and payment flow management reduce queue abandonment in high-traffic environments.
- Stock Replenishment:Automated alerts trigger warehouse movements based on shelf-level depletion signals.
- Customer Engagement:Personalized promotion delivery integrates with loyalty systems at point-of-decision moments.
- Supply Chain Monitoring:End-to-end traceability satisfies FDA food safety guidelines while enabling recall precision.
Loss Prevention commands current capital allocation. Checkout Optimization is gaining share fastest as labor scarcity intensifies.
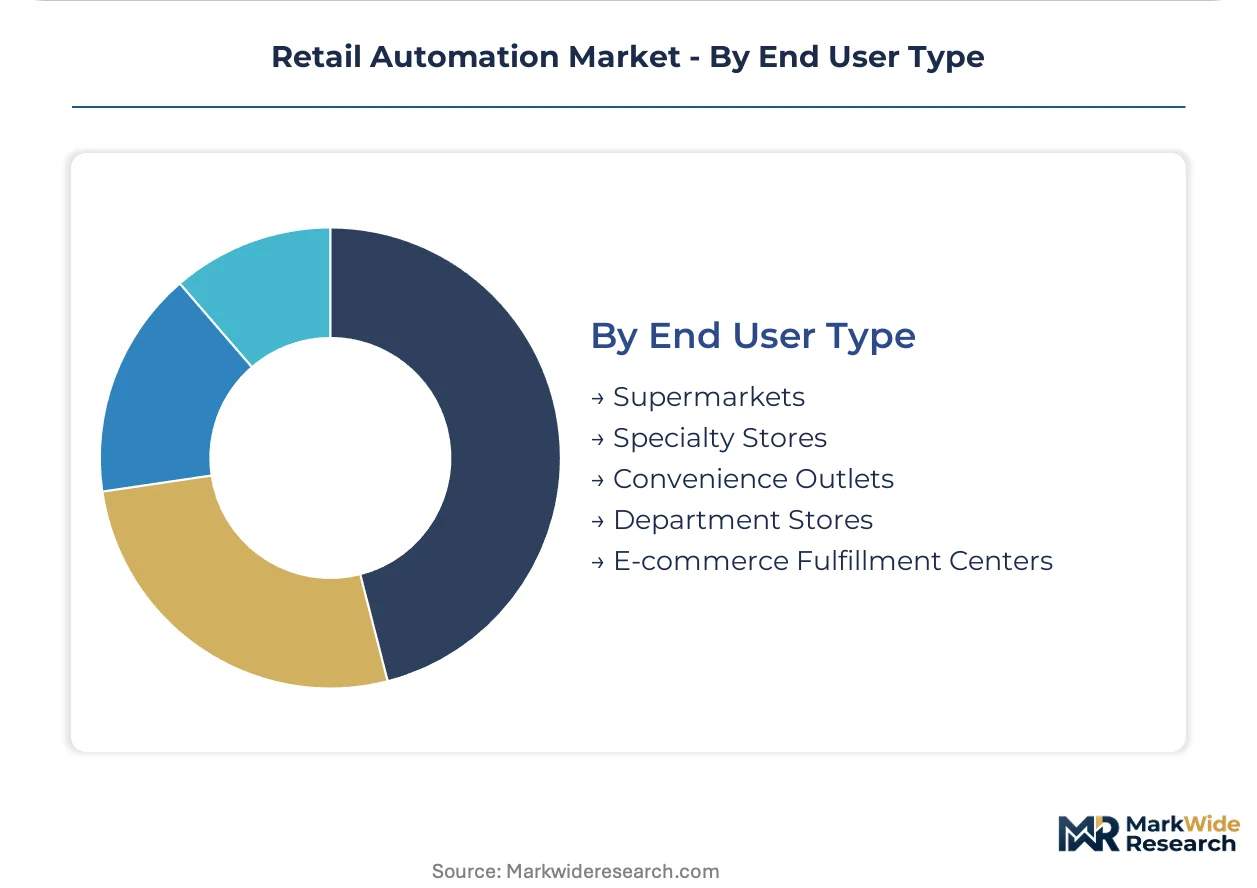
End User Type:
Buyer concentration among top-ten grocery chains consolidates procurement leverage and compresses vendor evaluation cycles.
- Supermarkets:High-SKU environments with complex replenishment requirements drive integrated automation stack investments. United States, China, and Germany retailers are deploying self-checkout and robotics at scale to modernize fulfillment infrastructure.
- E-commerce Fulfillment Centers:Labor substitution priorities accelerate robotics and warehouse management system adoption. India's PLI scheme incentives for electronics manufacturing are attracting vendors to establish local assembly capacity.
- Convenience Outlets:Limited footprints favor compact self-checkout terminals and wireless digital shelf label deployments.
- Specialty Stores:Curated assortments prioritize customer analytics for personalization over inventory velocity.
- Department Stores:Multi-category complexity drives demand for unified commerce platforms bridging physical and digital channels.
Supermarkets dominate procurement volume. E-commerce Fulfillment Centers represent the fastest-climbing segment as online grocery penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce shortages in retail fulfillment and checkout operations concentrate automation demand across three dominant economies. Germany, the United States, and China anchor procurement volume through distinct regulatory and infrastructure pathways.
United States
Kroger, Walmart, and Target are standardizing self-checkout deployments to offset wage inflation in high-traffic stores. FCC rulings on unlicensed spectrum for IoT sensor networks accelerate wireless digital shelf label rollouts without proprietary infrastructure. The Chicago and Dallas-Fort Worth metro areas concentrate pilot programs for camera-integrated loss prevention systems.
Germany
Retailers in Germany face EU AI Act conformity assessment obligations for algorithmic checkout optimization and dynamic pricing engines. GDPR constraints on customer analytics data processing mandate privacy-preserving machine learning architectures. The Rhine-Ruhr corridor hosts dense fulfillment automation clusters serving pan-European distribution networks.
China
Domestic grocery chains deploy dense storage robotics at scale to address fulfillment labor scarcity in high-SKU environments. MIIT standards on industrial IoT interoperability shape vendor certification requirements for warehouse management system integration. The Yangtze River Delta anchors robotics manufacturing and deployment concentration for Asia-Pacific retail networks.
India
The country's PLI scheme incentives for electronics manufacturing attract fulfillment automation vendors to establish local assembly capacity. BIS certification requirements for imported automation hardware extend procurement timelines for multinational retailers. Maharashtra and Karnataka host emerging fulfillment center clusters serving domestic e-commerce penetration growth.
France
French retailers must maintain technical documentation and human oversight protocols under EU AI Act risk-based classification for automated decision systems. CNIL enforcement on algorithmic transparency extends deployment timelines for loss prevention AI. The Île-de-France region concentrates headquarters-level procurement decisions for automation stack investments.
Retail Automation Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the automation stack. The vendor base splits between integrated platform providers and specialized point solution developers. Three archetypes dominate: warehouse management heritage anchors, dense storage robotics specialists, and autonomous inventory scanning innovators. Competitive moves center on API-first architecture standardization and multi-vendor interoperability partnerships.
Within the warehouse management heritage tier, Manhattan Associates exemplifies enterprise-grade automation stack anchoring. Hai Robotics occupies a position representing dense storage robotics specialization for Asia-Pacific fulfillment networks. Simbe Robotics sits within the autonomous inventory scanning archetype, extending shelf-level visibility without infrastructure overhaul requirements.
| Leading Market Players |
|---|
| Blue Yonder |
| Tompkins Robotics |
| Badger Technologies |
| Yoobic |
| Wiser |
| Hai Robotics |
| Manhattan Associates |
| Zipline |
| Simbe Robotics |
| Others |
Cost & Logistics Intelligence
Buyer unbundling of hardware, software, and maintenance contracts across Kroger, Walmart, and Target procurement cycles is compressing vendor margins and forcing supply chain reconfiguration toward component-level sourcing flexibility.
Pricing Analysis
The bundled-versus-unbundled service split now defines competitive positioning across the automation stack. Tier-one retailers standardize on API-first platforms that enable component substitution, eroding integrated-premium pricing power. Price differentiation rests on EU AI Act certification grade and after-sales service bundling. Cost compression in mid-tier point solutions is intensifying because buyer procurement teams now benchmark modular alternatives.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States and German grocery chains, while distributor networks serve mid-tier convenience outlets. Robotics and edge AI hardware draws from Taiwan and South Korea semiconductor foundries. Critical inputs include CMOS image sensors, lithium-ion power cells, and precision servo motors. Single-source vulnerability in advanced node semiconductors elevates delivery risk for computer vision terminals. Distribution runs through systems integrators anchoring warehouse management deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: EU AI Act compliance costs in Germany and France run 40-50% above United States certification expenses, creating margin expansion for vendors with pre-certified architectures.
For Market Incumbents: Deepen vertical integration into edge AI chip design to escape Taiwan foundry bottlenecks and defend margin position against modular point-solution entrants. Anchor enterprise-grade automation stacks through API-first architecture standardization that locks in switching costs. Prioritize EU AI Act pre-certification investment to capture German and French procurement cycles ahead of compliance-delayed rivals. For New Entrants and Emerging Players: Begin with India's PLI scheme incentives for local electronics assembly, leveraging BIS certification timelines to establish fulfillment automation capacity before multinational retailers expand domestic e-commerce networks. Target convenience outlet digital shelf label deployments where wireless power advances reduce infrastructure barriers. Lead with FCC unlicensed spectrum compatibility to bypass proprietary network investments. For Investors and Strategic Acquirers: Asymmetric upside sits with dense storage robotics specialists serving Asia-Pacific fulfillment networks where labor scarcity accelerates warehouse automation penetration. Five-to-ten year viability hinges on multi-vendor interoperability protocol adoption. Monitor MIIT industrial IoT standards convergence as inflection indicator for China vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Accelerates German and French procurement cycles ahead of compliance-delayed competitors. |
| API-First Platform Standardization | Enables component substitution for Kroger, Walmart, and Target procurement optimization. |
| India PLI Scheme Local Assembly | Bypasses BIS import certification delays for domestic e-commerce fulfillment expansion. |
| Computer Vision-Weight Convergence R&D | Reduces shrinkage without hardware layer additions at self-checkout terminals. |
| Multi-Vendor Interoperability Partnership | Mitigates stranded technology risk from fragmented robotics middleware protocols. |
Research Approach
Coverage spans the United States, Germany, China, India, and France, with primary inputs from each market cluster combining executive interviews with grocery chain procurement officers, warehouse operations directors, automation vendor product managers, and systems integration specialists. Secondary validation draws from FCC rulings, EU AI Act technical documentation, MIIT industrial IoT standards, SEC 10-K automation vendor disclosures, and customs trade data. Bottom-up and top-down triangulation reconciles equipment shipment volumes with enterprise software licensing patterns.
Granularity-level modeling segments by solution type, technology layer, application function, and end-user archetype across the projection horizon. CAGRs derive from logistic growth curve fitting against replacement cycle timing and regulatory compliance deadline clustering. Industry-specific forecast inputs include self-checkout terminal deployment schedules from top-ten grocery chains and robotics capital expenditure tracking from Asia-Pacific fulfillment network expansions.
Several conditions sit outside the modeled scope, including tariff rate fluctuations, semiconductor foundry capacity allocation shifts, and unannounced EU AI Act enforcement guidance revisions. Forecasts reflect documented assumptions about labor cost inflation trajectories and unlicensed spectrum allocation stability. Periodic stress-testing of base assumptions is recommended against algorithmic bias audit requirement evolution and legacy ERP integration friction severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Door and Window Automation Market
Automation
Laboratory Automation Market
Automation
Automated Cell Block Systems Market
Automation
Window Automation Market
Automation
Global Smart Vending Machines Market
Automation
North America Marketing Automation Software Market
Automation
Global Warehouse Execution System Market
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
Elevator Control Market
Automation
Process Control Systems for Steel Market
Automation
Network Automation Market
Automation
Distribution Automation Solutions Market
Automation
Computer Numerical Control Market
Automation
Global Zig-Bee Automation Market
Automation
Lab Automation Market
Automation
Automatic Message Handling System Market