
 Process Automation Market | 2026-2036
Process Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Process Automation Market Outlook
Chemical processing is decoupling from manual control systems faster than food and beverage operations. Siemens AG leverages deep vertical integration across distributed control systems to sustain pricing power in European petrochemical installations. ABB Ltd anchors its position through robotics-heavy process automation suites that dominate specialty chemical batch operations. Rockwell Automation differentiates via programmable logic controller ecosystems that control material handling in North American refineries.
Process automation encompasses engineered systems that sense, analyze, and actuate industrial workflows through programmable controllers, field instrumentation, and supervisory software executing closed-loop control algorithms with millisecond response tolerances. Its primary purpose is eliminating process variability, reducing unplanned downtime, and enforcing repeatable quality thresholds across continuous and batch manufacturing environments. Workflow Automation captures expanding margin pools as enterprises layer low-code orchestration atop legacy SCADA investments, while Robotic Process Automation matures into a cost-commodity segment where deployment scale determines vendor viability. Manufacturing end users channel the majority of new capital expenditure into hybrid cloud-edge architectures that unify plant-floor control with enterprise resource planning visibility.
ISO 9001 quality management standards and IEC 61511 functional safety frameworks shape product certification requirements and buyer procurement criteria across process industries. The EU Machinery Directive and OSHA process safety management regulations in the United States enforce hardware redundancy and operator training protocols that inflate system complexity and vendor qualification barriers. Stakeholders must monitor how NIST cybersecurity frameworks for operational technology reshape software update liability and remote access architectures without disrupting continuous process availability.
Market Dynamics
Pharmaceutical manufacturers are decoupling from legacy batch systems as ISO 9001 quality mandates tighten across the European Union, forcing distributed control system vendors to re-engineer architectures for continuous processing validation.
Growth Catalysts
- REACH chemical safety compliance:European petrochemical operators are retrofitting installations with sensor-heavy automation stacks to automate substance tracking and eliminate manual batch record errors.
- Hybrid cloud-edge architectures:Manufacturing end users channel capital expenditure into unified plant-floor control systems that synchronize supervisory data with enterprise resource planning visibility.
- Battery cell manufacturing:Gigafactory construction across Germany and Poland is pulling precision motion control and robotic process automation into electrode coating and cell assembly lines.
Market Restraints
- Semiconductor component volatility:Field instrumentation and programmable logic controller supply chains remain exposed to foundry capacity constraints in Taiwan and South Korea.
- Specialized systems integrator concentration:Complex petrochemical automation deployments depend on a thin layer of certified engineering firms concentrated in Germany's industrial corridor.
- Cybersecurity liability fragmentation:NIST cybersecurity frameworks for operational technology create ambiguous software update liability between control system vendors and end-user operators.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic pharmaceutical and agrochemical manufacturers qualify for production-linked incentives that subsidize automation capex in batch processing facilities.
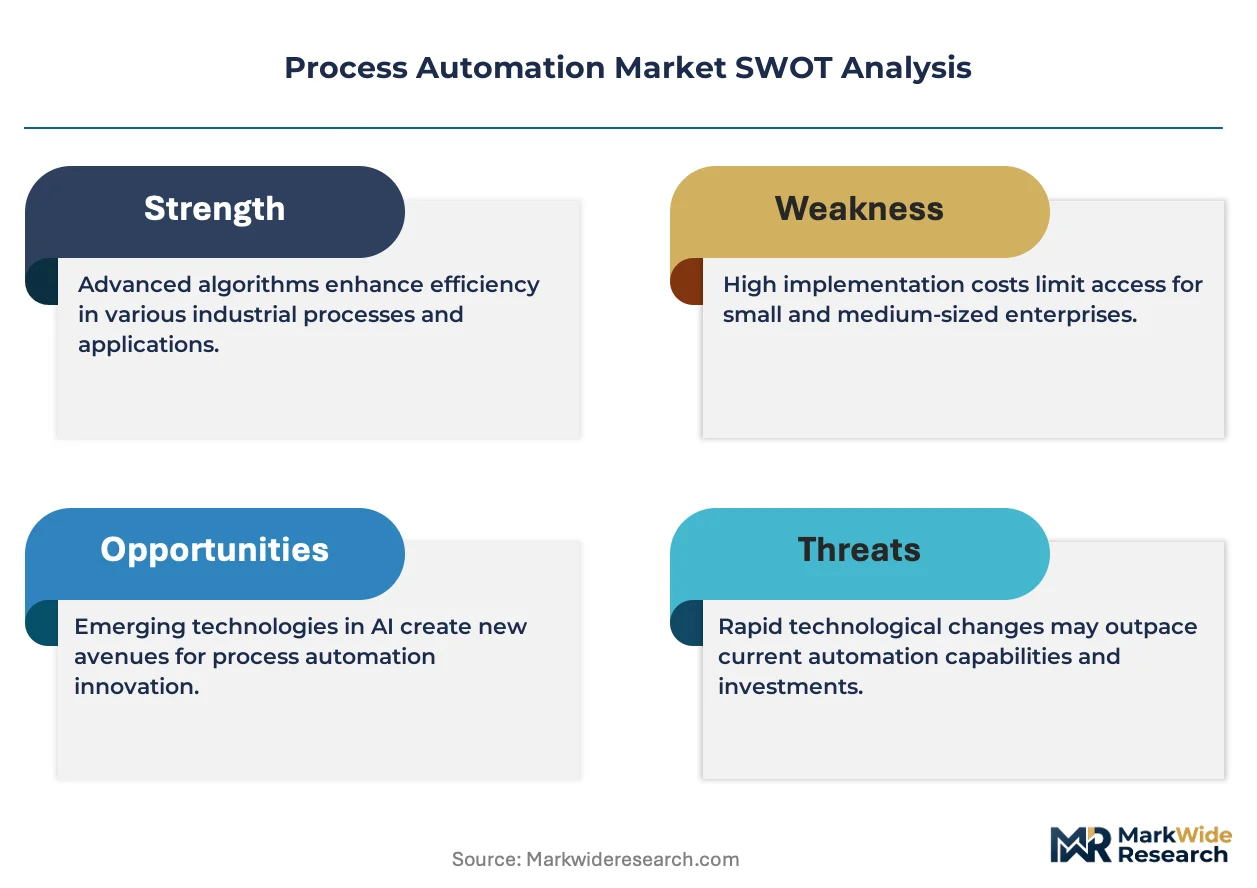
- Digital twin convergence with AI-driven predictive maintenance:Vendors bundling physics-based simulation with machine learning anomaly detection can capture service revenue from continuous process industries.
- Modular skid-mounted systems:Prefabricated process units with embedded automation reduce field commissioning time and open channel sales through engineering procurement contractors.
Industry Challenges
- IEC 61511 functional safety certification timelines:Safety instrumented system validation for process industries stretches 18-24 months, compressing product launch windows and inflating project risk reserves.
- Interoperability friction between proprietary protocols:Legacy SCADA investments using vendor-specific fieldbus architectures resist integration with open-standard OPC UA middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Automation Market |
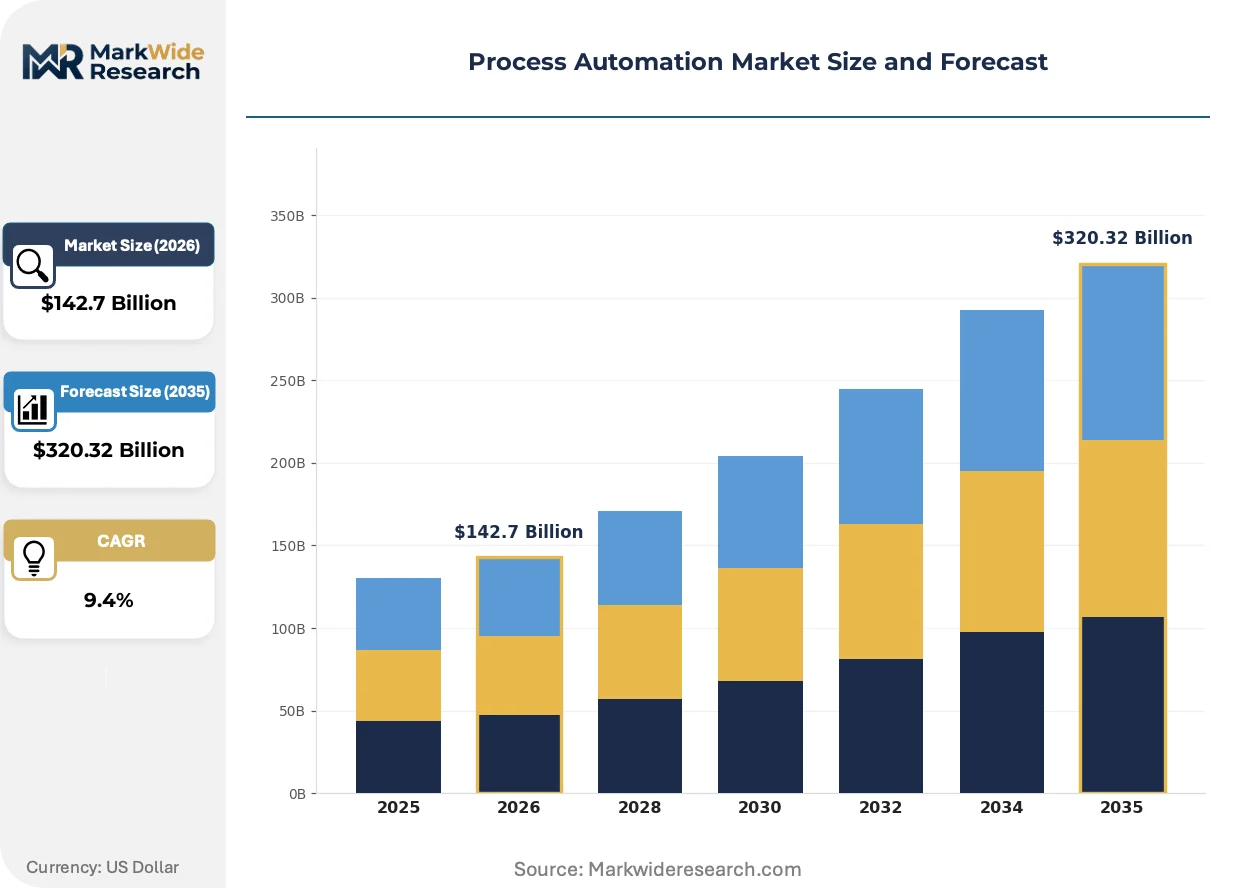
| Market Size in 2026 | $142.7 Billion |
| Market Size in 2035 | $320.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Robotic Process Automation, Artificial Intelligence, Machine Learning, Workflow Automation End User: Manufacturing, BFSI, Retail, Telecommunications Deployment: On-Premise, Cloud, Hybrid, Managed Services Application: Supply Chain Management, Inventory Management, HR Automation, Customer Service |
| Companies Covered | Siemens AG, ABB Ltd, Schneider Electric, Emerson Electric Co., Honeywell International Inc., Rockwell Automation, General Electric Company, Eaton Corporation plc, Dassault Systemes SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Automation Market Strategic Shifts
Artificial intelligence inference at the edge is compressing control loop response times while forcing vendors to re-architect hardware for thermal and electromagnetic constraints in hazardous process environments.
Digital twin platforms are automating real-time synchronization between physical assets and virtual models across continuous chemical processing. BASF and Dow have deployed these systems at scale in German and US Gulf Coast refineries. The technology is automating scenario testing for control setpoint adjustments without disrupting live production.
The EU AI Act's risk classification framework for industrial automation systems is mandating algorithmic transparency and human oversight protocols for safety-critical process control. European machinery manufacturers must now document training data provenance and decision logic for AI-enabled quality inspection systems. Specialty chemical batch operations in Belgium and the Netherlands face the steepest compliance ramps.
After-sales service unbundling is fragmenting traditional automation vendor revenue models as end users source spare parts and technical support through third-party industrial marketplaces. North American refineries and pulp mills now procure programmable logic controller modules and field instrumentation through distributor aggregators rather than direct OEM contracts. This pattern is most visible in the US Midwest manufacturing belt where maintenance procurement teams prioritize cost transparency over single-source relationships.
Process Automation Market Segmentation
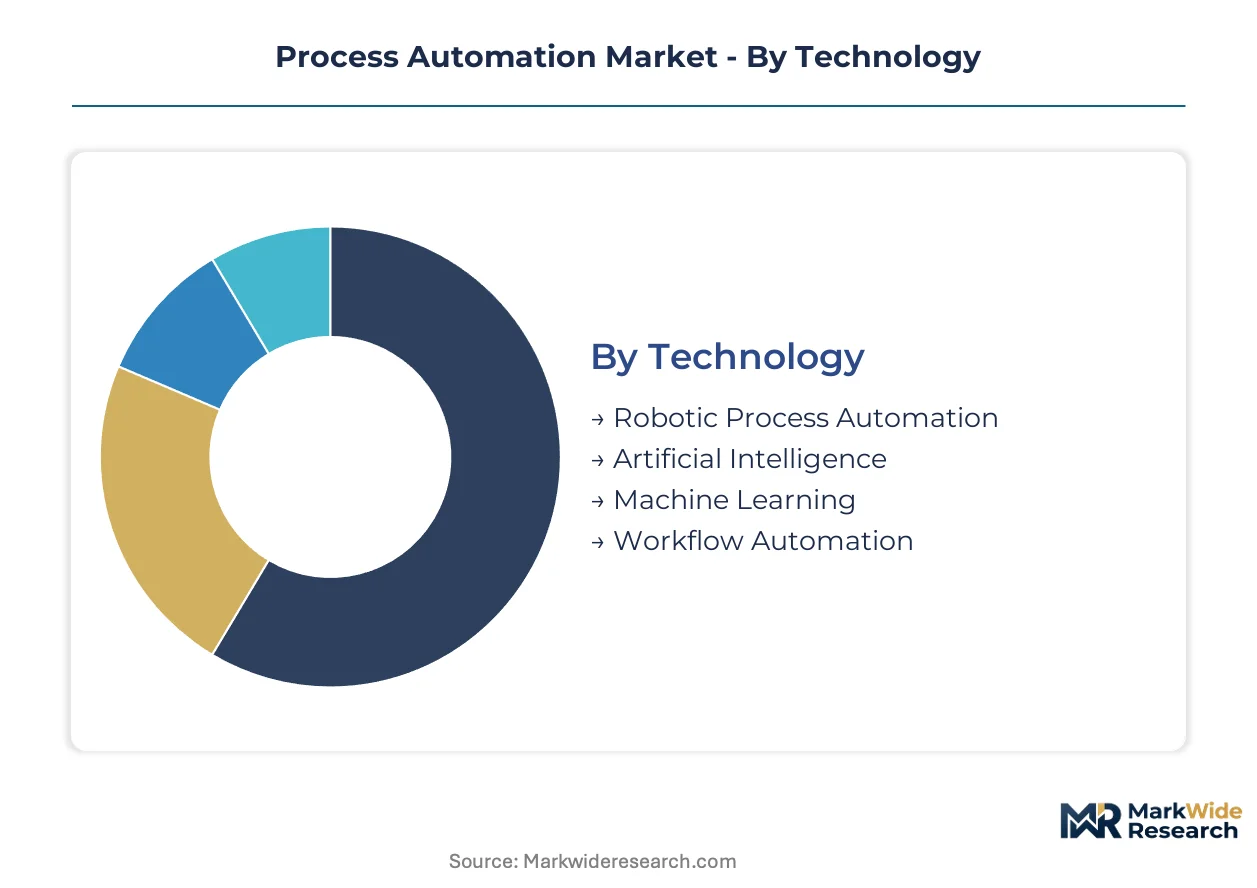
Process automation procurement splits sharply between capital-heavy plant-floor systems and software-centric workflow tools. Understanding where engineering intensity concentrates versus where subscription models dominate shapes vendor strategy and buyer budgeting cycles across industrial and service sectors.
Technology:
Capital intensity peaks in AI and machine learning infrastructure requiring specialized edge hardware and thermal management for hazardous environments, while software-only segments demand lighter upfront commitment.
- Artificial Intelligence:Inference engines process sensor data at millisecond tolerances using ruggedized GPUs in petrochemical and pharmaceutical batch operations. German industrial corridors anchor demand as REACH compliance mandates real-time substance tracking with predictive anomaly detection.
- Machine Learning:Algorithm training pipelines for predictive maintenance require cloud-scale compute resources and continuous data lake expansion. Battery cell gigafactories across Germany and Poland pull the steepest investment as electrode coating tolerances tighten.
- Robotic Process Automation:Screen-scraping and API orchestration tools automate back-office workflows with minimal infrastructure overhead.
- Workflow Automation:Low-code platforms layer atop legacy SCADA through OPC UA middleware, unifying plant-floor and enterprise visibility.
Most installed capacity flows through Robotic Process Automation. Expansion is steepest in Artificial Intelligence.
End User:
Application complexity varies from continuous process control in heavy industry to discrete transaction processing in services, reshaping implementation timelines and integration architecture.
- Manufacturing:Distributed control systems synchronize continuous chemical processing with enterprise resource planning through hybrid cloud-edge stacks. ISO 9001 validation requirements in European pharmaceutical plants extend commissioning cycles and inflate project reserves.
- BFSI:Compliance automation for transaction monitoring and anti-money laundering rules drives document processing robotics. India's PLI scheme for specialty chemicals indirectly funds adjacent financial automation as corporate treasury operations scale.
- Retail:Warehouse robotics and inventory orchestration platforms manage fulfillment velocity.
- Telecommunications:Network provisioning automation and customer churn prediction models optimize infrastructure utilization.
Manufacturing carries the heaviest legacy integration burden. BFSI is climbing fastest as regulatory reporting obligations multiply.
Deployment:
Operational technology security requirements and latency tolerances fragment architecture choices between air-gapped plant floors and cloud-native service layers.
- Hybrid:Unified plant-floor and enterprise visibility architectures dominate capital expenditure as manufacturers synchronize supervisory control with ERP systems. NIST cybersecurity frameworks reshape software update liability and remote access protocols without disrupting continuous availability.
- On-Premise:Air-gapped distributed control systems satisfy IEC 61511 functional safety mandates in petrochemical and pharmaceutical environments with 18-24 month validation timelines.
- Cloud:SaaS workflow platforms reduce upfront automation capex for mid-market manufacturers.
- Managed Services:Third-party industrial marketplaces now unbundle after-sales support and spare parts procurement.
Hybrid architectures absorb the majority of new capital allocation. Managed Services is gaining share fastest as procurement teams prioritize cost transparency.
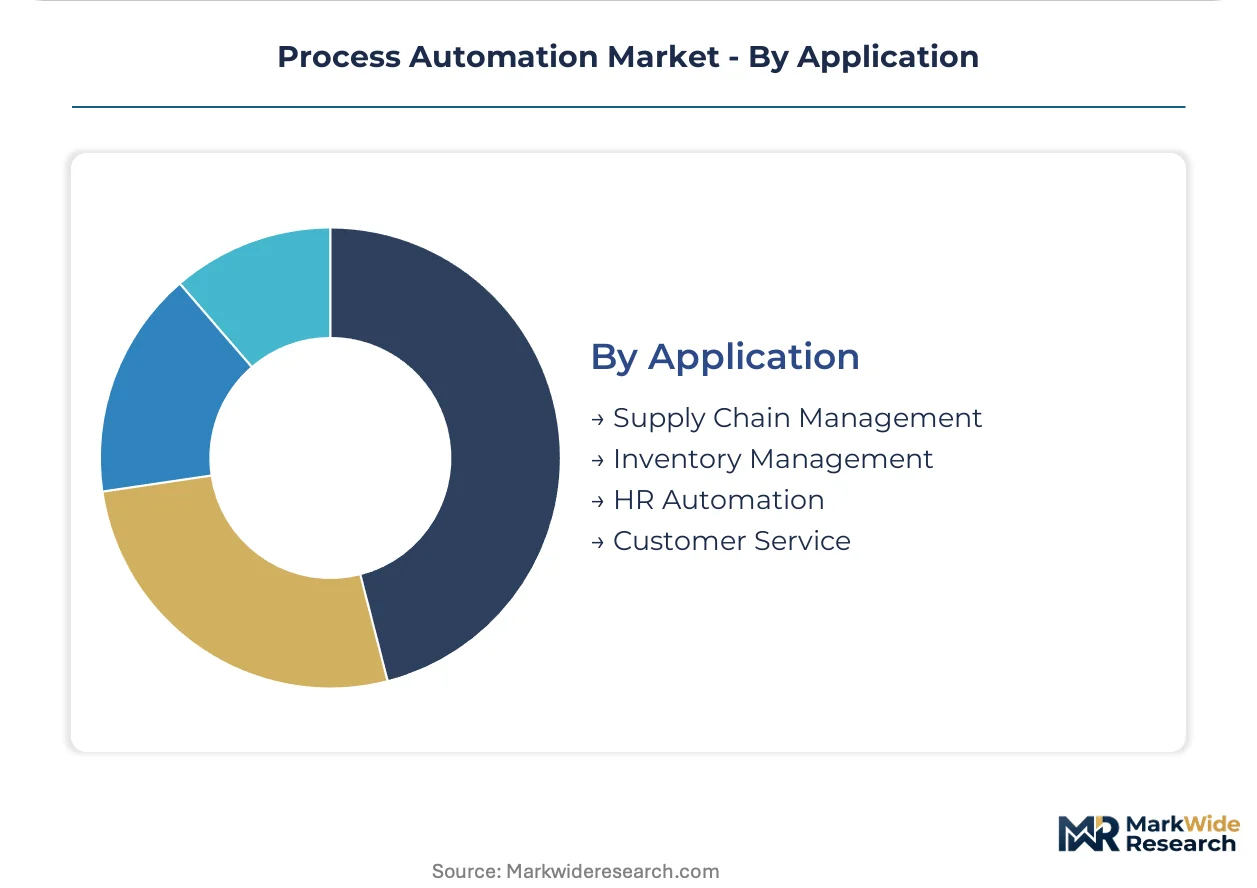
Application:
Process variability reduction targets differ between physical material flows and human capital workflows, determining sensor density and control loop architecture.
- Supply Chain Management:Real-time inventory positioning and demand sensing automate procurement decisions across multi-tier supplier networks. REACH substance tracking mandates in European petrochemical operations retrofit sensor-heavy automation stacks.
- Inventory Management:Automated storage and retrieval systems with machine vision quality inspection reduce picking errors in high-velocity fulfillment centers.
- HR Automation:Document processing and onboarding workflows streamline administrative overhead.
- Customer Service:Conversational AI and ticket routing algorithms manage inquiry volume scaling.
Supply Chain Management commands the largest installed base. Inventory Management is expanding most quickly as e-commerce fulfillment complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration tracks regulatory cost differentials as REACH compliance inflates European capex and India's PLI subsidies pull pharmaceutical batch automation eastward. Manufacturers arbitrage IEC 61511 validation timelines against local incentive structures when siting new continuous processing facilities.
Germany
Battery cell gigafactories across Lower Saxony and Baden-Württemberg pull precision motion control systems into electrode coating lines. The EU AI Act mandates algorithmic transparency for safety-critical process control, forcing documentation of training data provenance. BASF's Ludwigshafen complex deploys digital twin platforms for real-time refinery optimization.
United States
OSHA process safety management regulations enforce hardware redundancy in Gulf Coast petrochemical installations. North American refineries now procure PLC modules through third-party industrial marketplaces rather than direct OEM contracts. The Midwest manufacturing belt concentrates maintenance procurement teams prioritizing cost transparency over single-source relationships.
India
Domestic pharmaceutical and agrochemical manufacturers qualify for PLI scheme subsidies that fund automation capex in batch processing facilities. The Central Electricity Authority mandates grid synchronization standards that shape distributed control system architectures. Gujarat's specialty chemical corridor anchors retrofit demand as ISO 9001 quality mandates tighten for export certification.
China
Dual carbon goals accelerate sensor-heavy automation stacks in petrochemical operations for real-time emissions tracking. The Ministry of Ecology and Environment enforces substance tracking protocols that mirror REACH compliance structures. Yangtze River Delta refineries retrofit legacy SCADA with hybrid cloud-edge architectures unifying plant-floor and ERP visibility.
Poland
Gigafactory construction in the Silesian industrial region pulls robotic process automation into cell assembly lines. EU Machinery Directive compliance inflates system complexity for safety instrumented system validation. The Katowice-Opole corridor concentrates demand for modular skid-mounted systems reducing field commissioning timelines.
Process Automation Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with distributed control system vendors commanding consolidated positions in continuous processing while workflow automation fragments into low-code platform competition. Siemens AG and ABB Ltd anchor the European industrial corridor through deep vertical integration across hardware and software stacks. Three archetypes dominate: diversified industrial conglomerates with captive automation divisions, pure-play control system specialists, and emerging AI-native challengers bundling predictive maintenance services. Competitive moves concentrate on M&A for functional safety certification capabilities and strategic partnerships bridging proprietary fieldbus protocols with open-standard OPC UA middleware.
Within the diversified industrial tier, Siemens AG and ABB Ltd exemplify European-anchored conglomerates with captive automation divisions spanning distributed control systems and robotics-heavy process suites. Rockwell Automation occupies a position representing North American PLC ecosystem specialists defending programmable logic controller dominance in material handling applications. Schneider Electric sits within the energy management-to-automation convergence archetype, leveraging power distribution heritage into hybrid cloud-edge architectures.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Schneider Electric |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Rockwell Automation |
| General Electric Company |
| Eaton Corporation plc |
| Dassault Systemes SE |
| Others |
Value Chain & Pricing Dynamics
North American refinery procurement teams concentrate maintenance spend through third-party industrial marketplaces, locking in contract-based long-term offtake pricing for programmable logic controller modules and field instrumentation. This buyer concentration feeds back into supplier channel strategies, forcing automation vendors to unbundle after-sales service and compete on parts transparency rather than single-source loyalty.
Pricing Analysis
Distributor margins in European process automation absorb 15-25 point spreads between OEM list pricing and end-user contract rates. Three-tier pricing structure across premium, standard, and economy levels separates safety-certified IEC 61511 systems from general-purpose distributed control architectures. Pricing pressure stems from semiconductor component volatility inflating hardware input costs. Mid-market manufacturers exhibit highest price sensitivity, while pharmaceutical batch operators accept premium tiers for validation documentation.
Supply Chain Analysis
India's PLI scheme domestic-content mandates reshape sourcing patterns for specialty chemical automation capex. Component supply draws from Taiwan and South Korea for field instrumentation semiconductors, Germany for precision motion control systems, and China for sensor assemblies. Single-source vulnerability concentrates in foundry capacity for ruggedized edge computing hardware. Distribution runs through certified systems integrators concentrated in Germany's industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process automation functions as a stable compounder, with regulatory compliance mandates across the European Union and United States enforcing non-discretionary replacement cycles regardless of industrial capex cycles.
For Market Incumbents: Anticipate margin compression from AI-native challengers bundling predictive maintenance services by deepening certification moats around IEC 61511 functional safety validation. Prioritize backward integration into edge hardware thermal management to defend pricing power in hazardous environment deployments. Channel control through captive systems integrator networks in Germany's industrial corridor remains the critical defensive lever. For New Entrants and Emerging Players: REACH in Europe opens a window for sensor-heavy automation stacks targeting substance tracking retrofits in petrochemical installations. White-space concentrates in modular skid-mounted systems for Poland's gigafactory corridor, where field commissioning speed trumps brand heritage. India's PLI scheme for specialty chemicals offers the most penetrable geography for batch processing automation. Go-to-market should route through engineering procurement contractors rather than direct OEM competition. For Investors and Strategic Acquirers: Industrial conglomerates with captive automation divisions are the most active acquirer in this space, seeking functional safety certification capabilities to fill portfolio gaps. Long-term viability centers on vendors bridging proprietary fieldbus protocols with open-standard OPC UA middleware. Acquisition targets should display certified engineering density in continuous process verticals. Watch NIST cybersecurity framework implementation timelines as inflection indicator for software update liability restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Investment | IEC 61511 validation capabilities compress competitor launch windows in petrochemical markets. |
| Hybrid Cloud-Edge Architecture Deployment | Unified plant-floor ERP visibility captures capital expenditure from BASF and Dow refinery modernization. |
| Modular Skid-Mounted System Development | Prefabricated process units reduce commissioning time for Poland's Silesian gigafactory cluster. |
| AI-Driven Predictive Maintenance Bundling | Physics-based simulation with machine learning captures service revenue from continuous chemical processing. |
| Third-Party Marketplace Channel Partnership | Industrial distributor aggregators unlock North American mid-market procurement spend. |
Study Parameters
Multiple input streams — plant manager interviews, OEM procurement lead discussions, aftermarket service head conversations, and regulatory affairs director briefings — were reconciled against customs trade data, SEC 10-K automation segment disclosures, and ECHA REACH compliance filings. Bottom-up project pipeline tracking across Germany's industrial corridor and top-down vendor revenue analysis triangulated market sizing.
Data-stream reconciliation applied across technology, end-user, deployment, and application segmentation dimensions throughout the forecast period. CAGRs derived from weighted average of capital expenditure trajectories in battery cell manufacturing, pharmaceutical batch modernization, and petrochemical retrofit cycles. Modeled inputs incorporated ISO 9001 validation timeline inflation and NIST cybersecurity framework compliance cost absorption.
Revisions become necessary when semiconductor foundry capacity constraints intensify, EU AI Act enforcement timelines accelerate, or India's PLI scheme subsidy structures shift. Forecasts reflect documented assumptions on regulatory stability and industrial capital availability. A small set of named triggers — IEC 61511 certification backlog expansion, OPC UA middleware adoption velocity, and third-party marketplace procurement penetration — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
APAC Water Automation and Instrumentation Market
Automation
Home Automation System Market
Automation
Marketing Automation Solutions Market
Automation
United States Laboratory Automation Market
Automation
Dropshipping Automation Software Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
Parcel Sorting System Market
Automation
Computer Numerical Control Market
Automation
Workload Scheduling and Automation Market
Automation
Home Automation and Controls Market
Automation
Global Door and Window Automation Market
Automation
North America Data Center Automation Market
Automation
Automation Testing Market
Automation
Pneumatic Tube System Market
Automation
Global Warehouse Barcode System Market
Automation
Elevator Control Market