
 North America Data Center Automation Market | 2026-2036
North America Data Center Automation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Data Center Automation Market Analytics
Software-defined infrastructure is rewriting how North American data centers provision compute and storage resources across distributed environments. Microsoft Corporation leverages its Azure Stack and hybrid cloud portfolio to anchor enterprise automation deployments across multi-site footprints. Cisco Systems Inc. competes through silicon-to-software integration that extends programmable networking into server and storage domains. IBM Corporation specializes in AIOps-driven predictive maintenance for mission-critical mainframe and cloud-native workloads.
Data center automation encompasses the orchestration of physical and virtual infrastructure through policy-driven software controllers that manage server provisioning, network configuration, storage allocation, and thermal load balancing with sub-second response thresholds. Its primary commercial purpose is eliminating manual intervention in facility operations while maintaining uptime guarantees above 99.999%. Server Automation and Network Management command the largest share of deployed capital as legacy three-tier architectures migrate to spine-leaf topologies requiring zero-touch provisioning. Cloud Computing and Artificial Intelligence represent the fastest-expanding technology layers, with inference-optimized GPU clusters demanding autonomous workload placement that static rule engines cannot deliver. Consulting and Managed Services capture disproportionate margin pools as enterprises lack internal Site Reliability Engineering depth.
FCC regulations governing edge computing spectrum allocation interact with NIST cybersecurity frameworks to mandate encrypted telemetry and automated patch compliance for critical infrastructure operators. EPA ENERGY STAR and state-level renewable portfolio standards in California and Texas shape cooling architecture decisions and carbon accounting automation requirements. Stakeholders must weigh in-house platform development against vendor consolidation risk as Broadcom's VMware strategy and BMC's mainframe-to-cloud bridge define divergent ecosystem bets.
Market Dynamics
Hyperscale cloud providers in Northern Virginia's Data Center Alley are compressing deployment cycles for automated orchestration platforms as power density requirements exceed 50kW per rack, forcing facility operators to eliminate manual provisioning entirely.
Growth Catalysts
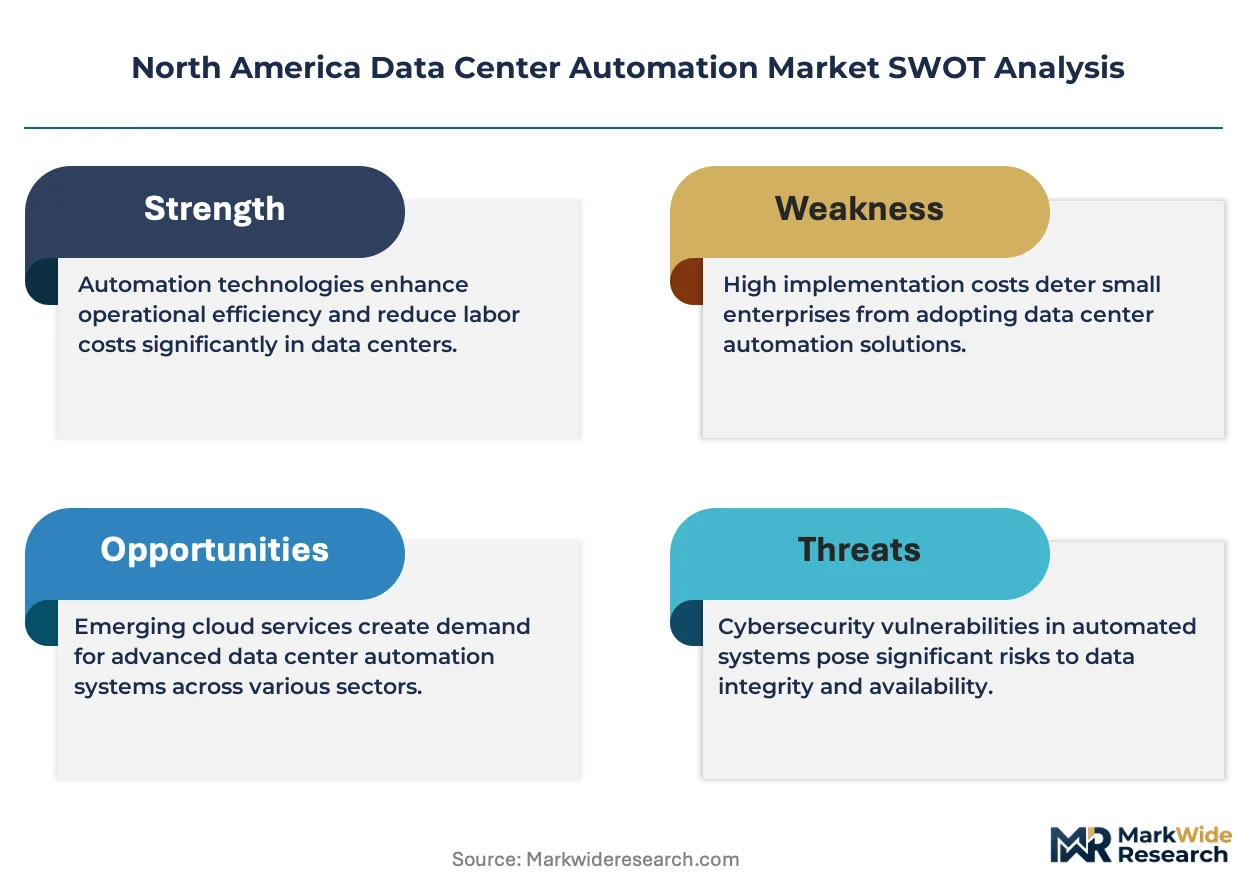
- NIST Cybersecurity Framework:Mandatory encrypted telemetry and automated patch compliance for critical infrastructure operators creates procurement pull for integrated security orchestration layers.
- GPU Cluster Density:Inference-optimized AI workloads demand autonomous workload placement that static rule engines cannot deliver, accelerating silicon-to-software integration investments.
- Texas Renewable Portfolio Standards:State-level mandates for carbon accounting automation reshape cooling architecture decisions and drive thermal load balancing software upgrades.
Market Restraints
- Power Infrastructure Bottlenecks:Utility interconnection queues in Northern Virginia and Dallas-Fort Worth extend 36-48 months, constraining physical expansion regardless of software readiness.
- VMware Ecosystem Consolidation:Broadcom's licensing strategy creates vendor lock-in risk that delays enterprise migration decisions and fragments multi-cloud orchestration roadmaps.
- Sub-second Response Thresholds:Latency requirements for autonomous thermal management exceed capabilities of legacy BACnet implementations, forcing premature infrastructure replacement.
Strategic Opportunities
- Edge Computing Spectrum Allocation:FCC regulations governing CBRS and millimeter-wave bands enable distributed automation nodes for manufacturing and autonomous vehicle infrastructure in the US Midwest.
- Consulting and Managed Services:Enterprise Site Reliability Engineering skill gaps create margin pools for third-party automation platform management and policy optimization.
- Spine-Leaf Topology Migration:Legacy three-tier architectures in financial services and healthcare verticals require zero-touch network provisioning, opening greenfield deployment windows.
Industry Challenges
- Certification Timeline Compression:EPA ENERGY STAR and state efficiency mandates require simultaneous compliance documentation across cooling, power distribution, and carbon reporting systems.
- Integration Complexity:Mainframe-to-cloud bridge implementations demand specialized engineering talent that competes with hyperscale direct hiring, inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Data Center Automation Market |
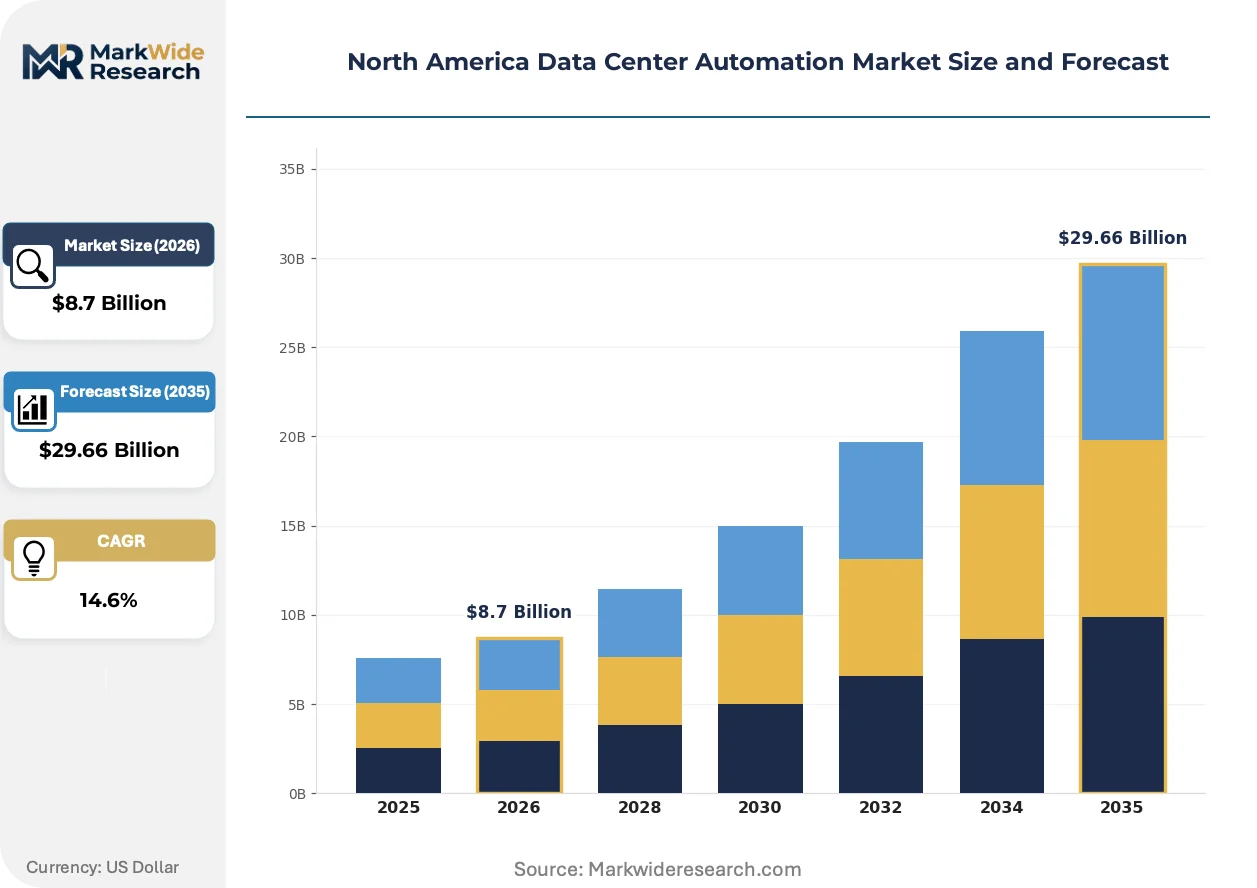
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Server Automation, Network Management, Storage Automation, Environmental Monitoring Service Type: Consulting, Managed Services, Deployment, Support Services Technology: Artificial Intelligence, Machine Learning, Virtualization, Cloud Computing End User: Telecommunications, BFSI, Healthcare, E-Commerce |
| Companies Covered | BMC Software, Inc., Microsoft Corporation, IBM Corporation, Cisco Systems Inc., Dell Inc., Broadcom, Arista Networks, Inc., Micro Focus, Fujitsu, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Data Center Automation Market Evolving Landscape
Software-defined infrastructure controllers are actively compressing the boundary between compute orchestration and facility management, collapsing previously separate operational domains into unified policy engines.
Intent-based networking is hybridizing server provisioning with thermal load balancing through API-driven controllers that translate business policies into infrastructure configurations. Financial services and healthcare enterprises in Chicago and Toronto are deploying these systems at 18-month refresh cycles. This convergence is hybridizing previously siloed data center operations teams into unified platform engineering functions.
EPA ENERGY STAR certification requirements now mandate automated carbon intensity reporting for facilities exceeding 1MW capacity, forcing real-time telemetry integration across cooling and power distribution layers. California's Title 24 building efficiency standards extend these requirements to backup generator testing protocols. Operators in Silicon Valley and Phoenix are responding by deploying digital twin simulations for compliance scenario modeling.
Enterprise buyers are consolidating vendor relationships from an average of seven automation tool providers to three integrated platforms, compressing procurement evaluation cycles from 14 months to 8 months. This concentration is displacing point-solution vendors in network configuration management and server provisioning segments. The pattern is most visible in Northern Virginia, where hyperscale-adjacent colocation providers prioritize single-vendor orchestration stacks to reduce interoperability risk.
North America Data Center Automation Market Segmentation
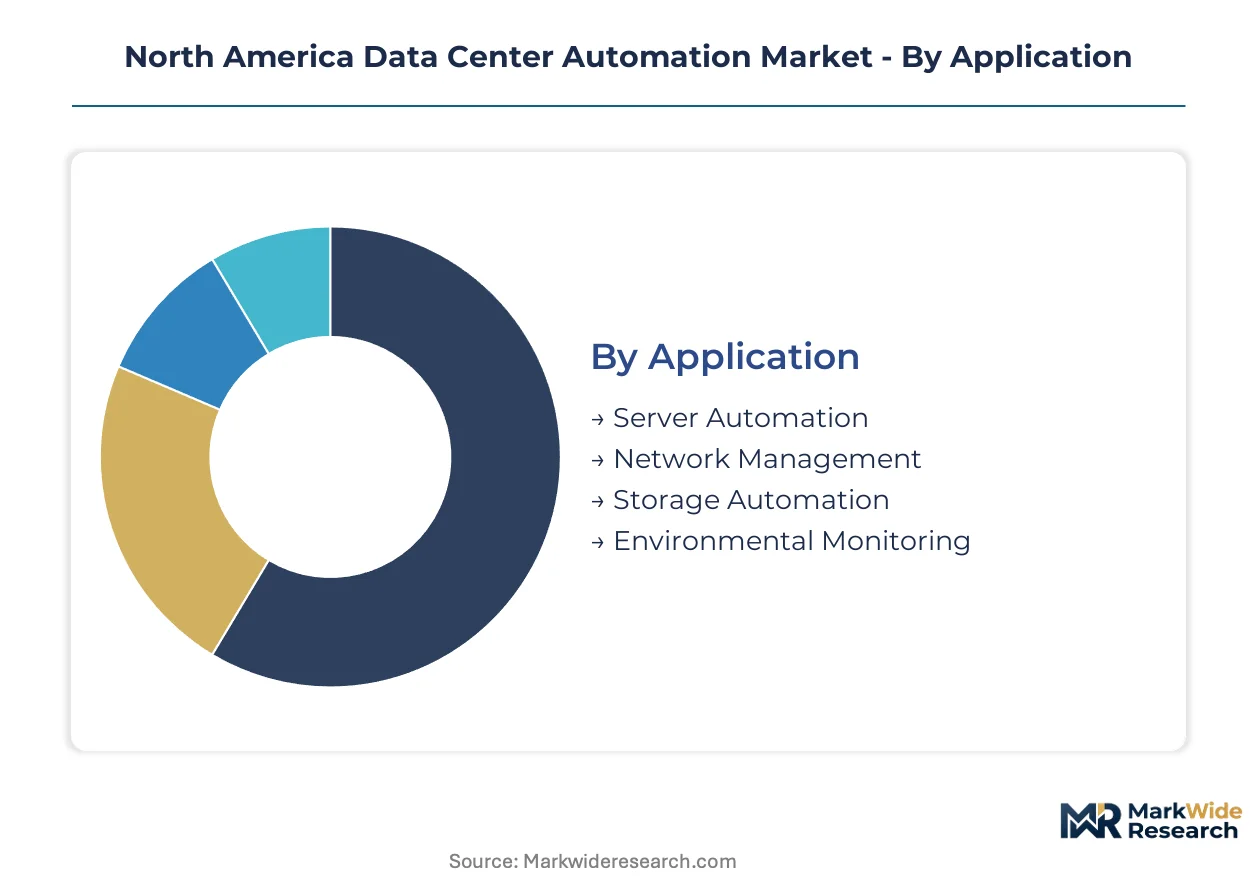
Segmentation in North American data center automation reveals how procurement decisions split between mature infrastructure replacement and emerging workload types. Understanding these divides helps vendors calibrate platform investments against actual deployment velocity across facility tiers.
Application:
Mature segments dominate capital deployment while emerging categories reshape operational priorities.
- Server Automation:Policy-driven provisioning engines orchestrate bare-metal and virtualized compute resources across distributed footprints. Northern Virginia's Data Center Alley consumes the majority of new licenses as hyperscale operators eliminate manual rack-and-stack workflows. NIST cybersecurity frameworks mandate encrypted credential rotation that only automated agent-based systems can satisfy at scale.
- Network Management:Intent-based controllers translate business policies into switch and router configurations with sub-second convergence. Financial services enterprises in Chicago and Toronto deploy these at 18-month refresh cycles to support spine-leaf topology migrations. Static CLI-based provisioning cannot meet latency thresholds for AI inference clusters exceeding 50kW per rack.
- Storage Automation:Tiered data placement across flash, disk, and object tiers based on access patterns and compliance retention policies.
- Environmental Monitoring:Real-time telemetry integration across cooling and power distribution layers for EPA ENERGY STAR carbon intensity reporting.
Server Automation handles the majority of throughput; Environmental Monitoring is expanding most quickly on share.
Service Type:
Margin concentration follows capability scarcity rather than transaction volume.
- Consulting:Advisory engagements for platform selection, policy architecture, and multi-vendor integration roadmapping. Healthcare and BFSI verticals in Texas and California rely on third-party expertise to bridge mainframe-to-cloud implementations. Enterprise Site Reliability Engineering skill gaps sustain premium billing rates regardless of automation software maturation.
- Managed Services:Ongoing platform administration, patch compliance, and policy optimization delivered under outcome-based contracts. Colocation providers in Northern Virginia outsource orchestration layer management to focus on physical infrastructure. Broadcom's VMware licensing complexity accelerates demand for vendor-agnostic operational support.
- Deployment:Physical installation, configuration validation, and cutover execution for automation controller rollouts.
- Support Services:Break-fix resolution, version upgrades, and technical account management for licensed platforms.
Consulting captures the highest margin per engagement; Managed Services is gaining share fastest as internal capability gaps persist.
Technology:
Adoption velocity separates proven infrastructure layers from experimental deployments.
- Artificial Intelligence:Autonomous workload placement, predictive failure detection, and anomaly-driven policy adjustment for GPU-intensive clusters. Inference-optimized deployments in Silicon Valley and Phoenix demand placement engines that static rule-based systems cannot deliver. Sub-second thermal response thresholds exceed legacy BACnet capabilities, forcing controller replacement cycles.
- Machine Learning:Pattern recognition across telemetry streams to optimize cooling setpoints and power distribution efficiency. Texas renewable portfolio standards mandate carbon accounting automation that ML-based forecasting engines satisfy. EPA ENERGY STAR certification requirements now extend to backup generator testing protocols through predictive maintenance models.
- Virtualization:Hypervisor abstraction enabling workload mobility and resource pooling across heterogeneous hardware generations.
- Cloud Computing:API-native orchestration bridging on-premises infrastructure with hyperscale service consumption patterns.
Cloud Computing anchors the installed base; Artificial Intelligence shows the steepest expansion trajectory as GPU density requirements climb.
End User:
Procurement sophistication varies sharply across regulated and consumer-facing verticals.
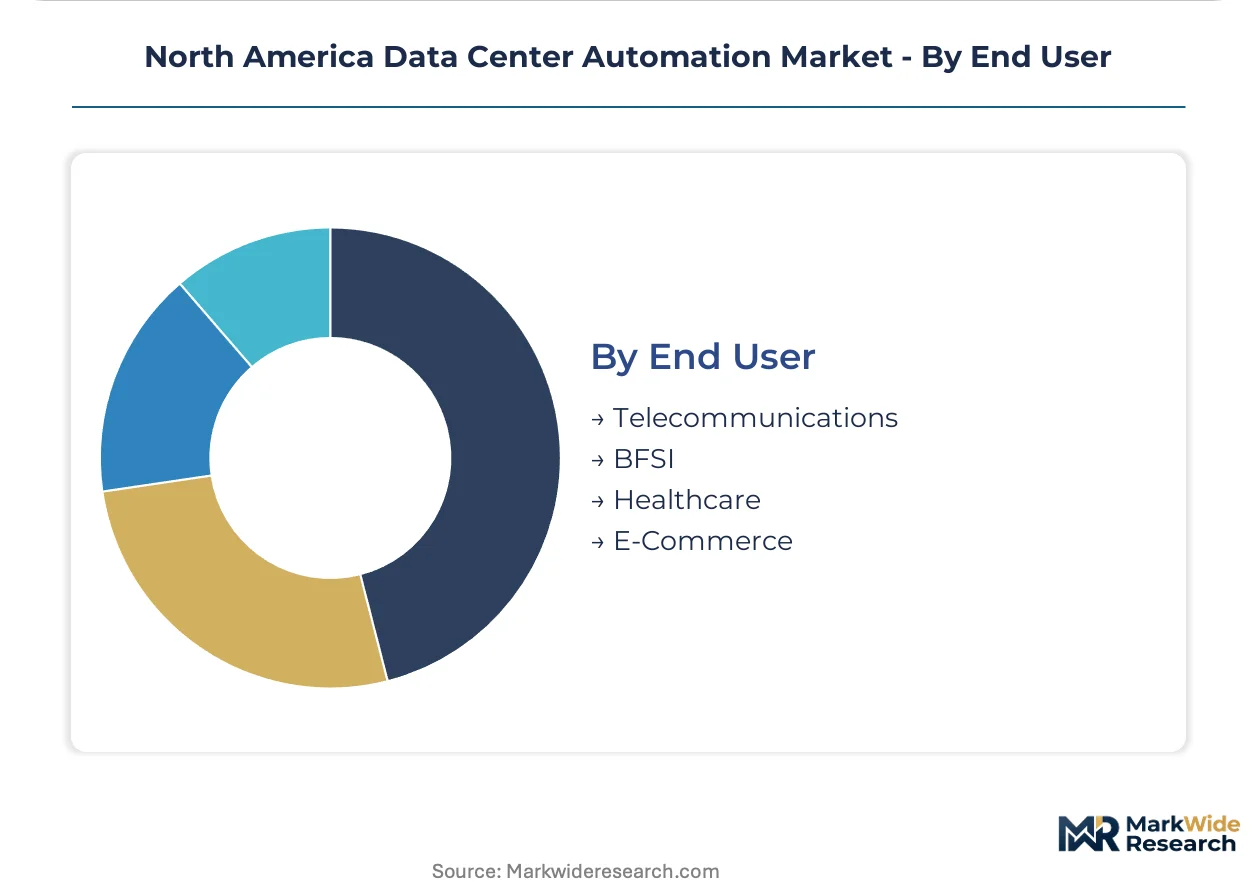
- Telecommunications:Edge computing automation for 5G infrastructure and distributed radio access network management. FCC spectrum allocation for CBRS and millimeter-wave bands enables automation nodes across the US Midwest for manufacturing and autonomous vehicle infrastructure. Latency-sensitive applications demand intent-based networking with autonomous failover capabilities.
- BFSI:Zero-touch provisioning for trading floor infrastructure and compliance-hardened multi-region disaster recovery. Chicago and Toronto financial services clusters drive spine-leaf topology adoption to replace legacy three-tier architectures. HIPAA and SEC cybersecurity mandates require encrypted telemetry with automated patch compliance documentation.
- Healthcare:Electronic health record system automation with strict access control and audit trail generation for HIPAA compliance.
- E-Commerce:Seasonal elasticity automation for fulfillment center compute and storage scaling during demand surges.
Telecommunications directs the largest procurement volume; Healthcare is climbing fastest as HIPAA enforcement tightens telemetry requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States data center automation vendors supply orchestration platforms to Canadian enterprise buyers and Mexican edge computing deployments, creating a north-south technology corridor anchored by hyperscale procurement clusters.
United States
Northern Virginia's Data Center Alley and Dallas-Fort Worth drive hyperscale demand for autonomous thermal management as power density exceeds 50kW per rack. EPA ENERGY STAR mandates now require automated carbon intensity reporting for facilities above 1MW capacity. Chicago financial services clusters deploy intent-based networking controllers to replace legacy three-tier architectures.
Canada
Toronto and Vancouver financial services sectors procure zero-touch provisioning systems for multi-region disaster recovery compliance. Health Canada cybersecurity guidance for critical infrastructure operators accelerates encrypted telemetry adoption. Montreal's AI research corridor demands GPU cluster automation that static rule engines cannot satisfy.
Mexico
Querétaro and Mexico City manufacturing zones deploy edge computing automation for automotive and electronics supply chain visibility. FCC-equivalent spectrum allocation for industrial IoT enables distributed automation nodes. Northern border states attract US hyperscale colocation investment requiring bilingual orchestration platform support.
North America Data Center Automation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated vendor base where three integrated platform families capture majority procurement volume. Microsoft Corporation, Cisco Systems Inc., and IBM Corporation anchor the top tier through hybrid cloud, silicon-to-software integration, and AIOps specializations respectively. Mid-tier challengers compete on vertical-specific compliance modules or regional service density. Dominant competitive moves include strategic partnerships with hyperscale operators and portfolio diversification into edge computing orchestration.
Within the infrastructure software tier, BMC Software Inc. and Broadcom occupy positions defined by mainframe-to-cloud bridge capabilities and virtualization ecosystem control. Microsoft Corporation exemplifies the cloud-native archetype through Azure Stack hybrid deployments. These three entities represent divergent strategic bets: mainframe legacy integration, virtualization licensing consolidation, and API-native multi-cloud orchestration.
| Leading Market Players |
|---|
| BMC Software, Inc. |
| Microsoft Corporation |
| IBM Corporation |
| Cisco Systems Inc. |
| Dell Inc. |
| Broadcom |
| Arista Networks, Inc. |
| Micro Focus |
| Fujitsu |
| Others |
Value Network & Pricing Analysis
Northern Virginia's Data Center Alley concentrates hyperscale procurement volume, compressing vendor margins for automation controllers while amplifying pricing power for specialized thermal management software. Utility interconnection queues extending 36-48 months create capacity scarcity that tilts contract terms toward facility operators.
Pricing Analysis
Next-generation AI-optimized orchestration platforms command 40-60% premiums over legacy rule-based systems, while prior-generation virtualization tools face commoditization. Three-tier pricing structure across premium, standard, and economy levels segments by deployment complexity and SLA guarantees. Cost compression in mid-tier network automation is intensifying because VMware ecosystem consolidation fragments multi-cloud roadmaps. Colocation providers in Northern Virginia exhibit lowest price sensitivity due to uptime guarantee requirements, while regional healthcare systems in Texas and California negotiate hardest on perpetual licensing terms.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing risk for programmable networking silicon and server management controllers. Hardware supply concentrates in Taiwan, South Korea, and Malaysia for advanced switching ASICs and edge computing gateways. Raw material dependencies span gallium nitride substrates, high-bandwidth memory modules, and precision cooling refrigerants. Single-source vulnerability persists for intent-based networking chipsets from merchant silicon vendors. Distribution runs through hyperscale-direct procurement channels and value-added reseller networks serving enterprise and mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as GPU cluster density requirements split procurement between cloud-native orchestration and legacy mainframe-to-cloud bridge implementations. NIST cybersecurity framework mandates create compliance-hardened niches for specialized vendors.
For Market Incumbents: Entrench platform position by deepening silicon-to-software integration investments that static rule engines cannot replicate. Broadcom's VMware licensing consolidation threatens multi-cloud orchestration revenue streams; defend by accelerating API-native controller development. Prioritize certification investment for EPA ENERGY STAR and state-level renewable portfolio standards to lock out unqualified challengers.
For New Entrants and Emerging Players: Mexico's northern border states attract US hyperscale colocation investment requiring bilingual orchestration platform support, creating white-space entry. Target edge computing automation for manufacturing and autonomous vehicle infrastructure in the US Midwest where FCC spectrum allocation enables distributed nodes. Lead with managed services wrappers around open-source controllers to bypass incumbent licensing complexity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AIOps-driven predictive maintenance specialists over commodity server provisioning vendors. Long-term viability rests on capabilities spanning thermal load balancing and encrypted telemetry compliance. Acquisition target archetype: vertical-specific compliance modules for HIPAA-hardened healthcare or SEC-regulated financial services. Watch hyperscale capital expenditure disclosures as inflection indicator for orchestration platform procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Silicon-to-software convergence collapses compute and facility management into unified policy engines. |
| Strategic Partnership | Hyperscale operator alliances in Northern Virginia secure reference architectures for spine-leaf migrations. |
| Geographic Expansion | Querétaro and Mexico City manufacturing zones demand edge automation for automotive supply chains. |
| Acquisition of Specialist Firm | Mainframe-to-cloud bridge capabilities address healthcare and BFSI legacy modernization requirements. |
| Product Launch | Digital twin simulations for EPA ENERGY STAR compliance scenario modeling open greenfield accounts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center facility directors, Site Reliability Engineering leads, hyperscale procurement officers, and automation platform vendors. Secondary validation drew from EPA ENERGY STAR certification databases, FCC spectrum allocation filings, NIST cybersecurity framework documentation, and hyperscaler capital expenditure disclosures. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against aggregate infrastructure spending anchored the analytical framework.
Calibration against historical procurement patterns and forward-looking capacity expansion announcements shaped projections across the analysis window. Segmentation dimensions modeled include application type, service delivery model, technology layer, deployment scale tier, and regional regulatory cluster. CAGRs were derived from slope analysis of adoption curves adjusted for infrastructure replacement cycles and compliance mandate effective dates. Forecast inputs incorporated utility interconnection queue durations and GPU cluster density trajectories.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments and hyperscale capital allocation priorities would shift the trajectory. Forecasts embed assumptions regarding NIST framework enforcement timelines and EPA mandate expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Smart Vending Machines Market
Automation
Self Bag Drop Machine Market
Automation
Asia-Pacific Data Center Automation Market
Automation
Europe Laboratory Automation Market
Automation
Retail Automation Market
Automation
Smart Home Automation Market
Automation
Dropshipping Automation Software Market
Automation
Voice Picking Solutions Market
Automation
Italy Process Orchestration Market
Automation
Elevator Control Market
Automation
Intelligent Remote Terminal Unit Market
Automation
RFID Kanban Systems Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Italy Marketing Automation Market
Automation
Distributed Control System Market
Automation
North America Marketing Automation Software Market