
 Global Professional Service Automation (PSA) Software Market | 2026-2036
Global Professional Service Automation (PSA) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Professional Service Automation (PSA) Software Market Outlook
Modular bundling of time tracking, resource management, and billing functions into configurable subscription tiers is expanding buyer choice across mid-market professional services firms. Deltek leverages deep vertical specialization in architecture, engineering, and construction workflows to sustain premium positioning. Kantata anchors its competitive stance through integrated project accounting and workforce planning capabilities. BigTime Software differentiates via mobile-first design and streamlined expense capture for distributed consulting teams.
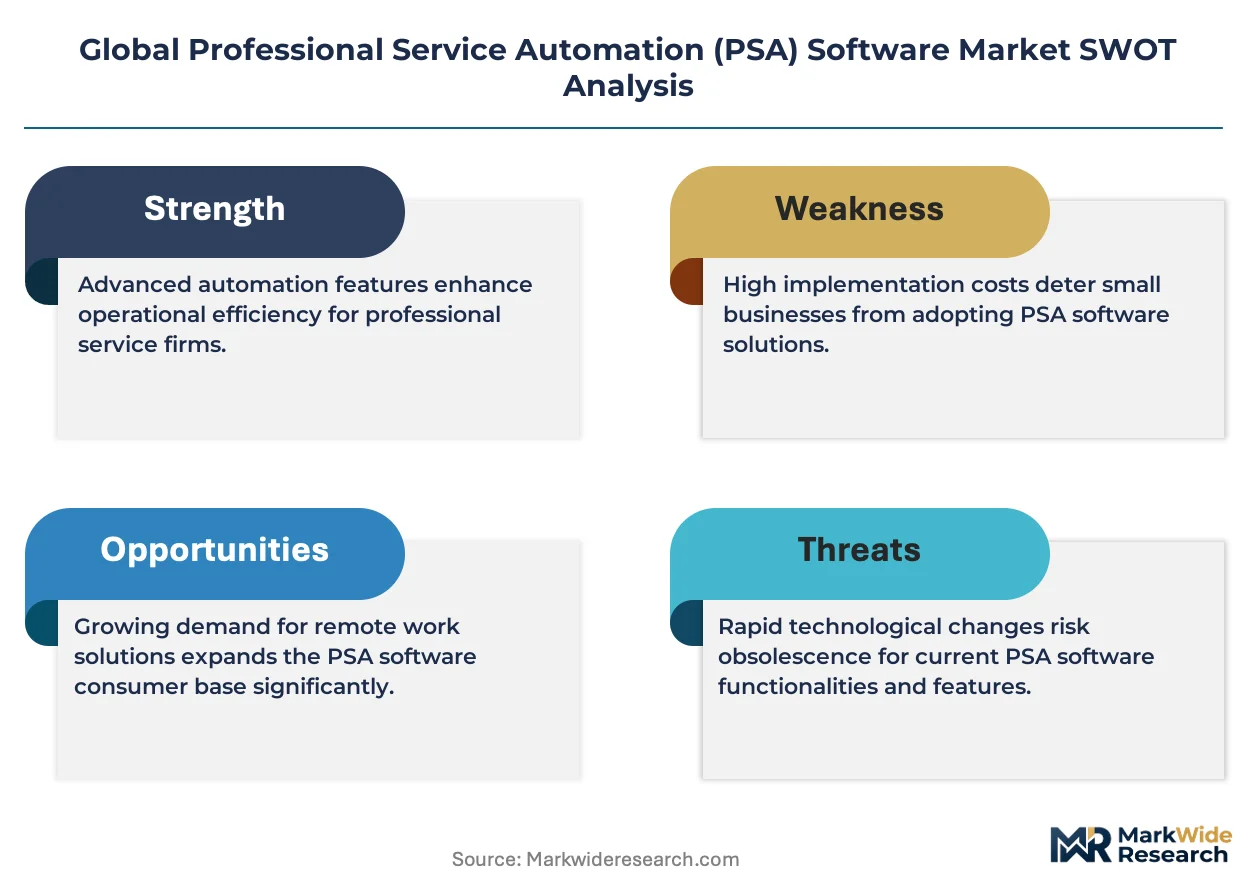
Professional Service Automation software comprises integrated platforms that orchestrate project lifecycle management, resource allocation, time capture, and revenue recognition for billable-services organizations. Core functional parameters include real-time utilization dashboards, multi-currency invoicing engines, and API connectivity with ERP and CRM systems, serving the commercial purpose of converting labor hours into accurate, auditable revenue streams. Public Cloud deployment leads segment traction due to lower capital barriers and automatic feature updates, while Resource Management services represent the fastest-growing service type as firms prioritize talent optimization over basic time entry. The Billing segment remains mature with stable margin pools, whereas Analytics solutions are capturing new margin as clients demand predictive insights on project profitability.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements on PSA platforms processing automated resource recommendations and client billing data. The SEC's cybersecurity disclosure rules for US-listed professional services firms are accelerating demand for audit-ready time and expense documentation. India's Digital Personal Data Protection Act is creating localization requirements that favor hybrid deployment architectures. Stakeholders must monitor how evolving AI governance frameworks reshape feature development roadmaps and cross-border data handling protocols.
Market Dynamics
Cloud-native architectures are displacing on-premise PSA deployments as professional services firms prioritize elastic capacity and zero-downtime updates over capital-intensive infrastructure ownership. The EU AI Act's algorithmic transparency mandates are forcing vendors to re-engineer automated resource recommendation engines, while India's Digital Personal Data Protection Act is fragmenting data residency requirements across hybrid deployment models.
Growth Catalysts
- EU AI Act compliance mandates:Professional services firms in Germany and France must deploy auditable decision trails for automated billing algorithms, creating replacement demand for legacy PSA platforms lacking explainable AI modules.
- SEC cybersecurity disclosure rules:US-listed consulting firms now require immutable time-and-expense documentation chains, accelerating cloud PSA adoption for audit-ready data lineage.
- India's Digital Personal Data Protection Act:Localization requirements for client billing data are driving hybrid cloud architectures that split processing between Mumbai data centers and edge nodes.
Market Restraints
- GDPR data residency friction:Cross-border project teams face operational delays when PSA platforms cannot guarantee EU-only data processing for automated workforce scheduling.
- API integration complexity:Legacy ERP systems in established professional services firms require expensive middleware development to synchronize real-time utilization dashboards with existing financial ledgers.
- Substitution by vertical SaaS:Specialized architecture and engineering firms are bypassing generic PSA suites for industry-specific project accounting tools with embedded resource management.
Strategic Opportunities
- Underpenetrated mid-market legal sector:Law firms with 50-200 attorneys in the United States remain underserved by configurable PSA platforms that can accommodate contingent fee arrangements alongside hourly billing.
- Convergence of PSA and ESG reporting:The EU Corporate Sustainability Reporting Directive is creating demand for carbon-aware resource allocation algorithms that track project-level emissions alongside profitability metrics.
- Embedded finance integration:PSA platforms that embed working capital financing for project-based cash flow gaps can capture margin from lending relationships currently held by traditional banks.
Industry Challenges
- AI/ML engineering talent scarcity:Vendors struggle to hire data scientists capable of building predictive profitability models that satisfy both performance requirements and EU algorithmic transparency standards.
- Multi-tenant security architecture:Cloud PSA providers face escalating capex demands for isolated encryption environments that prevent cross-tenant data leakage in shared infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Professional Service Automation (PSA) Software Market |
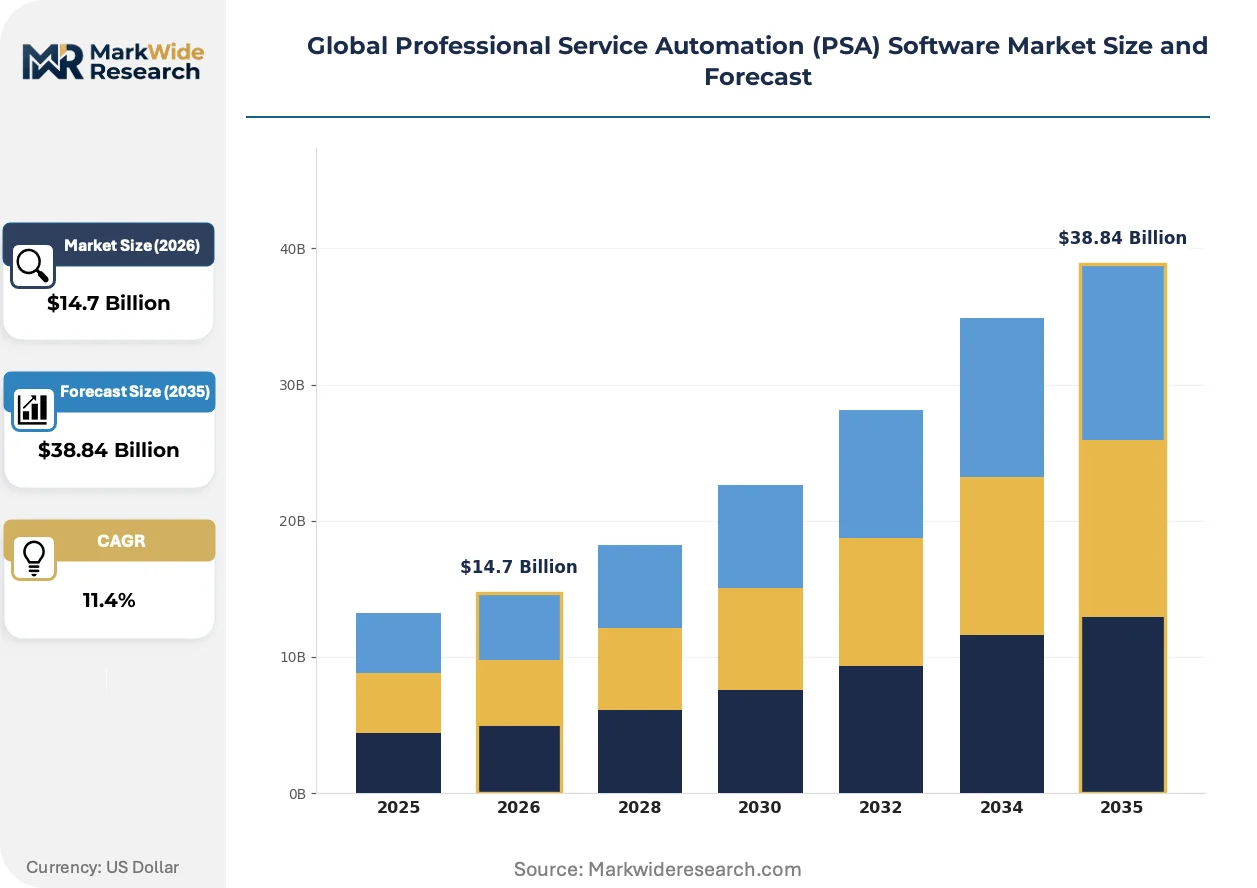
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Consulting, Project Management, Resource Management, Billing End User: IT Firms, Marketing Agencies, Financial Services, Professional Services Solution: Time Tracking, Invoicing, Reporting, Analytics |
| Companies Covered | Autotask Corporation, Kantata, Certinia, Deltek, ConnectWise, BigTime Software, Accelo, Clarizen, Cloud Coach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Professional Service Automation (PSA) Software Market Strategic Shifts
Generative AI is rewriting core PSA workflows, from automated project scoping to natural-language time entry, while regulatory pressure on algorithmic accountability is reshaping vendor roadmaps. Deployment models are fragmenting as data sovereignty requirements harden across jurisdictions.
Agentic AI systems are expanding into routine PSA functions through autonomous task decomposition. Mid-market consulting firms in the United States are piloting these tools for automated project status reporting and resource conflict resolution. This capability compression is threatening traditional PSA implementation services by reducing configuration complexity.
The EU AI Act's risk-based classification system is forcing vendors to redesign automated decision modules. High-risk applications including predictive billing optimization now require human-in-the-loop validation and technical documentation. German engineering consultancies are demanding these compliance features as standard, not premium, functionality.
Subscription fatigue among professional services buyers is shortening PSA evaluation cycles and compressing pilot-to-production timelines. Procurement teams now expect configurable trial environments with pre-loaded industry templates. This behavioral shift is most visible in India's IT services sector, where vendor switching costs have collapsed due to standardized API schemas.
Global Professional Service Automation (PSA) Software Market Segmentation
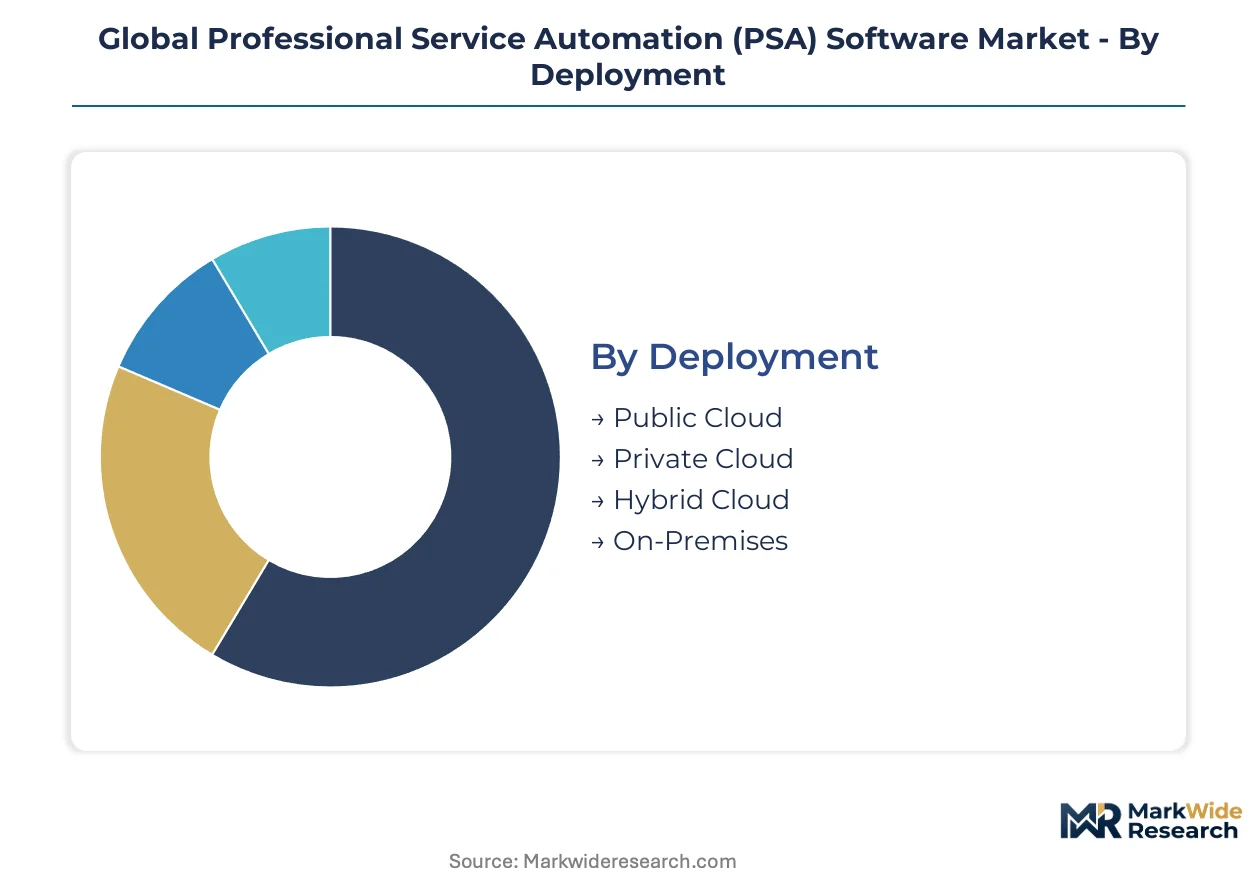
Professional Service Automation software segments reflect divergent buyer priorities across infrastructure control, functional depth, and industry verticals. Deployment architecture and service type configurations determine implementation complexity and recurring revenue durability for vendors.
Deployment:
The customization-standardization spectrum spans fully managed SaaS to self-hosted environments requiring dedicated IT resources.
- Public Cloud:Multi-tenant SaaS delivery with automatic feature updates and elastic scaling. Demand concentrates among mid-market IT firms in India seeking zero-capex onboarding and rapid deployment cycles without infrastructure ownership.
- Private Cloud:Single-tenant cloud infrastructure with dedicated resource isolation. German engineering consultancies under EU AI Act mandates favor this model for auditable data processing and algorithmic transparency compliance.
- Hybrid Cloud:Split architecture with sensitive billing data on-premises and analytics workloads in cloud. India's Digital Personal Data Protection Act drives adoption as firms localize client data while retaining cloud agility.
- On-Premises:Self-hosted deployment with full infrastructure control. Legacy financial services institutions in the United States maintain this model for SEC cybersecurity disclosure compliance and immutable audit trails.
Leading the category by volume: Public Cloud. Expanding most quickly: Hybrid Cloud.
Service Type:
Service tiers map to operational maturity, from advisory implementation through automated core workflows.
- Consulting:Advisory services for PSA configuration, change management, and workflow optimization. United States-based IT consulting firms with complex ERP integration requirements drive premium engagement volumes.
- Project Management:Core planning, scheduling, and milestone tracking functionality. Marketing agencies in Germany adopt these modules for EU Green Deal-aligned project carbon accounting and client reporting.
- Resource Management:Workforce allocation, skills matching, and utilization optimization. This segment captures the steepest expansion trajectory as talent scarcity pressures professional services firms toward predictive staffing algorithms.
- Billing:Time capture, invoicing, and revenue recognition engines. Mature demand from legal and accounting firms in the United States sustains stable margin pools despite slower feature innovation.
Highest revenue concentration: Billing. Gaining share fastest: Resource Management.
End User:
Vertical specialization requirements fragment buyer needs across regulatory exposure and project complexity.
- IT Firms:Software development and systems integration consultancies with distributed delivery models. India's IT services sector demonstrates shortest evaluation cycles due to standardized API schemas and subscription fatigue.
- Marketing Agencies:Creative and digital marketing services with project-based staffing. These buyers prioritize mobile-first time capture and streamlined expense workflows for distributed creative teams.
- Financial Services:Audit, tax, and advisory practices with strict compliance requirements. SEC disclosure rules and immutable documentation mandates accelerate cloud PSA adoption among US-listed firms.
- Professional Services:Legal, accounting, and general consulting practices with complex billing arrangements. Mid-market law firms with 50-200 attorneys remain underpenetrated due to contingent fee configuration complexity.
Deepest vertical integration: Financial Services. Fastest digitization pace: IT Firms.
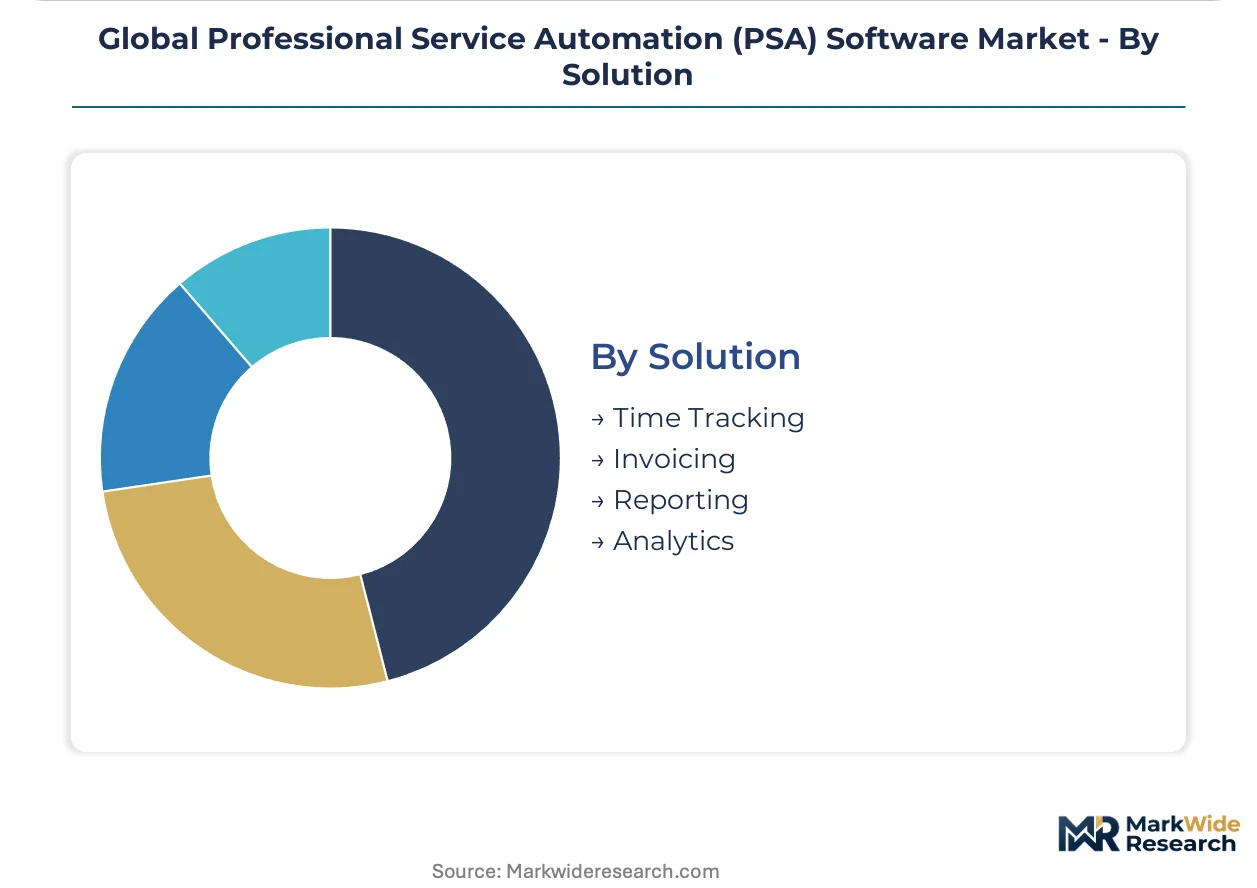
Solution:
Functional modules range from operational data capture to predictive intelligence layers.
- Time Tracking:Labor hour capture through desktop, mobile, and automated activity monitoring. Consulting teams across Germany demand EU AI Act-compliant audit trails for automated time entry validation.
- Invoicing:Multi-currency billing engines with tax calculation and payment processing. Mature functionality with stable demand across all professional services verticals.
- Reporting:Standardized dashboards for project status, utilization, and financial performance. Marketing agencies leverage these tools for client-facing progress documentation.
- Analytics:Predictive models for profitability forecasting and resource optimization. This segment climbs fastest as firms demand project-level emissions tracking alongside financial metrics under EU Corporate Sustainability Reporting Directive.
Widest installed base: Invoicing. Steepest feature investment: Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bangalore and Hyderabad concentrate Indian IT services procurement, while Germany's Industrie 4.0 clusters drive compliance-heavy PSA adoption. United States federal contracting requirements and SEC disclosure mandates accelerate cloud migration among consulting firms.
United States
SEC cybersecurity disclosure rules and immutable audit trail requirements drive cloud PSA adoption among federal contractors and publicly listed consulting firms. The Sarbanes-Oxley framework reinforces documentation standards for billable hour tracking. Washington D.C. and Northern Virginia clusters host defense and government services firms deploying compliance-ready platforms.
Germany
EU AI Act algorithmic transparency mandates and Industrie 4.0 digitization initiatives reshape engineering consultancy procurement. The country's national data protection authority enforces strict GDPR compliance for cross-border project teams. Munich and Stuttgart industrial clusters demand auditable resource allocation systems with human-in-the-loop validation.
India
Digital Personal Data Protection Act localization requirements and IT services export growth accelerate hybrid cloud PSA deployment. Software Technology Parks of India tax incentives concentrate vendor development in Bangalore and Hyderabad. Mumbai financial services firms split billing data between local data centers and cloud analytics workloads.
United Kingdom
Financial Conduct Authority operational resilience requirements and post-Brexit data adequacy negotiations complicate cross-border PSA implementations. London's professional services density sustains demand for multi-currency invoicing and international project accounting. The city's fintech corridor pilots embedded finance integrations within PSA workflows.
Japan
METI's Society 5.0 initiative and labor shortage pressures drive predictive resource management adoption among consulting and IT services firms. The country's personal information protection commission mandates strict data handling protocols for automated workforce scheduling. Tokyo and Osaka metropolitan areas concentrate mid-market firm digitization efforts.
Global Professional Service Automation (PSA) Software Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across deployment architectures and vertical specializations. The vendor base organizes into three strategic tiers: ERP-integrated suite providers, standalone cloud-native platforms, and industry-specific workflow tools. Consolidation pressures intensify as mid-market buyers demand pre-configured templates reducing implementation timelines. Dominant competitive moves include vertical specialization through targeted acquisitions and API ecosystem expansion deepening ERP connectivity.
Among North American platform providers, Deltek and BigTime Software occupy distinct positioning archetypes. Deltek anchors the vertical-specialist tier through deep workflow integration in project-based industries. BigTime Software exemplifies mobile-first design philosophy targeting distributed professional services teams. Kantata represents the integrated-project-accounting archetype combining workforce planning with financial operations. These three firms illustrate how specialization vectors—vertical depth, user experience, and functional breadth—define competitive differentiation without direct feature parity.
| Leading Market Players |
|---|
| Autotask Corporation |
| Kantata |
| Certinia |
| Deltek |
| ConnectWise |
| BigTime Software |
| Accelo |
| Clarizen |
| Cloud Coach |
| Others |
Value Chain & Pricing Dynamics
Mid-market IT consulting firms in India and Germany concentrate procurement volumes, anchoring subscription-based SaaS pricing with tiered feature access calibrated to employee headcount and integration complexity.
Pricing Analysis
Short lead-time deployments command premium positioning as Indian IT services buyers demand zero-capex onboarding within 48-hour windows. Three-tier pricing structure across premium, standard, and economy levels segments by API integration depth, vertical template availability, and dedicated support tiers. Cost compression in the economy tier intensifies because hyperscaler infrastructure commoditizes base compute resources. Marketing agencies exhibit highest price sensitivity due to project-based cash flow volatility, while financial services firms accept premium positioning for SEC-compliant audit trails.
Supply Chain Analysis
Workforce availability constraints in Bangalore and Hyderabad development centers tether platform engineering capacity to regional talent pipelines. Cloud infrastructure sourcing draws from hyperscaler data centers in the United States, Ireland, and Singapore, with API middleware components originating from specialized integration shops in Germany and the United Kingdom. Single-source vulnerability concentrates in proprietary machine-learning frameworks licensed from concentrated AI research labs. Distribution runs through direct vendor sales teams and hyperscaler marketplace channels serving mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU AI Act compliance mandates is forcing subscale vendors lacking explainable AI engineering depth toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through backward integration into proprietary data residency architectures that satisfy India's Digital Personal Data Protection Act localization requirements. Acquire mid-market legal-sector specialists with contingent-fee billing configurations to block new entrant white-space penetration. Vertical specialization in architecture-engineering-construction workflows sustains premium pricing power against generic platform substitution. For New Entrants and Emerging Players: Begin with embedded finance integration for project-based working capital gaps, targeting mid-market US law firms with 50-200 attorneys where contingent-fee configuration complexity has suppressed incumbent penetration. Carbon-aware resource allocation algorithms aligned with EU Corporate Sustainability Reporting Directive reporting requirements offer differentiated entry positioning against established workforce planning modules. For Investors and Strategic Acquirers: The window for entry favors vertical-specialist PSA platforms with pre-configured industry templates and compliance-ready audit trails. Long-term viability hinges on algorithmic transparency engineering capabilities that satisfy evolving EU AI Act risk classifications. Watch for SEC cybersecurity disclosure rule expansion to private professional services firms as inflection signal accelerating audit-ready platform replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Acquisition of Legal-Sector Specialist | Captures underpenetrated mid-market law firms with contingent-fee billing complexity. |
| Hybrid Cloud Architecture Development | Addresses India's Digital Personal Data Protection Act localization mandates for Mumbai financial services clients. |
| Explainable AI Module Integration | Satisfies EU AI Act algorithmic transparency requirements for German engineering consultancy procurement. |
| Embedded Finance Partnership | Captures working capital lending margin currently held by traditional banking relationships. |
| Carbon-Aware Resource Allocation Algorithm | Aligns project profitability tracking with EU Corporate Sustainability Reporting Directive emissions reporting. |
Study Parameters
Document review covered SEC cybersecurity disclosure filings, EU AI Act technical documentation, and hyperscaler infrastructure capex reports, complemented by interviews with PSA platform CTOs, IT procurement officers at mid-market consulting firms, integration specialists, and channel partners. Secondary validation drew from vendor SEC 10-K disclosures, EU regulatory implementation guidance, and Indian Digital Personal Data Protection Act compliance frameworks. Bottom-up deployment model sizing and top-down vertical spending pattern analysis enabled triangulation.
Historical adoption curves were cross-referenced against executive panel input on procurement cycle compression and pilot-to-production timeline acceleration. Segmentation modeling spanned deployment architecture, service type maturity, end-user vertical regulatory exposure, and solution functional depth across the projection horizon. CAGRs were derived from elasticity-adjusted pricing trajectory assumptions and workforce optimization demand intensity indicators.
Underlying measurement precision varies by segment; public cloud deployment and billing solution estimates carry tighter precision than emerging analytics and agentic AI capability forecasts. Projections rest on assumptions regarding EU AI Act enforcement consistency, SEC disclosure rule scope expansion, and hyperscaler infrastructure pricing stability. Material deviation in regulatory implementation timelines or cross-border data flow restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Newsroom Software Market
Software & Services
Application Lifecycle Management (ALM) Market
Software & Services
Global Recruiting Software Market
Software & Services
Global Political Campaign Software Market
Software & Services
Global Architect Software Market
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
North America IT Services Market
Software & Services
APAC Interior Design Software Market
Software & Services
Live Software Market
Software & Services
Global App Design Software Market
Software & Services
Global Software Resellers Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Appointment Scheduling Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Self-Storage Software Market
Software & Services
Global App Builder Software Market