
 Laboratory Benchtop Automation Market | 2026-2036
Laboratory Benchtop Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Benchtop Automation Market Outlook
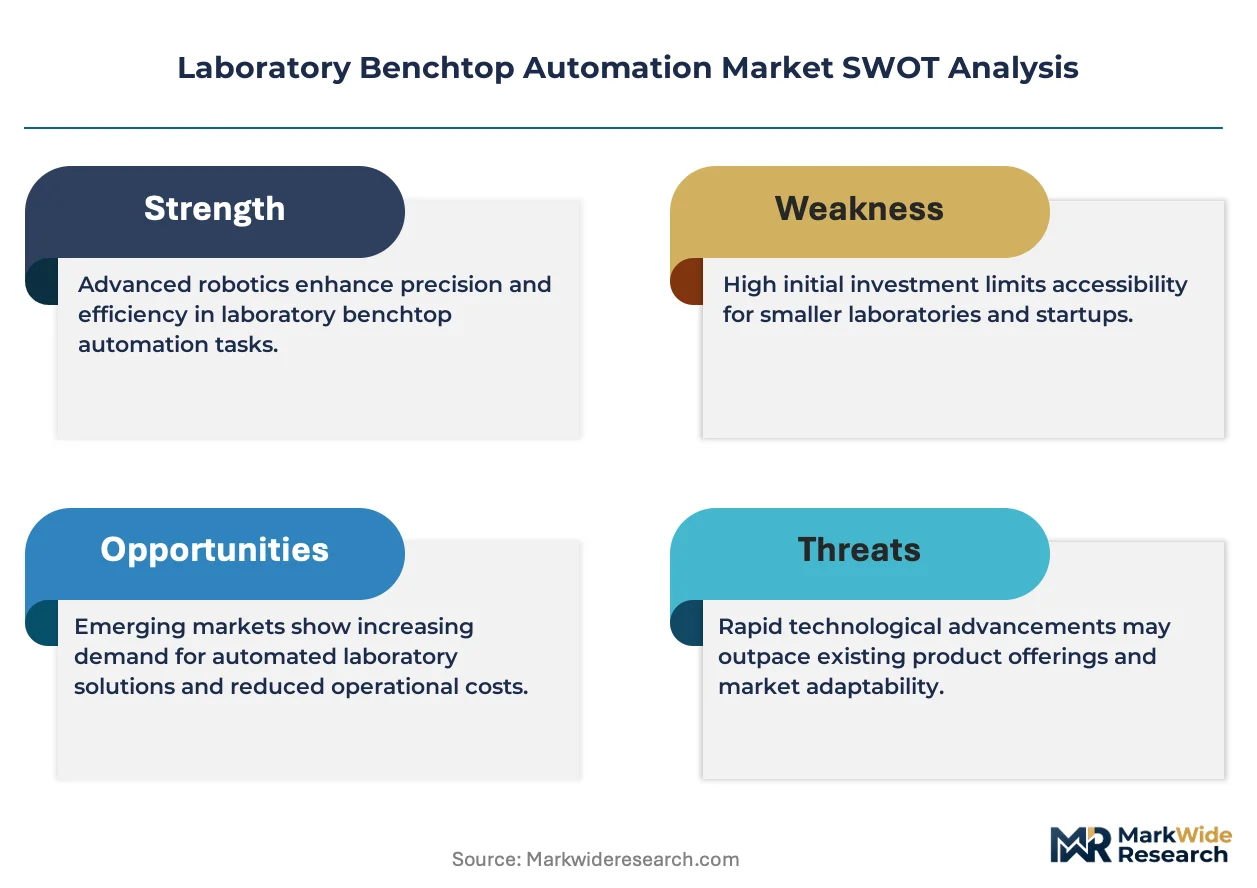
Leasing and subscription-based financing is narrowing the competitive field for laboratory benchtop automation. Danaher Corporation leverages its Life Sciences segment breadth to bundle instrumentation with consumables and service contracts. Thermo Fisher Scientific anchors its position through direct sales infrastructure and applied biosystems integration. Tecan Group Ltd. specializes in liquid handling precision, competing on modularity for mid-sized research laboratories.
Laboratory benchtop automation encompasses compact, self-contained robotic systems designed for specimen processing, liquid transfer, and analytical preparation within limited physical footprints, typically operating on surfaces under two meters in length with precision tolerances measured in microliters. These systems integrate electromechanical actuators, optical sensors, and control software to execute repetitive protocols in drug discovery, genomics, and clinical diagnostics without full walk-away infrastructure. Liquid handling systems dominate installed base volumes due to universal demand across PCR, ELISA, and next-generation sequencing prep workflows, while artificial intelligence-enabled platforms represent the fastest-expanding margin pool as laboratories seek predictive maintenance and autonomous protocol optimization. Software integration sits at the mature center of technology adoption, with most buyers now requiring LIMS connectivity and cloud-based data export as baseline specifications rather than premium features.
The FDA enforces 21 CFR Part 11 compliance for electronic records in pharmaceutical and clinical laboratories, directly shaping software architecture requirements and validation documentation burdens for system vendors. ISO 13485 quality management standards and the EU In Vitro Diagnostic Regulation create parallel certification pathways that filter market access for non-compliant manufacturers. Stakeholders must monitor evolving AI validation frameworks from the FDA and EMA as autonomous decision-making capabilities expand beyond simple scheduling into real-time sample quality assessment and protocol adaptation.
Market Dynamics
Pharmaceutical laboratories face mounting pressure to validate electronic records under 21 CFR Part 11 while compressing assay turnaround times, forcing vendors to embed compliance-ready software architectures as standard rather than premium features.
Growth Catalysts
- High-throughput screening workflows:Drug discovery pipelines at contract research organizations require parallel processing of thousands of compounds daily, driving replacement of manual pipetting with precision liquid handling systems.
- FDA 21 CFR Part 11 enforcement:Electronic records mandates in pharmaceutical quality control laboratories eliminate paper-based systems and accelerate validated platform procurement cycles.
- Genomics sample prep automation:Next-generation sequencing workflows demand standardized library preparation, creating sustained replacement demand for aging manual protocols.
Market Restraints
- Pneumatic component supply concentration:Precision valves and linear actuators for sub-microliter dispensing originate from specialized German and Japanese suppliers, exposing lead time volatility.
- EU In Vitro Diagnostic Regulation certification burden:Extended clinical validation timelines for diagnostic-classified benchtop systems delay revenue recognition for manufacturers targeting European clinical laboratories.
- Manual protocol substitution:Low-complexity assays in resource-constrained settings retain human technicians due to minimal capital requirements and flexible workflow adaptation.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO-registered production facilities under the PLI scheme require quality control automation to meet export compliance standards for regulated markets.
- AI-enabled predictive maintenance:Convergence of machine learning algorithms with sensor telemetry allows autonomous calibration scheduling and consumable replenishment before failure.
- Subscription financing penetration:Leasing models reduce capital barriers for mid-sized academic laboratories previously excluded from automated platform acquisition.
Industry Challenges
- Mechatronics engineering scarcity:Cross-functional expertise spanning fluid dynamics, embedded firmware, and ISO 13485 quality systems commands premium compensation and extends hiring timelines.
- LIMS integration complexity:Legacy laboratory information management systems at academic medical centers require custom middleware development for seamless data exchange.
- Multi-site protocol standardization:Distributed pharmaceutical R&D networks struggle to maintain assay reproducibility across heterogeneous instrument vintages and software revisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Benchtop Automation Market |
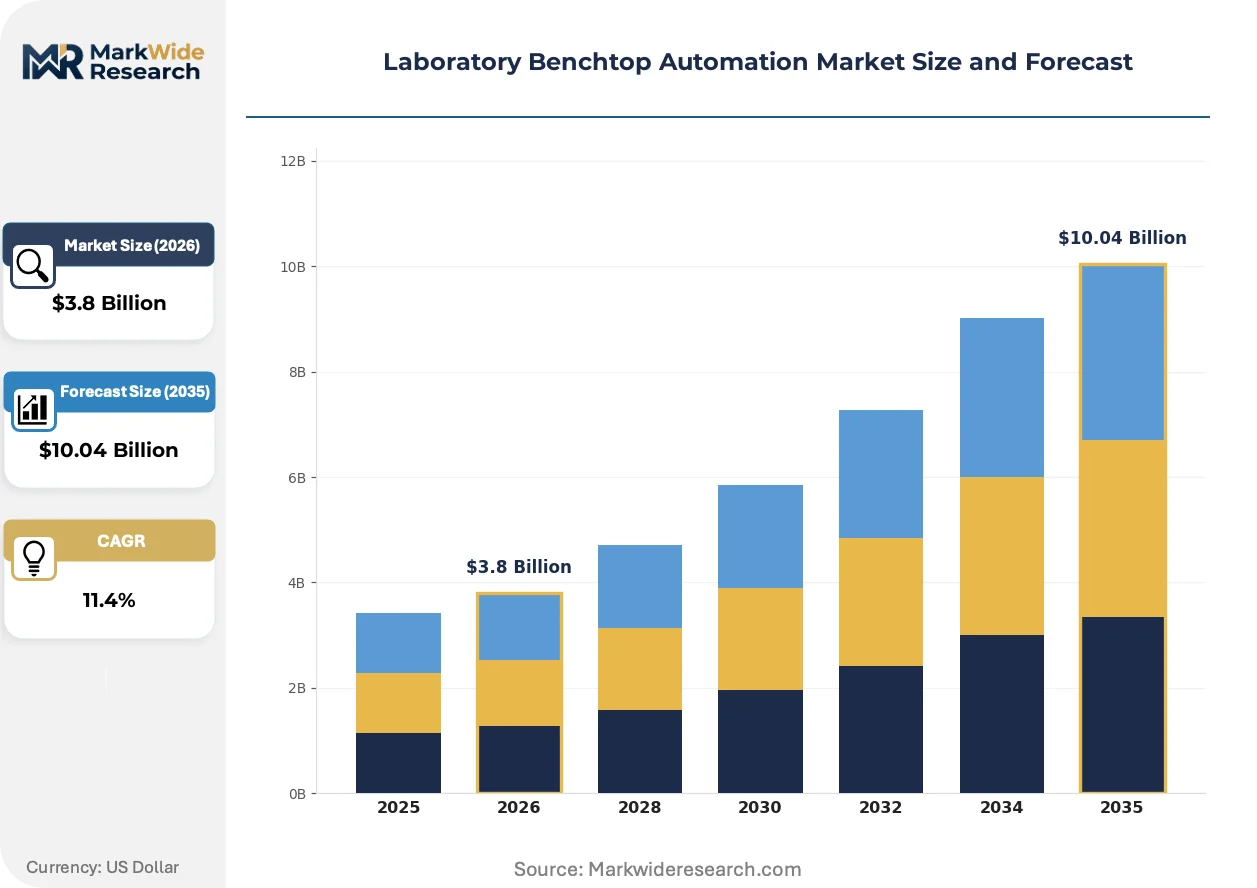
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Handling, Plate := Readers, Automated Pipetting, Sample Storage End User: Research Laboratories, Quality Control, Clinical Laboratories, Pharmaceutical Companies Technology: Robotics, Software Integration, Artificial Intelligence, Microfluidics Application: Drug Discovery, Genetic Testing, Clinical Diagnostics, Environmental Testing |
| Companies Covered | Agilent Technologies, Inc., Thermo Fisher Scientific, Inc., Danaher Corporation, PerkinElmer, Inc., QIAGEN GmbH, Tecan Group Ltd., Hamilton Company, F. Hoffmann-La Roche AG, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Benchtop Automation Market Strategic Shifts
Artificial intelligence capabilities are migrating from scheduling optimization into real-time sample quality assessment, compressing the boundary between automation and autonomous decision-making in analytical preparation workflows.
Acoustic liquid handling technology eliminates physical contact between pipette tips and samples, reducing consumable costs and cross-contamination risk in high-value biologic assays. Large-molecule drug developers at contract manufacturing organizations are adopting these systems for formulation screening. Traditional positive-displacement pipetting is rendering obsolete for applications requiring nanoliter precision with minimal sample loss.
The FDA and EMA are developing parallel validation frameworks for AI-enabled analytical systems that adapt protocols based on real-time sample characteristics. These draft guidance documents will impose algorithm transparency requirements and locked-model documentation burdens on vendors. Clinical diagnostic laboratories in the United States and Germany are pre-positioning quality management systems to accommodate anticipated pre-market review pathways.
Service unbundling is separating hardware warranties from software maintenance and application support contracts, allowing buyers to optimize lifecycle costs based on internal technical capabilities. Academic core facilities with embedded engineering staff are declining comprehensive service packages in favor of remote diagnostics-only tiers. This pattern is most pronounced in Boston and San Diego biotech clusters where talent density supports self-sufficient operations.
Laboratory Benchtop Automation Market Segmentation
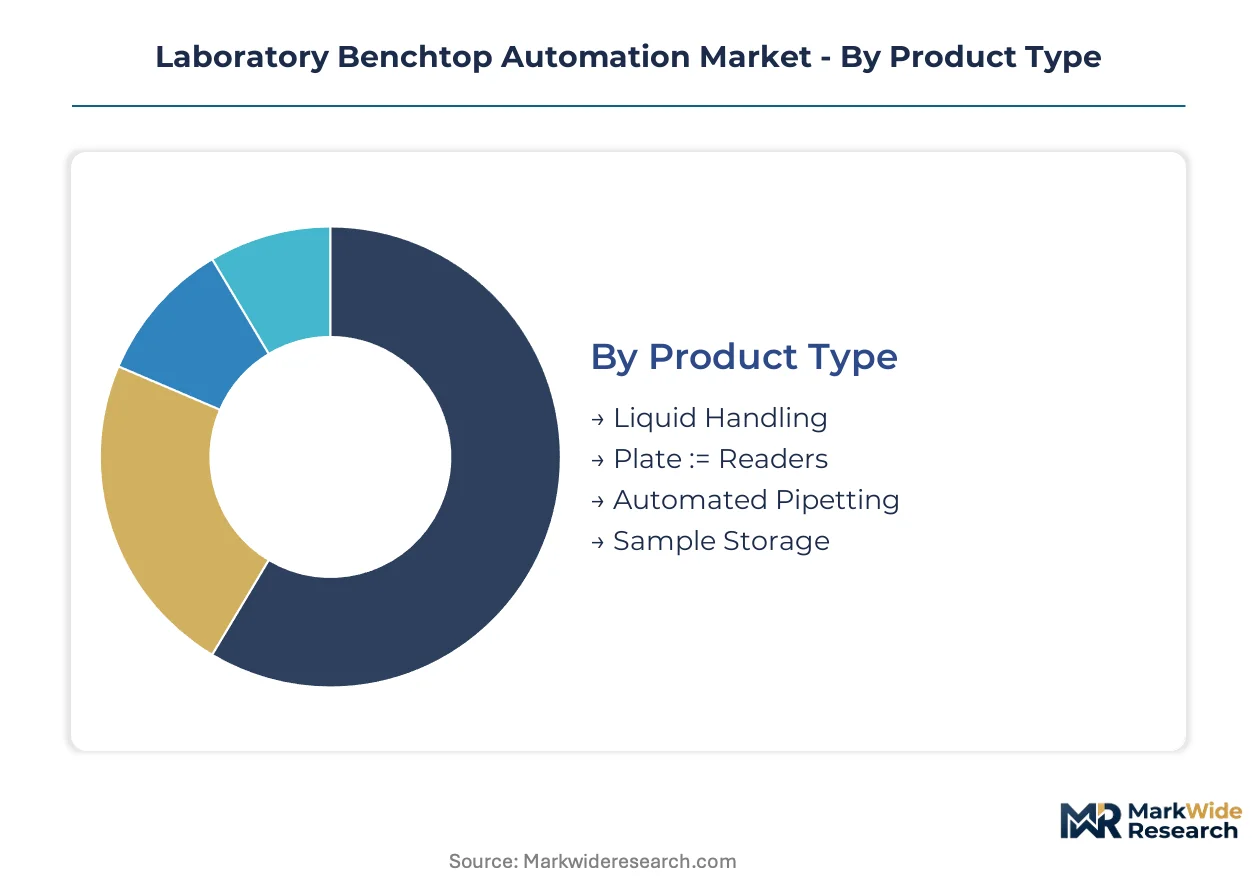
Benchtop automation procurement decisions fragment across four distinct axes. Product type determines capital intensity and consumable attach rates. End-user category shapes compliance requirements and service contract structures. Technology tier separates legacy replacement cycles from greenfield AI deployments. Application focus dictates throughput specifications and validation documentation burdens.
Product Type:
After-sales service intensity varies dramatically across hardware categories, with liquid handling systems demanding quarterly calibration contracts while sample storage units require minimal field intervention.
- Liquid Handling:Electromechanical systems with sub-microliter precision tolerances dominate installed base volumes. Pharmaceutical quality control laboratories in the United States drive replacement demand as FDA 21 CFR Part 11 enforcement eliminates manual pipetting workflows.
- Automated Pipetting:Compact single-channel and multi-channel dispensers address lower-throughput environments. Academic core facilities prioritize these systems for flexible protocol adaptation without full workflow reconfiguration.
- Plate Readers:Absorbance, luminescence, and fluorescence detection modules integrate with upstream liquid handlers. High-content screening applications at contract research organizations sustain premium pricing for multimodal configurations.
- Sample Storage:Automated tube handling and barcode tracking systems preserve specimen integrity across temperature gradients. Biobank expansion in Germany and Japan generates demand for modular capacity expansion.
Liquid handling holds the largest share; momentum sits with automated pipetting as mid-sized laboratories seek entry-level automation.
End User:
Cost tier segmentation separates capital-rich pharmaceutical buyers from budget-constrained academic institutions, with quality control laboratories occupying the highest per-site spending band due to regulatory validation requirements.
- Pharmaceutical Companies:Integrated drug discovery and quality control operations demand enterprise-scale platform standardization. CDSCO-registered manufacturing facilities in India under the PLI scheme are modernizing quality control infrastructure to meet export compliance standards.
- Research Laboratories:Academic medical centers and core facilities prioritize modularity over throughput. Boston and San Diego biotech clusters exhibit self-sufficient engineering capabilities that reduce reliance on comprehensive vendor service contracts.
- Clinical Laboratories:Diagnostic-classified systems face extended EU In Vitro Diagnostic Regulation certification timelines. German and French clinical networks are pre-positioning quality management systems for anticipated AI validation frameworks from EMA.
- Quality Control:Pharmaceutical manufacturing release testing requires locked software versions and audit trail documentation. FDA enforcement of electronic records mandates accelerates procurement cycles for validated platforms.
Pharmaceutical companies command the highest per-site revenue; clinical laboratories are expanding most quickly as diagnostic automation penetrates hospital networks.
Technology:
Volume concentration skews toward mature robotics and software integration, while AI-enabled platforms capture disproportionate margin expansion through predictive maintenance and autonomous protocol optimization.
- Robotics:Cartesian and SCARA kinematic systems with electromechanical actuators constitute the installed base majority. Pneumatic component supply concentration in German and Japanese specialist vendors exposes lead time volatility for precision valve assemblies.
- Software Integration:LIMS connectivity and cloud-based data export have shifted from premium features to baseline procurement requirements. Legacy system middleware development at academic medical centers extends implementation timelines.
- Artificial Intelligence:Machine learning algorithms converging with sensor telemetry enable autonomous calibration scheduling. FDA and EMA draft guidance on algorithm transparency and locked-model documentation is reshaping vendor development roadmaps.
- Microfluidics:Lab-on-chip architectures reduce reagent consumption for high-value biologic assays. Acoustic liquid handling technology eliminates physical tip contact, rendering traditional positive-displacement pipetting obsolete for nanoliter precision applications.
Robotics maintains dominant volume; artificial intelligence is climbing the fastest as laboratories seek predictive maintenance capabilities.
Application:
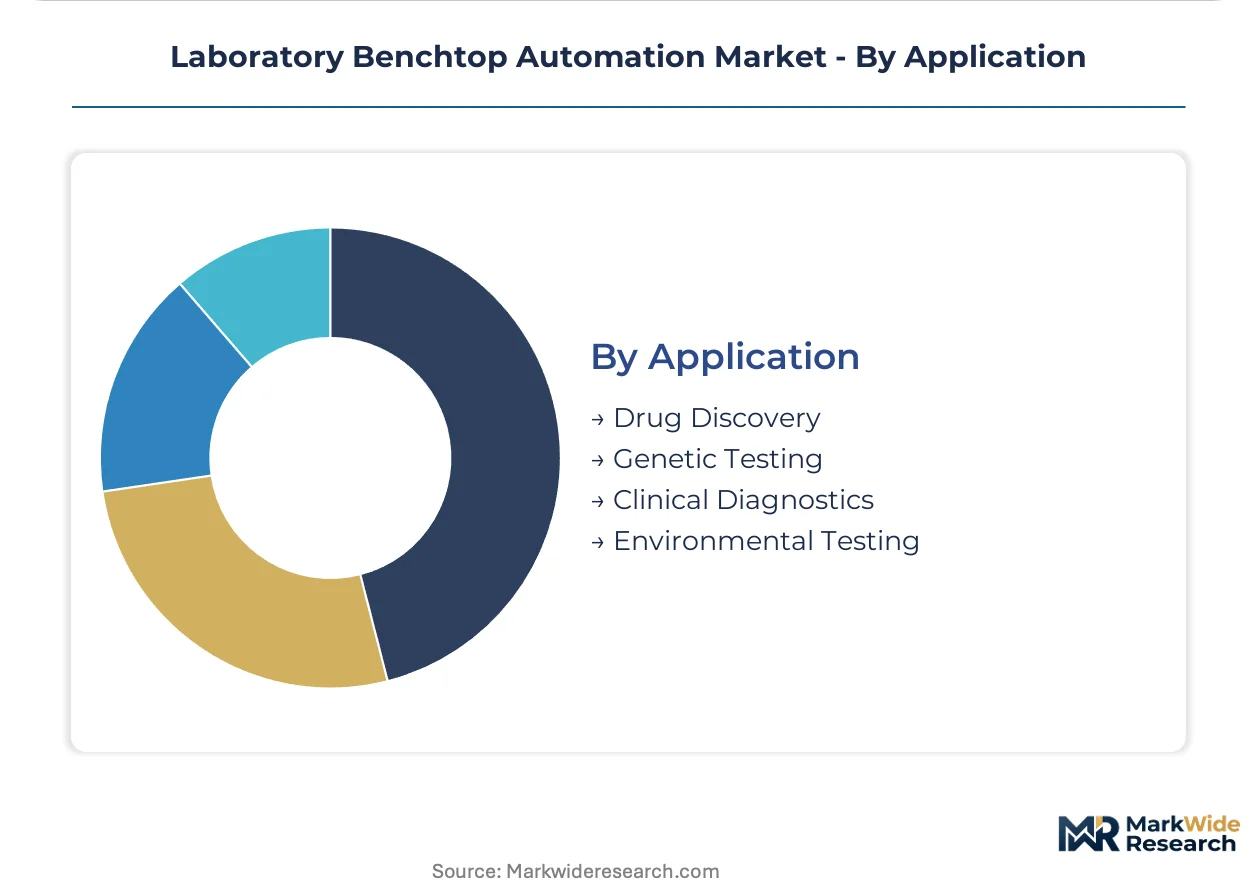
Maturity gradients separate established drug discovery automation from emerging environmental testing deployments, with genetic testing occupying the steepest technology refresh cycle.
- Drug Discovery:High-throughput screening workflows at contract research organizations process thousands of compounds daily. Parallel liquid handling demand sustains replacement cycles for aging manual protocols.
- Genetic Testing:Next-generation sequencing library preparation standardization drives sustained platform investment. Clinical diagnostic laboratories in the United States face CMS reimbursement pressure to compress turnaround times.
- Clinical Diagnostics:Automated ELISA and immunoassay processing reduces technician variability. EU In Vitro Diagnostic Regulation certification burdens delay European revenue recognition for diagnostic-classified system vendors.
- Environmental Testing:Water quality and soil contamination monitoring applications remain underpenetrated. Regulatory enforcement variance across jurisdictions fragments standardization efforts.
Drug discovery captures the largest revenue pool; genetic testing is gaining share fastest as clinical sequencing expands beyond research applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented pharmaceutical manufacturing in India and Germany generates inbound demand for validated benchtop systems, while the United States remains the dominant import market for precision instrumentation. Trade flows concentrate laboratory automation procurement in regulatory-aligned jurisdictions with established quality infrastructure.
United States
FDA 21 CFR Part 11 enforcement drives replacement cycles at pharmaceutical quality control laboratories and academic medical centers. The agency's electronic records mandates eliminate manual workflows and accelerate procurement of validated software-integrated platforms. Boston and San Diego biotech clusters exhibit self-sufficient engineering capabilities that reduce reliance on comprehensive vendor service contracts.
Germany
Precision pneumatic component manufacturing and biobank infrastructure expansion sustain demand for sample storage and liquid handling systems. EU In Vitro Diagnostic Regulation certification requirements filter market access for diagnostic-classified benchtop systems. The Rhine-Ruhr and Bavarian industrial regions concentrate pharmaceutical manufacturing facilities modernizing quality control automation.
India
CDSCO-registered production facilities under the PLI scheme require quality control automation to meet export compliance standards for regulated markets. The national pharmaceutical regulator mandates validated electronic records systems for facilities supplying to the United States and European Union. Maharashtra and Gujarat pharmaceutical manufacturing corridors are modernizing wet-lab infrastructure with benchtop liquid handling platforms.
Japan
PMDA-aligned quality management standards and precision manufacturing heritage sustain demand for sub-microliter liquid handling systems. METI industrial policy supports laboratory automation adoption in contract research organizations serving global pharmaceutical clients. The Kanto region around Tokyo concentrates diagnostic instrument manufacturers integrating benchtop modules into distributed hospital networks.
Switzerland
Swissmedic certification requirements and precision engineering capabilities position the country as a hub for high-value analytical instrumentation development. The national pharmaceutical regulator maintains alignment with FDA and EMA validation frameworks for AI-enabled laboratory systems. Basel and Zurich pharmaceutical research clusters drive demand for acoustic liquid handling technology in biologic assay development.
Laboratory Benchtop Automation Market Competitive Environment
On the supply side, the industry is consolidating around diversified life sciences conglomerates with captive distribution infrastructure and specialized precision instrumentation developers with modular platform architectures. Three strategic archetypes dominate: integrated conglomerates bundling hardware with consumables and service contracts, precision specialists competing on liquid handling accuracy, and emerging AI-enabled platform developers. Competitive moves center on M&A for software capabilities and geographic expansion into CDSCO-registered manufacturing corridors.
Among diversified life sciences conglomerates, Danaher Corporation and Thermo Fisher Scientific occupy positions anchored by direct sales infrastructure and segment breadth. Tecan Group Ltd. represents the precision specialist archetype, competing on modularity for mid-sized research laboratories. These three entities exemplify the tiered competitive structure separating scale-driven platform standardization from specialized workflow adaptation.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| Thermo Fisher Scientific, Inc. |
| Danaher Corporation |
| PerkinElmer, Inc. |
| QIAGEN GmbH |
| Tecan Group Ltd. |
| Hamilton Company |
| F. Hoffmann-La Roche AG |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
German and Japanese precision pneumatic component suppliers command outsized influence over liquid handling system margins, concentrating pricing power upstream while downstream buyers fragment across pharmaceutical, academic, and diagnostic tiers. This asymmetry shapes how vendors structure service contracts and consumable attach rates to recover margin.
Pricing Analysis
Pharmaceutical quality control laboratories anchor pricing stratification across premium, standard, and economy tiers. FDA 21 CFR Part 11 certification requirements separate premium validated platforms from standard research-grade systems, while academic core facilities populate the economy tier with minimal service bundling. Price differentiation hinges on software validation documentation and ISO 13485 quality system integration. Cost compression in the mid-tier intensifies as subscription financing models reduce upfront capital barriers. Academic laboratories exhibit highest price sensitivity due to grant-dependent budgets, whereas pharmaceutical QC operations prioritize compliance over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electromechanical actuator sourcing. Precision valve assemblies and linear motion components concentrate manufacturing in Germany, Japan, and Switzerland, with secondary machining capacity in South Korea and Taiwan. Raw material dependencies span specialty aluminum alloys, medical-grade polymers, and rare-earth magnet materials for servo motors. Single-source vulnerability persists for sub-microliter dispensing nozzles where Japanese suppliers maintain process IP advantages. Distribution runs through direct field service organizations for pharmaceutical accounts and authorized distributors for academic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory benchtop automation sits in early-cycle expansion as AI-enabled predictive maintenance capabilities penetrate beyond early adopters into mainstream pharmaceutical QC workflows. This technology migration creates asymmetric opportunity for vendors with embedded software architectures.
For Market Incumbents: Entrench platform standardization through LIMS integration depth and locked-model AI validation documentation. Prioritize captive consumable supply for liquid handling tips and reagent cartridges to defend against modular competitors. Acoustic liquid handling technology from Swiss and German specialists threatens traditional positive-displacement pipetting margins; backward integration into precision nozzle manufacturing or exclusive licensing agreements with acoustic technology developers protects pricing power.
For New Entrants and Emerging Players: Establish a beachhead in mid-sized contract research organizations seeking flexible automation without enterprise-scale capital commitments. India's CDSCO-registered manufacturing corridors under the PLI scheme offer the most penetrable geography, with quality control automation demand outpacing domestic vendor capacity. Lead with subscription-based financing and remote diagnostics-only service tiers to match Boston and San Diego biotech cluster self-sufficiency preferences.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with precision instrumentation developers holding ISO 13485 certification and established FDA master file documentation but lacking AI-enabled software roadmaps. Five-to-ten-year viability favors vendors converging mechatronics expertise with machine learning algorithm development. Watch FDA and EMA draft guidance publication timing on AI validation frameworks as the inflection signal for platform refresh cycles and M&A urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Predictive Maintenance Platform Launch | FDA draft guidance on algorithm transparency reshapes vendor development priorities for pharmaceutical QC laboratories. |
| Acoustic Liquid Handling Technology Licensing | Swiss and German biologic assay developers eliminate consumable costs and cross-contamination risk in high-value formulations. |
| CDSCO-Registered Manufacturing Corridor Expansion | India's PLI scheme quality control requirements create inbound demand for validated electronic records platforms. |
| LIMS Middleware Integration Partnership | Legacy academic medical center systems require custom data exchange solutions to unlock automation procurement. |
| Subscription Financing Model Penetration | Mid-sized research laboratories previously excluded from capital acquisition now access automated platforms through operational expenditure structures. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with laboratory directors, biomedical engineers, pharmaceutical QC managers, GPO contracts specialists, and regulatory affairs leads; and secondary validation against FDA 510(k) filings, EMA technical documentation, CDSCO registration databases, ISO 13485 certification records, and hospital procurement system contracts. Bottom-up triangulation across product type, end-user category, technology tier, and application focus converged with top-down macroeconomic and regulatory scenario modeling.
Forecast inputs span robotics hardware replacement cycles, software integration adoption curves, AI-enabled platform penetration rates, genomics sample prep automation demand, and pharmaceutical manufacturing capacity expansion across regulated markets. Segmentation dimensions modeled include product type capital intensity, end-user compliance burden, technology maturity gradient, and application throughput specifications. CAGRs were derived from installed base growth, replacement cycle compression, and pricing trajectory analysis across the projection horizon.
Stress conditions across pneumatic component supply disruption, EU In Vitro Diagnostic Regulation certification timeline extension, and AI validation framework implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
APAC Water Automation and Instrumentation Market
Automation
North America Data Center Automation Market
Automation
Global Form Automation Software Market
Automation
Home Automation Market
Automation
IoT Home Automation Market
Automation
Terminal Automation Systems Market
Automation
Parcel Sorting System Market
Automation
Europe Marketing Automation Software Market
Automation
Escalator Control Systems Market
Automation
North America Marketing Automation Software Market
Automation
Asia Pacific Marketing Automation Software Market
Automation
Lab Automation Market
Automation
Distribution Automation Solutions Market
Automation
RFID Kanban Systems Market
Automation
Voice Picking Solutions Market
Automation
Global Remote Monitoring and Control Market