
 Global Process Automation and Instrumentation Market | 2026-2036
Global Process Automation and Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Process Automation and Instrumentation Market Intelligence
The EU's Corporate Sustainability Reporting Directive (CSRD) is decoupling industrial efficiency investments from purely operational cost savings. This regulation mandates detailed reporting on energy consumption and environmental impact, creating a compliance-driven need for advanced monitoring. Siemens AG leverages its digital twin technology to help clients meet these new reporting obligations. Rockwell Automation specializes in integrated control systems for both process and discrete manufacturing, while Honeywell International Inc. competes with its extensive portfolio of sensors and control solutions for heavy industries.
Process automation and instrumentation involves using computer-based control systems and measurement devices to manage industrial operations. These systems maintain variables like temperature and pressure within precise tolerances, enhancing production efficiency and safety. Distributed Control Systems (DCS) are prevalent in capital-intensive sectors such as Oil & Gas. In contrast, Programmable Logic Controllers (PLC) provide scalable control for discrete manufacturing and chemical processing applications, offering flexibility for varied operational scales.
Regulatory frameworks from the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) mandate strict emissions monitoring. Concurrently, the EU's REACH regulation imposes controls on chemical handling, necessitating precise process instrumentation for compliance. Stakeholder decisions will increasingly center on selecting platforms that not only provide hardware accuracy but also integrate seamlessly with enterprise-level data analytics and reporting systems.
Market Dynamics
The central tension shaping the market is the collision between operational technology hardware lifecycles and the rapid software-driven demands for enterprise data integration. This dynamic is accelerated by compliance pressures from regulations like the EU's CSRD and the EPA's emissions rules.
Growth Catalysts
- Regulatory Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) creates a compliance-driven need for advanced sensors and monitoring systems by mandating detailed reporting on energy consumption and environmental impact across the manufacturing sector.
- Technology-Driven Validation:Uptake of digital twin technology in the pharmaceuticals industry enables virtual process simulation, helping companies meet stringent data integrity and process validation guidelines from regulators like the US FDA.
- National Industrial Policies:Industrial modernization programs in China, guided by its "dual carbon goals," are accelerating investment in high-efficiency instrumentation and control systems within advanced manufacturing hubs in coastal provinces.
Market Restraints
- Capital Intensity:The high initial capital expenditure required to deploy and commission large-scale Distributed Control Systems (DCS) remains a significant barrier for small and medium-sized enterprises, particularly in the bulk chemicals sector.
- Legacy System Integration:Integrating new automation platforms with aging, proprietary operational technology (OT) infrastructure is complex and costly, often leading to prolonged implementation cycles and unexpected compatibility issues for plant operators.
- Component Supply Concentration:The supply of high-performance semiconductors and microcontrollers, critical components for modern PLCs and smart sensors, is heavily concentrated in specific East Asian countries, creating supply chain vulnerabilities.
Strategic Opportunities
- New Vertical Penetration:The food and beverage industry presents a significant opportunity for track-and-trace solutions, using process instrumentation to provide the supply chain transparency and quality control data demanded by consumers and regulators.
- Predictive Maintenance Services:The convergence of process automation with AI and machine learning creates an opportunity to shift business models from one-time hardware sales to recurring revenue from software-based predictive maintenance services.
- Geographic Expansion:Underpenetrated markets in Southeast Asia, especially within Vietnam's expanding electronics and automotive assembly sectors, offer white space for vendors providing scalable, PLC-based automation solutions tailored for mid-sized factories.
Industry Challenges
- Skills Gap:A persistent shortage of automation engineers and data scientists who possess expertise in both operational technology (OT) and information technology (IT) hinders the effective deployment and optimization of sophisticated control systems.
- Cybersecurity Vulnerability:The increasing connectivity of industrial control systems (ICS) to enterprise networks and the cloud exposes critical infrastructure to a growing range of cybersecurity threats, demanding specialized security protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Process Automation and Instrumentation Market |
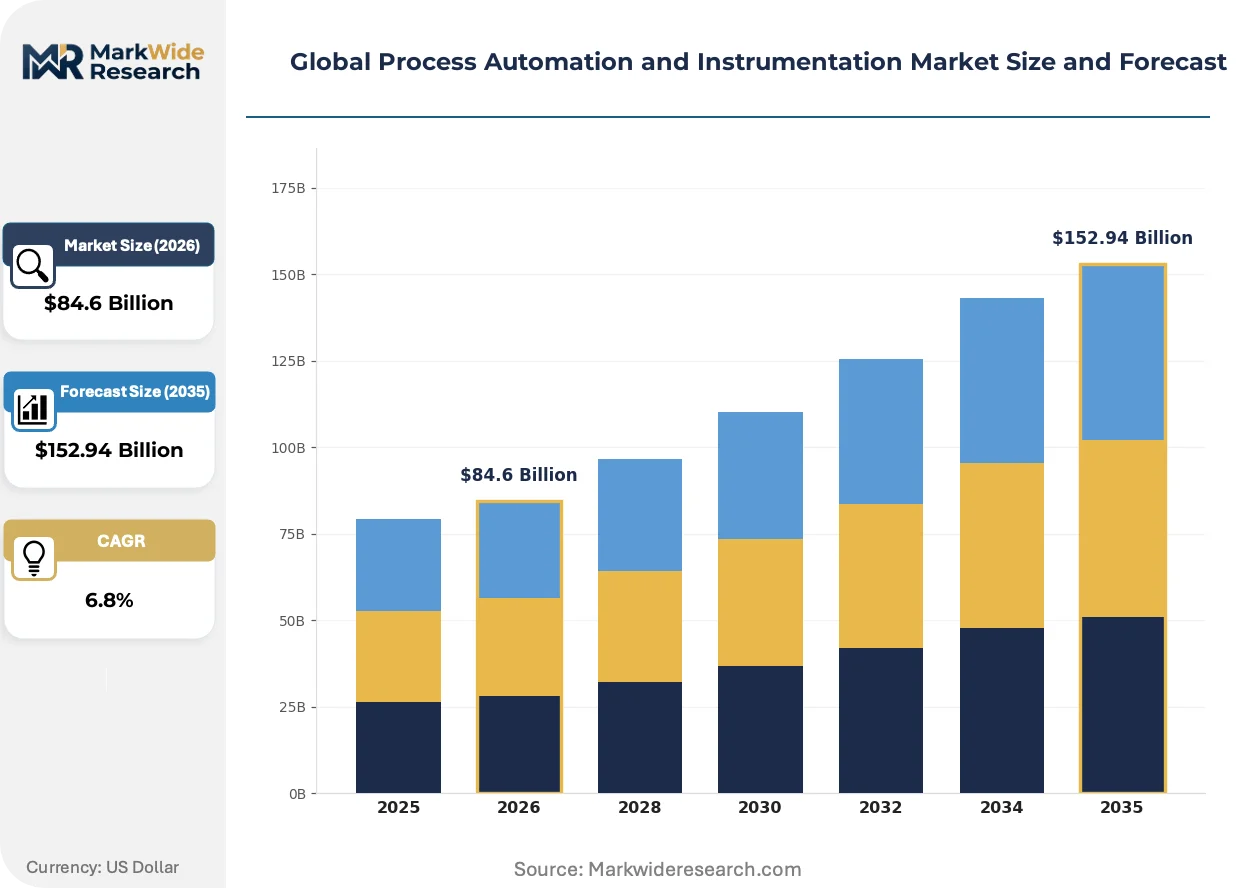
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLC, DCS, SCADA, HMI End User: Oil & Gas, Chemicals, Pharmaceuticals, Manufacturing Technology: Industrial Internet of Things, Cloud Computing, Machine Learning, Big Data Application: Process Control, Data Acquisition, Monitoring, Quality Assurance |
| Companies Covered | Emerson Electric Co., Rockwell Automation, Siemens AG, Mitsubishi Electric Corporation, Yokogawa Electric Corporation, ABB Ltd., Honeywell International Inc., Endress+Hauser Group, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Process Automation and Instrumentation Market Strategic Shifts & Innovations
The core evolution is the shift from isolated control loops to interconnected, data-centric industrial ecosystems. This transformation is driven by the need to feed operational data into higher-level enterprise planning and regulatory compliance reporting systems, moving value from hardware to software.
Edge computing integrates data processing capabilities directly within or near instrumentation devices like sensors and controllers. Process-intensive industries like oil and gas adopt this to reduce latency for real-time operational adjustments without relying on centralized cloud infrastructure. This trend is modularizing control architectures, allowing functions to be deployed flexibly rather than being confined to a central DCS.
Stricter mandates from the US Environmental Protection Agency (EPA) are tightening emissions monitoring requirements for industrial facilities under the Clean Air Act. This regulation compels operators in power generation and chemical processing to install and operate certified analytical instrumentation for pollutants. The heavy industry sector is most affected, investing in continuous emission monitoring systems (CEMS) that integrate with plant control platforms.
A behavioral shift involves end-users prioritizing platform interoperability and open standards over single-vendor, proprietary systems. This pattern disrupts the traditional vendor lock-in model, with buyers selecting best-of-breed components from multiple suppliers. This preference is most visible in Europe's discrete manufacturing sector, where Industry 4.0 initiatives promote data exchange across the value chain.
Global Process Automation and Instrumentation Market Segmentation
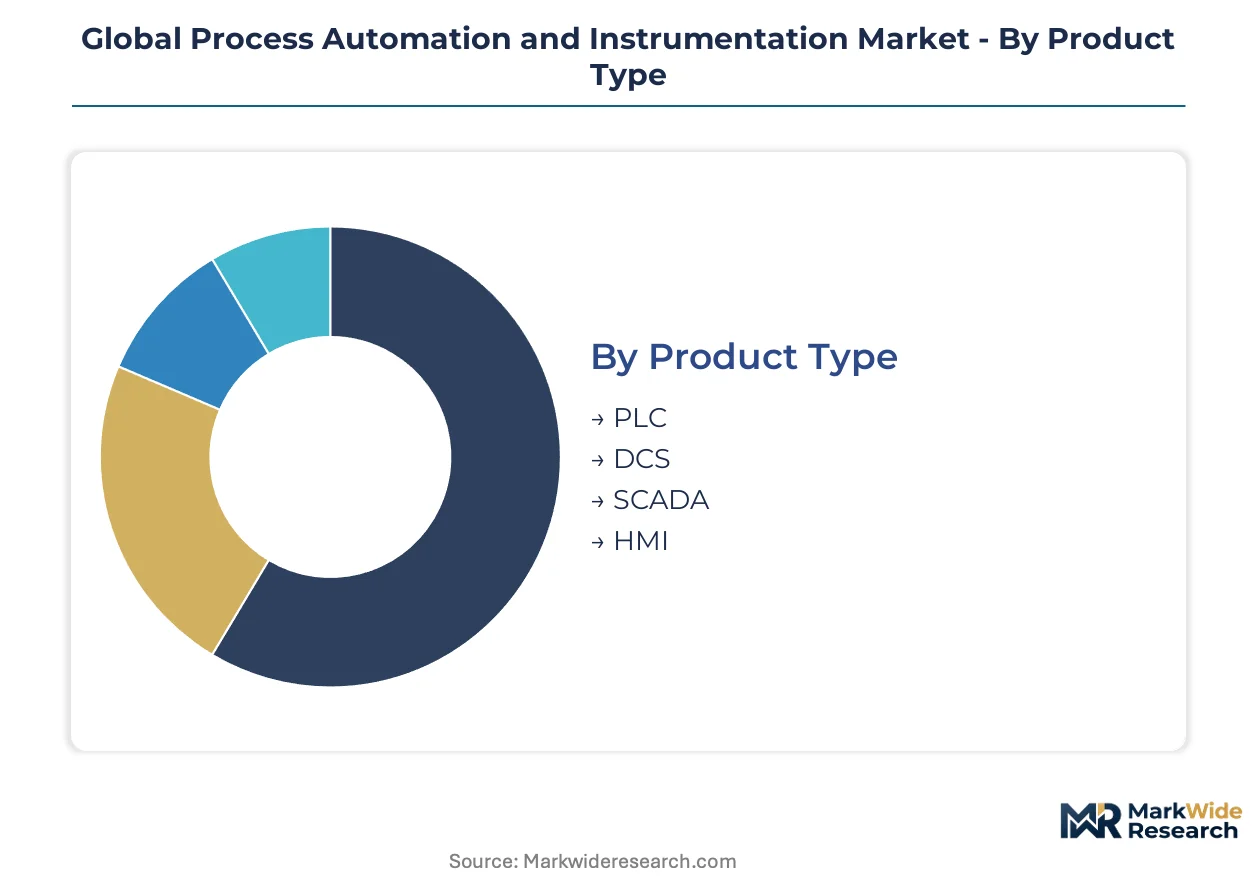
Understanding the market's segmentation reveals the diverse operational needs and technological preferences driving investment in process automation and instrumentation. Strategic decisions for vendors depend on targeting specific product types, end-user industries, and technological advancements. This detailed breakdown highlights areas of concentrated demand and emerging growth opportunities across the global landscape.
Product Type:
Buyers prioritize specific product types based on the complexity, scale, and criticality of their industrial processes.
- DCS:Distributed Control Systems (DCS) provide centralized control for large-scale, continuous processes, integrating thousands of I/O points across expansive facilities. Capital-intensive sectors like Oil & Gas in the Middle East heavily rely on DCS for robust, fault-tolerant operations, ensuring safety and efficiency.
- PLC:Programmable Logic Controllers (PLC) offer flexible, modular control for discrete manufacturing and batch processes, executing logic-based commands with high speed and reliability. Germany's automotive plants utilize PLCs extensively for precise assembly line automation, adapting quickly to production changes.
- SCADA:Supervisory Control and Data Acquisition (SCADA) systems monitor and control industrial processes remotely, aggregating data from various field devices.
- HMI:Human-Machine Interfaces (HMI) provide graphical user interfaces for operators to interact with control systems, visualizing process data.
Volume sits with Programmable Logic Controllers (PLC) due to their widespread use in discrete manufacturing; growth tilts toward Distributed Control Systems (DCS) for critical infrastructure projects.
End User:
End-user industries select automation solutions based on their unique operational requirements, regulatory environments, and product quality demands.
- Pharmaceuticals:The Pharmaceuticals sector requires highly precise instrumentation and validated control systems to meet stringent regulatory guidelines from bodies like the US FDA and EU EMA. Investment in digital twin technology helps pharmaceutical manufacturers in Ireland and Switzerland ensure data integrity and process reproducibility.
- Oil & Gas:Oil & Gas operations demand robust, explosion-proof instrumentation and advanced control for extreme environments, ensuring safety and optimizing resource extraction. Facilities in Saudi Arabia and Norway deploy continuous monitoring systems to manage complex drilling and refining processes effectively.
- Chemicals:The Chemicals industry uses process automation for precise temperature, pressure, and flow control, managing hazardous materials safely.
- Manufacturing:The Manufacturing sector adopts automation to enhance production line efficiency, reduce waste, and improve product consistency.
The sector is dominated by Manufacturing due to its broad application base; Pharmaceuticals shows the fastest expansion driven by compliance and quality imperatives.
Technology:
Technology choices are increasingly driven by the need for enhanced data flow, real-time analytics, and improved decision-making capabilities across industrial operations.
- Industrial Internet of Things:Industrial Internet of Things (IIoT) integrates sensors, devices, and control systems with network connectivity, enabling real-time data exchange for operational visibility and remote management. Manufacturers in Japan leverage IIoT platforms to optimize asset performance and implement predictive maintenance strategies.
- Machine Learning:Machine Learning (ML) algorithms analyze vast datasets from industrial processes to identify patterns, predict equipment failures, and optimize control parameters autonomously. Energy providers in the United States deploy ML for grid optimization and early fault detection in power generation facilities.
- Cloud Computing:Cloud Computing provides scalable infrastructure for storing and processing industrial data, supporting remote access.
- Big Data:Big Data analytics processes large volumes of operational information to extract actionable insights for process improvement.
While Industrial Internet of Things forms the foundational layer for connectivity, Machine Learning is rapidly gaining traction for advanced analytics and predictive insights.
Application:
Applications of process automation and instrumentation align with distinct core functions and operational objectives within industrial environments.
- Process Control:Process Control involves maintaining critical operational variables like temperature, pressure, and flow within specified setpoints using feedback loops and control algorithms. Chemical plants in Germany utilize advanced process control to ensure product consistency and optimize energy consumption.
- Monitoring:Monitoring applications involve continuous measurement and tracking of operational parameters, environmental emissions, or equipment health to ensure compliance and prevent deviations. Industrial facilities in China deploy continuous emission monitoring systems (CEMS) to meet strict MEE regulations.
- Data Acquisition:Data Acquisition systems collect raw sensor data from various points, converting it into digital formats for analysis.
- Quality Assurance:Quality Assurance applications verify product specifications and process integrity through automated inspection and measurement.
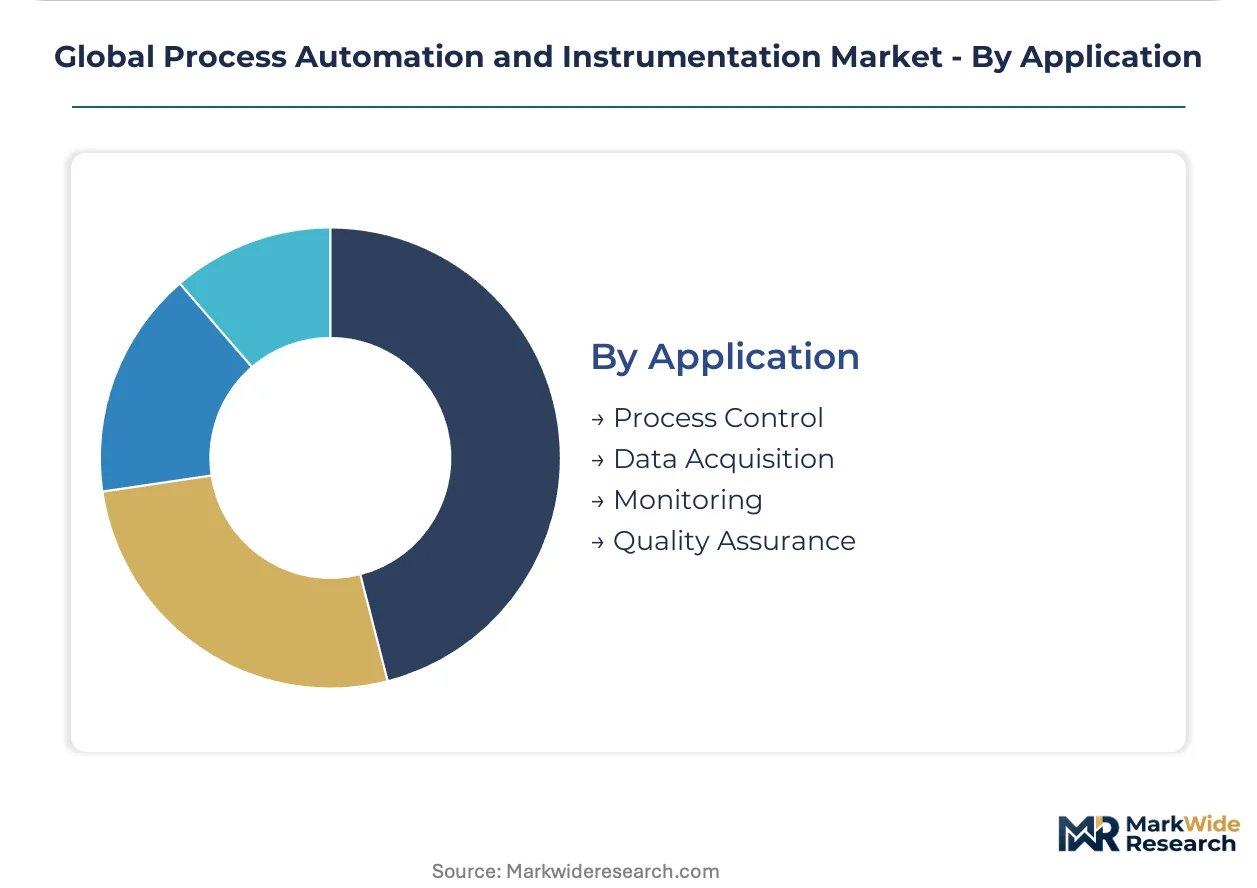
The primary focus remains on Process Control for operational stability, but Monitoring is becoming increasingly strategic due to escalating regulatory pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Free Trade Zone, a key economic initiative, drives significant investment in advanced manufacturing within China. This zone attracts companies seeking to leverage favorable policies for high-tech industrial development. Such concentrated economic areas foster specialized demand for process automation and instrumentation solutions.
China
Industrial modernization programs in China's coastal provinces fuel demand for advanced instrumentation and control systems. The Ministry of Ecology and Environment (MEE) mandates strict emissions monitoring, requiring continuous emission monitoring systems (CEMS). Advanced manufacturing hubs in Shenzhen and Suzhou are implementing high-efficiency automation to meet national "dual carbon goals."
Germany
Germany's automotive plants and chemical processing sectors require precise automation for efficiency and quality. The EU's Corporate Sustainability Reporting Directive (CSRD) creates a compliance-driven need for advanced monitoring solutions. Bavaria and North Rhine-Westphalia concentrate industrial automation firms and end-users, focusing on Industry 4.0 initiatives.
United States
Pharmaceuticals and energy sectors in the United States drive demand for validated control systems and robust instrumentation. The US Environmental Protection Agency (EPA) enforces stringent emissions rules, compelling investment in analytical instrumentation for pollutants. Texas's petrochemical corridor and California's biotech clusters deploy sophisticated process control for operational stability.
Saudi Arabia
Oil & Gas operations in Saudi Arabia necessitate explosion-proof instrumentation and advanced control for harsh environments. The Kingdom's Vision 2030 industrial diversification plan encourages local manufacturing, increasing automation adoption. Facilities in the Eastern Province, particularly Jubail, are deploying continuous monitoring systems to optimize complex refining processes.
Vietnam
Expanding electronics and automotive assembly sectors in Vietnam present significant opportunities for scalable automation solutions. The government's industrial development policies aim to attract foreign direct investment in high-tech manufacturing. Industrial parks near Ho Chi Minh City and Hanoi are adopting PLC-based systems to enhance production line efficiency.
Global Process Automation and Instrumentation Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the process automation and instrumentation market. The competitive landscape shows a tiered structure, with established industrial giants alongside agile technology providers. Key archetypes include global engineering solution providers, specialized sensor and device manufacturers, and software-centric analytics firms. Companies are pursuing strategic partnerships for technology integration and geographic expansion into emerging industrial markets.
Within the global engineering solutions archetype, Siemens AG and Rockwell Automation exemplify providers offering extensive portfolios spanning control systems and digital twin technologies. Siemens AG, a German-based multinational, delivers integrated industrial software and automation platforms across diverse sectors. Rockwell Automation, a US-based company, occupies a position specializing in integrated control systems for both process and discrete manufacturing applications. Endress+Hauser Group, a Swiss-based specialist, anchors the segment of high-precision measurement instrumentation and services. These firms represent different facets of market leadership, from broad-spectrum industrial automation to niche, high-accuracy sensor solutions.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Rockwell Automation |
| Siemens AG |
| Mitsubishi Electric Corporation |
| Yokogawa Electric Corporation |
| ABB Ltd. |
| Honeywell International Inc. |
| Endress+Hauser Group |
| Schneider Electric |
| Others |
Cost & Logistics Intelligence
Critical infrastructure-grade process automation, distinct from modular control systems, dictates both premium pricing for reliability and specialized supply chains for complex components. This market features a diverse set of suppliers, ranging from broad-spectrum industrial giants to niche specialists, each catering to specific segments with varying pricing power and supply chain resilience.
Pricing Analysis
Lead-time sensitivity drives premium pricing for highly customized DCS solutions, while standard PLC units often see spot market discounts. Project-based pricing dominates for DCS, while per-unit transactional models are common for PLCs. Certification levels like FDA validation and extensive after-sales service drive significant price differentiation. Pricing softness reflects competition from agile software providers. Small and medium-sized enterprises in discrete manufacturing are highly price-sensitive, unlike large pharmaceutical or Oil & Gas operators.
Supply Chain Analysis
Regional distribution centers facilitate the delivery of standard PLC components, while complex DCS modules often ship direct from specialized manufacturing hubs. Supply of critical components like high-performance semiconductors and microcontrollers concentrates heavily in East Asian countries. Germany provides specialized sensor technology and precision engineering. Single-source vulnerability for these advanced components presents a significant supply chain risk. Distribution runs through direct sales channels for large-scale projects and a network of system integrators for smaller, modular installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The process automation and instrumentation market is experiencing a vertical-integration race, with players actively pursuing software capability development as a key downstream lever.
For Market Incumbents: Deepen integration of digital twin technology across existing DCS portfolios to counter the threat from agile software-centric entrants. Invest in specialized cybersecurity solutions for industrial control systems, protecting critical infrastructure from increasing connectivity vulnerabilities. Expand recurring revenue models through software-as-a-service offerings for predictive maintenance, shifting from one-time hardware sales.
For New Entrants and Emerging Players: Open-standard, interoperable PLC solutions create a technology-first wedge into underpenetrated markets. Target mid-sized factories in Vietnam's expanding electronics and automotive assembly sectors with scalable automation. Focus on providing track-and-trace solutions for the food and beverage industry, leveraging compliance-driven demand for transparency. A go-to-market angle emphasizing rapid deployment and lower total cost of ownership will resonate.
For Investors and Strategic Acquirers: Re-rating potential sits with software-centric analytics firms given the compliance-driven demand for enterprise data integration. Long-term viability remains strong for companies enabling industrial decarbonization and regulatory reporting over the next decade. Acquisition targets should focus on specialized sensor manufacturers with robust intellectual property in emissions monitoring or digital twin providers. Increased M&A activity involving AI/ML firms for predictive maintenance will signal market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Digital Twin Technology | Siemens AG leverages this for process validation, ensuring data integrity for pharmaceutical clients. |
| Develop AI/ML Predictive Maintenance Services | Rockwell Automation can shift to recurring revenue by optimizing asset performance for heavy industries. |
| Expand Continuous Emission Monitoring Systems (CEMS) | Honeywell International Inc. meets strict EPA and MEE regulations for industrial facilities. |
| Acquire Industrial Cybersecurity Specialists | ABB Ltd. strengthens protection for critical infrastructure against increasing ICS connectivity threats. |
| Standardize on Open Automation Platforms | Yokogawa Electric Corporation attracts more diverse end-users seeking interoperability across discrete manufacturing. |
Research Approach
US FDA guidelines, EU CSRD documentation, and China's MEE mandates formed the secondary backbone for this analysis. Primary interviews with plant managers, automation engineers, and regulatory compliance officers provided critical qualitative insights. This qualitative data was triangulated with quantitative information from industry association reports and company financial filings. A bottom-up approach to market sizing was validated against top-down industry projections.
A bottom-up analytical framework aggregated demand across distinct product types and end-user industries. Segmentation dimensions modeled included technology, application, and regional regulatory environments across the analysis window. Compound Annual Growth Rates were derived from historical data trends and projected future adoption rates. Industrial modernization programs in China and pharmaceutical sector validation requirements served as key forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts and rapid component technology obsolescence. Forecasts reflect assumptions regarding regulatory stability and economic growth within advanced manufacturing hubs. Supply chain disruptions or major cybersecurity incidents could revise these projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Micro Fulfillment Market
Automation
Automation Lifecycle Services Market
Automation
Europe Data Center Automation Market
Automation
AR Automation Market
Automation
Global Automated Liquid Handlers Market
Automation
Laboratory Automation Market
Automation
Cognitive Process Automation Market
Automation
Pneumatic Tube System Market
Automation
Helpdesk Automation Market
Automation
Retail Automation Market
Automation
Computer Numerical Control Market
Automation
Window Automation Market
Automation
Europe Laboratory Automation Market
Automation
Global Database Automation Systems Market
Automation
Italy Process Orchestration Market
Automation
Home Automation System Market