
 Data Center Automation Market | 2026-2036
Data Center Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Automation Market Intelligence
Multi-source procurement of automation platforms is broadening as enterprises diversify vendor relationships beyond single-stack dependencies. Cisco Systems Inc. anchors physical networking automation through its unified fabric controllers. Microsoft Corporation extends cloud-native orchestration capabilities across hybrid estates. BMC Software Inc. specializes in mainframe-to-cloud workflow automation for legacy modernization.
Data center automation encompasses software-driven orchestration of compute, storage, and cooling resources with sub-second telemetry response thresholds for workload optimization. Its primary purpose eliminates manual provisioning latency while enforcing policy consistency across distributed infrastructure. Automation Software and DCIM Tools represent mature margin pools where incumbent platforms sustain recurring revenue, whereas Edge Computing deployment models attract fastest-growing investment as latency-sensitive applications proliferate outside core facilities. AI and Machine Learning technologies command premium positioning by enabling predictive capacity planning and autonomous remediation.
ISO standards for IT service management, the EU AI Act's risk classification framework, and Germany's BSI IT-Grundschutz baseline shape product certification requirements and cross-border deployment eligibility. These frameworks compel vendors to embed audit trails and explainability modules directly into automation engines. Stakeholders must weigh interoperability commitments against emerging sovereign cloud mandates before locking architecture decisions.
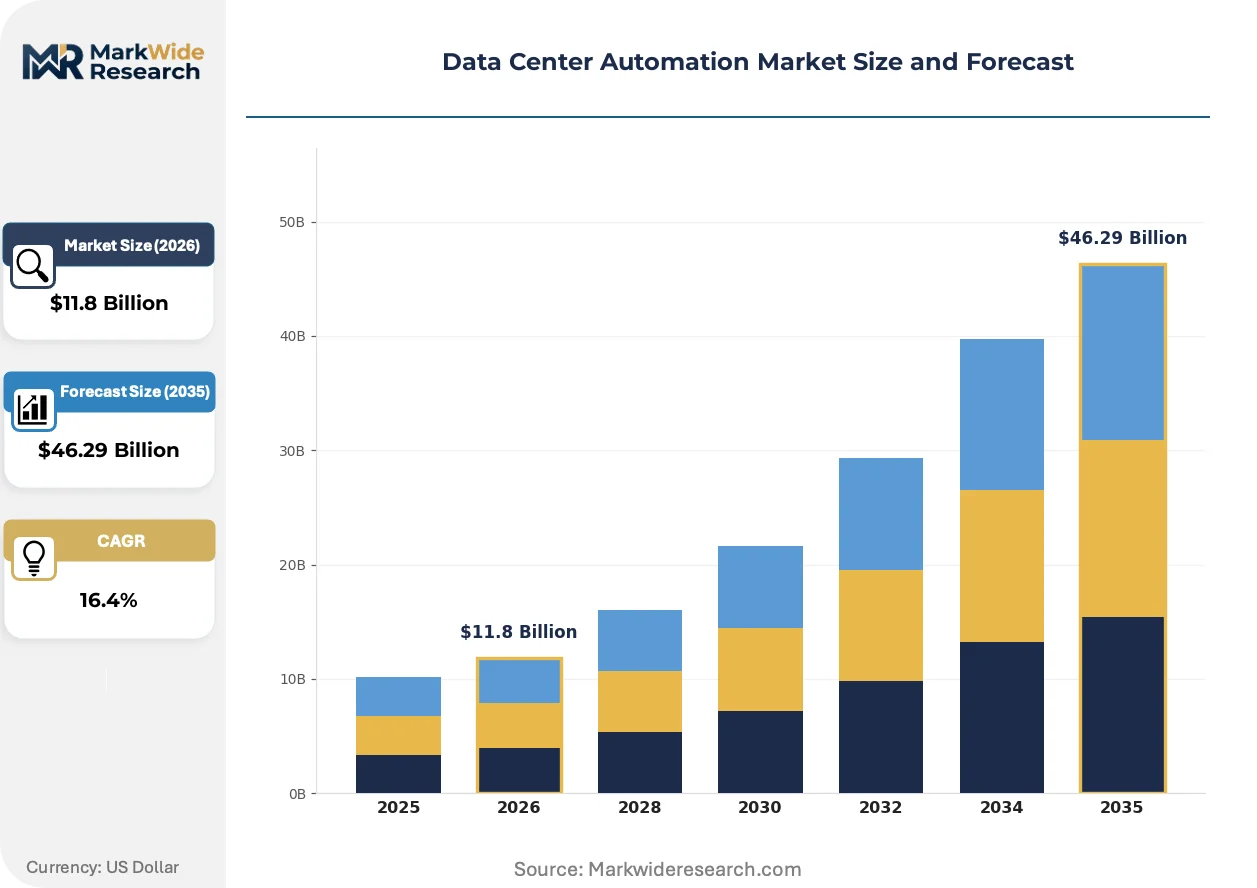
Market Dynamics
Hyperscale cloud operators are compressing provisioning cycles from hours to seconds, forcing automation vendors to engineer telemetry pipelines that sustain sub-second response thresholds across continental-scale infrastructure footprints.
Growth Catalysts
- EU AI Act Risk Classification:The EU AI Act mandates automated audit trails for high-risk AI systems, compelling data center operators to deploy governance engines that embed explainability modules directly into orchestration stacks.
- Edge Computing Latency Requirements:Autonomous vehicles and industrial robotics in Germany and Japan demand compute placement within 10 milliseconds of end-users, accelerating investment in distributed automation controllers outside core facilities.
- Liquid Cooling Infrastructure:Thermal management automation for direct-to-chip cooling is overtaking traditional air-handling architectures as AI training clusters exceed 100 kilowatts per rack in Northern Virginia and Singapore.
Market Restraints
- Specialized Engineering Talent Scarcity:The pipeline of engineers fluent in both mainframe COBOL and Kubernetes orchestration constrains legacy modernization velocity for financial services operators.
- Semiconductor Supply Concentration:Taiwan-based foundries dominate the fabrication of SmartNICs and DPUs that accelerate software-defined networking, creating single-source dependency for automation hardware.
- BSI IT-Grundschutz Certification Burden:Germany's baseline security standard requires 18-24 month validation cycles for automation platforms, delaying deployment timelines for multi-tenant facilities.
Strategic Opportunities
- France Nuclear-Powered Hyperscale Sites:The Gravelines and Tricastin nuclear clusters offer carbon-free baseload for AI training farms, attracting automation vendors to engineer sovereign cloud orchestration stacks compliant with ANSSI cybersecurity directives.
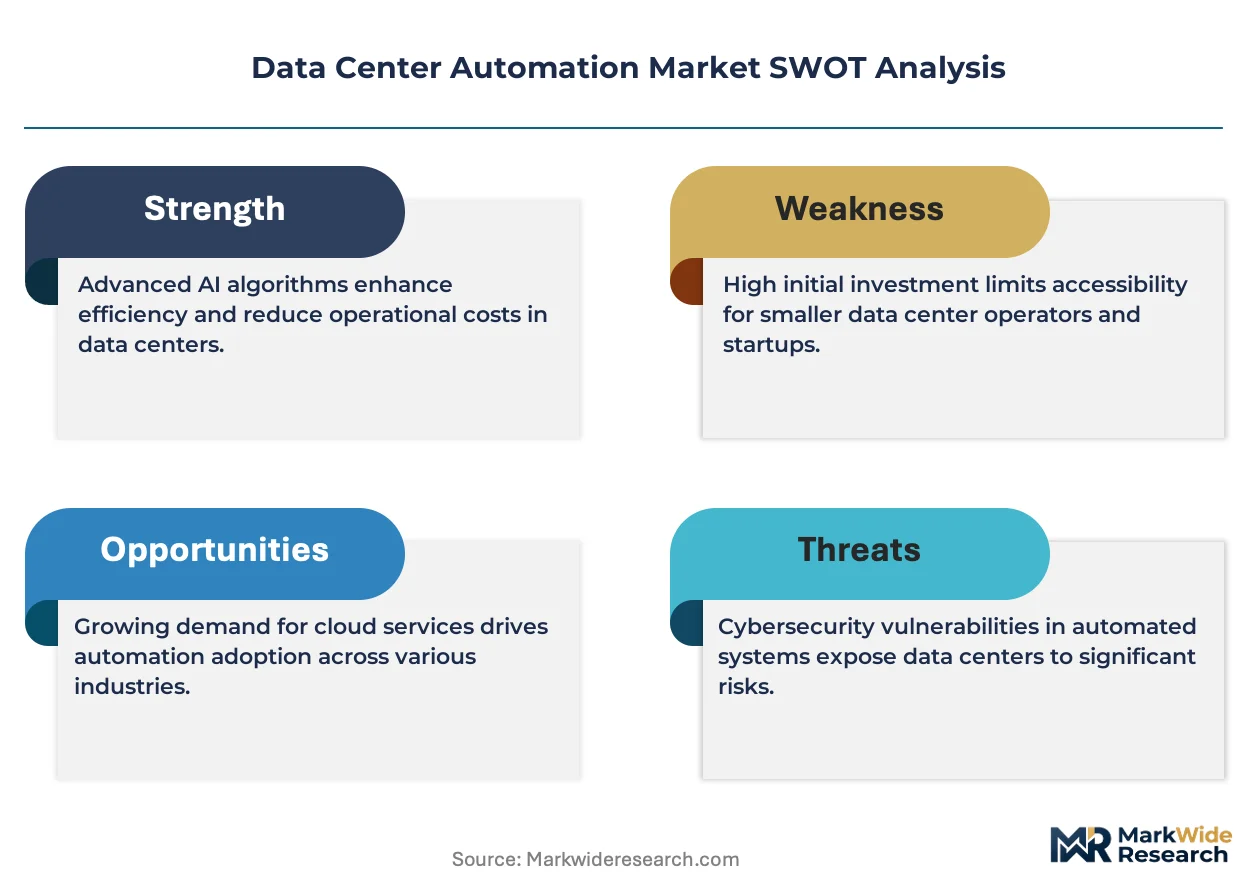
- Converged AI-Ops and FinOps Platforms:Real-time cost optimization algorithms fused with predictive failure detection are creating new software categories that command premium pricing from enterprise buyers.
- India Data Center Localization Mandate:The Reserve Bank of India's data localization requirements for financial services are forcing global operators to deploy in-country automation stacks, opening greenfield deployment opportunities in Mumbai and Chennai.
Industry Challenges
- Multi-Vendor API Fragmentation:Proprietary northbound interfaces from networking, storage, and compute vendors force integration teams to maintain custom middleware layers that degrade upgrade velocity.
- ISO 27001 Certification Backlogs:Third-party audit capacity constraints are stretching information security management system certification timelines to 14 months, blocking contract eligibility for automation service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Automation Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $46.29 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automation Software, DCIM Tools, Control Systems, Robotics Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Large Enterprises, SMEs, Data Center Providers, Managed Services Technology: AI, Machine Learning, IoT, Virtualization |
| Companies Covered | Cisco Systems Inc., Dell Technologies Inc., International Business Machines Corp., Hewlett Packard Enterprise Co., BMC Software Inc., Microsoft Corporation, Fujitsu Ltd., ServiceNow Inc., Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Automation Market Strategic Shifts & Innovations
Workload orchestration is fragmenting from monolithic platforms toward composable microservices that enable buyers to assemble best-of-breed automation stacks without vendor lock-in.
Intent-based networking is overtaking CLI-driven configuration management in hyperscale environments. The technology translates business policy into automated infrastructure state without manual translation layers. Cloud operators in the United States and Netherlands are deploying these systems at rack-scale density. This compression of the human-in-the-loop is enabling fleet-wide policy propagation in under 90 seconds.
The EU AI Act's risk classification framework is mandating embedded audit capabilities for high-risk automated decision systems. Vendors must now engineer explainability modules that trace infrastructure provisioning decisions to originating policy statements. German and French operators are prioritizing platforms with pre-certified compliance architectures to accelerate deployment timelines.
Consumption-based automation licensing is displacing perpetual software agreements in enterprise procurement cycles. Buyers in financial services and healthcare verticals are negotiating utility-priced orchestration tied to actual workload throughput. This shift is most visible in the United Kingdom and Australia, where CFOs are capitalizing automation spend as operational rather than capital expenditure.
Data Center Automation Market Segmentation
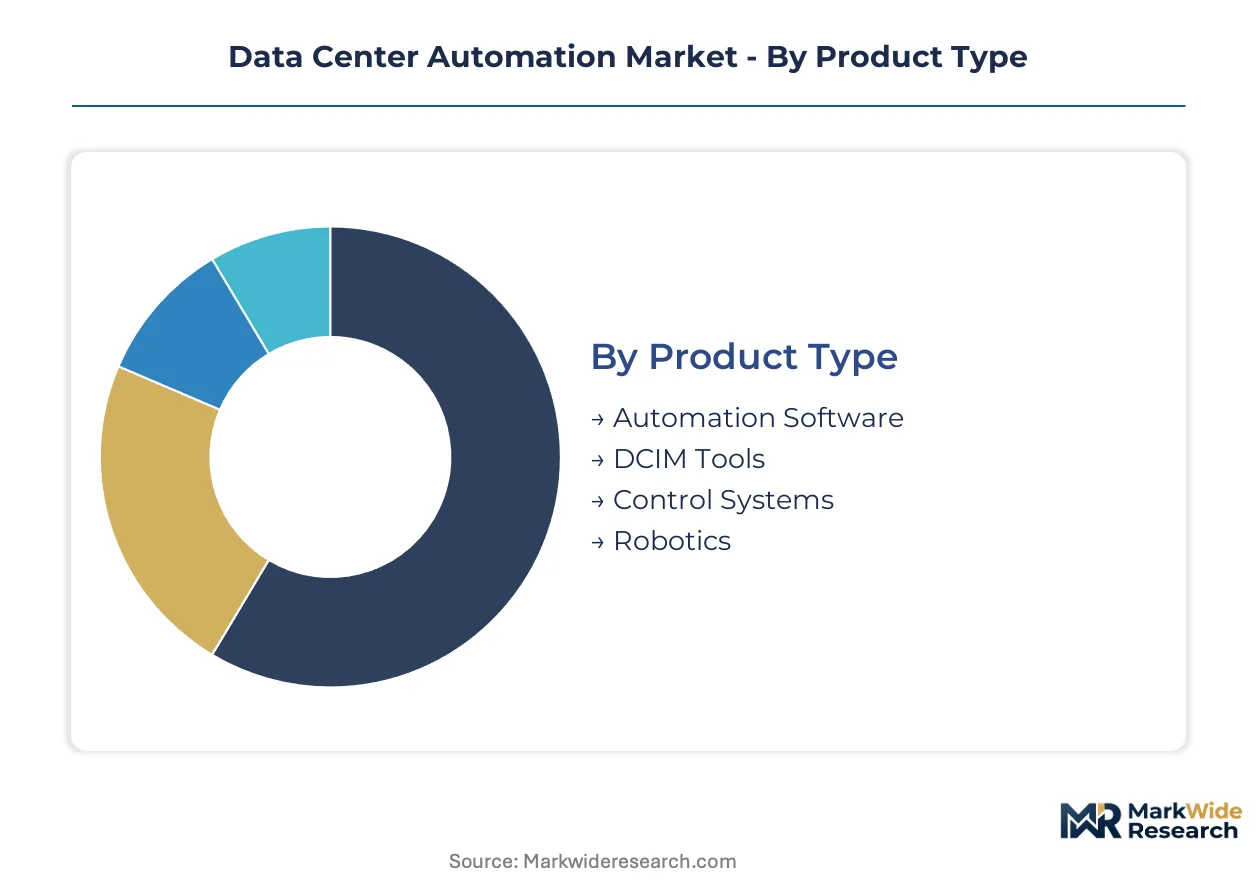
Segmentation in data center automation reveals how procurement priorities diverge across infrastructure maturity levels. Buyers in Northern Virginia's hyperscale clusters prioritize sub-second telemetry response, while European operators weight compliance certification cycles more heavily in vendor selection.
Product Type:
Cost tier differentiation separates buyers maintaining legacy estates from those building greenfield AI training facilities.
- Automation Software:Orchestration platforms provision compute, storage, and cooling resources through policy-driven APIs with sub-second execution loops. Financial services operators in Frankfurt and Singapore deploy these systems to compress provisioning cycles from hours to seconds while embedding EU AI Act audit trails directly into workflow engines.
- DCIM Tools:Data center infrastructure management platforms deliver real-time visibility into power, cooling, and space utilization across multi-tenant facilities. Colocation providers in Dallas-Fort Worth and Amsterdam rely on these systems to meet SLA commitments for latency-sensitive workloads while optimizing PUE metrics for sustainability reporting.
- Control Systems:Industrial-grade PLCs and SCADA integrations govern physical plant operations including UPS switching and generator sequencing.
- Robotics:Autonomous mobile robots handle server racking, cable management, and hardware replacement in unmanned facilities.
Automation Software leads volumes today; Robotics is gaining share fastest.
Deployment Model:
Application latency requirements dictate architecture choice more than capital availability for most buyers.
- On-Premises:Dedicated automation stacks deployed within facility boundaries satisfy sovereign data requirements and air-gapped security mandates. German operators pursuing BSI IT-Grundschutz certification favor these deployments to maintain direct control over audit trail generation.
- Cloud-Based:SaaS-delivered orchestration platforms reduce upfront capital commitment while enabling rapid scaling across distributed footprints. Mid-market enterprises in the United Kingdom and Australia prefer these models to classify automation spend as operational expenditure.
- Hybrid:Split orchestration across private control planes and public cloud bursting handles variable AI training workloads.
- Edge Computing:Distributed automation controllers operate outside core facilities to serve latency-critical applications.
On-Premises retains the largest installed base; Edge Computing shows the steepest expansion trajectory.
End User:
Customer type determines whether procurement emphasizes integration depth or deployment velocity.
- Large Enterprises:Fortune 500 technology and financial services firms operate automation programs spanning mainframe-to-cloud estates. These buyers in the United States and Japan demand vendors fluent in both COBOL legacy systems and Kubernetes-native orchestration.
- SMEs:Mid-market organizations prioritize pre-integrated platforms with reduced customization requirements. These buyers favor consumption-based licensing tied to actual workload throughput rather than perpetual software agreements.
- Data Center Providers:Colocation and wholesale facility operators automate multi-tenant provisioning and billing integration.
- Managed Services:Third-party operators deliver automation-as-a-service to clients lacking internal engineering capacity.
Large Enterprises dominate current procurement; Managed Services is climbing the fastest.
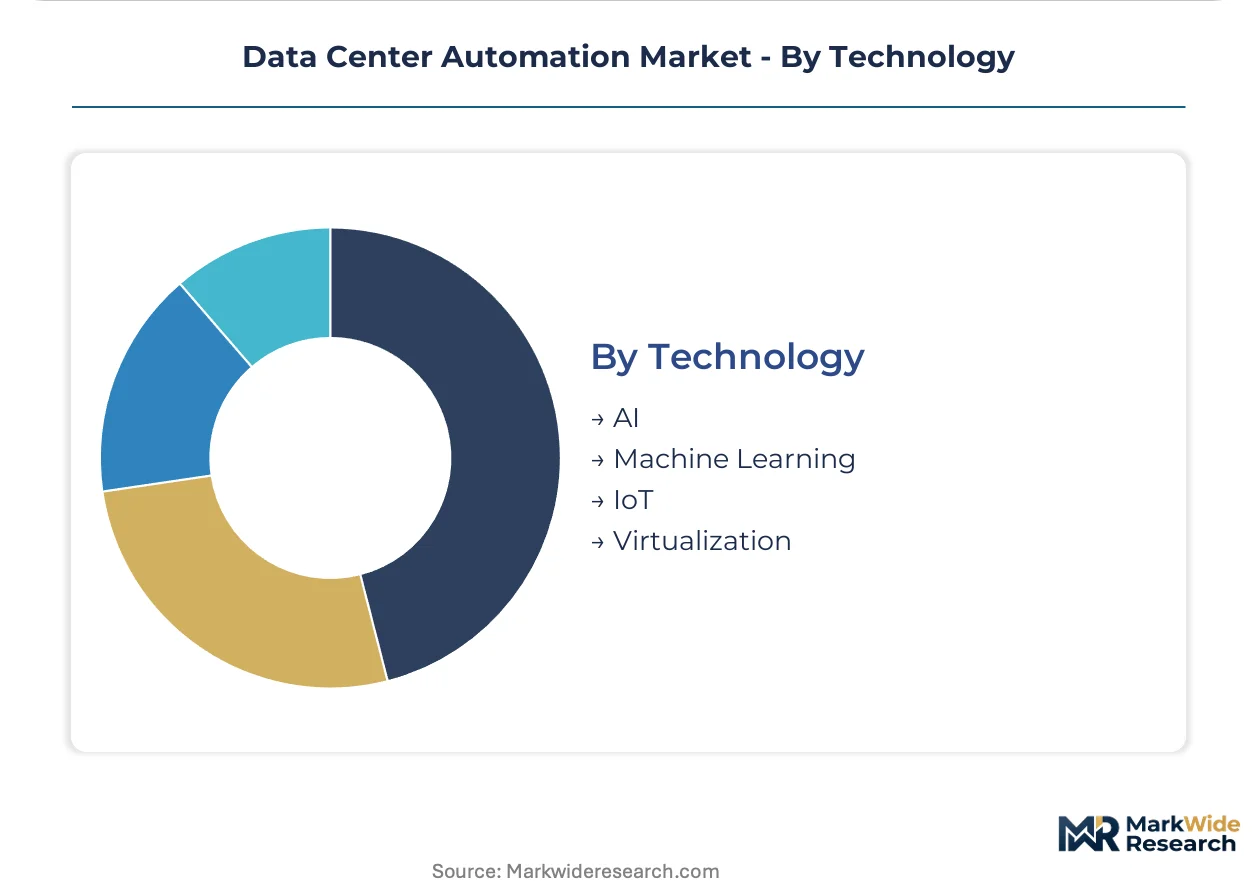
Technology:
Supply concentration in semiconductor fabrication shapes which technology layers attract premium investment.
- AI:Predictive capacity planning and autonomous remediation engines command premium positioning in vendor portfolios. Hyperscale operators in Northern Virginia deploy these systems to anticipate thermal anomalies before they trigger workload migration.
- Machine Learning:Pattern recognition models optimize cooling setpoints and power distribution based on historical workload telemetry. These capabilities attract strongest demand from facilities exceeding 100 kilowatts per rack density thresholds.
- IoT:Sensor networks deliver granular environmental telemetry for real-time infrastructure optimization.
- Virtualization:Software-defined abstraction layers decouple workload placement from physical hardware constraints.
Virtualization anchors the largest technology spend; AI is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's hyperscale corridor commands the largest concentration of automated infrastructure deployment, with Dallas-Fort Worth and Phoenix forming secondary gravity centers. Regulatory fragmentation across jurisdictions is reshaping vendor certification requirements and procurement timelines.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth compress provisioning cycles to sub-second thresholds for AI training clusters exceeding 100 kilowatts per rack. FERC interconnection standards and state-level renewable portfolio mandates in Texas and Virginia shape automation architecture decisions. The Phoenix data center cluster is expanding fastest as operators seek lower power costs and reduced seismic risk.
Germany
BSI IT-Grundschutz certification requirements impose 18-24 month validation cycles for multi-tenant automation platforms, slowing deployment velocity despite strong demand. The EU AI Act's risk classification framework mandates embedded audit trails for high-risk systems, compelling vendors to engineer explainability modules. Frankfurt anchors continental European automation procurement, with Berlin emerging as a secondary hub for sovereign cloud orchestration.
France
Nuclear-powered baseload at Gravelines and Tricastin attracts carbon-conscious hyperscale operators deploying AI training infrastructure. ANSSI cybersecurity directives govern sovereign cloud orchestration stack certification, creating compliance barriers for non-EU vendors. The Paris region concentrates financial services automation demand, with Marseille gaining traction for Mediterranean latency-sensitive workloads.
India
RBI data localization mandates for financial services force global operators to deploy in-country automation stacks in Mumbai and Chennai. The country's national IT regulator and central bank shape certification requirements for multi-tenant facilities. Bangalore's technology corridor drives demand for hybrid orchestration spanning mainframe legacy and cloud-native estates.
Singapore
Tropical thermal constraints accelerate adoption of liquid cooling automation as rack densities breach 100 kilowatts for AI inference workloads. The national cybersecurity agency and energy regulator enforce sustainability disclosure requirements that embed directly into DCIM procurement specifications. The Jurong and Tuas industrial zones concentrate new facility construction with integrated automation from ground-up design.
Data Center Automation Market Key Industry Players
Global majors compete with regional champions across orchestration stack certification and compliance specialization. The vendor base organizes around three tiers: full-stack infrastructure incumbents, cloud-native platform specialists, and legacy modernization boutiques. Consolidation pressure intensifies as buyers demand unified control planes spanning mainframe-to-cloud estates. Dominant competitive moves include strategic partnerships for API interoperability and geographic expansion into sovereign cloud markets.
Within the full-stack infrastructure tier, Cisco Systems Inc. and Dell Technologies Inc. anchor physical networking and compute automation respectively. Microsoft Corporation occupies a distinct position bridging cloud-native orchestration with hybrid estate management. BMC Software Inc. exemplifies the legacy modernization archetype, specializing in mainframe-to-cloud workflow automation for financial services operators in Frankfurt and Tokyo.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Dell Technologies Inc. |
| International Business Machines Corp. |
| Hewlett Packard Enterprise Co. |
| BMC Software Inc. |
| Microsoft Corporation |
| Fujitsu Ltd. |
| ServiceNow Inc. |
| Broadcom Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up automation specialists have consolidated fragmented DCIM and orchestration vendors across the United States and Europe, tightening pricing discipline while embedding sovereign-cloud compliance costs into platform premiums. Their portfolio companies now cross-sell certification-ready stacks to hyperscale operators, passing through semiconductor and liquid-cooling component inflation while capturing margin from bundled audit-trail modules.
Pricing Analysis
Input-cost pass-through from SmartNIC and DPU fabrication in Taiwan anchors subscription-tier escalation for orchestration platforms serving Northern Virginia and Frankfurt clusters. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act pre-certified stacks from baseline configurations lacking embedded explainability modules. Cost compression in standard-tier DCIM licensing is intensifying because mid-market buyers in the United Kingdom and Australia negotiate utility-priced consumption models. SMEs exhibit highest price sensitivity, while hyperscale operators in Dallas-Fort Worth absorb premium positioning for sub-second telemetry guarantees.
Supply Chain Analysis
India's phased manufacturing program and data localization mandates for financial services are reshaping sourcing patterns for automation hardware deployed in Mumbai and Chennai facilities. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, while liquid-cooling component production centers on Germany and Singapore. Raw material dependencies span gallium nitride for power electronics, specialized alloys for direct-to-chip cold plates, and high-purity copper for thermal interfaces. Single-source vulnerability in Taiwan-based SmartNIC foundries threatens provisioning timelines for software-defined networking stacks. Distribution runs through direct OEM relationships with hyperscale operators, supplemented by systems integrators serving enterprise and colocation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the EU AI Act's risk classification framework mandates continuous compliance investment, embedding recurring revenue into vendor relationships and elevating procurement budgets for explainability-ready infrastructure.
For Market Incumbents: Acquire mainframe-to-cloud workflow automation boutiques in Frankfurt and Tokyo to consolidate legacy modernization capabilities before Kubernetes-native challengers fragment financial services accounts. Invest in BSI IT-Grundschutz pre-certification for orchestration stacks to compress Germany's 18-24 month validation cycles into competitive moats. Prioritize backward integration into liquid-cooling controller firmware to capture margin from AI training cluster thermal automation.
For New Entrants and Emerging Players: Enter via sovereign cloud orchestration stacks tailored to France's ANSSI cybersecurity directives and nuclear-powered Gravelines deployments, where incumbent platforms lack localized compliance architectures. Target India's RBI-mandated data localization segment in Mumbai and Chennai, where global operators require greenfield automation deployment without legacy integration burden. Lead with consumption-based SaaS pricing to align with CFO preference for operational expenditure classification in mid-market procurement cycles.
For Investors and Strategic Acquirers: Valuations sit cheapest among DCIM specialists with pre-integrated EU AI Act audit capabilities but limited geographic footprint, offering rollup potential into full-stack platforms. Long-term viability hinges on orchestration software capturing increasing share of data center capital deployment as rack densities exceed 100 kilowatts and thermal automation becomes workload-critical. Monitor FERC interconnection queue clearance rates in Texas and Virginia as inflection indicator for hyperscale automation procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified control planes spanning mainframe COBOL and Kubernetes estates reduce middleware maintenance for Fortune 500 operators in Japan and the United States. |
| Acquisition of Specialist Firm | DCIM vendors with pre-certified BSI IT-Grundschutz architectures command premium multiples from buyers seeking Germany deployment acceleration. |
| Strategic Partnership | API interoperability agreements between networking and storage vendors alleviate integration team burden from proprietary northbound interfaces. |
| Geographic Expansion | Sovereign cloud orchestration stacks compliant with ANSSI directives unlock France's nuclear-powered hyperscale sites at Gravelines and Tricastin. |
| Product Launch | Converged AI-Ops and FinOps platforms with real-time cost optimization create new software categories commanding premium enterprise pricing. |
Research Approach
Multiple input streams — hyperscaler capex disclosures, SEC filings from automation vendors, and EU regulatory certification databases — were reconciled with primary interviews across data center operators, platform engineers, and IT procurement officers at financial services and colocation firms. Secondary validation drew from FERC interconnection filings, BSI certification registries, and ANSSI cybersecurity directive documentation. Bottom-up facility-level automation spend estimates were triangulated against top-down vendor revenue aggregation across the analysis window.
Data-stream reconciliation anchored volume projections to modeled segmentation across deployment model, organization size, vertical compliance intensity, integration complexity, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating AI training cluster expansion rates, edge computing latency requirement proliferation, and sovereign cloud mandate implementation timelines. Forecast inputs included rack density trajectories in Northern Virginia and Singapore, plus certification backlog durations for ISO 27001 and BSI IT-Grundschutz.
Inputs from hyperscaler engineering executives and German BSI auditors were available through the study window; gaps in private colocation operator spend disclosure introduce uncertainty bands around mid-market penetration estimates. Forecasts reflect assumptions regarding EU AI Act enforcement consistency and Taiwan semiconductor supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Process Automation Market
Automation
Global Warehouse Execution System Market
Automation
Retail Automation Market
Automation
Italy Marketing Automation Software Market
Automation
Automation Lifecycle Services Market
Automation
Middle East and Africa Workforce Management Market
Automation
Global Database Automation Systems Market
Automation
Workload Scheduling and Automation Market
Automation
Self Bag Drop Machine Market
Automation
Global Process Automation and Instrumentation Market
Automation
Process Control Systems for Steel Market
Automation
Distributed Control System Market
Automation
Home Automation and Controls Market
Automation
Global Cloud Automation Market
Automation
Global Form Automation Software Market
Automation
Automation Testing Market