
 Global Containerized Data Center Market | 2026-2036
Global Containerized Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Global Containerized Data Center Market Foresight
Data center engineering talent is bifurcating between hyperscale operators and specialized modular integrators, creating acute shortages in thermal design and containerized power distribution. Schneider Electric leverages its integrated power and cooling portfolio to anchor large European edge deployments. Huawei Technologies competes aggressively in emerging markets through captive manufacturing of prefabricated modules. Dell Technologies differentiates via software-defined infrastructure orchestration layered onto its modular hardware platforms.
Containerized data centers are self-contained, transportable facilities built within ISO-standard shipping frames, typically housing 100-500 kW of IT load with integrated cooling, power distribution, and fire suppression in a weatherized enclosure. These units deploy in weeks rather than years, serving enterprises that need rapid capacity expansion, remote edge processing, or disaster recovery sites. Prefabricated units dominate current revenue as established vendors scale factory production, while micro data centers represent the fastest-expanding category as 5G base stations and autonomous systems require sub-100 kW nodes at the network fringe. Edge deployment models are capturing disproportionate investment attention from telecommunications providers building distributed infrastructure for low-latency services.
FCC rules in the United States govern electromagnetic emissions from modular IT enclosures, while the EU Energy Efficiency Directive mandates granular power usage reporting for containerized facilities deployed across member states. Japan's METI enforces thermal performance standards that effectively require liquid cooling in high-density modular builds. Buyers must monitor how divergent efficiency codes across Germany, Japan, and India reshape equipment specifications and supplier qualification timelines.
Market Dynamics
Hyperscale cloud operators are compressing deployment timelines from years to weeks, forcing modular integrators to reengineer supply chains around factory pre-commissioning rather than field assembly. This velocity imperative is redrawing competitive boundaries between traditional data center construction firms and industrial manufacturing specialists.
Growth Catalysts
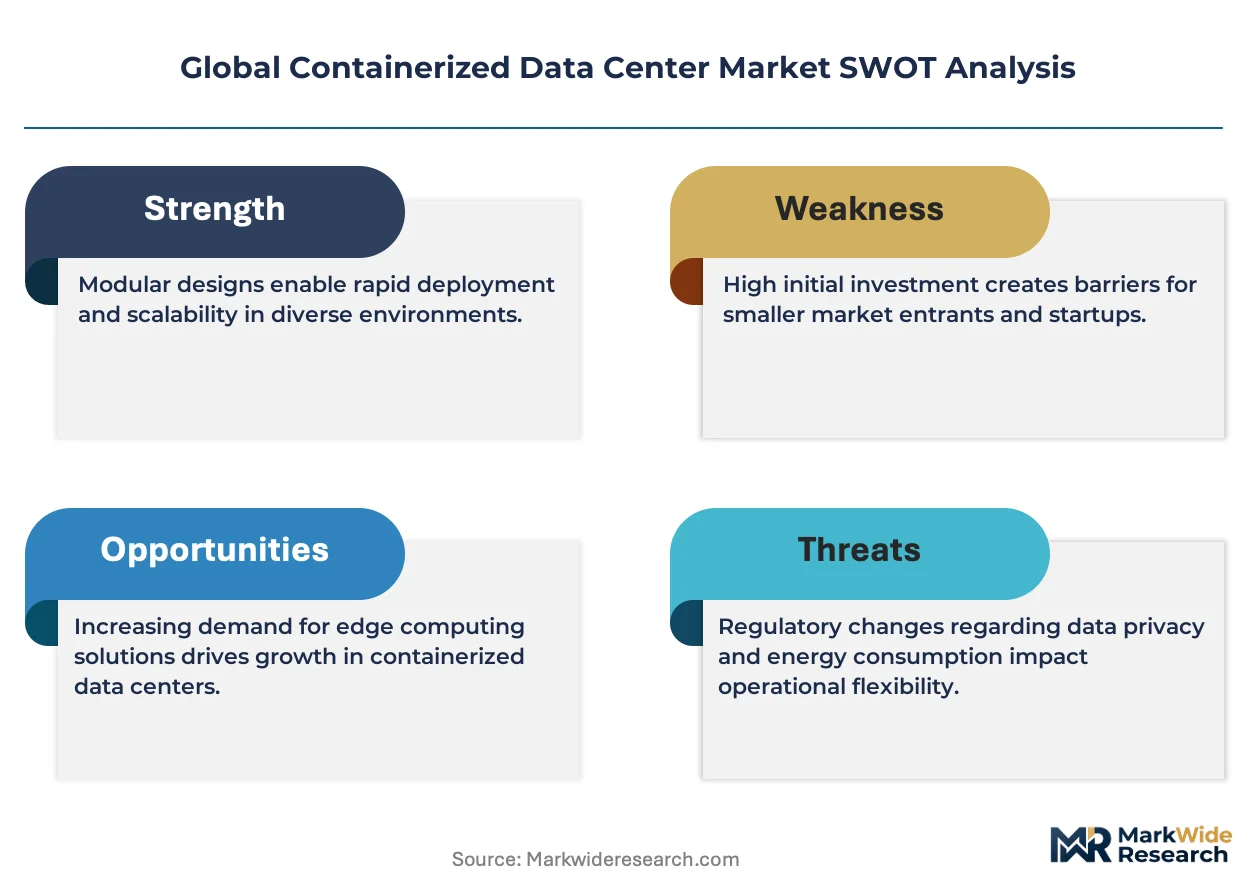
- EU Energy Efficiency Directive:Mandated PUE thresholds below 1.3 for new modular deployments are accelerating liquid cooling retrofits and factory-integrated thermal management across member states.
- AI inference workloads:Edge-located model serving for autonomous systems and real-time analytics is pulling sub-100 kW containerized nodes into 5G base station footprints.
- Germany:Sovereign cloud infrastructure requirements under Gaia-X principles are driving demand for domestically manufactured, certified modular facilities with encrypted supply chains.
Market Restraints
- Copper and electrical steel volatility:Prefabricated power distribution assemblies face margin compression when commodity prices spike, with limited pass-through mechanisms in fixed-price contracts.
- Specialized enclosure fabrication:ISO-standard weatherized frames rely on a concentrated supplier base in East Asian heavy-industry zones, creating single-source vulnerability.
- Electromagnetic compatibility certification:FCC Part 15 testing for modular IT enclosures adds 8-14 weeks to qualification timelines, delaying revenue recognition for new product variants.
Strategic Opportunities
- Brazil:Disaster recovery mandates for financial institutions under central bank regulations are opening procurement windows for rapidly deployable secondary sites outside São Paulo and Rio de Janeiro.
- Direct liquid cooling convergence:Integration of single-phase immersion systems with prefabricated power distribution is enabling 50 kW per rack densities in edge-constrained footprints.
- India:PLI scheme incentives for domestic electronics manufacturing are subsidizing local assembly of containerized modules, reducing landed cost for hyperscale operators.
Industry Challenges
- Thermal design engineering scarcity:Factory-integrated cooling system design requires simultaneous expertise in CFD simulation, refrigerant thermodynamics, and maritime transport shock loading, with fewer than 200 qualified practitioners globally.
- Multi-jurisdiction certification stacking:A single module deployed across Germany, Japan, and Australia requires sequential testing against divergent efficiency codes, fire suppression standards, and seismic ratings, extending time-to-revenue by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Containerized Data Center Market |
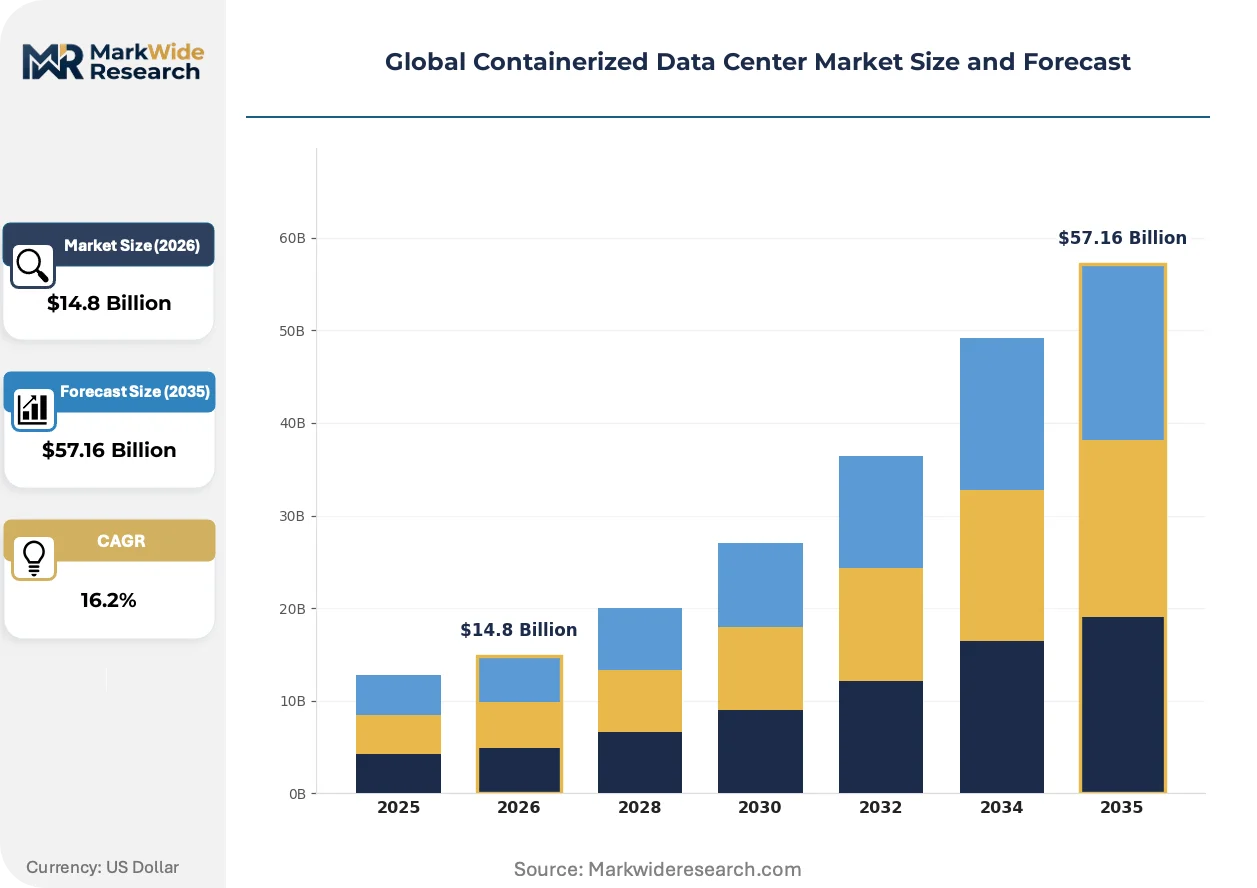
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $57.16 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Colocation, Edge, Cloud Connected Solution Type: Prefabricated Units, Modular Containers, Micro Data Centers, Portable Data Centers Application: Telecom, Banking & Finance, Media & Entertainment, Research Institutions End User: Telecommunications Providers, Financial Services Firms, Content Delivery Networks, Scientific Laboratories |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, Schneider Electric, Huawei Technologies, IBM Corporation, Vertiv Holdings, Cisco Systems, Amazon Web Services, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Containerized Data Center Market Shifts & Advancements
Modular data center architecture is converging with industrial manufacturing disciplines, compressing the boundary between IT equipment and building systems. Three developments are restructuring how capacity reaches the network edge.
Single-phase immersion cooling is miniaturizing thermal management into rack-level sealed systems that eliminate mechanical refrigeration. Telecommunications providers deploying 5G distributed units are specifying these systems for tropical climates where ambient temperatures exceed 35°C. The technology is miniaturizing cooling infrastructure from facility-scale chillers to sealed dielectric baths that ship pre-charged from the factory.
Japan's METI thermal performance standards are mandating liquid cooling for any modular build exceeding 30 kW per rack, effectively prohibiting air-cooled designs in high-density configurations. Japanese system integrators are now certifying factory-built modules against JIS earthquake resistance and METI energy efficiency benchmarks simultaneously. Domestic manufacturers are capturing this regulated demand through captive engineering services that bundle compliance documentation with hardware delivery.
Enterprise buyers are unbundling hardware procurement from multi-year managed service contracts, treating containerized modules as capital equipment with separate software orchestration layers. This pattern is displacing the integrated lease-to-operate models that dominated early modular adoption. Financial services firms in Singapore and Sydney are driving this shift, preferring to own depreciating assets while contracting operations to specialized third parties.
Global Containerized Data Center Market Segmentation
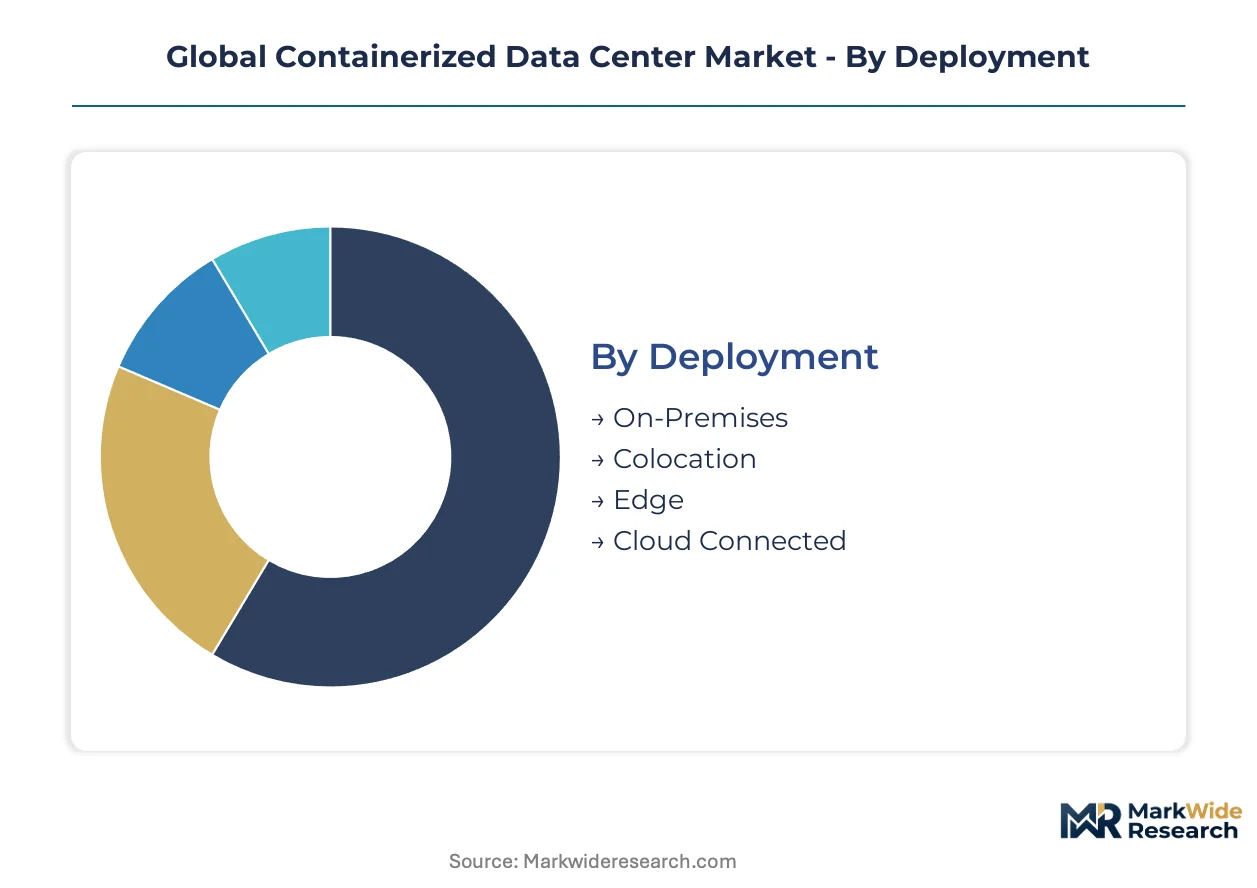
Containerized data center segmentation reveals how deployment velocity, thermal density, and sovereignty requirements reshape procurement patterns. Buyers select configurations based on jurisdictional compliance burdens and latency constraints rather than capital cost alone.
Deployment:
FCC Part 15 governs electromagnetic emissions for modular enclosures in the United States, while the EU Energy Efficiency Directive mandates granular PUE reporting across member states, creating divergent qualification pathways for identical hardware.
- On-Premises:Enterprises deploy these units within owned facilities for sovereign data control and compliance isolation. German manufacturers under Gaia-X principles supply encrypted supply chain modules for Frankfurt and Munich financial clusters facing domestic data residency mandates.
- Colocation:Third-party facility operators integrate containerized pods to expand available sellable capacity without structural construction. Demand concentrates in Amsterdam and Singapore where land scarcity and permitting delays make modular expansion economically decisive.
- Edge:Sub-100 kW nodes deploy at 5G base stations and autonomous system endpoints. Brazil's central bank disaster recovery regulations for financial institutions outside São Paulo and Rio de Janeiro accelerate procurement of rapidly deployable secondary edge sites.
- Cloud Connected:Hybrid architectures link modular facilities to hyperscale backbones for burst capacity and backup. Indian PLI scheme subsidies for domestic electronics manufacturing reduce landed costs for hyperscale operators building distributed cloud infrastructure.
Established volume favors On-Premises; emerging adoption favors Edge.
Solution Type:
Cost tier differentiation separates factory-integrated thermal management from field-assembly alternatives, with liquid cooling commanding premium positioning in high-density configurations.
- Prefabricated Units:Factory-built modules with pre-integrated power distribution and cooling ship with completed commissioning documentation. These dominate current revenue as established vendors scale production lines for standardized 100-500 kW configurations.
- Modular Containers:ISO-standard shipping frames with customizable internal layouts accommodate variable rack densities and power topologies. Japanese METI thermal performance standards mandating liquid cooling above 30 kW per rack reshape specifications for high-density variants.
- Micro Data Centers:Sub-100 kW self-contained nodes serve network fringe applications. These are expanding most quickly as 5G infrastructure and autonomous systems proliferate, with telecommunications providers specifying sealed dielectric bath cooling for tropical climates exceeding 35°C ambient.
- Portable Data Centers:Rapidly deployable units on transportable skids address disaster recovery and temporary capacity needs. Australian financial services procurement for business continuity sites outside primary metropolitan zones drives specification requirements.
Factory scale advantages concentrate in Prefabricated Units; deployment velocity advantages concentrate in Micro Data Centers.
Application:
Customer type determines thermal density requirements and certification stacking complexity, with regulated industries accepting longer lead times for multi-jurisdiction compliance documentation.
- Telecom:Distributed infrastructure for low-latency services requires sub-100 kW nodes at cell tower footprints. 5G network buildouts specify liquid-cooled micro data centers for real-time streaming and AI inference workloads.
- Banking & Finance:Disaster recovery mandates and data sovereignty requirements dominate procurement. Brazil's central bank regulations and Singapore financial authority guidelines create dual compliance burdens for multinational institutions.
- Media & Entertainment:Content delivery networks deploy edge-located caching nodes to reduce streaming latency. Live event production requires rapidly deployable temporary capacity for broadcast infrastructure.
- Research Institutions:High-performance computing workloads demand 50 kW per rack densities enabled by direct liquid cooling convergence with prefabricated power distribution. Seismic rating requirements for laboratory-adjacent deployment add certification complexity.
Procurement standardization favors Telecom; compliance complexity favors Banking & Finance.
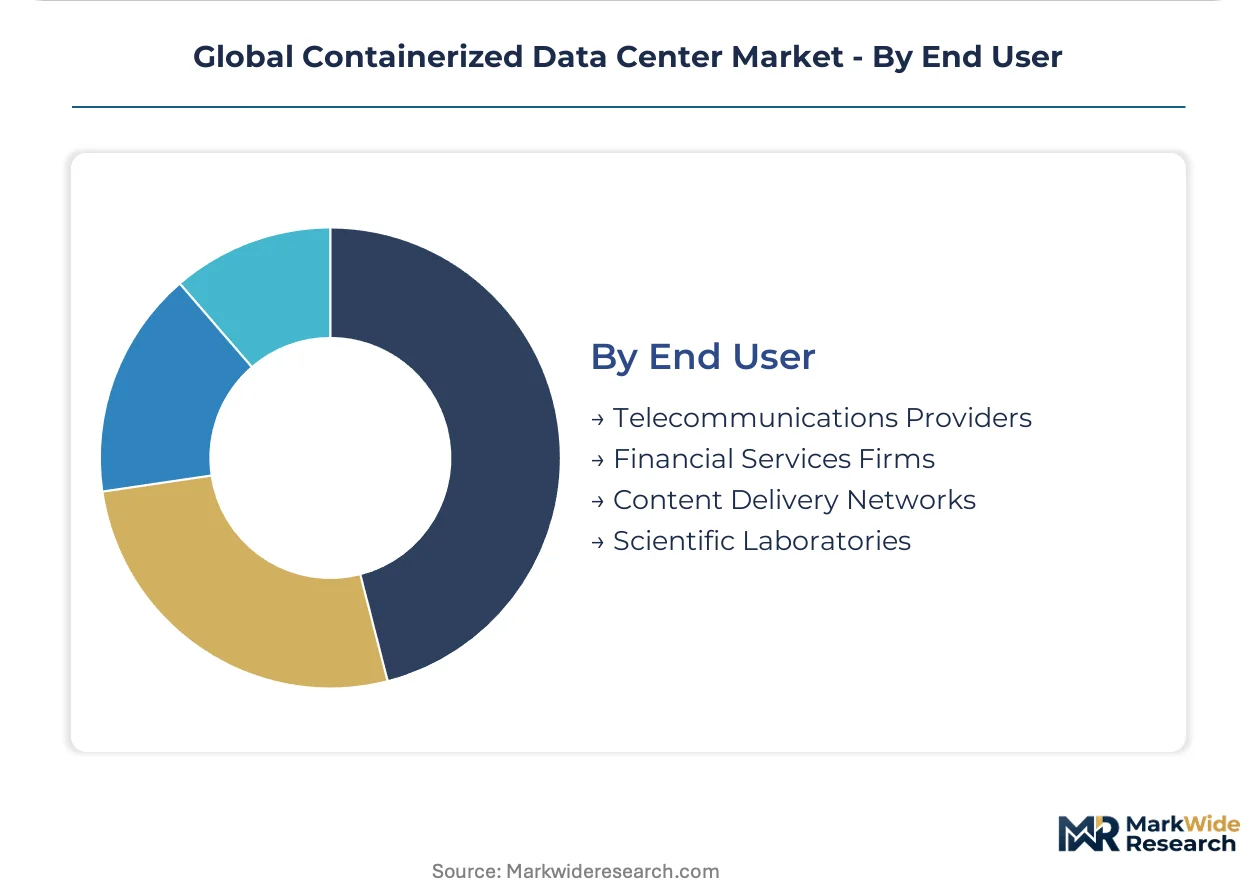
End User:
Margin structure varies by buyer sophistication, with hyperscale operators compressing supplier margins through volume aggregation while specialized integrators capture premium pricing from compliance-constrained enterprises.
- Telecommunications Providers:Distributed 5G infrastructure investment prioritizes factory pre-commissioning to compress deployment timelines from years to weeks. These buyers unbundle hardware procurement from managed service contracts, treating modules as capital equipment.
- Financial Services Firms:Singapore and Sydney institutions drive the shift toward asset ownership with separate operations contracting. Sovereign cloud requirements under Germany's Gaia-X principles mandate domestically manufactured, certified modular facilities.
- Content Delivery Networks:Edge footprint expansion for streaming optimization requires tropical-climate thermal specifications. Single-phase immersion cooling eliminates mechanical refrigeration in ambient temperatures exceeding 35°C.
- Scientific Laboratories:High-density computing requirements combine with seismic and fire suppression standards that extend qualification timelines. Multi-jurisdiction certification stacking for modules deployed across Germany, Japan, and Australia adds 4-6 months to revenue recognition.
Volume concentration sits with Telecommunications Providers; margin premium capture sits with Financial Services Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes containerized data centers for sovereign cloud compliance, while Brazil deploys identical hardware for disaster recovery mandates—revealing how regulatory intent reshapes identical technology across geographies.
United States
FCC Part 15 electromagnetic compliance and hyperscale edge expansion drive procurement patterns. Cloud operators compress deployment timelines through factory pre-commissioning rather than field assembly. Northern Virginia and Dallas-Fort Worth clusters anchor demand for sub-100 kW modular nodes at 5G base stations.
Germany
Gaia-X sovereign cloud principles mandate domestically manufactured modules with encrypted supply chains. The EU Energy Efficiency Directive enforces PUE thresholds below 1.3, accelerating liquid cooling retrofits. Frankfurt and Munich financial clusters procure certified facilities for data residency compliance.
Japan
METI thermal performance standards prohibit air-cooled designs above 30 kW per rack, mandating liquid cooling in high-density configurations. JIS earthquake resistance certification runs parallel to energy benchmarks. Tokyo and Osaka system integrators bundle compliance documentation with factory-built module delivery.
India
PLI scheme subsidies for domestic electronics manufacturing reduce landed costs for hyperscale operators building distributed infrastructure. Sovereign cloud requirements and disaster recovery mandates concentrate demand in Mumbai and Bangalore. Local assembly lines scale factory production for standardized configurations.
Brazil
Central bank regulations mandate disaster recovery sites for financial institutions outside São Paulo and Rio de Janeiro. Rapidly deployable secondary sites specify weatherized enclosures for tropical climates. Edge procurement accelerates as telecommunications providers build distributed infrastructure for low-latency services.
Global Containerized Data Center Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in factory-pre-commissioned thermal and power systems. The structure bifurcates between hyperscale-captive suppliers and modular integrators serving compliance-constrained enterprises. Two archetypes dominate: diversified industrial conglomerates leveraging integrated portfolios, and specialized fabricators capturing premium pricing through certification bundling. Competitive moves center on supply chain compression through factory pre-commissioning and geographic qualification stacking for multi-jurisdiction deployment.
Within the integrated infrastructure tier, Schneider Electric anchors European edge deployments through captive power and cooling portfolios. Huawei Technologies exemplifies emerging-market penetration via prefabricated module manufacturing. Dell Technologies occupies a position in software-defined orchestration layered onto modular hardware platforms.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| Schneider Electric |
| Huawei Technologies |
| IBM Corporation |
| Vertiv Holdings |
| Cisco Systems |
| Amazon Web Services |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Factory pre-commissioning cycles of 12-16 weeks compress pricing power toward integrators with captive manufacturing, while spot buyers of ISO-standard enclosures absorb volatility in copper and electrical steel. Long-term offtake contracts for prefabricated modules anchor revenue recognition, yet fixed-price agreements expose margins when commodity indices spike.
Pricing Analysis
Long-term offtake contracts dominate hyperscale procurement, locking unit economics across multi-year deployment schedules. Price differentiation separates liquid-cooled premium configurations from air-cooled standard tiers, with certification stacking for Japan's METI standards commanding additional margin. Cost compression in entry-level prefabricated units intensifies as Indian PLI-subsidized local assembly floods price-sensitive segments. Financial services firms in Singapore and Sydney exhibit lowest price sensitivity, prioritizing encrypted supply chains and compliance documentation over capital cost.
Supply Chain Analysis
Strait of Malacca transit routes concentrate risk for specialized enclosure fabrication, as ISO-standard weatherized frames draw from concentrated heavy-industry zones in China, South Korea, and Taiwan. Raw material dependencies center on copper busbar assemblies, electrical-grade steel laminations, and dielectric cooling fluids. Single-source vulnerability in maritime-grade aluminum extrusion creates exposure to logistics disruption. Distribution runs through factory-direct channels for hyperscale operators, while regional system integrators capture margin through certification bundling and field commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale cloud operators building sovereign cloud infrastructure present a substitution threat to traditional modular integrators, as captive engineering teams internalize factory-pre-commissioned capacity.
For Market Incumbents: Compound factory scale advantages through backward integration into power distribution assembly and liquid cooling component manufacturing. Defend against hyperscale verticalization by anchoring multi-jurisdiction certification expertise—specifically METI thermal standards and EU Energy Efficiency Directive compliance—that cloud operators cannot replicate without 4-6 month qualification delays. For New Entrants and Emerging Players: Lead with edge deployment velocity in Brazil's disaster recovery procurement windows and India's PLI-subsidized assembly corridors. Target telecommunications providers unbundling hardware from managed services, offering software-defined orchestration layers as the wedge for modular hardware attachment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core data center infrastructure divisions. Five-to-ten-year viability hinges on thermal design engineering scarcity—watch for inflection when CFD simulation and refrigerant thermodynamics training programs expand qualified practitioner pools beyond current sub-200 global estimates.| Strategic Initiative | Industry Significance |
|---|---|
| Factory Pre-Commissioning Scale-Up | Compresses deployment timelines from years to weeks for hyperscale edge expansion. |
| Multi-Jurisdiction Certification Stacking | Captures premium pricing through bundled METI, EU Energy Efficiency, and Gaia-X compliance. |
| Direct Liquid Cooling Convergence | Enables 50 kW per rack densities in tropical climates exceeding 35°C ambient. |
| PLI-Subsidized Local Assembly | Reduces landed costs for hyperscale operators building sovereign cloud infrastructure in India. |
| Software-Defined Orchestration Layer | Differentiates modular hardware platforms through unbundled procurement models in Singapore and Sydney. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, EU regulatory filings, and customs trade data for containerized infrastructure imports. Data center engineering directors, thermal design specialists, and procurement leads at telecommunications providers provided operational validation. Facility operators in Frankfurt, Tokyo, and Mumbai contributed deployment economics. SEC filings from integrated infrastructure suppliers and METI certification databases furnished secondary triangulation. Bottom-up unit economics and top-down market sizing were cross-referenced for convergence.
Segmentation dimensions modeled include deployment type, solution configuration, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derive from installed base growth rates, replacement cycles, and penetration assumptions for edge versus core deployment. Forecast inputs incorporate PLI scheme subsidy trajectories, copper price volatility bands, and 5G base station buildout schedules.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale edge expansion, stable commodity input costs, or unaltered efficiency code stringency would require recalibration. Practitioners should keep alternative scenarios live as sovereign cloud mandates and liquid cooling technology maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Dedicated Server Hosting Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
United States Data Center Server Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
Russia Data Center Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Mexico Data Center Rack Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Germany Data Center Physical Security Market