
 Automated Cell Block Systems Market | 2026-2036
Automated Cell Block Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Cell Block Systems Market Outlook
A capital-intensity divergence between large instrument manufacturers and specialized histopathology firms is rotating competitive dynamics toward platform ecosystems versus point solutions. Thermo Fisher Scientific leverages its life sciences instrumentation breadth to bundle automated cell block systems with adjacent sample preparation workflows. Danaher Corporation anchors its position through Leica Biosystems, sustaining diagnostic pathology channel control across hospital laboratories. Sakura Finetek competes on tissue-processing specialization, dominating installed bases in anatomical pathology departments.
Automated cell block systems are electromechanical platforms that fix, embed, and section cellular specimens into paraffin blocks with micron-level precision for histological analysis. These instruments typically process 50–200 samples per run, replacing manual embedding methods that introduce sectioning artifacts and inter-operator variability. Closed systems command the highest average selling prices due to contained reagent handling and biosafety containment features that appeal to high-throughput clinical laboratories. Microfluidics-enabled platforms represent the fastest-growing technology segment, as miniaturized fluidic channels reduce reagent consumption and enable single-cell resolution for genetic testing applications. Robotics integration is maturing in pharmaceutical company settings, where automated cell block systems feed directly into digital slide scanners for compound screening pipelines.
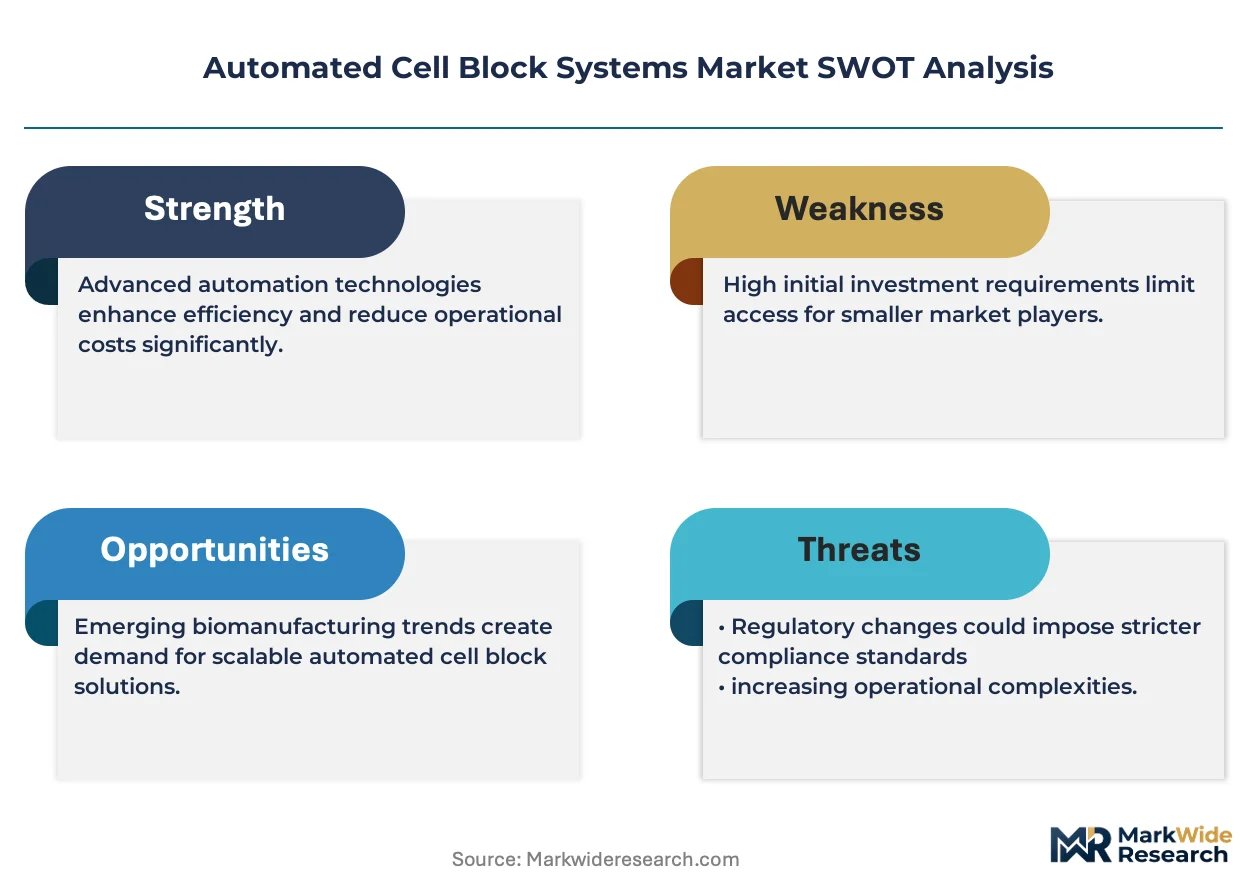
FDA 510(k) clearance requirements and EU MDR technical documentation obligations are extending product development timelines and favoring established manufacturers with regulatory affairs infrastructure. ISO 15189 accreditation standards for medical laboratories are shaping instrument validation protocols and service contract structures. Pathology departments must evaluate whether modular system architectures or fully integrated platforms align with their biobanking and diagnostics volume trajectories as reimbursement shifts toward outcome-based care models.
Market Dynamics
Histopathology laboratories face mounting pressure from FDA 510(k) clearance timelines and EU MDR technical documentation burdens that favor manufacturers with established regulatory infrastructure over emerging entrants.
Growth Catalysts
- EU MDR conformity pathways:The 2017 Medical Device Regulation mandates stricter clinical evidence for in vitro diagnostic devices, compelling laboratories to upgrade from manual to validated automated platforms that demonstrate reproducible micron-level precision.
- Digital pathology infrastructure expansion:Hospital systems in Germany, Japan, and the United States are deploying automated cell block systems as feedstock for whole-slide imaging pipelines, creating demand concentration in precision medicine corridors.
- Microfluidics miniaturization:Single-cell resolution capabilities enable genetic testing workflows that manual embedding cannot replicate, opening clinical applications in oncology biobanking and companion diagnostic development.
Market Restraints
- Reagent supply concentration:Proprietary consumables for closed-system architectures lock laboratories into single-source dependencies, with formulation control resting with a handful of histopathology-specialized chemical suppliers.
- Capital intensity barriers:High-throughput platforms require dedicated biosafety containment infrastructure and HVAC modifications that community hospital laboratories cannot finance without consolidated procurement networks.
- FDA 510(k) timeline extension:Predicate device requirements for novel microfluidics-enabled systems stretch validation periods, freezing smaller manufacturers out of commercialization pathways.
Strategic Opportunities
- Modular system architectures:Biobanking facilities require scalable platforms that expand from fifty-sample runs to two-hundred-sample capacities without full instrument replacement, favoring vendors with upgradeable hardware ecosystems.
- Pharmaceutical compound screening:Robotics integration that feeds directly into digital slide scanners creates automated pipelines for toxicology studies, with contract research organizations representing an underpenetrated buyer segment.
- ISO 15189 accreditation tailwinds:Medical laboratory quality standards are mandating instrument validation protocols that automated systems satisfy more readily than manual methods, accelerating replacement cycles in accredited facilities.
Industry Challenges
- Histotechnologist workforce scarcity:Specialized technicians capable of troubleshooting electromechanical embedding platforms and interpreting sectioning artifacts are concentrated in academic medical centers, leaving regional hospitals dependent on vendor field service.
- Legacy LIS integration friction:Automated cell block systems must interface with laboratory information systems that lack standardized data exchange protocols, forcing customized middleware development that delays go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Cell Block Systems Market |
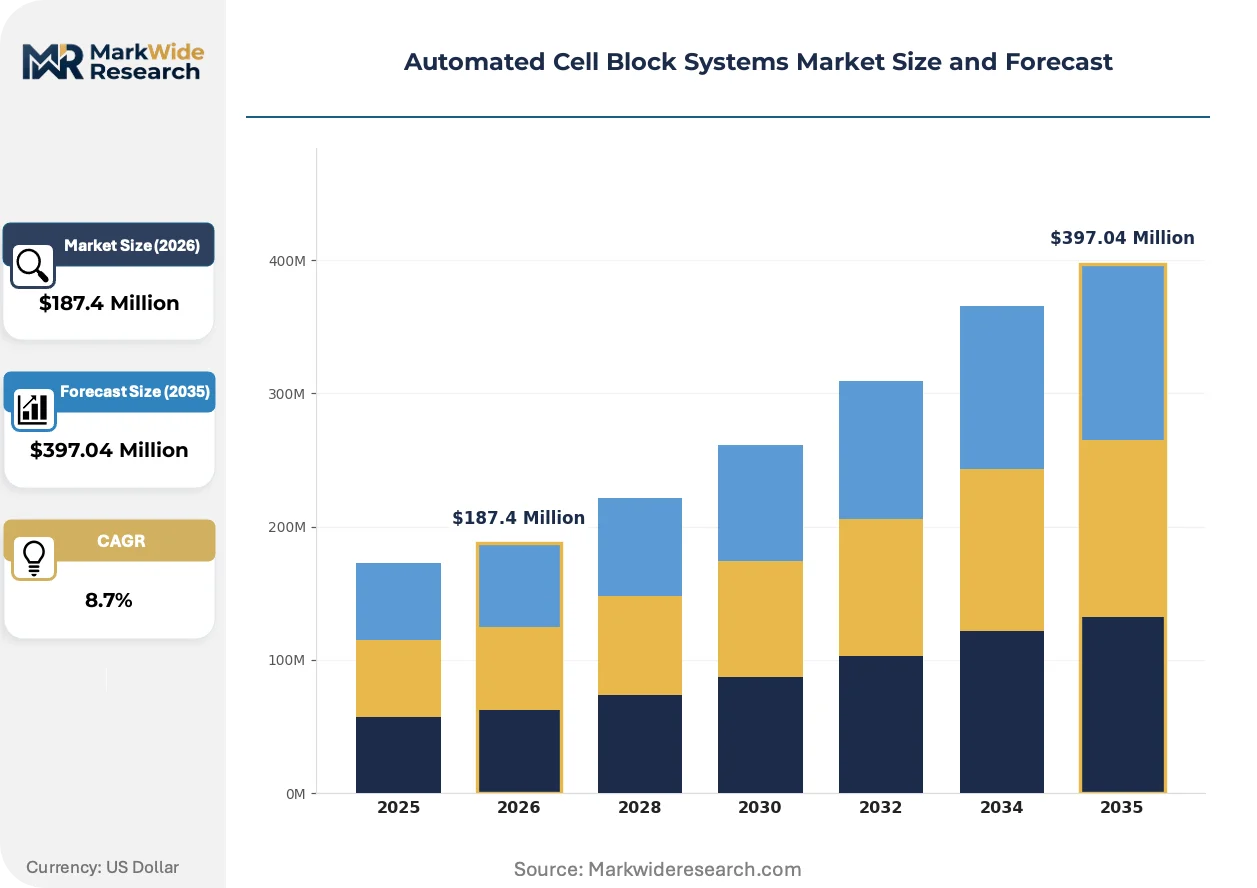
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed System, Open System, Modular System, Integrated System End User: Research Laboratories, Pharmaceutical Companies, Clinical Laboratories, Forensic Institutions Technology: HTP, Microfluidics, Automation Software, Robotics Application: Drug Discovery, Diagnostics, Biobanking, Genetic Testing |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Becton Dickinson and Company, Sakura Finetek, Agilent Technologies, Roche Diagnostics, Siemens Healthineers, Leica Biosystems, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Cell Block Systems Market Strategic Shifts
Platform architectures are fragmenting between closed-system precision and open-system flexibility, with buyers weighing biosafety containment against reagent cost control in their technology selections.
Microfluidics-enabled cell block preparation is decomposing the traditional embedding workflow into discrete, miniaturized fluidic steps that reduce paraffin consumption and enable single-cell isolation. Academic medical centers in the United States and Japan are piloting these platforms for rare-cell oncology applications. The technology is decomposing established instrument categories by collapsing fixation, embedding, and sectioning into continuous-flow processes that eliminate batch-processing constraints.
EU MDR technical documentation obligations now require clinical performance studies for automated tissue-processing devices that previously qualified under self-certification routes. Manufacturers must submit post-market surveillance plans and periodic safety update reports that extend product development cycles by eighteen to thirty-six months. High-throughput clinical laboratories in Germany and France are prioritizing vendors with notified body relationships and established quality management systems.
Service contract unbundling is separating preventive maintenance from reagent supply agreements, allowing pathology departments to negotiate hardware coverage independently of consumable pricing. Hospital procurement committees are demanding line-item transparency that vendor ecosystems historically resisted. This restructuring is most visible in United States health systems where group purchasing organizations are consolidating automated pathology instrument acquisitions across multi-hospital networks.
Automated Cell Block Systems Market Segmentation
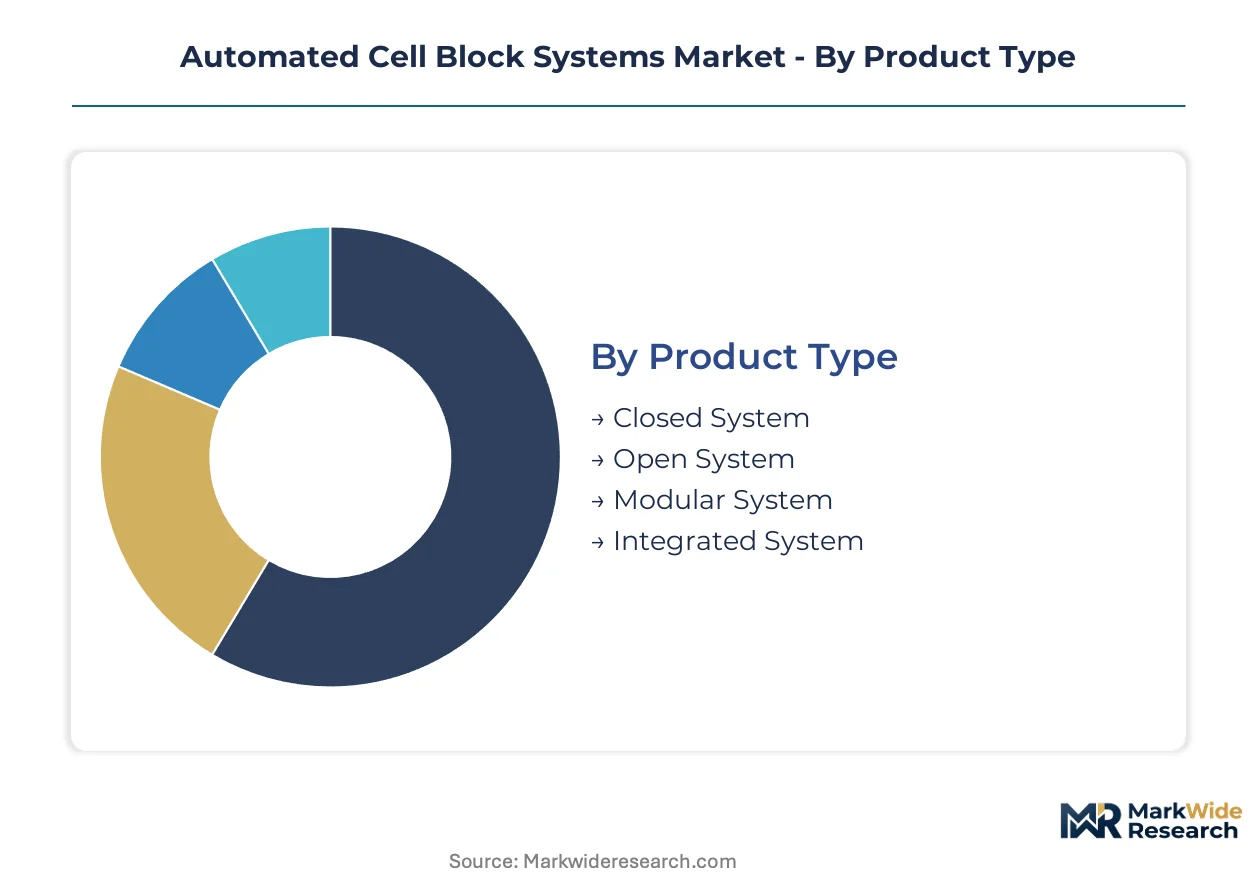
Automated cell block systems fragment across four interlocking dimensions that determine procurement economics and technology roadmaps. Product architecture choices lock laboratories into reagent ecosystems, while end-user scale dictates throughput requirements and regulatory validation intensity.
Product Type:
Margin pools concentrate in closed-system architectures where proprietary consumables generate recurring revenue streams and biosafety containment commands premium pricing.
- Closed System:Fully contained platforms with integrated reagent handling and biosafety enclosures prevent cross-contamination in high-throughput clinical settings. Demand clusters in United States academic medical centers where FDA 510(k) validation and CAP accreditation requirements favor validated, reproducible workflows over manual alternatives.
- Modular System:Scalable hardware ecosystems allow biobanking facilities to expand from fifty-sample to two-hundred-sample capacities through field upgrades rather than full instrument replacement. Germany's precision medicine infrastructure expansion is driving procurement of these upgradeable platforms.
- Open System:Flexible architectures permit third-party reagent sourcing and custom protocol development, appealing to research laboratories with specialized fixation requirements.
- Integrated System:Fully automated pipelines connecting cell block preparation directly to digital slide scanning, primarily deployed in pharmaceutical toxicology screening operations.
Closed System holds installed capacity. Modular System is rotating up the share rankings.
End User:
Volume concentration follows diagnostic reimbursement scale, with clinical laboratories processing the highest sample throughput per instrument.
- Clinical Laboratories:Hospital-based pathology departments and reference laboratories process 50–200 specimens per run under ISO 15189 quality management systems. Japan's expanding national health insurance coverage for molecular diagnostics is accelerating replacement of manual embedding methods in accredited facilities.
- Pharmaceutical Companies:Contract research organizations and in-house toxicology groups deploy robotics-integrated platforms for compound screening pipelines. United States biopharma clusters in Boston and San Francisco represent concentrated demand for high-throughput, GMP-compliant sample preparation.
- Research Laboratories:Academic medical centers pilot microfluidics-enabled platforms for rare-cell isolation and single-cell genomics applications.
- Forensic Institutions:Crime laboratories require chain-of-custody documentation and evidentiary-grade sectioning precision for DNA extraction from cellular material.
Clinical Laboratories dominate instrument placements. Pharmaceutical Companies are gaining share fastest as companion diagnostic development expands.
Technology:
Technology selection determines reagent consumption economics and resolution capabilities, with microfluidics miniaturization opening clinical applications unavailable to conventional batch processing.
- Microfluidics:Miniaturized fluidic channels reduce paraffin consumption and enable single-cell resolution for genetic testing workflows. Japan's PMDA is evaluating these platforms for oncology companion diagnostic applications where manual embedding cannot isolate rare circulating tumor cells.
- Robotics:Automated material handling feeds cell blocks directly into digital slide scanners, eliminating manual transfer steps in pharmaceutical high-content screening operations.
- HTP:High-throughput parallel processing architectures maximize sample throughput for clinical laboratories with standardized diagnostic menus.
- Automation Software:Protocol management and LIS integration middleware enables remote monitoring and batch scheduling across distributed laboratory networks.
HTP maintains the largest installed base. Microfluidics shows the steepest expansion trajectory as single-cell clinical applications mature.
Application:
Application focus determines regulatory pathway complexity and reimbursement environment, with diagnostics commanding the most stringent quality system requirements.
- Diagnostics:Histopathological analysis for cancer staging and infectious disease identification requires micron-level sectioning precision under CLIA or ISO 15189 oversight. United States hospital systems consolidating pathology services across multi-hospital networks are standardizing on automated platforms to reduce inter-operator variability.
- Biobanking:Specimen preservation for longitudinal research and precision medicine initiatives demands reproducible embedding protocols that maintain nucleic acid integrity. Germany's national biobanking infrastructure investments are driving platform standardization.
- Drug Discovery:Toxicology studies and compound efficacy screening utilize high-throughput cell block preparation for tissue microarray construction.
- Genetic Testing:Molecular pathology workflows including FISH and next-generation sequencing sample preparation require platform compatibility with downstream nucleic acid extraction protocols.
Diagnostics anchors revenue concentration. Biobanking is climbing the fastest as national precision medicine programs expand specimen repository capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States hospitals prioritize closed-system biosafety containment for high-throughput clinical workflows, while German laboratories emphasize modular upgrade paths aligned with EU MDR validation timelines. Japanese facilities concentrate on microfluidics-enabled platforms for companion diagnostic development.
United States
FDA 510(k) clearance pathways and CAP accreditation requirements drive demand for validated automated platforms in academic medical centers. Hospital systems consolidating pathology services across multi-hospital networks standardize on instruments that reduce inter-operator variability. Boston and San Francisco biopharma clusters deploy robotics-integrated systems for toxicology screening pipelines.
Germany
EU MDR technical documentation obligations and national biobanking infrastructure investments accelerate replacement of manual embedding methods. Notified body relationships determine vendor selection as quality management system audits intensify. Heidelberg and Berlin precision medicine corridors concentrate platform deployments for longitudinal specimen repository expansion.
Japan
PMDA evaluations of microfluidics-enabled platforms for oncology companion diagnostics create regulatory tailwinds for single-cell resolution technologies. National health insurance coverage expansion for molecular diagnostics accelerates accredited facility upgrades. Tokyo and Osaka metropolitan hospitals lead instrument placements for rare circulating tumor cell isolation protocols.
United Kingdom
NHS pathology consolidation programs and ISO 15189 accreditation mandates favor automated systems that demonstrate reproducible micron-level precision. London and Cambridge academic medical centers pilot integrated platforms connecting cell block preparation to digital slide scanning. Procurement frameworks emphasize total cost of ownership over capital expenditure minimization.
China
NMPA medical device registration requirements and hospital tier classification systems shape demand for mid-range automated platforms. Shanghai and Beijing tertiary hospitals import closed-system architectures while domestic manufacturers develop localized alternatives. Precision medicine initiatives in the Yangtze River Delta drive biobanking facility construction.
Automated Cell Block Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with life sciences conglomerates leveraging instrumentation breadth against histopathology-focused firms competing on tissue-processing depth. The upper tier bundles automated cell block systems with adjacent sample preparation workflows, while specialists dominate installed bases in anatomical pathology departments. Two strategic archetypes prevail: platform ecosystem builders and point solution optimizers. Competitive moves concentrate on M&A for diagnostic channel control and modular hardware ecosystem expansion.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify the platform ecosystem archetype, anchoring competitive positioning through instrumentation breadth and diagnostic pathology channel relationships respectively. Sakura Finetek occupies a specialist position, representing the tissue-processing depth vector that dominates installed bases in anatomical pathology departments. These three entities collectively illustrate the capital-intensity divergence rotating competitive dynamics toward bundled workflows versus specialized precision.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Becton Dickinson and Company |
| Sakura Finetek |
| Agilent Technologies |
| Roche Diagnostics |
| Siemens Healthineers |
| Leica Biosystems |
| Hologic |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance requirements and EU MDR technical documentation obligations gate both supplier qualification and price differentiation simultaneously, favoring manufacturers with established regulatory affairs infrastructure while compressing margins for emerging entrants lacking predicate device pathways.
Pricing Analysis
Long-term service contracts dominate automated cell block system procurement, bundling preventive maintenance with reagent supply agreements that lock laboratories into multi-year commitments. Three-tier pricing structure across premium closed-system, standard modular, and economy open-system levels reflects biosafety containment certification and throughput capacity. Cost compression in mid-tier modular platforms is intensifying because biobanking facilities demand scalable upgrade paths without full instrument replacement. Community hospital laboratories exhibit highest price sensitivity due to capital intensity barriers, while academic medical centers prioritize validation pedigree over acquisition cost.
Supply Chain Analysis
Proprietary reagent formulation control concentrates in Germany, Japan, and the United States, creating single-source dependencies for closed-system architectures that process 50–200 specimens per run. Precision electromechanical components and medical-grade paraffin formulations anchor upstream input requirements, with biosafety enclosure manufacturing resting on specialized HVAC fabrication capabilities. Tariff exposure on precision instrumentation from German and Japanese suppliers threatens margin stability for North American distributors. Distribution runs through diagnostic pathology channel partners and group purchasing organizations that consolidate multi-hospital network acquisitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Histotechnologist workforce scarcity constrains both operational scaling and field service coverage, creating competitive advantage for vendors with embedded training ecosystems and remote diagnostics capabilities.
For Market Incumbents: Consolidate diagnostic channel control through Leica Biosystems-style pathology department relationships while accelerating modular hardware ecosystem expansion to capture biobanking infrastructure investments. Microfluidics-enabled platform development represents the priority R&D lever against emerging entrants lacking predicate device pathways. Backward integration into proprietary reagent formulation secures consumable revenue streams against open-system competitors. For New Entrants and Emerging Players: Lead with contract research organization penetration for pharmaceutical toxicology screening applications, where robotics-integrated platforms remain underrepresented relative to clinical laboratory saturation. Japan's PMDA evaluation window for companion diagnostic applications offers the most penetrable regulatory entry point. ISO 15189 accreditation tailwinds enable validation-protocol positioning against manual method incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microfluidics-enabled platforms as single-cell resolution capabilities require specialized fabrication infrastructure. Acquisition targets should display established notified body relationships and quality management system maturity. The signal to watch is EU MDR periodic safety update report submission volumes as a proxy for regulatory compliance durability.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Hardware Ecosystem Expansion | Biobanking facilities in Germany demand scalable fifty-to-two-hundred-sample upgrade paths without full replacement. |
| Microfluidics Platform Development | PMDA evaluations in Japan create regulatory tailwinds for single-cell oncology companion diagnostic applications. |
| Reagent Supply Contract Unbundling | United States group purchasing organizations force line-item transparency that vendor ecosystems historically resisted. |
| Robotics Integration for Pharma Pipelines | Boston and San Francisco biopharma clusters deploy automated feedstock for digital slide scanner connectivity. |
| ISO 15189 Accreditation Alignment | Medical laboratory quality standards accelerate replacement cycles in Japan's expanding molecular diagnostics coverage. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across hospital pathology departments, reference laboratory directors, biomedical engineers, and group purchasing organization contract managers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and ISO 15189 accreditation registries. Bottom-up instrument placement counts triangulated against top-down market size estimates derived from reagent consumption patterns and service contract disclosures.
Across the analysis window, volume and value outputs reflect segmentation modeling across product architecture, end-user scale, technology type, and application focus with geographic regulatory cluster differentiation. CAGRs were derived from instrument replacement cycle analysis, precision medicine program expansion rates, and companion diagnostic pipeline maturation. Microfluidics adoption curves and biobanking infrastructure investment trajectories served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EU MDR conformity assessment procedures; material policy shifts would require re-modeling predicate device requirements or notified body capacity constraints. Practitioners should keep alternative scenarios live as PMDA evaluation timelines and national health insurance coverage expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Automated Liquid Handling System Market
Automation
Global Business Process Automation Software Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Digital Process Automation Market
Automation
Marketing Automation Solutions Market
Automation
Universal Process Control Market
Automation
Global Warehouse Execution System Market
Automation
Terminal Automation Systems Market
Automation
Parcel Sorting System Market
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
Global Cloud Automation Market
Automation
Laboratory Benchtop Automation Market
Automation
Global Automated Liquid Handlers Market
Automation
Automation-As-A-Service Market
Automation
Cognitive Process Automation Market
Automation
Elevator Control Market