
 Virtual Augmented and Mixed Reality (VR/AR) Market | 2026-2036
Virtual Augmented and Mixed Reality (VR/AR) Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Augmented and Mixed Reality (VR/AR) Market Insights
Enterprise buyer concentration is repositioning procurement power toward Fortune 500 training divisions and defense contractors. Meta leverages its Quest ecosystem to anchor consumer volume while extending into workplace collaboration tools. Microsoft competes through HoloLens integration with Azure cloud services for industrial clients. Sony specializes in premium VR entertainment hardware, dominating console-tethered experiences through PlayStation VR.
Virtual augmented and mixed reality encompasses immersive computing systems that overlay or replace visual fields using stereoscopic displays with refresh rates exceeding 90 Hz, inside-out tracking cameras, and spatial audio arrays for industrial simulation, medical visualization, and interactive entertainment. Headsets capture the largest value pool among device types due to compute-intensive requirements and premium pricing, while smart glasses represent the fastest-growing category as optical waveguide technology matures for lightweight enterprise deployment. Gaming applications maintain volume leadership among consumer segments, though healthcare applications command superior margins through FDA-validated surgical planning and diagnostic imaging workflows.
FCC equipment authorization rules govern radio-frequency emissions for VR headsets sold in the United States, while the EU AI Act imposes conformity assessments on biometric inference systems including gaze tracking and emotion recognition. China's MIIT enforces GB standards for near-eye display safety that manufacturers must satisfy for market access. Stakeholders must monitor evolving interoperability mandates between competing spatial computing platforms as regulatory fragmentation risks locking content ecosystems into single-vendor hardware dependencies.
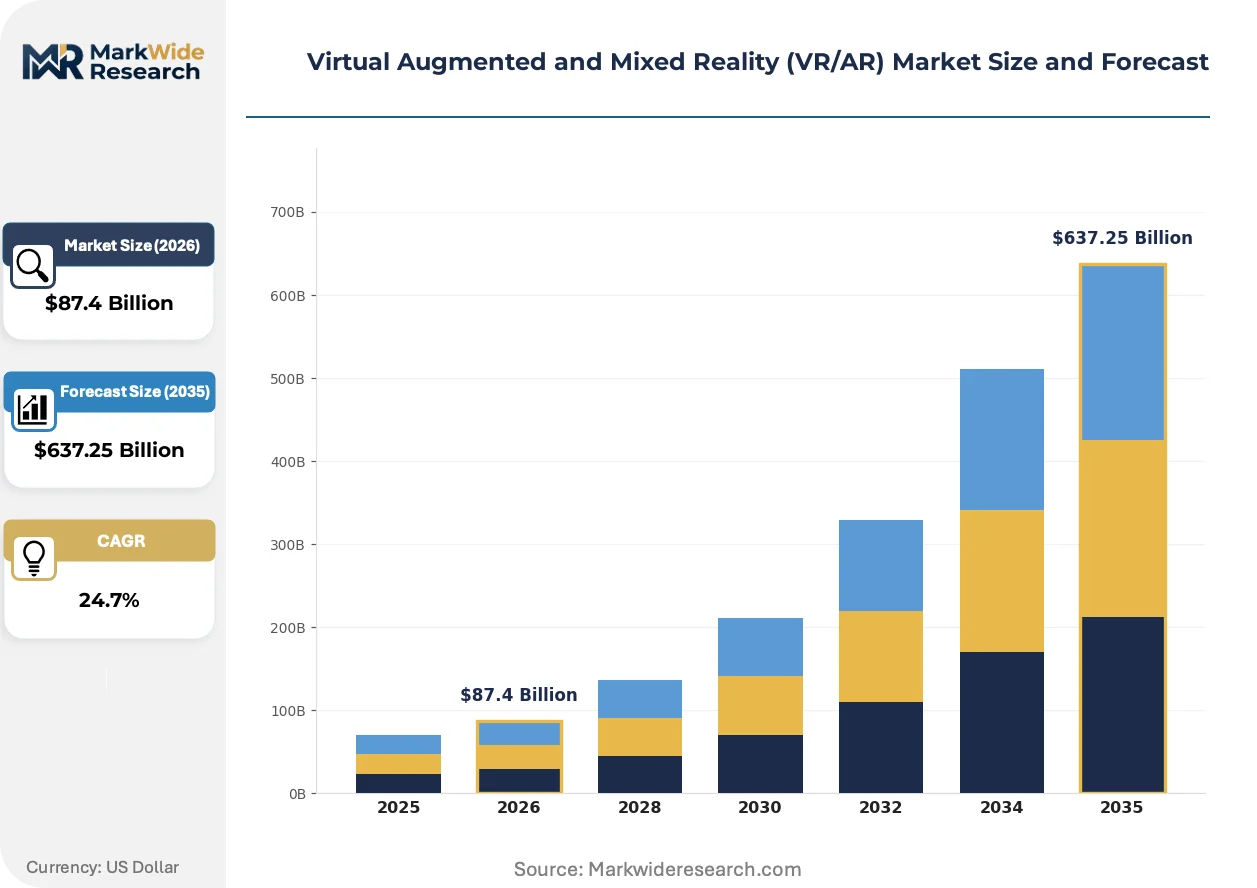
Market Dynamics
Enterprise training procurement at Boeing and Walmart is consolidating headset demand into multi-year fleet contracts, compressing vendor margins while locking in volume commitments that reshape supplier prioritization toward B2B service architectures.
Growth Catalysts
- EU AI Act biometric compliance:European vendors redesigning gaze-tracking data pipelines are creating certified hardware tiers that command premium positioning in privacy-sensitive healthcare and defense verticals.
- Display panel demand concentration:China and South Korea now absorb the majority of micro-OLED and pancake lens output, attracting module assembly investment that shortens supply chains for headset manufacturers.
- Industrial simulation:FAA-certified flight training modules and OSHA-aligned hazard rehearsal systems are embedding VR into mandatory workforce credentialing programs across aviation and heavy manufacturing.
Market Restraints
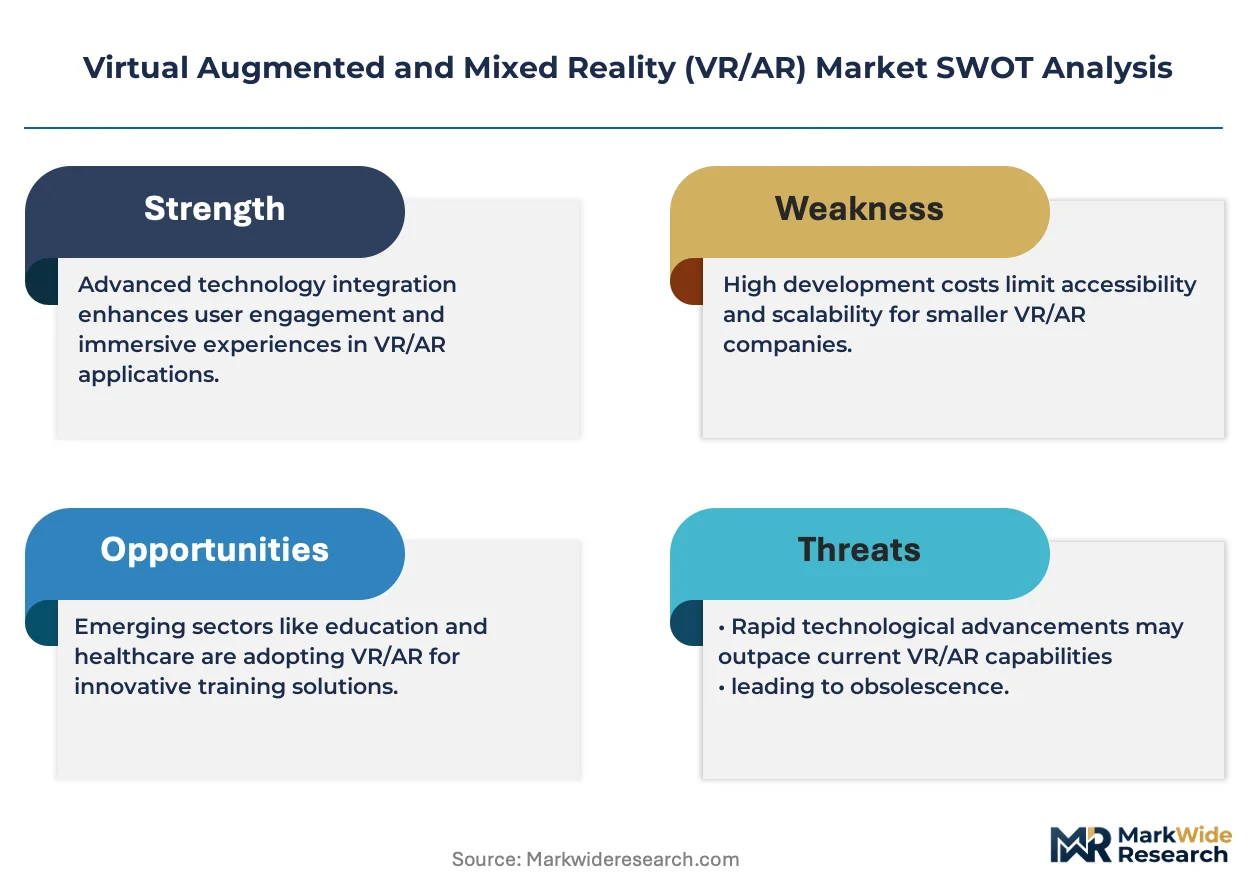
- Input cost volatility:Rare-earth magnet prices for compact haptic actuators fluctuate with Chinese export quotas, squeezing margins on mid-tier consumer headsets.
- Supply concentration risk:Single-source dependency on Taiwanese semiconductor foundries for custom ASICs used in inside-out tracking creates vulnerability to geopolitical disruption.
- Technical limitation:Optical waveguide yield rates below 40% constrain smart glass production volumes, delaying lightweight enterprise deployment timelines.
Strategic Opportunities
- Underpenetrated surgical planning:FDA 510(k) pathways for diagnostic imaging overlays remain sparsely utilized, creating first-mover advantage for mixed reality visualization in orthopedic and neurosurgical workflows.
- Technology convergence:Integration of generative AI with spatial computing enables real-time environment reconstruction, opening architectural walkthrough and remote assistance applications.
- Distribution innovation:Direct-to-enterprise subscription models bypassing retail channels are capturing training divisions seeking turnkey hardware-software-service bundles with predictable refresh cycles.
Industry Challenges
- Specialized optics talent scarcity:Waveguide design and freeform lens engineering expertise concentrates in a handful of research clusters, inflating compensation costs and extending product development timelines.
- Certification timeline compression:Simultaneous FCC equipment authorization and EU AI Act conformity assessments for biometric-enabled headsets require parallel regulatory teams, increasing compliance overhead.
- Legacy system integration friction:Industrial clients demand seamless data exchange between immersive training platforms and existing SCADA or MES infrastructure, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Augmented and Mixed Reality (VR/AR) Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $637.25 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Headsets, Smart Glasses, Mobile Devices, Wearables Application: Gaming, Training, Healthcare, Education End User: Enterprises, Consumers, Healthcare Professionals, Educators Technology: Optical, Sensor Fusion, Computer Vision, Haptic Feedback |
| Companies Covered | Meta, Apple, Microsoft, Google, Sony, HTC, Samsung Electronics, Nvidia, Pico, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Augmented and Mixed Reality (VR/AR) Market Trends and Innovations
Spatial computing architectures are fragmenting into specialized stacks optimized for distinct latency, fidelity, and mobility requirements rather than converging on universal platforms.
Edge inference chips embedded directly into headset frames are decentralizing compute loads previously routed to tethered PCs or cloud instances. Industrial training programs at energy facilities and logistics hubs are adopting these standalone configurations to eliminate cable hazards and network dependency. This architecture is decentralizing hardware procurement decisions away from IT departments toward operational safety managers who control training budgets.
The EU AI Act's risk-based classification system is mandating conformity assessments for biometric inference systems including gaze tracking and emotion recognition. Hardware vendors must now maintain technical documentation and human oversight protocols for high-risk applications. Medical device manufacturers seeking CE marking for surgical planning tools face the steepest compliance burden, driving partnerships with specialized notified bodies.
Buyer concentration among Fortune 500 training divisions is compressing vendor sales cycles from speculative pilot programs to structured procurement frameworks. Systems integrators and specialized VARs are displacing direct OEM relationships as the primary channel for enterprise deployment. This pattern is most visible in North American defense and aviation sectors where security-cleared intermediaries control facility access.
Virtual Augmented and Mixed Reality (VR/AR) Market Segmentation
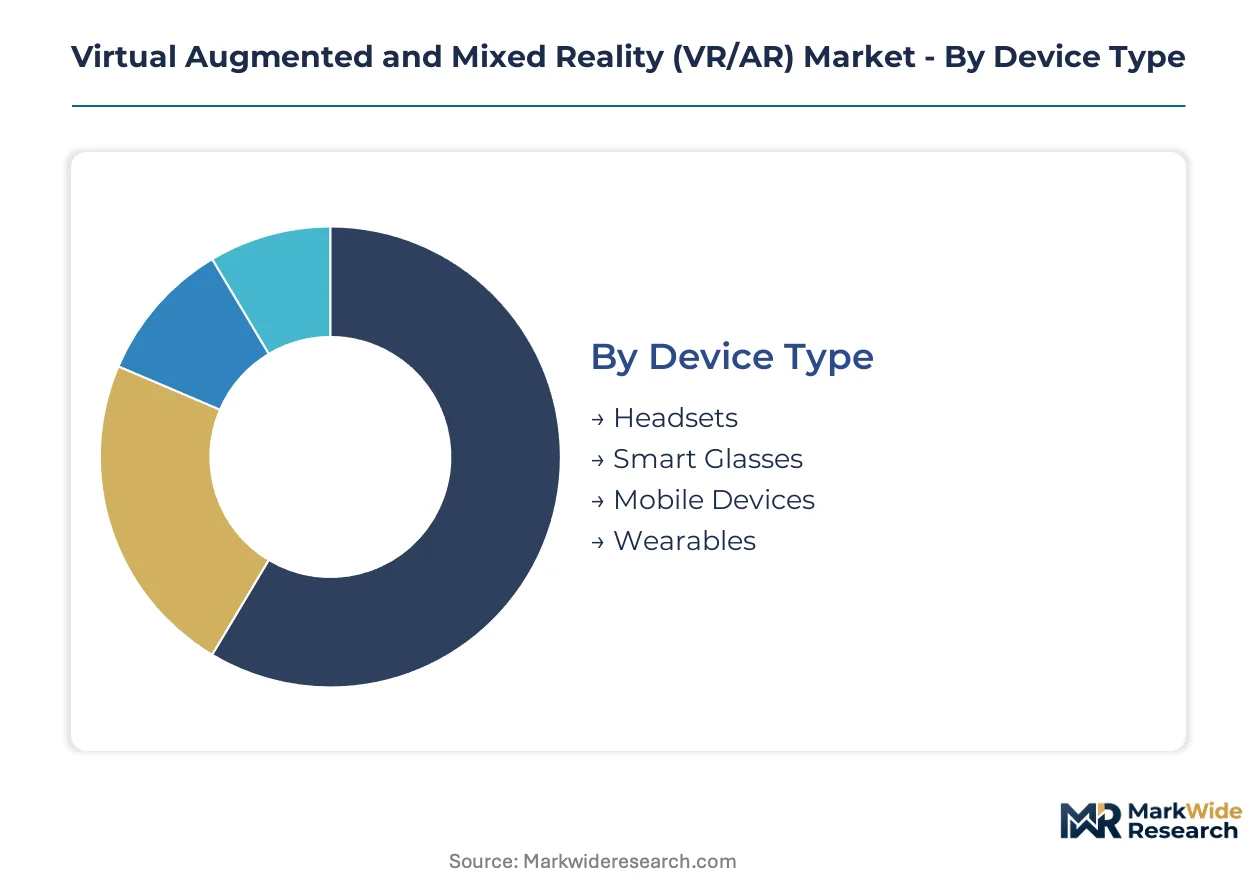
Device architecture and application maturity create divergent margin profiles across the VR/AR landscape. Supply chain positioning and regulatory exposure vary sharply by segment, reshaping vendor prioritization and investment allocation.
Device Type:
Module assembly capacity clusters in China and South Korea, concentrating procurement leverage for display panels and optical engines among a handful of vertically integrated suppliers.
- Headsets:Stereoscopic displays with 90+ Hz refresh rates and inside-out tracking cameras dominate compute-intensive applications. Boeing and Walmart training programs anchor fleet procurement volumes, compressing margins through multi-year contracts while locking in supplier prioritization.
- Smart Glasses:Optical waveguide technology enables lightweight enterprise deployment with sub-40% manufacturing yield rates currently constraining volumes. Privacy-sensitive healthcare and defense verticals in Europe absorb certified hardware tiers redesigned for EU AI Act biometric compliance.
- Mobile Devices:Smartphone-tethered viewers leverage existing compute infrastructure for cost-sensitive consumer entry points.
- Wearables:Haptic-enabled garments and accessories extend immersion beyond visual fields for specialized industrial simulation.
Headsets absorb the bulk of installed capacity; smart glasses are expanding most quickly.
Application:
Margin stratification follows certification intensity, with FDA-validated workflows commanding premium positioning against volume-driven entertainment segments.
- Gaming:Console-tethered experiences through PlayStation VR and standalone Quest ecosystems drive consumer volume leadership. Meta's ecosystem anchors mass-market penetration while Sony specializes in premium hardware for enthusiast segments.
- Healthcare:FDA 510(k) pathways for surgical planning and diagnostic imaging overlays command superior margins through validated orthopedic and neurosurgical workflows. CE marking requirements under EU AI Act impose steepest compliance burden on medical device manufacturers.
- Training:FAA-certified flight modules and OSHA-aligned hazard rehearsal systems embed VR into mandatory credentialing across aviation and heavy manufacturing.
- Education:Institutional procurement cycles and budget constraints limit near-term penetration despite demonstrated engagement benefits.
Gaming captures the greatest volume throughput; healthcare delivers the steepest margin expansion.
End User:
Procurement authority is decentralizing from IT departments toward operational safety managers and training division heads controlling dedicated budgets.
- Enterprises:Fortune 500 training divisions consolidate demand into structured procurement frameworks, displacing speculative pilot programs. Systems integrators and security-cleared VARs control facility access in North American defense and aviation sectors.
- Consumers:Direct-to-consumer channels face margin pressure from mid-tier headset price competition, with rare-earth magnet cost volatility squeezing profitability.
- Healthcare Professionals:Surgeon-led demand for diagnostic visualization tools drives specialized hardware-software bundles with predictable refresh cycles.
- Educators:Institutional purchasing committees prioritize interoperability with existing learning management infrastructure.
Enterprises dominate committed procurement volumes; healthcare professionals are climbing the fastest as a customer class.
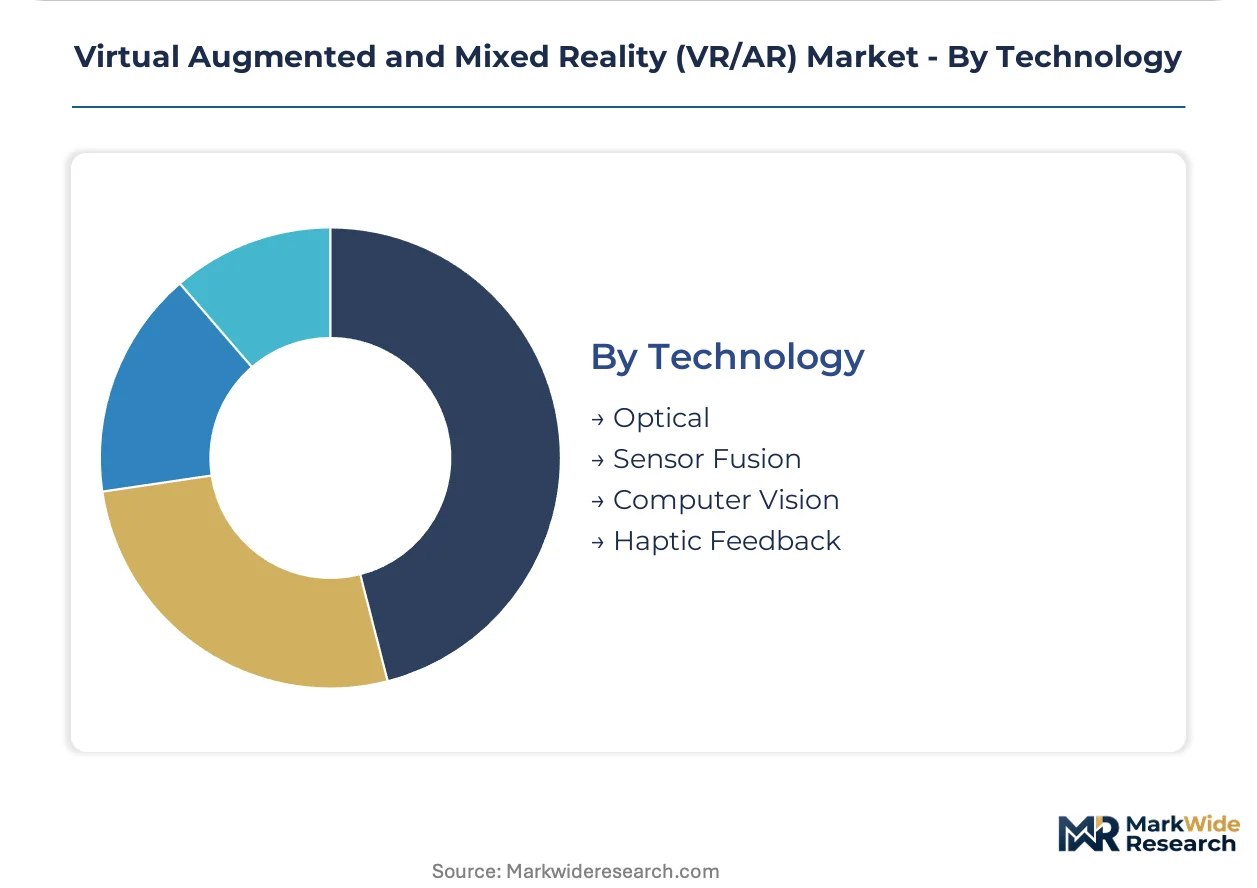
Technology:
Intellectual property concentration in waveguide design and freeform lens engineering inflates compensation costs and extends development timelines for specialized optics talent.
- Optical:Pancake lens and micro-OLED display architectures determine form factor and visual fidelity. Chinese and South Korean foundries absorb majority of panel output, shortening supply chains for assembly partners.
- Sensor Fusion:Inside-out tracking ASICs face single-source dependency on Taiwanese semiconductor foundries, creating geopolitical vulnerability for headset manufacturers.
- Computer Vision:Edge inference chips embedded directly into headset frames decentralize compute loads previously routed to tethered PCs or cloud instances.
- Haptic Feedback:Compact actuators dependent on rare-earth magnets face price volatility from Chinese export quota fluctuations.
Optical technology anchors the greatest installed base; computer vision is gaining share fastest through standalone training deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise training procurement concentrates demand in the United States, Germany, China, South Korea, and Japan, where defense contractors and Fortune 500 manufacturers anchor multi-year fleet contracts for immersive hardware.
United States
Boeing's flight training modules and Walmart's distribution center simulations drive enterprise headset volumes. FCC equipment authorization rules govern radio-frequency emissions for devices sold domestically. Seattle and Austin host clusters of systems integrators serving North American defense and aviation sectors.
Germany
Industrial automation firms embed mixed reality into manufacturing workflows for precision assembly and quality control. EU AI Act conformity assessments apply to biometric inference systems including gaze tracking. Munich and Stuttgart concentrate optical engineering talent for waveguide design and freeform lens development.
China
Domestic display panel demand absorbs the majority of micro-OLED and pancake lens output from local foundries. MIIT enforces GB standards for near-eye display safety as a condition of market access. Shenzhen and Beijing anchor vertically integrated supply chains spanning module assembly to finished headset production.
South Korea
Electronics conglomerates leverage captive display technology for premium headset development targeting enterprise and consumer segments. MFDS regulates medical device software incorporating diagnostic imaging overlays. Seoul Capital Area concentrates semiconductor packaging capacity for edge inference chips embedded in standalone training configurations.
Japan
Precision optics manufacturers supply pancake lens architectures to global headset assemblers. METI oversees standards for industrial simulation equipment used in workforce credentialing programs. Nagoya and Osaka host specialized clusters for haptic actuator component production.
Virtual Augmented and Mixed Reality (VR/AR) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue lightweight enterprise smart glasses and surgical visualization tools. The vendor base stratifies across three tiers: ecosystem-anchored platform holders, cloud-integrated industrial specialists, and component-focused hardware fabricators. Dominant competitive moves include strategic partnerships with systems integrators and backward integration into display panel sourcing.
Within the ecosystem-anchored tier, Meta and Apple represent contrasting approaches to consumer volume versus premium hardware positioning. Microsoft occupies a position among cloud-integrated industrial specialists, exemplifying the Azure-aligned service architecture favored by Fortune 500 training divisions. Sony anchors the console-tethered entertainment segment, sitting within a specialization tier that trades ecosystem breadth for fidelity-focused enthusiast markets.
| Leading Market Players |
|---|
| Meta |
| Apple |
| Microsoft |
| Sony |
| HTC |
| Samsung Electronics |
| Nvidia |
| Pico |
| Others |
Pricing and Supply Chain Analysis
Optical waveguide manufacturing transitions from research-scale prototyping to pilot production lines are compressing unit economics for smart glasses while simultaneously redistributing procurement leverage toward Chinese and South Korean display panel foundries. This dual shift tightens margins on mid-tier consumer headsets even as premium enterprise tiers capture certification-driven price premiums.
Pricing Analysis
Volume leadership in gaming-oriented headsets runs on thin margins, while FDA-validated surgical planning tools and EU AI Act-certified biometric hardware tiers command substantial premiums. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in mid-tier consumer segments is intensifying because rare-earth magnet price volatility squeezes haptic actuator margins. Enterprise training divisions show least price sensitivity due to predictable refresh cycle budgeting, while direct-to-consumer channels face acute sensitivity from price-competitive standalone headset offerings.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor foundries for custom inside-out tracking ASICs, creating geopolitical exposure for headset manufacturers dependent on these components. Module assembly capacity clusters in China, South Korea, and Japan, drawing from micro-OLED substrates, pancake lens optics, and rare-earth magnet feedstocks. Tariff exposure on Chinese-sourced display components threatens margin stability for vendors without diversified sourcing. Distribution runs through systems integrators and security-cleared VARs in North American defense and aviation sectors, bypassing direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VR/AR market sits in a technology-transition phase where edge inference chips embedded in headset frames are replacing tethered PC and cloud-dependent architectures, decentralizing procurement authority toward operational safety managers.
For Market Incumbents: Lock in multi-year fleet contracts with Fortune 500 training divisions before emerging entrants capture share through direct-to-enterprise subscription models. Prioritize backward integration into micro-OLED panel sourcing to defend against Chinese and South Korean foundry concentration. Invest in parallel regulatory teams to compress simultaneous FCC equipment authorization and EU AI Act conformity timelines.
For New Entrants and Emerging Players: Begin with FDA 510(k) surgical planning pathways in orthopedic and neurosurgical workflows, where incumbent penetration remains sparse and surgeon-led demand drives predictable refresh cycles. Target healthcare professionals as the fastest-climbing customer class through specialized hardware-software bundles. Pursue partnerships with notified bodies specializing in CE marking for medical device manufacturers.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by cloud-integrated industrial specialists seeking Azure-aligned service architectures for Fortune 500 training divisions. Long-term viability hinges on capabilities in waveguide design and freeform lens engineering, where talent scarcity inflates compensation costs and extends development timelines. Watch optical waveguide yield rate improvements as the inflection signal for smart glass volume scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure cloud alignment captures Boeing and Walmart training procurement through bundled hardware-software-service offerings. |
| Acquisition of Specialist Firm | Waveguide design boutiques in Munich and Stuttgart clusters address optical engineering talent scarcity constraining smart glass volumes. |
| Regulatory Certification Pathway | Parallel FCC and EU AI Act conformity teams compress timeline risks for biometric-enabled headset launches. |
| Backward Integration | In-house micro-OLED panel production reduces dependency on Chinese and South Korean foundry concentration. |
| Geographic Expansion | Seoul Capital Area semiconductor packaging investment supports edge inference chip capacity for standalone training deployments. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and FDA 510(k) submission databases formed the secondary backbone, cross-referenced with primary interviews across headset engineering directors, Fortune 500 training division procurement leads, regulatory affairs specialists at notified bodies, and biomedical engineers at hospital systems. Bottom-up triangulation against top-down trade flow analysis validated shipment estimates for display panel and optical engine module assembly.
Historical trendline analysis of refresh rate specifications, inside-out tracking camera deployments, and spatial audio array integrations informed the projection framework across device type, application maturity, end-user procurement authority, and optical technology segmentation. CAGRs were derived from elasticity modeling of enterprise training budget allocations and consumer entertainment spending patterns. Edge inference chip adoption curves and optical waveguide yield improvement trajectories served as technology-specific forecast inputs.
Underlying measurement precision varies by segment; FDA-validated healthcare applications and FCC-authorized enterprise headsets carry tighter precision than speculative consumer smart glass volumes. Forecasts reflect assumptions around EU AI Act implementation timelines, Chinese export quota stability for rare-earth magnets, and Taiwanese foundry capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Internet of Senses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality (XR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market