
 Global Smart Vending Machines Market | 2026-2036
Global Smart Vending Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Vending Machines Market Outlook
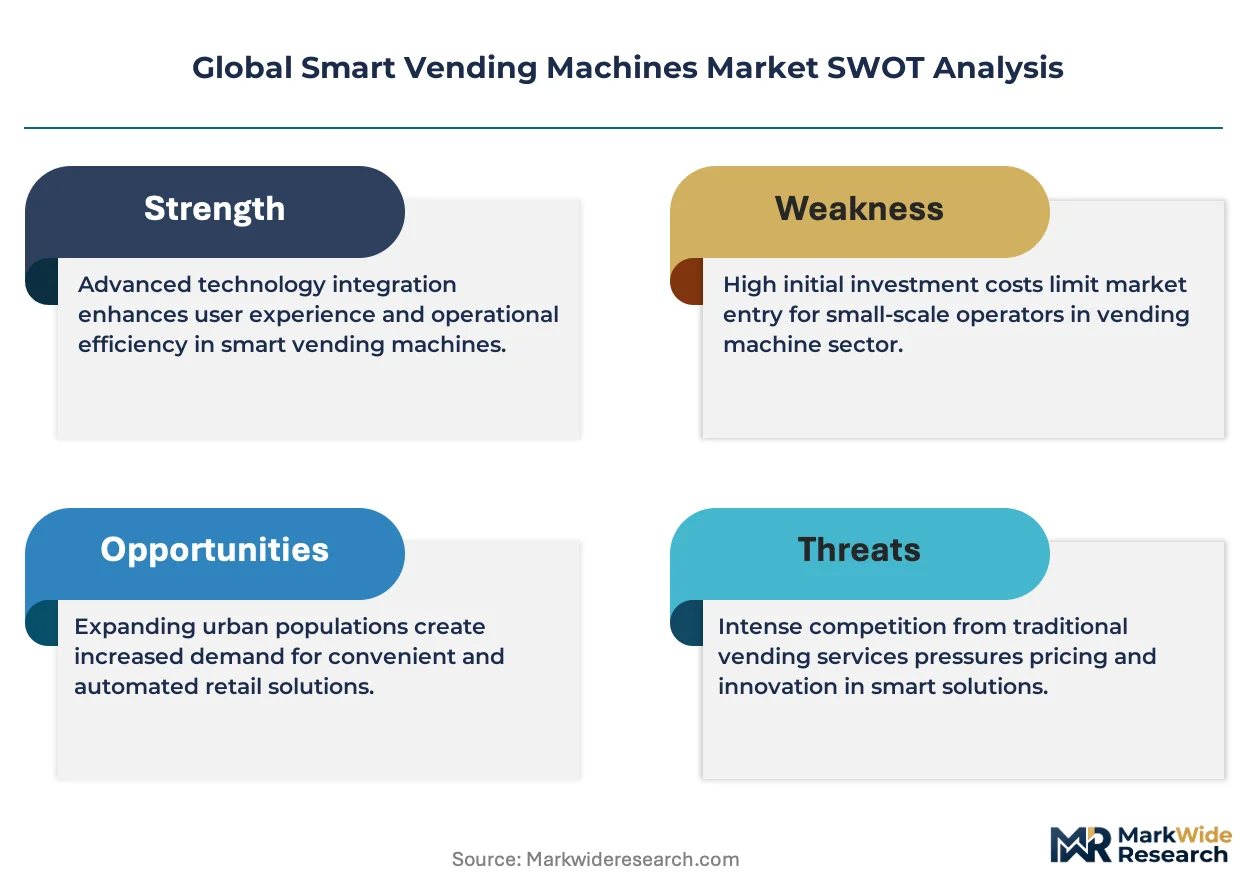
A shortage of embedded systems engineers with IoT firmware expertise is redrawing competitive boundaries across the smart vending landscape. Fuji Electric leverages its semiconductor heritage to sustain in-house production of payment modules and refrigeration controllers. Sanden Holdings Corporation anchors its position through captive supply of compressor technology for beverage dispensers. Crane Merchandising Systems competes on software stack depth, offering cloud-based inventory management that reduces operator downtime.
Smart vending machines integrate sensors, payment terminals, and networked telemetry into self-service retail units designed for 24-hour unattended operation. These systems typically employ 150-300W energy budgets with variable refrigeration loads and support multi-protocol cashless acceptance including NFC, QR, and biometric verification. Beverage dispensers dominate installed base value owing to higher unit costs and recurring consumable revenue, while healthy food units represent the fastest-expanding product category as workplace wellness programs reshape office space procurement. IoT integration and touchless interaction together command premium positioning across technology tiers, though cloud-based management delivers the stickiest operator retention through predictive maintenance alerts.
FDA guidelines on food-contact surfaces and temperature logging shape sanitary design requirements for US-deployed units, while CE marking and the EU F-Gas Regulation constrain refrigerant selection and energy efficiency benchmarks across European installations. Japan's METI enforces stringent standby power limits that filter out lower-efficiency hardware from its transit-heavy market. Stakeholders must weigh refrigerant transition timelines against IoT platform refresh cycles when allocating capital across geographic portfolios.
Market Dynamics
A shortage of embedded systems engineers with IoT firmware expertise is redrawing competitive boundaries across the smart vending landscape, forcing manufacturers to choose between in-house capability building and strategic outsourcing partnerships.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-GWP refrigerants accelerate equipment refresh cycles across European transit hubs and airports, creating replacement demand for compliant refrigeration systems.
- Workplace wellness programs:Corporate procurement departments prioritize healthy food vending units in office towers, expanding the addressable market beyond traditional beverage-centric deployments.
- Touchless payment convergence:NFC and biometric verification integration reduces transaction friction in Japan's high-density urban corridors where METI standby power limits already filter hardware selection.
Market Restraints
- Refrigerant transition timelines:The EU F-Gas Regulation compresses R-134a phase-out schedules, forcing operators to retire functional units before full depreciation.
- Compressor supply concentration:Captive production of variable-speed compressors concentrates among Japanese and German industrial groups, limiting second-source options for mid-tier assemblers.
- Embedded firmware scarcity:The shallow talent pool for ARM-based IoT development constrains feature velocity across payment module and telemetry controller roadmaps.
Strategic Opportunities
- India transit infrastructure:Metro rail expansion in Mumbai, Delhi, and Bangalore creates greenfield deployment potential for unattended retail in high-footfall stations.
- Cloud-native management platforms:Predictive maintenance APIs reduce operator downtime and create recurring SaaS revenue streams distinct from hardware margins.
- Biometric age verification:Facial recognition integration opens regulated product categories (tobacco, alcohol) previously excluded from automated retail channels.
Industry Challenges
- FDA food-contact compliance:Temperature logging and surface material certification for US-deployed units extends product development cycles by 8-14 months.
- Legacy payment protocol fragmentation:Operators must maintain parallel support for magnetic stripe, EMV chip, and QR code systems, multiplying firmware validation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Vending Machines Market |
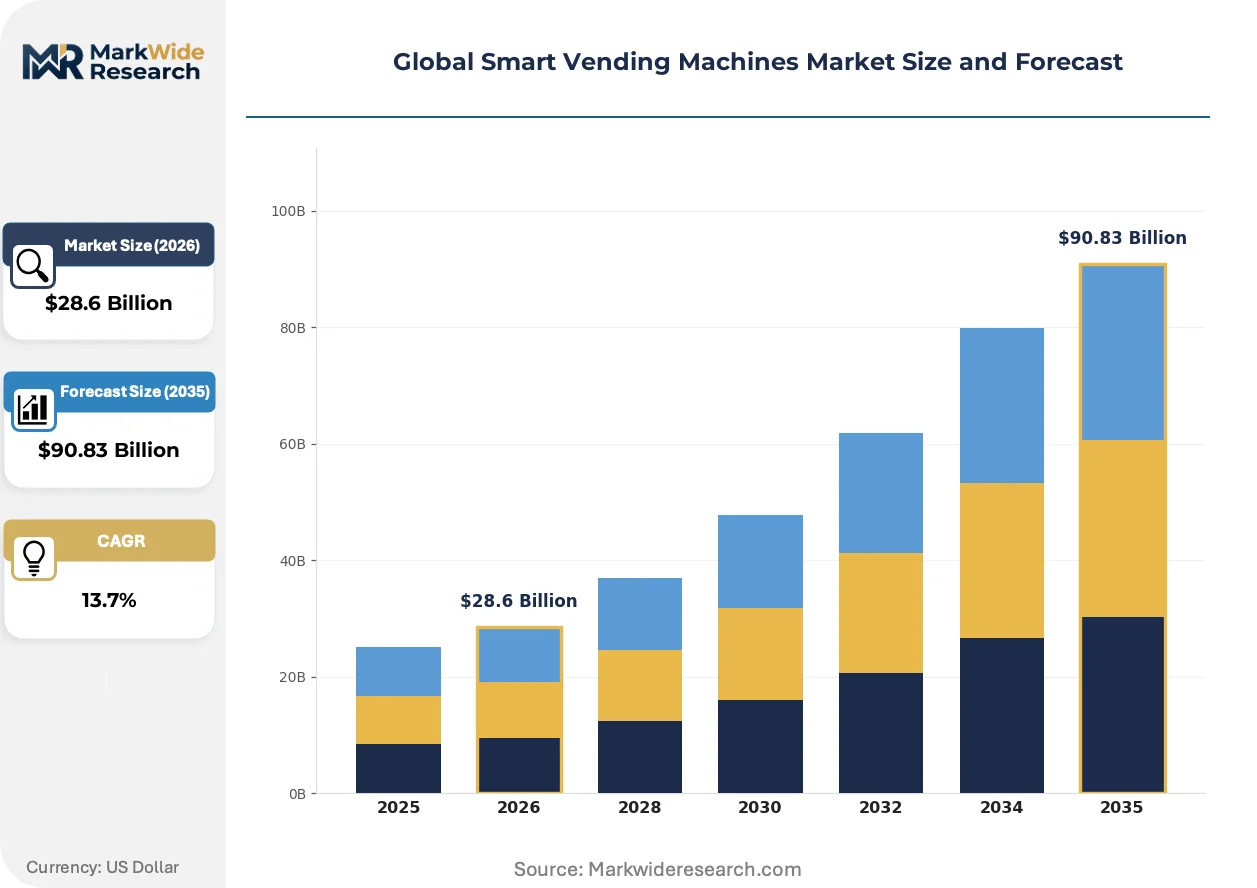
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $90.83 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Machines, Beverage Dispensers, Combo Vending Machines, Healthy Food Units Technology: Cashless Payment Systems, IoT Integration, Cloud-Based Management, Touchless Interaction End User: Office Spaces, Educational Institutions, Public Transport Hubs, Retail Environments Distribution Channel: Direct Sales, Online Retail, Third-Party Distributors, Franchise Models |
| Companies Covered | Azkoyen Group, N&W Global Vending, Fuji Electric, Selecta Group, Jofemar, Crane Merchandising Systems, Royal Vendors, Inc., SandenVendo America, Sanden Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Vending Machines Market Strategic Shifts
Three interconnected shifts are restructuring how smart vending systems are specified, deployed, and monetized: refrigeration technology transitions, regulatory compliance automation, and operator procurement model evolution.
Variable-speed compressor technology with natural refrigerant compatibility is supplanting fixed-speed R-134a systems in premium European and Japanese installations. Transit hub operators in Germany and the UAE specify these units to preempt F-Gas and METI enforcement thresholds. The technology is compressing total cost of ownership calculations by 18-24% over equipment life, tilting procurement criteria toward energy efficiency metrics.
CE marking requirements under the EU F-Gas Regulation now mandate embedded refrigerant leak detection and automated reporting interfaces. Manufacturers must integrate IoT sensors directly into refrigeration loops rather than bolting on aftermarket monitoring. Beverage dispenser units face the steepest redesign burden, as their higher refrigerant charge volumes trigger stricter containment protocols.
Workplace facility managers now specify vending services through integrated foodservice contracts rather than standalone equipment leases. This bundling displaces traditional operator-procurement relationships in US and German office markets. Channel intermediaries with existing corporate catering relationships capture preferential placement rights, forcing pure-play vending operators to develop partnership structures or vertical foodservice capabilities.
Global Smart Vending Machines Market Segmentation
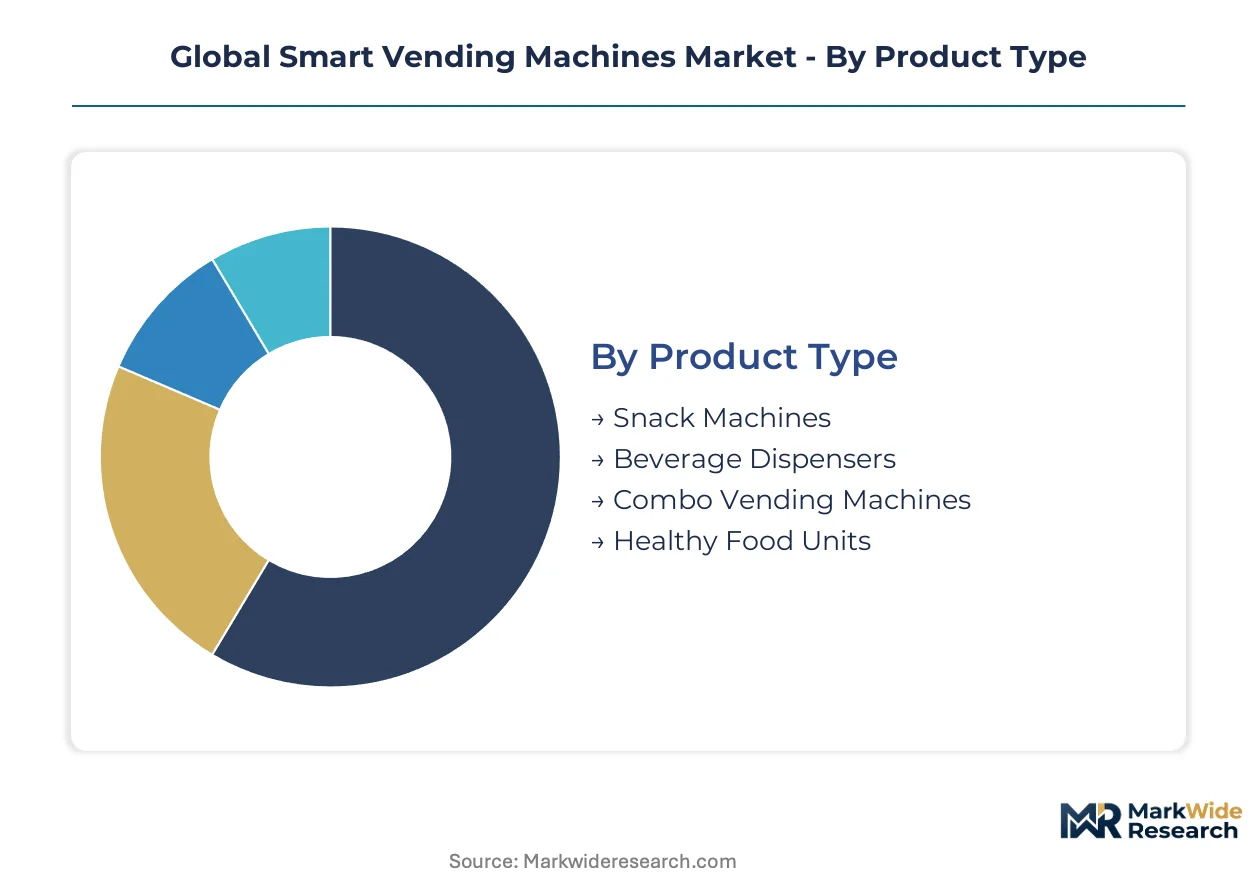
Smart vending machine procurement channels vary sharply by segment maturity and operator sophistication. Beverage and healthy food units flow through distinct sales motions, while technology tiers command separate distribution economics.
Product Type:
Beverage and healthy food segments concentrate in corporate foodservice contracts, while snack and combo machines move through traditional equipment leasing channels.
- Beverage Dispensers:These units integrate 150-300W variable-speed compressor systems with multi-temperature zones for carbonated, still, and functional beverages. Demand clusters in Japan's transit corridors and German airport terminals where METI standby limits and EU F-Gas Regulation filter hardware selection. Workplace wellness programs in US office towers accelerate replacement cycles for units with temperature logging capabilities.
- Healthy Food Units:Refrigerated cabinets with HACCP-compliant temperature monitoring and rapid-cooldown cycles preserve fresh salads, proteins, and prepared meals. Corporate procurement departments in the United Arab Emirates and Germany specify these through integrated foodservice contracts rather than standalone leases. FDA food-contact surface certification extends US development timelines.
- Snack Machines:Ambient-temperature dispensers with spiral or conveyor delivery mechanisms dominate transit hub deployments in India.
- Combo Vending Machines:Dual-zone units combining ambient snack storage with refrigerated beverage compartments serve mixed-traffic locations.
By volume, beverage dispensers lead. By expansion trajectory, healthy food units are climbing the fastest.
Technology:
Technology tiers stratify by operator IT maturity and payment infrastructure readiness across deployment geographies.
- IoT Integration:ARM-based telemetry controllers with cellular or Wi-Fi connectivity transmit inventory, temperature, and fault data to cloud platforms. Japan's METI enforces stringent standby power limits that filter out lower-efficiency hardware. Predictive maintenance APIs reduce operator downtime and create recurring SaaS revenue streams.
- Cloud-Based Management:Browser-based dashboards with predictive analytics and automated reordering workflows reshape operator procurement criteria. German transit hub operators specify these interfaces to preempt EU F-Gas automated reporting mandates. The technology compresses total cost of ownership calculations by enabling remote fault diagnosis.
- Cashless Payment Systems:Multi-protocol terminals supporting NFC, EMV chip, QR codes, and biometric verification reduce transaction friction in high-density urban corridors.
- Touchless Interaction:Gesture-based selection and voice ordering interfaces command premium positioning in post-pandemic workplace deployments.
By installed base, cashless payment systems dominate. By feature velocity, cloud-based management is gaining share fastest.
End User:
End-use concentration follows footfall density and dwell-time patterns across urban infrastructure.
- Public Transport Hubs:Metro rail stations, airports, and bus terminals in Mumbai, Delhi, and Bangalore generate greenfield deployment potential. India transit infrastructure expansion creates unattended retail opportunities where beverage dispensers with natural refrigerant compatibility meet emerging efficiency standards.
- Office Spaces:Corporate towers and business parks in the United States and Germany specify vending services through bundled foodservice contracts. Facility managers prioritize healthy food units as workplace wellness programs reshape procurement.
- Educational Institutions:University campuses and K-12 facilities in Japan deploy touchless-enabled units to reduce surface contact points.
- Retail Environments:Shopping malls and convenience stores utilize combo machines to maximize SKU density in constrained footprints.
By deployment count, public transport hubs lead. By contract value expansion, office spaces are pulling ahead.
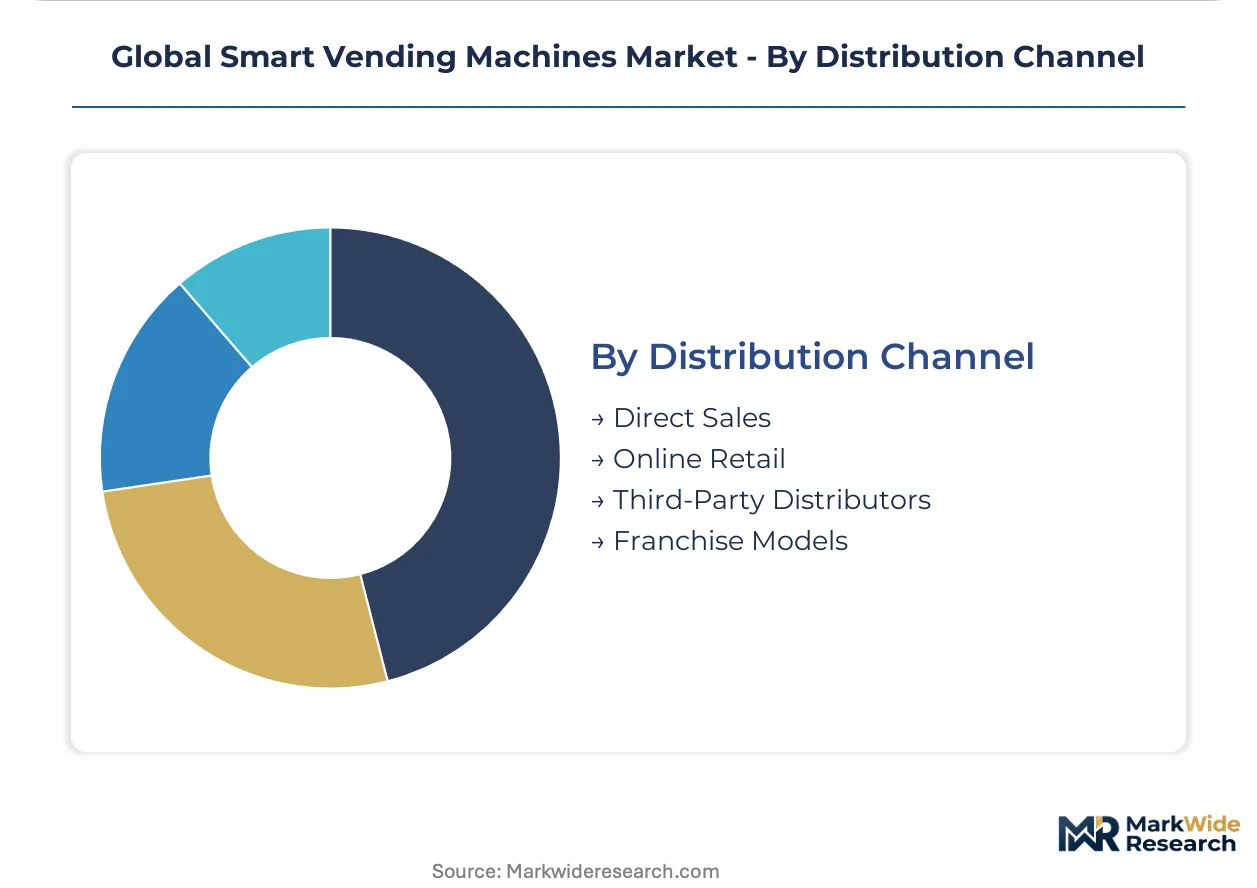
Distribution Channel:
Channel economics diverge by customer scale and service bundling requirements.
- Direct Sales:Manufacturer field teams engage large transit authorities and corporate foodservice providers in Germany and the United Arab Emirates. Direct relationships capture preferential placement rights in airport concession tenders.
- Third-Party Distributors:Regional equipment dealers with local service networks dominate mid-market office and retail deployments across India.
- Franchise Models:Operator-owned networks with territorial exclusivity concentrate in Japanese urban corridors.
- Online Retail:E-commerce platforms serve small-format operators and replacement part procurement.
By revenue concentration, direct sales leads. By geographic reach expansion, third-party distributors are extending fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan deploys smart vending machines as dense urban infrastructure with biometric payment integration, while Germany treats them as energy-efficiency compliance platforms under EU F-Gas mandates. The United States and United Arab Emirates pursue divergent paths: workplace wellness bundling versus luxury transit hub automation.
Japan
Tokyo's metro corridors and Osaka's rail stations host the world's densest vending machine networks, with METI standby power limits filtering out inefficient hardware. Touchless payment convergence drives NFC and biometric verification integration in high-footfall urban zones. Kanto region operators specify natural refrigerant-compatible compressors to preempt regulatory thresholds.
Germany
Frankfurt Airport and Munich transit terminals generate replacement demand as EU F-Gas Regulation accelerates R-134a phase-out schedules. CE marking mandates embedded leak detection and automated reporting interfaces, forcing refrigeration loop redesigns. Bavaria's industrial corridor supplies variable-speed compressor technology to European assemblers.
United States
Corporate towers in Manhattan and Chicago specify healthy food units through bundled foodservice contracts rather than standalone equipment leases. FDA temperature logging requirements extend development cycles for sanitary design certification. West Coast tech campuses deploy gesture-based selection interfaces as workplace wellness amenities.
United Arab Emirates
Dubai International Airport and Abu Dhabi transit hubs prioritize premium unattended retail with multi-protocol cashless acceptance. MOHAP guidelines on food-contact surfaces shape specifications for fresh meal dispensing. Sharjah's logistics corridor supports equipment import and regional distribution networks.
India
Mumbai Metro, Delhi Metro, and Bangalore's Namma Metro expansion creates greenfield deployment potential in high-footfall stations. FSSAI compliance requirements for refrigerated food units filter vendor selection. Maharashtra's industrial belt assembles ambient-temperature snack dispensers for transit infrastructure.
Global Smart Vending Machines Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive technology production distinguishing premium positioning from assembly-dependent competitors. Semiconductor heritage and compressor manufacturing anchor the upper tier, while software depth and payment module integration define mid-tier differentiation. Strategic moves concentrate on cloud-native platform development and natural refrigerant compatibility roadmaps.
Within the integrated tier, Fuji Electric leverages its semiconductor heritage for in-house payment module production, while Sanden Holdings Corporation anchors positioning through captive compressor technology supply. Crane Merchandising Systems exemplifies the software-focused archetype with cloud-based inventory management capabilities. Azkoyen Group and N&W Global Vending occupy positions in the European specialist fabricator segment.
| Leading Market Players |
|---|
| Azkoyen Group |
| N&W Global Vending |
| Fuji Electric |
| Selecta Group |
| Jofemar |
| Crane Merchandising Systems |
| Royal Vendors, Inc. |
| SandenVendo America |
| Sanden Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Natural refrigerant adoption in European and Japanese deployments displaces R-134a systems while simultaneously concentrating compressor procurement around German and Japanese industrial groups and compressing pricing power for mid-tier assemblers lacking captive supply.
Pricing Analysis
Long-term equipment lease contracts with bundled service provisions dominate procurement relationships between manufacturers and transit authorities, though spot purchases of replacement compressors and payment modules introduce volatility for operators without backward integration. Price differentiation separates CE-marked EU F-Gas compliant units with embedded leak detection from standard-efficiency models bound for price-sensitive Indian transit infrastructure. Cost compression in mid-tier beverage dispensers is intensifying because Japanese and German compressor suppliers prioritize premium variable-speed production for domestic markets. Corporate foodservice buyers in US office towers exhibit lowest price sensitivity, prioritizing HACCP-compliant temperature logging over unit economics.
Supply Chain Analysis
Japan and Germany anchor production of variable-speed compressors with natural refrigerant compatibility, while Taiwan and South Korea feed ARM-based IoT controller fabrication for payment modules and telemetry systems. Refrigeration loops draw from aluminum coil stock and copper refrigerant lines, with embedded sensor arrays resting on semiconductor foundry output from East Asian suppliers. Single-source vulnerability concentrates in compressor technology where Sanden Holdings and German industrial groups maintain captive production. Distribution runs through manufacturer-direct field teams for airport concession tenders and regional equipment dealers for mid-market office deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart vending machine market sits in a cyclical recovery phase driven by EU F-Gas Regulation-mandated equipment refresh cycles across European transit infrastructure, creating replacement demand that favors suppliers with compliant refrigeration roadmaps.
For Market Incumbents: Compound defensive positioning through captive compressor technology investments and cloud-native platform depth that locks in operator switching costs. The embedded firmware talent shortage threatens feature velocity for payment module roadmaps; vertical integration into semiconductor controller design preserves margin structure against mid-tier assemblers dependent on outsourced ARM development. For New Entrants and Emerging Players: Lead with biometric age verification integration to unlock regulated product categories previously excluded from automated retail channels. India's metro rail expansion in Mumbai, Delhi, and Bangalore presents the most penetrable geography for greenfield beverage dispenser deployment. A partnership-first go-to-market approach with established regional foodservice intermediaries accelerates placement rights in corporate tower environments. For Investors and Strategic Acquirers: The market sits at a regulatory-compliance phase that favors vertically integrated manufacturers with refrigerant technology roadmaps and IoT platform assets. Long-term viability over the next decade hinges on natural refrigerant compatibility and predictive maintenance API monetization. Watch compressor supply allocation decisions by Japanese industrial groups as the inflection indicator for mid-tier assembler distress.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Transition | EU F-Gas Regulation compliance preempts enforcement thresholds and captures replacement demand in German airports. |
| Cloud-Native Platform Development | Predictive maintenance APIs reduce operator downtime and generate recurring SaaS revenue distinct from hardware margins. |
| Biometric Payment Integration | NFC and facial recognition convergence reduces transaction friction in Japan's METI-regulated high-density urban corridors. |
| Corporate Foodservice Partnership | Bundled service contracts displace standalone equipment leases in US and German workplace wellness procurement. |
| India Transit Infrastructure Entry | Metro rail expansion in Mumbai, Delhi, and Bangalore creates greenfield deployment potential for unattended retail. |
Study Parameters
The analysis maps beverage dispensers, healthy food units, snack machines, and combo configurations, each validated through equipment procurement directors at transit authorities, corporate foodservice managers, refrigeration technology engineers, and IoT platform product leads. Primary interview findings triangulate against secondary sources including EU F-Gas Regulation implementation reports, METI standby power compliance databases, FDA food-contact surface guidance documents, and airport concession tender filings. Bottom-up unit deployment estimates reconcile with top-down market sizing through cross-validation against manufacturer production disclosures.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models segmentation by product type, technology tier, end-use concentration, and distribution channel structure. CAGRs derive from equipment replacement cycle analysis, regulatory phase-out timelines, and operator procurement survey data. Forecast inputs incorporate refrigerant transition schedules, embedded systems engineering labor availability, and transit infrastructure capital expenditure patterns.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas enforcement, stable semiconductor foundry capacity, and continued India metro expansion would require recalibration. Forecasts reflect documented assumptions about regulatory implementation pace and operator technology refresh willingness. Specific risks that could revise projections include accelerated refrigerant phase-out schedules, embedded firmware talent pool contraction, and corporate foodservice contract bundling acceleration. Recalibration cycles align with material shifts in METI standby power thresholds and EU leak detection mandate enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Helpdesk Automation Market
Automation
Hyperautomation Market
Automation
United States Laboratory Automation Market
Automation
Marketing Automation Solutions Market
Automation
Automated Cell Block Systems Market
Automation
North America Data Center Automation Market
Automation
Laboratory Benchtop Automation Market
Automation
Process Automation Market
Automation
Escalator Control Systems Market
Automation
Automatic Message Handling System Market
Automation
Europe Data Center Automation Market
Automation
Automation-As-A-Service Market
Automation
Global Warehouse Barcode System Market
Automation
Parcel Sorting System Market
Automation
Universal Process Control Market
Automation
Workload Automation Software Market