
 Global Workforce Management Software Market | 2026-2036
Global Workforce Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Workforce Management Software Market Outlook
Enterprise software procurement is tilting toward subscription-based cloud platforms as buyers abandon perpetual license models. UKG Inc. leverages its unified human capital management stack to anchor mid-market and large enterprise accounts. SAP SE competes through deep ERP integration that sustains stickiness among manufacturing and retail clients. Oracle Corporation dominates database-centric workforce analytics, extending its footprint through infrastructure control.
Workforce management software comprises integrated applications for time tracking, employee scheduling, absence management, and labor compliance, typically delivered via cloud infrastructure with API connectivity to payroll and HRIS systems. Its primary purpose is optimizing labor allocation, ensuring regulatory adherence, and reducing administrative overhead across distributed workforces. Cloud-based deployment leads segment momentum as healthcare and retail buyers demand remote accessibility and automatic updates, while on-premises installations retain relevance in sectors with stringent data residency requirements. Compliance management functionality captures concentrated margin pools as jurisdictional labor laws multiply in complexity.
The U.S. Department of Labor enforces Fair Labor Standards Act provisions that shape time-tracking accuracy requirements, while the EU AI Act imposes algorithmic transparency obligations on automated scheduling systems deployed in Europe. ISO 30414 human capital reporting standards further condition how workforce data must be structured for investor-grade disclosure. Stakeholders must weigh regulatory fragmentation against platform consolidation when selecting vendors capable of spanning multiple compliance regimes.
Market Dynamics
Cloud migration is compressing deployment cycles across workforce management platforms as healthcare and retail buyers abandon perpetual license models for subscription infrastructure with embedded compliance automation.
Growth Catalysts
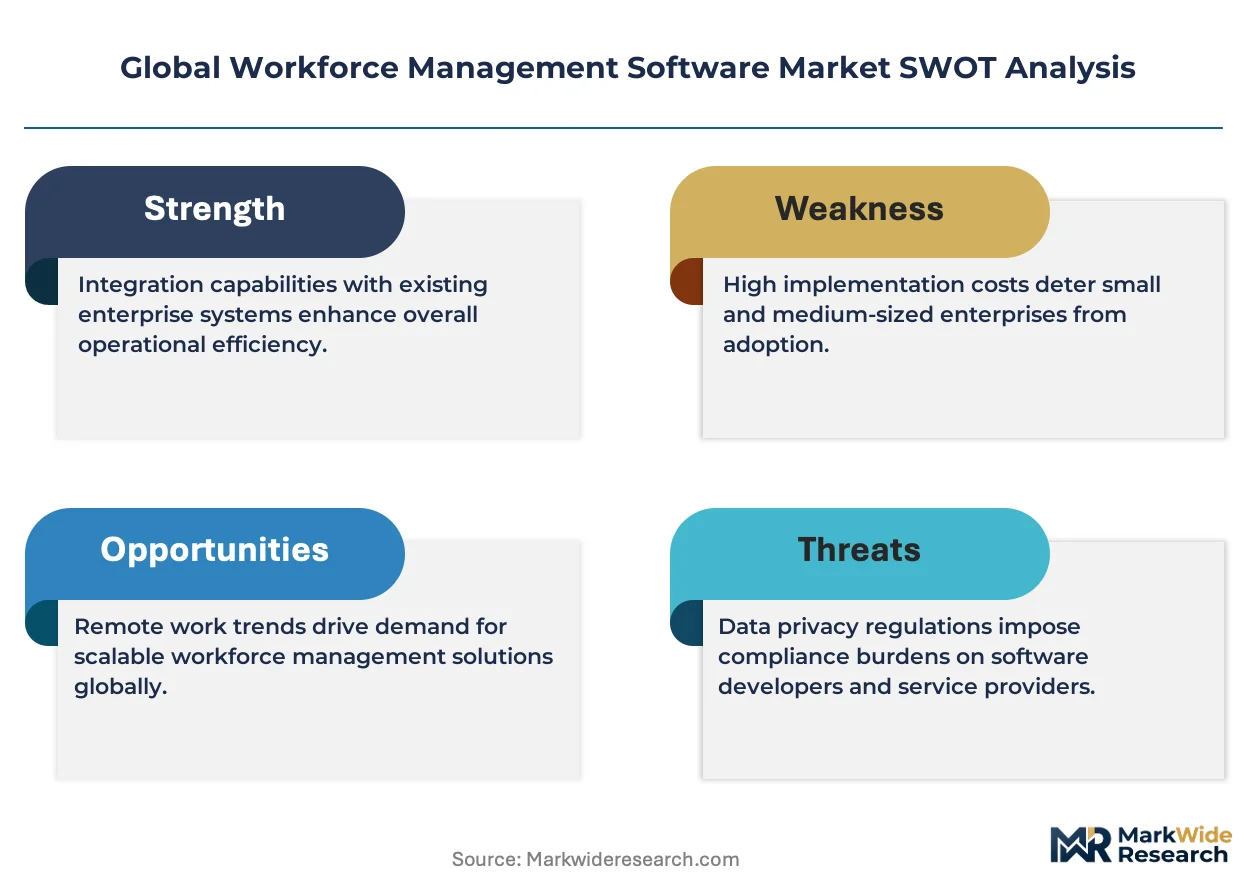
- EU AI Act transparency mandates:Automated scheduling systems in Europe must now expose algorithmic logic, creating replacement demand for compliant workforce platforms among multinational employers with European operations.
- Healthcare labor regulations:OSHA record-keeping requirements and state-level nurse staffing ratio laws in the United States are forcing hospital systems to upgrade time-tracking accuracy beyond legacy spreadsheet workflows.
- API-first architecture:Open connectivity standards are virtualizing integration between workforce platforms and payroll systems, reducing implementation friction for mid-market buyers previously locked out of enterprise-grade tools.
Market Restraints
- Data residency requirements:German banking and French public sector contracts mandate on-premises or sovereign cloud deployment, fragmenting vendor economies of scale and elevating infrastructure costs.
- Technical debt in legacy HRIS:Decades-old payroll systems in manufacturing and logistics sectors resist API connectivity, forcing expensive middleware development or manual reconciliation processes.
- Substitution by vertical SaaS:Industry-specific platforms for restaurants and construction are peeling off price-sensitive segments with pre-built compliance templates tuned to sector labor rules.
Strategic Opportunities
- ISO 30414 disclosure standards:Investor-grade human capital reporting requirements are creating premium pricing power for platforms that automate workforce metric aggregation for public company filings.
- India's PLI scheme expansion:Manufacturing incentives are accelerating formal sector employment growth, opening greenfield deployment opportunities for cloud-native workforce tools in automotive and electronics clusters.
- Gig economy compliance convergence:California AB5-style contractor classification rules spreading to Illinois and New York are forcing platform companies to adopt hybrid workforce management architectures.
Industry Challenges
- Algorithmic bias audit capabilities:Shortage of data scientists capable of validating automated scheduling fairness across demographic groups is delaying product releases and elevating legal exposure for vendors.
- Multi-jurisdiction compliance engineering:Engineering teams must maintain parallel rule engines for municipal, state, and federal labor laws, compressing release velocity and elevating quality assurance costs.
- Enterprise sales cycle elongation:Procurement committees now require security reviews, privacy impact assessments, and union consultation, extending average close timelines and straining vendor cash conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Workforce Management Software Market |
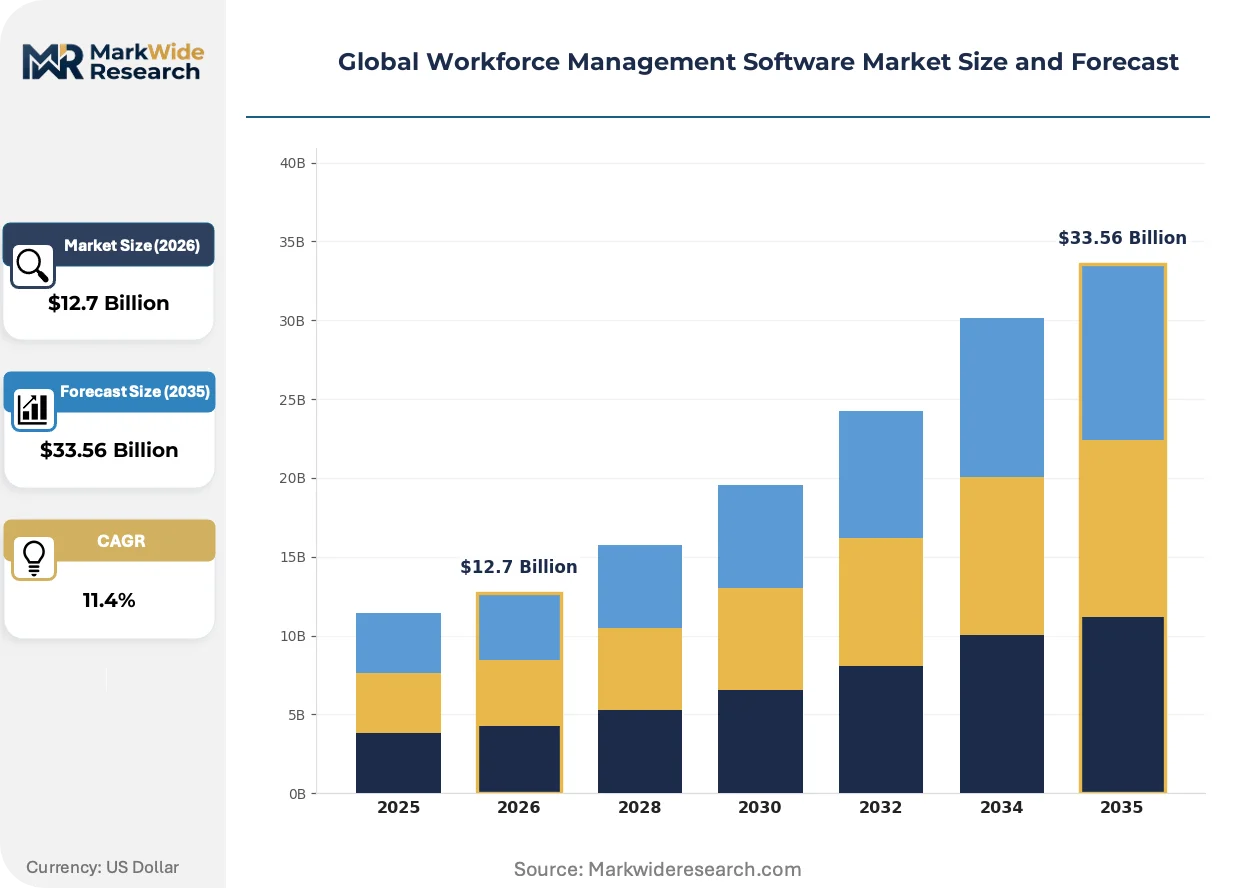
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Mobile End User: Healthcare, Retail, Manufacturing, Hospitality Functionality: Time Tracking, Scheduling, Compliance Management, Reporting Organization Size: Small Enterprises, Medium Enterprises, Large Enterprises, Startups |
| Companies Covered | UKG Inc., Workday Inc., Oracle Corporation, SAP SE, ADP Inc., Ceridian HCM Inc., Infor, NICE Ltd., Paycor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Workforce Management Software Market Strategic Shifts
Workforce platforms are embedding predictive capabilities that anticipate labor demand fluctuations, compressing the gap between operational planning and real-time scheduling adjustments across distributed workforces.
Edge computing infrastructure is virtualizing time-clock functionality, enabling biometric verification and geofenced attendance tracking on factory floors without persistent cloud connectivity. Automotive and warehousing operators in Germany and South Korea are piloting these deployments to reduce latency in high-throughput environments. The shift is compressing hardware replacement cycles and elevating cybersecurity requirements for endpoint device management.
Japan's METI has issued guidelines on algorithmic management transparency that extend beyond the EU AI Act's scope, requiring Japanese employers to document how automated scheduling systems weight seniority, skill certification, and availability. Manufacturing conglomerates with Japanese operations are consolidating vendor selection around platforms with built-in audit trails. The regulation is accelerating R&D investment in explainable AI interfaces for workforce optimization tools.
Buyers are unbundling implementation services from software subscriptions, negotiating fixed-scope deployment contracts with systems integrators rather than accepting vendor professional services at margin-inflated rates. Healthcare networks in Texas and Florida are leading this procurement pattern, treating workforce platforms as commodity infrastructure while competing aggressively on implementation pricing. The disintermediation is compressing services revenue for pure-play vendors and elevating the strategic importance of self-service configuration tools.
Global Workforce Management Software Market Segmentation
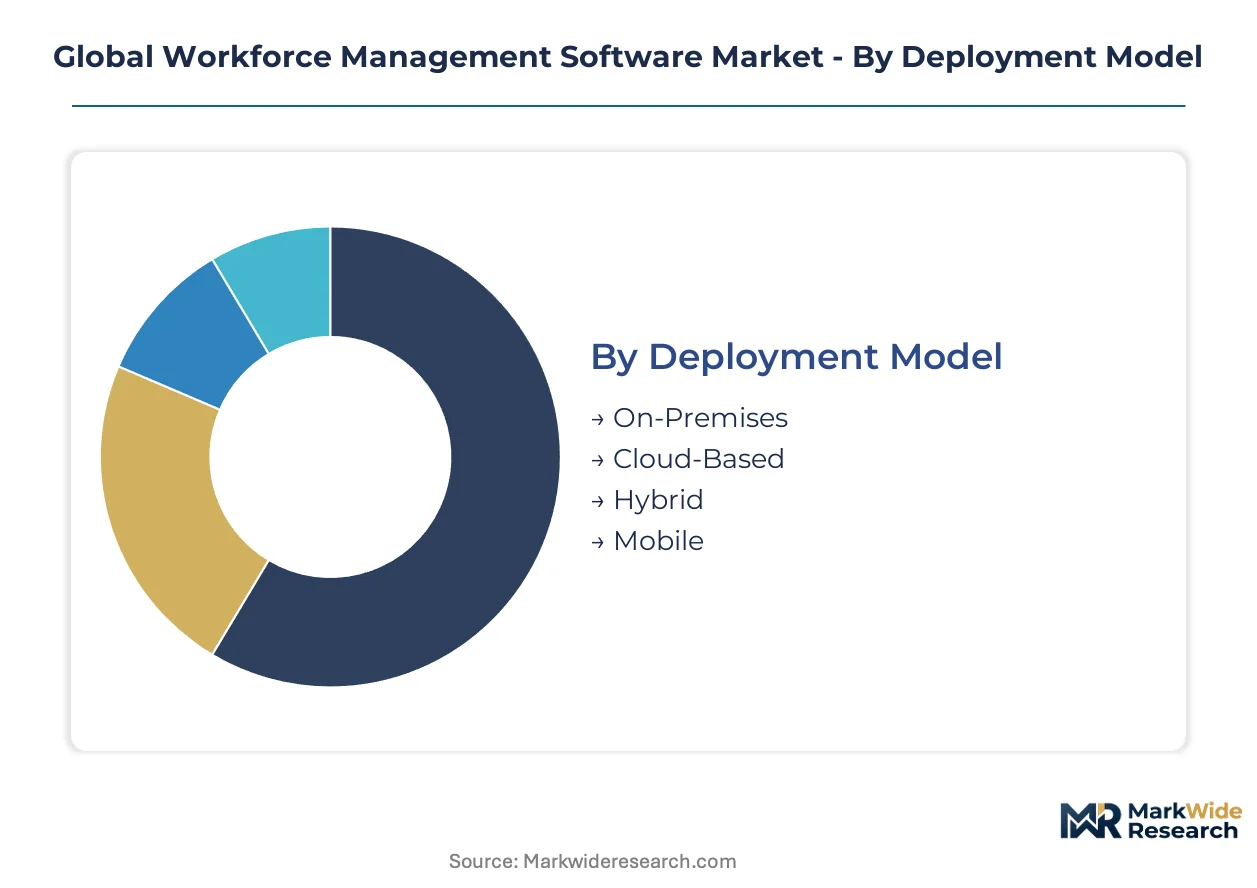
Workforce management software segments reflect divergent maturity curves across deployment infrastructure, end-use verticals, functional modules, and buyer scale. Each dimension carries distinct procurement patterns, integration complexity, and margin structures that shape vendor product roadmaps and sales motions.
Deployment Model:
Mature on-premises installations coexist with emerging cloud-native architectures as buyers navigate data sovereignty requirements against scalability imperatives.
- On-Premises:Legacy server installations persist in German banking and French public sector contracts where sovereign data residency rules block cross-border cloud processing. Compliance mandates from national regulators elevate infrastructure costs and compress vendor margins.
- Cloud-Based:Multi-tenant SaaS platforms dominate new procurement in United States healthcare networks and United Kingdom retail chains seeking automatic compliance updates and remote workforce accessibility. Subscription economics displace perpetual licenses, accelerating replacement cycles.
- Hybrid:Split architectures segment sensitive payroll data on-premises while routing scheduling modules through public cloud. Manufacturing conglomerates in Japan and South Korea pilot these configurations to balance latency requirements against centralized analytics.
- Mobile:Native iOS and Android applications extend time-tracking and shift-swapping to deskless workers. Warehousing operators in the Netherlands and gig platforms in California drive concentrated adoption.
Cloud-based deployment retains volume leadership; mobile represents the steepest expansion curve.
End User:
Vertical specialization intensity separates regulated healthcare environments from price-sensitive hospitality procurement.
- Healthcare:Hospital systems deploy integrated scheduling and compliance modules to satisfy OSHA record-keeping and state-level nurse staffing ratio laws. United States health networks in Texas and Florida unbundle implementation services to compress deployment costs.
- Retail:Franchise operators and big-box chains prioritize seasonal demand forecasting and multi-location workforce visibility. Cloud platforms with API payroll connectivity win mid-market accounts previously locked out of enterprise tools.
- Manufacturing:Shift-based production environments demand biometric time clocks and geofenced attendance verification. Automotive and electronics clusters in India's PLI scheme zones open greenfield opportunities for cloud-native vendors.
- Hospitality:Restaurants and hotels face substitution pressure from vertical SaaS with pre-built labor law templates tuned to sector rules. Price sensitivity limits addressable market for full-suite platforms.
Healthcare commands premium pricing power; manufacturing is expanding most quickly among formalizing emerging-market workforces.
Functionality:
Core administrative modules mature while compliance automation and predictive capabilities capture disproportionate R&D investment.
- Time Tracking:Foundational attendance capture integrates biometric verification and edge-computing time clocks for factory-floor latency reduction. German and South Korean automotive operators pilot these deployments.
- Scheduling:Algorithmic shift optimization now faces EU AI Act transparency mandates requiring exposed weighting logic for seniority, skills, and availability. Japanese METI guidelines extend these obligations further.
- Compliance Management:Automated rule engines for municipal, state, and federal labor laws command concentrated margin pools as jurisdictional complexity multiplies. Engineering teams maintain parallel codebases, compressing release velocity.
- Reporting:ISO 30414 human capital disclosure standards create premium pricing for platforms automating workforce metric aggregation for public company filings. Investor-grade reporting elevates procurement committee scrutiny.
Time tracking retains installed base dominance; compliance management delivers the steepest margin expansion.
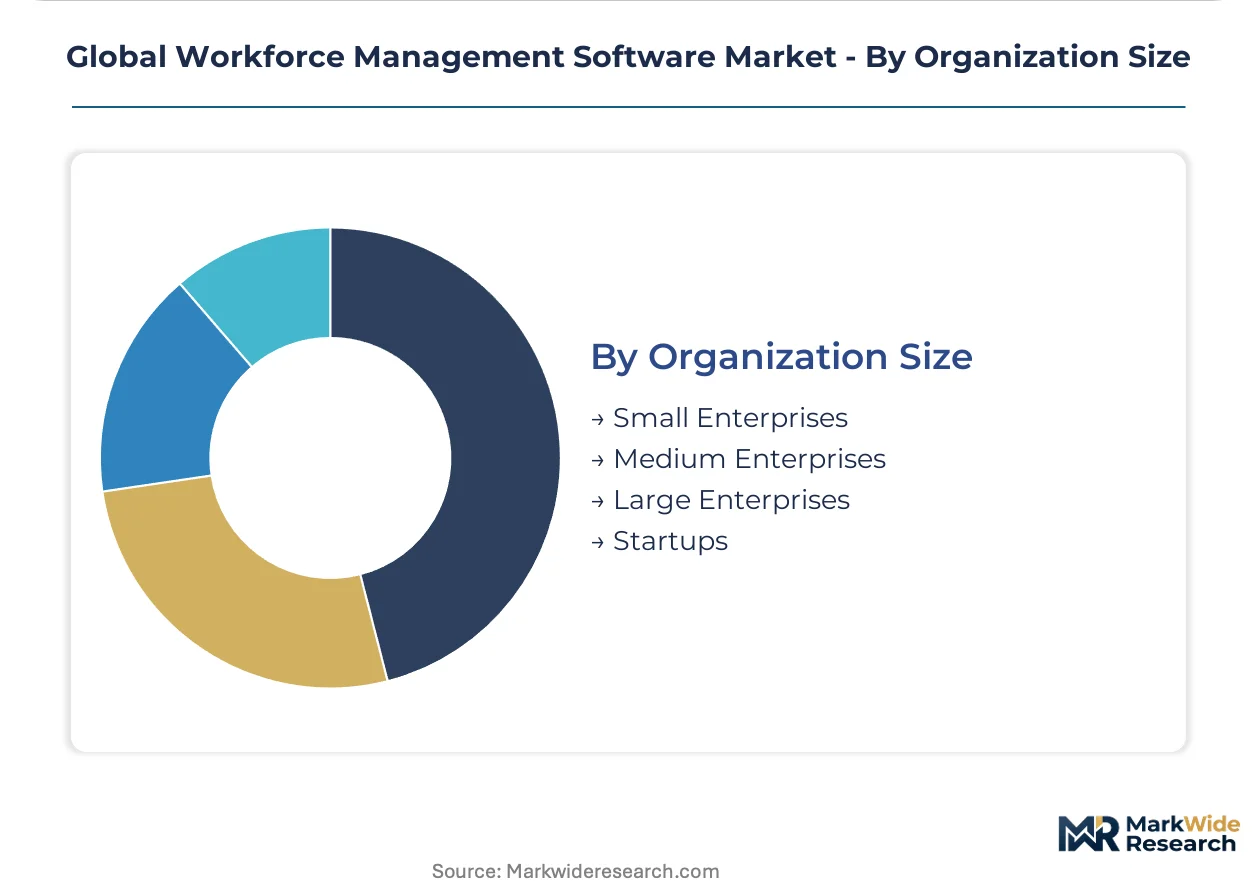
Organization Size:
Buyer scale determines integration complexity tolerance and professional services dependency.
- Small Enterprises:Simplified cloud configurations with self-service onboarding target businesses below 100 employees. API-first architectures reduce implementation friction for buyers lacking IT departments.
- Medium Enterprises:Mid-market accounts seek unified human capital management stacks without enterprise price tags. UKG Inc. anchors this segment through scalable platform consolidation.
- Large Enterprises:Global employers demand multi-jurisdiction compliance spanning OSHA, EU AI Act, and Japan METI requirements. Procurement committees impose security reviews, privacy impact assessments, and union consultation, elongating sales cycles.
- Startups:Venture-backed technology firms prioritize rapid configuration and gig-economy contractor classification support. California AB5-style rules spreading to Illinois and New York force hybrid workforce architectures.
Large enterprises sustain absolute revenue concentration; startups are gaining share fastest among cloud-native entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable systems landing at Ashburn, Virginia, and Bude, Cornwall, underpin the data infrastructure that sustains workforce software demand across major economies. Cloud-native platforms route through these nodes to serve distributed enterprises requiring real-time scheduling and compliance synchronization.
United States
Hospital networks in Texas and Florida drive concentrated procurement of scheduling and compliance modules as state-level nurse staffing ratio laws tighten. The Department of Labor enforces Fair Labor Standards Act provisions that shape time-tracking accuracy requirements for enterprise buyers. Dallas-Fort Worth health systems unbundle implementation services from software subscriptions, treating platforms as commodity infrastructure.
Germany
Automotive and banking sectors mandate sovereign cloud or on-premises deployment under data residency rules enforced by national regulators. The EU AI Act imposes algorithmic transparency obligations on automated scheduling systems deployed across German manufacturing conglomerates. Stuttgart automotive clusters pilot edge-computing time clocks with biometric verification to reduce factory-floor latency.
Japan
METI guidelines on algorithmic management transparency extend beyond EU AI Act scope, requiring documentation of how scheduling systems weight seniority and skill certification. Manufacturing conglomerates consolidate vendor selection around platforms with built-in audit trails. Nagoya automotive operators accelerate R&D investment in explainable AI interfaces for workforce optimization.
India
The PLI scheme expansion accelerates formal sector employment growth in automotive and electronics manufacturing. Central government incentives open greenfield deployment opportunities for cloud-native workforce tools in Tamil Nadu and Karnataka production clusters. Bangalore technology parks and Chennai automotive corridors drive mid-market adoption of API-first scheduling platforms.
United Kingdom
Retail chains prioritize seasonal demand forecasting and multi-location workforce visibility through cloud platforms with API payroll connectivity. GDPR compliance requirements shape data architecture decisions for workforce analytics vendors serving British enterprise buyers. London financial services firms and Manchester distribution centers lead adoption of hybrid deployment models splitting sensitive payroll data from scheduling modules.
Global Workforce Management Software Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying niche compliance engines or biometric verification modules. The vendor landscape consolidates around full-suite human capital management stacks while fragmenting at the edge with vertical SaaS substitutes. Three archetypes dominate: ERP-anchored conglomerates with infrastructure control, pure-play workforce specialists with unified HCM stacks, and API-native challengers targeting mid-market API-first procurement. Competitive moves center on M&A to absorb compliance automation capabilities and strategic partnerships to embed predictive analytics without in-house R&D burden.
Within the unified HCM tier, UKG Inc. and Workday Inc. occupy positions that exemplify platform consolidation strategies, while Oracle Corporation and SAP SE anchor the ERP-integrated segment through database-centric workforce analytics and deep manufacturing client relationships. ADP Inc. represents the payroll-origin archetype extending into adjacent workforce modules, and Ceridian HCM Inc. sits within the cloud-native specialist tier targeting mid-market buyers with rapid-deployment configurations.
| Leading Market Players |
|---|
| UKG Inc. |
| Workday Inc. |
| Oracle Corporation |
| SAP SE |
| ADP Inc. |
| Ceridian HCM Inc. |
| Infor |
| NICE Ltd. |
| Paycor Inc. |
| Others |
Value Chain & Pricing Dynamics
Transatlantic fiber optic corridors landing at Ashburn, Virginia, and Bude, Cornwall, transmit the compliance data streams that shape cost-to-serve differentials across workforce management vendors. Cloud-native platforms route through these nodes to serve distributed enterprises, concentrating infrastructure leverage among hyperscale providers while compressing margins for regional hosting alternatives.
Pricing Analysis
Volume-discount tiering structures separate enterprise commitments above ten thousand seats from mid-market bands and small-business self-service tiers. Subscription economics displace perpetual licenses as healthcare networks in Texas and Florida unbundle implementation services to compress total cost of ownership. Price differentiation hinges on compliance automation depth and API integration complexity, with manufacturing buyers proving least price-sensitive due to regulatory penalty exposure. Cost compression in the mid-market tier intensifies as vertical SaaS substitutes peel off price-conscious restaurant and construction segments.
Supply Chain Analysis
Upstream feedstock for workforce platforms draws from cloud infrastructure providers concentrated in the United States, Ireland, and Singapore. Compute instances, identity verification APIs, and biometric sensor modules constitute critical input dependencies. Single-source vulnerability persists in sovereign cloud certifications required by German banking and French public sector contracts. Distribution runs through direct enterprise sales teams and systems integrator partnerships, with self-service channels gaining share among sub-thousand-employee buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workforce management software sits at a platform-economics inflection where API-first interoperability is displacing monolithic suite dominance. The shift toward embedded compliance automation and predictive scheduling is rewiring vendor competitive positions.
For Market Incumbents: Insulate installed base stickiness by deepening ERP integration anchors and accelerating R&D investment in explainable AI interfaces that satisfy Japan METI audit trail requirements. Vertical SaaS substitutes targeting hospitality and construction represent the most acute substitution threat. Certification investment in ISO 30414 disclosure automation captures premium pricing power among public company buyers.
For New Entrants and Emerging Players: Mid-market healthcare networks in India's Tamil Nadu and Karnataka PLI scheme zones represent the most penetrable entry point for cloud-native scheduling platforms. API-first architectures with rapid-deployment configurations bypass professional services dependencies that elongate incumbent sales cycles. Partner-centric go-to-market angles through regional systems integrators accelerate traction without field sales infrastructure.
For Investors and Strategic Acquirers: Compliance automation specialists with multi-jurisdiction rule engines command acquisition premiums as labor law complexity multiplies. Long-term viability centers on platforms spanning OSHA, EU AI Act, and Japan METI requirements without parallel codebases. The signal to watch is replacement demand spikes following major regulatory enforcement actions in healthcare and logistics sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding payroll and HRIS connectivity through open APIs reduces implementation friction for mid-market buyers. |
| Acquisition of Specialist Firm | Absorbing niche compliance engine providers accelerates multi-jurisdiction rule coverage without internal R&D burden. |
| Strategic Partnership | Hyperscaler alliances for sovereign cloud certifications unlock German banking and French public sector contracts. |
| Product Launch | Explainable AI scheduling interfaces satisfy Japan METI transparency mandates and EU AI Act algorithmic disclosure requirements. |
| Geographic Expansion | Greenfield deployment in India's PLI scheme manufacturing clusters captures formalizing workforce growth in automotive and electronics. |
Study Parameters
Desk research of regulatory filings, vendor technical documentation, and industry association datasets preceded structured interviews with workforce management software executives, healthcare IT procurement officers, manufacturing plant managers, and systems integrator partners. Secondary validation drew from SEC 10-K disclosures, EU AI Act implementation guidance, Japan METI algorithmic management guidelines, and OSHA enforcement records. Bottom-up deployment estimates across organization size tiers were triangulated against top-down market sizing from subscription revenue aggregation.
Assumptions held fixed include sustained cloud migration momentum among healthcare and retail buyers, continued regulatory fragmentation across jurisdictional labor laws, and stable API standardization trajectories. The analytical framework modeled deployment model, organization size, vertical specialization, and integration complexity across the analysis window. CAGRs were derived from logistic adoption curves fitted to historical replacement cycle data and greenfield penetration rates in emerging manufacturing clusters.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting enterprise software procurement cycles or sovereign data residency enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding compliance automation demand and vertical SaaS substitution pressure. Cross-checking against hyperscaler capex disclosures and hospital capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Independent Software Vendors (Isvs) Market
Software & Services
Construction Enterprise Resource Planning (ERP) Software Market
Software & Services
Service Scheduling Software Market
Software & Services
Email Marketing Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
API Testing Market
Software & Services
Exploration and Production (E&P) Software Market
Software & Services
E-Clinical Solution Software Market
Software & Services
Non-Profit Software Market
Software & Services
Global Microscopy Software Market
Software & Services
Newsroom Software Market
Software & Services
Enterprise Intellectual Property (IP) Management Software Market
Software & Services
Sales Dialer Software Market
Software & Services
Ground Handling Software Market
Software & Services
Solar Rooftop Design Software Market
Software & Services
Association Management Software Market