
 Global Cloud Automation Market | 2026-2036
Global Cloud Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Automation Market Foresight
The capital-intensity divergence between hyperscale platform operators and specialized tooling vendors is bifurcating competitive dynamics in cloud automation. Microsoft Corporation leverages its Azure-native integration stack to sustain enterprise retention across hybrid deployments. HashiCorp, Inc. competes through open-source Terraform adoption that anchors its commercial cloud management suite. Amazon Web Services, Inc. dominates infrastructure automation through backward integration into its IaaS layer, controlling provisioning APIs that third-party tools must navigate.
Cloud automation encompasses software-driven orchestration of compute, storage, and network resources through policy-based provisioning, API abstraction, and declarative configuration management, eliminating manual intervention in multi-tenant environments. The technology enables organizations to enforce compliance guardrails, auto-scale workloads, and recover from failures through codified runbooks rather than operator action. Hybrid cloud deployment architectures currently absorb the largest share of enterprise investment as organizations straddle on-premises legacy systems with public elasticity. Continuous delivery solutions within the solution-type dimension are expanding fastest, reflecting pressure on software teams to compress release cycles. Banking and financial services within end-user industries represent a concentrated margin pool due to stringent audit requirements and penalty structures for downtime.
FDA oversight of cloud-hosted clinical trial data and HIPAA security rule enforcement shape automation requirements for healthcare workloads in the United States. The EU AI Act and GDPR impose algorithmic accountability and data residency constraints that European deployments must embed into automated policy engines. ISO 27001 and SOC 2 Type II certifications function as de facto market access filters for automation vendors serving regulated industries. Stakeholders must monitor how sovereign cloud mandates proliferate across national jurisdictions, as data localization rules fragment the addressable market for unified automation platforms.
Market Dynamics
Hyperscale cloud operators are consolidating control over provisioning APIs, forcing third-party automation vendors to navigate proprietary integration layers that lock enterprise workloads into vertically integrated stacks.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European financial services firms must embed audit trails into automated orchestration workflows, expanding demand for policy-as-code platforms that enforce explainability guardrails.
- Hybrid cloud workload portability:Kubernetes-native tooling enables seamless migration between on-premises data centers and public cloud environments, reducing vendor lock-in friction for regulated industries.
- India:The country's PLI scheme for data center infrastructure is accelerating domestic cloud capacity buildout, creating fresh demand for localized automation stacks that comply with data sovereignty requirements.
Market Restraints
- Specialized talent scarcity:Infrastructure-as-code expertise concentrates in North American and Western European labor markets, inflating implementation costs for enterprises in emerging economies.
- API dependency risk:Third-party automation vendors face backward integration pressure from hyperscale IaaS operators who control core provisioning interfaces and can deprecate access unilaterally.
- Governance tooling fragmentation:Competing policy frameworks from cloud-native computing foundation projects create integration overhead that delays enterprise standardization.
Strategic Opportunities
- Brazil:Underpenetrated financial services automation presents white space as ANVISA and the central bank tighten data residency requirements for cloud-hosted transactional systems.
- GitOps convergence with policy engines:Merging declarative configuration management with real-time compliance validation enables autonomous remediation loops that reduce mean-time-to-recovery.
- Edge computing orchestration:Distributed manufacturing and logistics facilities require lightweight automation agents that operate with intermittent connectivity, opening new deployment architectures beyond centralized cloud.
Industry Challenges
- Multi-cloud credential sprawl:Security teams struggle to maintain least-privilege access across fragmented identity providers, increasing breach surface area.
- Legacy mainframe integration:Financial institutions running COBOL-based core banking systems face months-long refactoring timelines to expose compatible APIs for modern automation hooks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Automation Market |
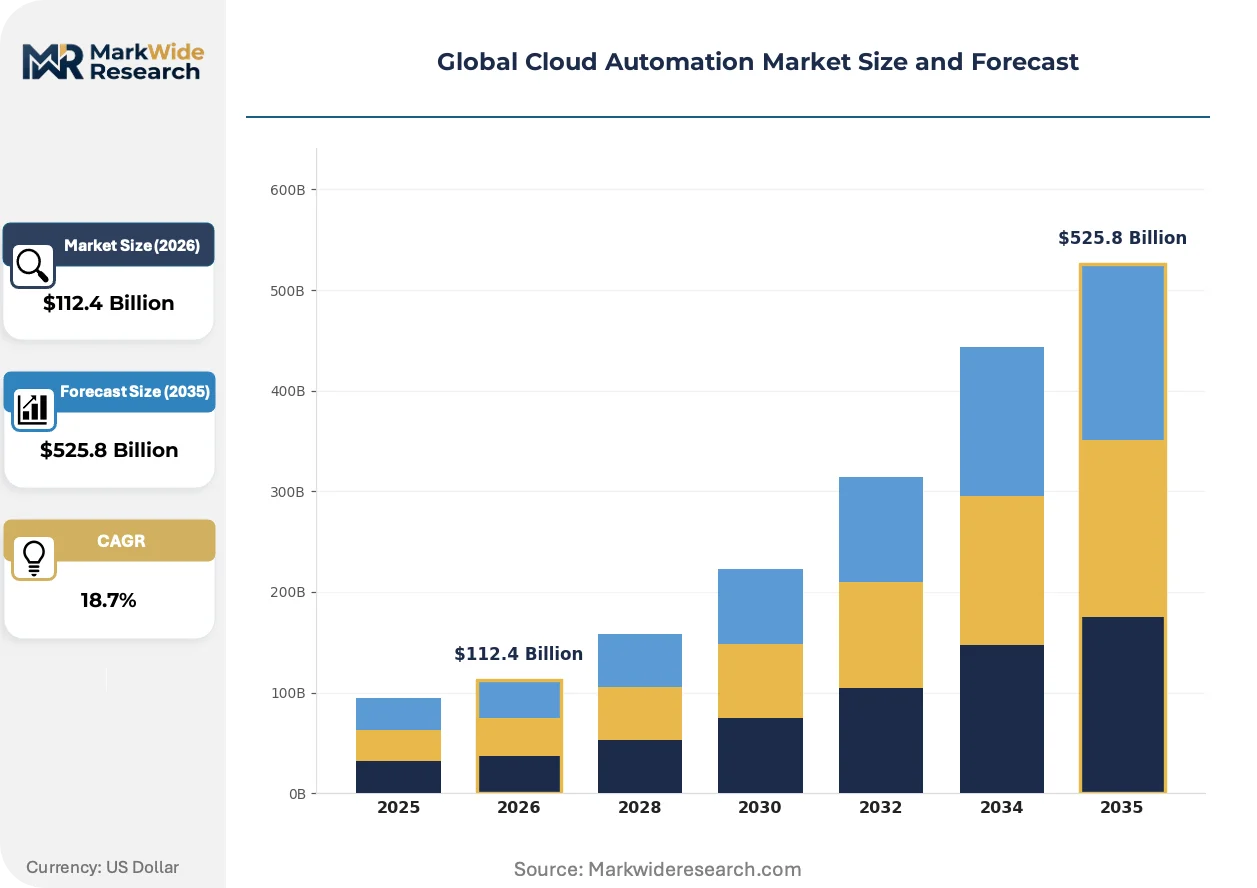
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $525.8 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Orchestration, Configuration Management, Continuous Integration, Continuous Delivery, Monitoring Application: IT Operations, Software Development, Security Automation, Network Management, DevOps End User Industry: Telecommunications, Banking & Financial Services, Media & Entertainment, Government, Education |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, Google Cloud, Broadcom Inc., Cisco Systems, Inc., VMware, Inc., HashiCorp, Inc., BMC Software, Inc., Chef Software, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Automation Market Shifts & Advancements
Agentic AI systems are displacing rule-based automation in cloud orchestration, enabling autonomous decision-making that compresses incident response from hours to minutes without human escalation.
Embedded observability telemetry is miniaturizing the feedback loop between infrastructure state and automated remediation. Platform engineering teams at hyperscale SaaS providers are adopting OpenTelemetry-native instrumentation as default architecture. This compression is miniaturizing the operational data path that separates detection from action, collapsing mean-time-to-resolution benchmarks.
The EU AI Act risk classification framework is forcing automation vendors to rearchitect opaque machine-learning-driven scaling algorithms. High-risk deployments in credit underwriting and fraud detection now require human-in-the-loop checkpoints. European banking consortia are responding by pooling resources for shared compliance tooling that amortizes certification costs across member institutions.
Consumption-based licensing for automation platforms is displacing perpetual seat models as the dominant procurement structure. Enterprise buyers in the United States are consolidating vendor relationships around usage-metered contracts that align costs with actual workload orchestration volume. This shift is most visible among Series C-stage software companies optimizing burn rates through granular cost attribution.
Global Cloud Automation Market Segmentation
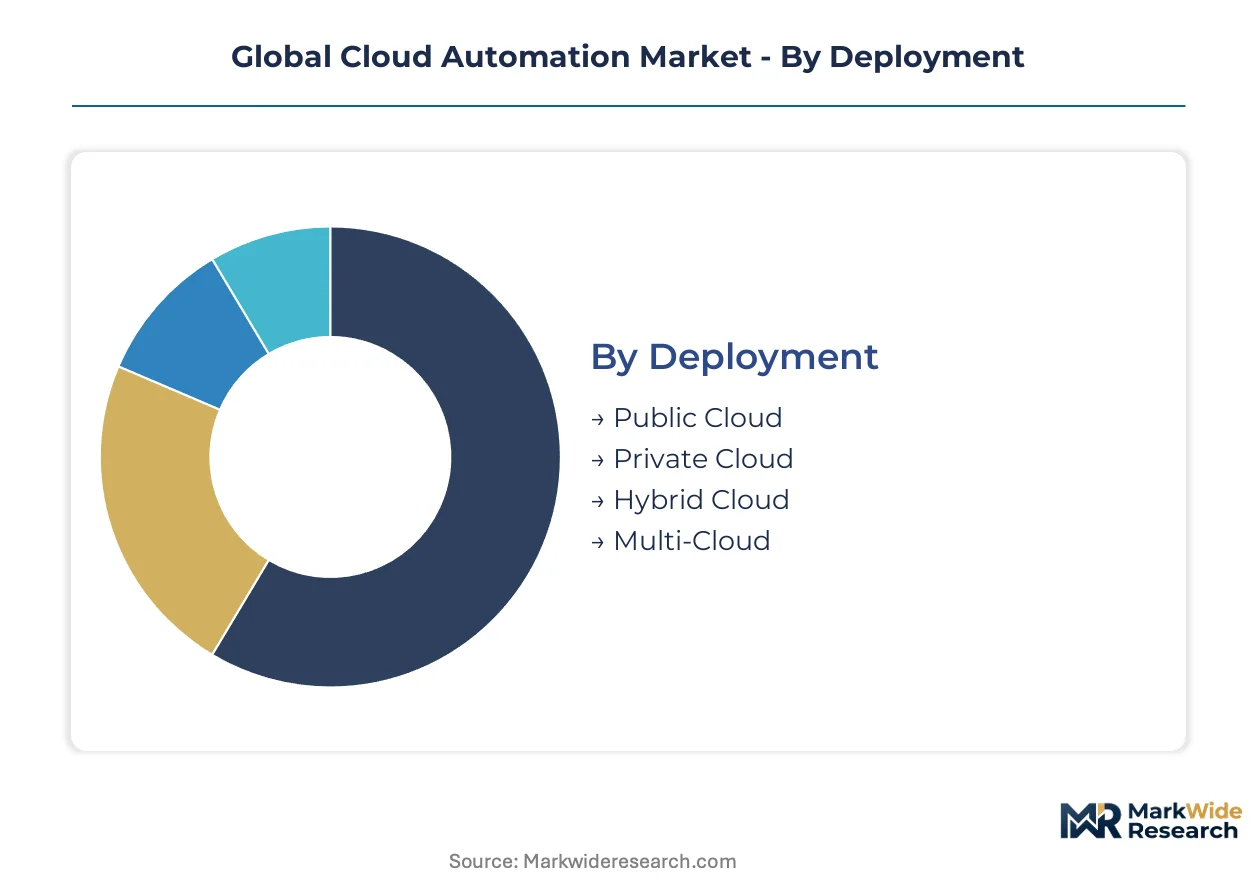
Cloud automation vendors capture divergent margin profiles across deployment architectures and solution layers. Procurement patterns reveal where enterprises prioritize premium tooling versus commoditized infrastructure abstraction.
Deployment:
Margin pools concentrate in architectures that bridge legacy infrastructure with elastic public capacity, commanding premium licensing for policy synchronization across environments.
- Public Cloud:Native API integration with hyperscale platforms enables rapid provisioning without capital expenditure. Demand concentrates among Series B-C software companies optimizing burn rates through consumption-metered contracts, though API dependency risk constrains long-term pricing power.
- Hybrid Cloud:Policy engines must reconcile on-premises governance with public elasticity, creating the steepest expansion trajectory as regulated industries straddle compliance boundaries. Financial services firms in the United States and Germany absorb the largest deployment volumes.
- Private Cloud:Sovereign data requirements drive dedicated infrastructure automation in defense and intelligence sectors.
- Multi-Cloud:Abstraction layers reduce vendor lock-in but introduce credential sprawl complexity that security teams struggle to govern.
The dominant share belongs to Hybrid Cloud, while Multi-Cloud is closing the gap fastest.
Solution Type:
Cost tier stratification separates enterprise-grade orchestration suites from open-source tooling that anchors commercial upsell funnels.
- Continuous Delivery:Pipeline automation compresses release cycles from weeks to hours through declarative configuration. United States-based SaaS providers represent the concentrated demand pool, pressured by investor expectations for velocity metrics.
- Orchestration:Workload scheduling across distributed clusters demands Kubernetes-native expertise that concentrates in North American labor markets. European banking consortia are pooling resources for shared compliance tooling that amortizes certification costs.
- Configuration Management:Infrastructure-as-code repositories enforce drift detection and automated remediation.
- Continuous Integration:Build automation precedes delivery pipelines in maturity curves.
- Monitoring:Embedded observability telemetry miniaturizes feedback loops between detection and action.
Continuous Delivery commands the dominant revenue position, though Orchestration is expanding most quickly as platform engineering teams consolidate toolchains.
Application:
Volume concentration tracks where operational headcount costs justify automation investment against manual intervention baselines.
- DevOps:Cross-functional collaboration platforms integrate pipeline orchestration with infrastructure provisioning. Technology companies in India and the United States drive procurement volume, attracted by talent arbitrage in offshore delivery centers.
- Security Automation:Policy-as-code enforcement embeds compliance guardrails directly into provisioning workflows. EU AI Act transparency mandates are accelerating European financial services adoption.
- IT Operations:Incident response automation reduces mean-time-to-recovery through codified runbooks.
- Software Development:Developer experience tooling abstracts infrastructure complexity from application teams.
- Network Management:Software-defined networking controllers automate traffic engineering across hybrid topologies.
DevOps maintains the dominant application share, while Security Automation is climbing the fastest as regulatory penalty structures intensify.
End User Industry:
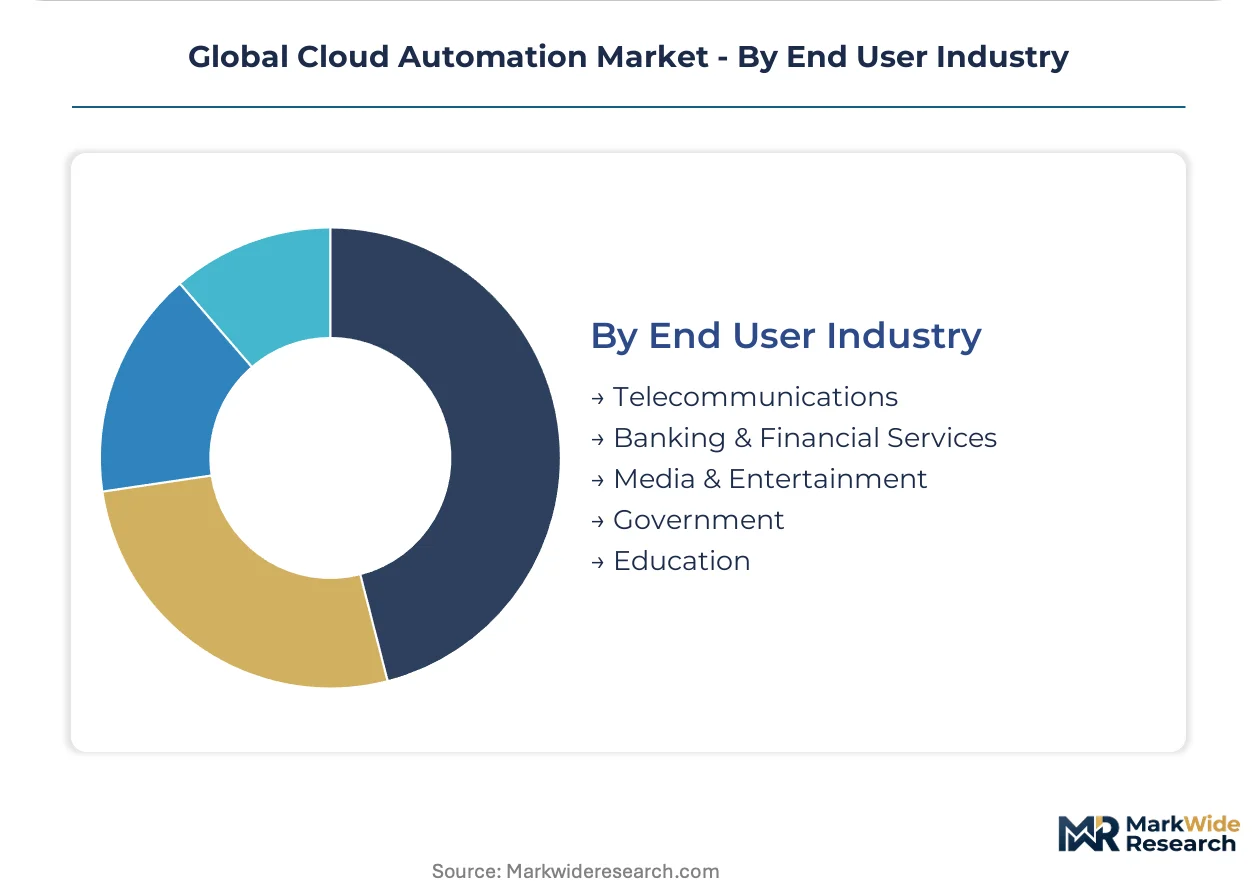
Customer type segmentation reveals where audit requirements and downtime penalties create inelastic demand for resilient automation.
- Banking & Financial Services:Core banking modernization demands API abstraction layers that expose COBOL-based systems to contemporary orchestration. ANVISA and Brazil's central bank are tightening data residency requirements that favor localized automation stacks.
- Telecommunications:5G network slicing requires edge-orchestration agents that operate with intermittent connectivity. India's PLI scheme for data center infrastructure is accelerating domestic capacity buildout and associated tooling demand.
- Government:FedRAMP and sovereign cloud mandates fragment procurement across national jurisdictions.
- Media & Entertainment:Burst compute for rendering pipelines drives consumption-based licensing adoption.
- Education:Cost constraints favor open-source tooling with commercial support tiers.
Banking & Financial Services holds the dominant margin pool, while Telecommunications is gaining share fastest as network virtualization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where hyperscale enterprises absorb premium tooling, while Indian service providers compress margins through offshore delivery arbitrage. European regulatory complexity sustains mid-market premiums. China's sovereign cloud mandates fragment procurement for foreign vendors.
United States
Hyperscale SaaS providers and financial services firms drive demand for consumption-metered automation contracts. FDA oversight of cloud-hosted clinical trial data and HIPAA enforcement shape healthcare workload requirements. Silicon Valley and Seattle clusters anchor platform engineering talent concentration.
Germany
Automotive and industrial manufacturing sectors demand Kubernetes-native orchestration for smart factory deployments. The EU AI Act and GDPR impose algorithmic accountability constraints on automated policy engines. Baden-Württemberg engineering consortia pool resources for shared compliance tooling.
India
Technology companies leverage talent arbitrage in offshore delivery centers for DevOps procurement. The PLI scheme for data center infrastructure accelerates domestic cloud capacity buildout. Mumbai and Bengaluru clusters specialize in localized automation stacks meeting data sovereignty requirements.
United Kingdom
Financial services firms in London expand automated compliance workflows under FCA scrutiny. ISO 27001 and SOC 2 Type II certifications function as market access filters for vendors. The Thames Valley corridor concentrates fintech automation adoption.
Brazil
Underpenetrated financial services automation presents expansion opportunity as ANVISA and the central bank tighten data residency requirements. Localized automation stacks gain preference over foreign platforms. São Paulo anchors transactional system modernization demand.
Global Cloud Automation Market Competitive Landscape
Concentration sits with hyperscale cloud operators who control core provisioning APIs and backward integration into infrastructure layers. Third-party tooling vendors navigate proprietary integration stacks that lock enterprise workloads. Two strategic archetypes dominate: vertically integrated platform operators and open-source-anchored commercial suites. Competitive moves center on API deprecation pressure and M&A absorption of specialized orchestration capabilities.
Within the hyperscale tier, Amazon Web Services, Inc. and Microsoft Corporation exemplify platform operators leveraging captive infrastructure control. HashiCorp, Inc. occupies a position among open-source-anchored vendors commercializing community adoption into enterprise suites. These three represent the structural fault line between API gatekeepers and abstraction-layer challengers.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Google Cloud |
| Broadcom Inc. |
| Cisco Systems, Inc. |
| VMware, Inc. |
| HashiCorp, Inc. |
| BMC Software, Inc. |
| Chef Software, Inc. |
| Others |
Supply & Pricing Matrix
Consumption-metered SaaS contracts lock in multi-year revenue visibility for automation vendors while anchoring enterprise buyers to predictable per-workload costs. This structure concentrates pricing power with hyperscale platform operators who bundle orchestration into captive infrastructure spend, forcing third-party tooling vendors toward freemium land-and-expand models that defer monetization until deployment scale.
Pricing Analysis
The customization-premium spread separates standard policy-as-code licenses from enterprise-grade managed services with embedded compliance engineering. SaaS-tiered subscription models dominate procurement, with price differentiation anchored in ISO 27001 certification tier and geographic data residency guarantees. Pricing pressure stems from open-source Terraform adoption commoditizing baseline infrastructure abstraction. Series B-C software companies exhibit highest price sensitivity, while financial services firms absorb premium tiers without elasticity.
Supply Chain Analysis
API gateway control by hyperscale operators in the United States, Ireland, and Singapore concentrates supply risk for third-party orchestration vendors. Provisioning interface dependencies draw from AWS CloudFormation, Azure Resource Manager, and Google Cloud Deployment Manager as critical inputs. Single-source vulnerability intensifies as hyperscale operators deprecate legacy API versions without notice. Distribution runs through cloud marketplaces and direct enterprise sales teams with professional services attach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed compliance-as-a-service layers expand faster than standalone automation licenses, converting capital expenditure into recurring revenue streams that improve customer lifetime value metrics. This service-attach dynamic rewards vendors who embed policy enforcement and audit remediation into subscription tiers rather than treating professional services as non-recurring add-ons.
For Market Incumbents: Compound platform stickiness by deepening Azure-native and AWS-native integration stacks that increase switching costs for enterprise workloads. Invest in FedRAMP and EU Cloud Code of Conduct certifications to defend margin position against European sovereign cloud mandates. Acquire Kubernetes-native policy engine specialists before open-source alternatives commoditize orchestration intelligence. For New Entrants and Emerging Players: Edge-orchestration agent deployment for manufacturing facilities with intermittent connectivity represents an underserved layer where incumbents lack lightweight footprint solutions. Brazil's ANVISA data residency requirements and India's PLI-scheme data center buildout create penetrable geography-application combinations. Lead with GitOps-native compliance validation as the go-to-market wedge against legacy configuration management incumbents. For Investors and Strategic Acquirers: Specialized orchestration vendors with healthcare and financial services vertical expertise command scarcity premiums as regulatory complexity intensifies. Long-term viability hinges on API abstraction durability against hyperscale backward integration pressure. Watch hyperscale capex disclosure trends as the inflection signal for third-party tooling margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepening Azure-native and AWS-native hooks increases enterprise switching costs and contract renewal rates. |
| Acquisition of Specialist Firm | Targeted buys of Kubernetes policy engine vendors preempt open-source commoditization of orchestration intelligence. |
| Geographic Expansion | Localized automation stacks in Brazil and India capture data sovereignty requirements tightening under ANVISA and RBI. |
| Product Launch | Edge-orchestration agents for intermittent connectivity open manufacturing and logistics deployment architectures. |
| Strategic Partnership | European banking consortia pooling compliance tooling amortizes certification costs across member institutions. |
Research Methodology
The analysis maps continuous delivery pipelines, orchestration engines, configuration management repositories, and security automation layers, each validated through platform engineering leads, cloud procurement officers, and DevOps directors. Primary fieldwork combined with hyperscaler capex disclosures, SEC 10-K infrastructure spend filings, and EU regulatory compliance databases enabled bottom-up and top-down triangulation across deployment models and solution types.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment architecture, solution type, application layer, and end-user industry dimensions, with CAGRs derived from policy engine adoption velocity and compliance mandate enforcement timelines. Kubernetes cluster density metrics and consumption-metered contract expansion rates served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU AI Act enforcement and FDA HIPAA oversight; material policy shifts would require re-modeling of healthcare and financial services automation demand. Practitioners should keep alternative scenarios live as sovereign cloud mandates and API deprecation schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Door and Window Automation Market
Automation
Global Direct Mail Automation Software Market
Automation
Universal Process Control Market
Automation
Europe Data Center Automation Market
Automation
Helpdesk Automation Market
Automation
Postal Automation System Market
Automation
Elevator Control Market
Automation
Global Automated Liquid Handling System Market
Automation
Global Automated Sample Storage Systems Market
Automation
Asia-Pacific Data Center Automation Market
Automation
Terminal Automation Systems Market
Automation
Global Database Automation Systems Market
Automation
Automation Testing Market
Automation
Lab Automation Market
Automation
North America Data Center Automation Market
Automation
Data Center Automation Market