
 Laboratory Automation Market | 2026-2036
Laboratory Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Automation Market Intelligence
Polymer-based microfluidic substrates are consolidating position against traditional glass and silicon alternatives in next-generation liquid handling platforms. Thermo Fisher Scientific leverages its integrated supply chain to anchor high-volume production of automated analyzers for clinical diagnostics. Danaher competes through specialized life sciences instrumentation that sustains premium positioning across biopharmaceutical workflows. Agilent Technologies dominates analytical measurement segments where precision requirements create durable customer lock-in.
Laboratory automation encompasses integrated hardware and software systems that execute repetitive experimental protocols with minimal human intervention, typically achieving throughput rates exceeding 10,000 samples daily in high-end configurations. These systems serve primarily to reduce manual error, standardize reproducibility, and accelerate data generation across pharmaceutical development and clinical testing environments. Liquid handling systems occupy the largest revenue pool among product categories, while artificial intelligence-enabled platforms represent the fastest-expanding technology segment as predictive maintenance and autonomous protocol optimization gain traction. Robotic systems maintain mature growth trajectories in genomics applications where established workflows limit disruption risk.
FDA 21 CFR Part 11 compliance requirements shape software validation protocols for electronic records in U.S. clinical laboratories, while EMA's In Vitro Diagnostic Regulation mandates performance documentation that elevates barriers for non-European equipment suppliers. ISO 15189 accreditation standards further dictate quality management systems for automated diagnostic platforms in medical testing facilities. Stakeholders must monitor evolving cross-border data governance frameworks as cloud-connected instruments proliferate across multinational research networks.
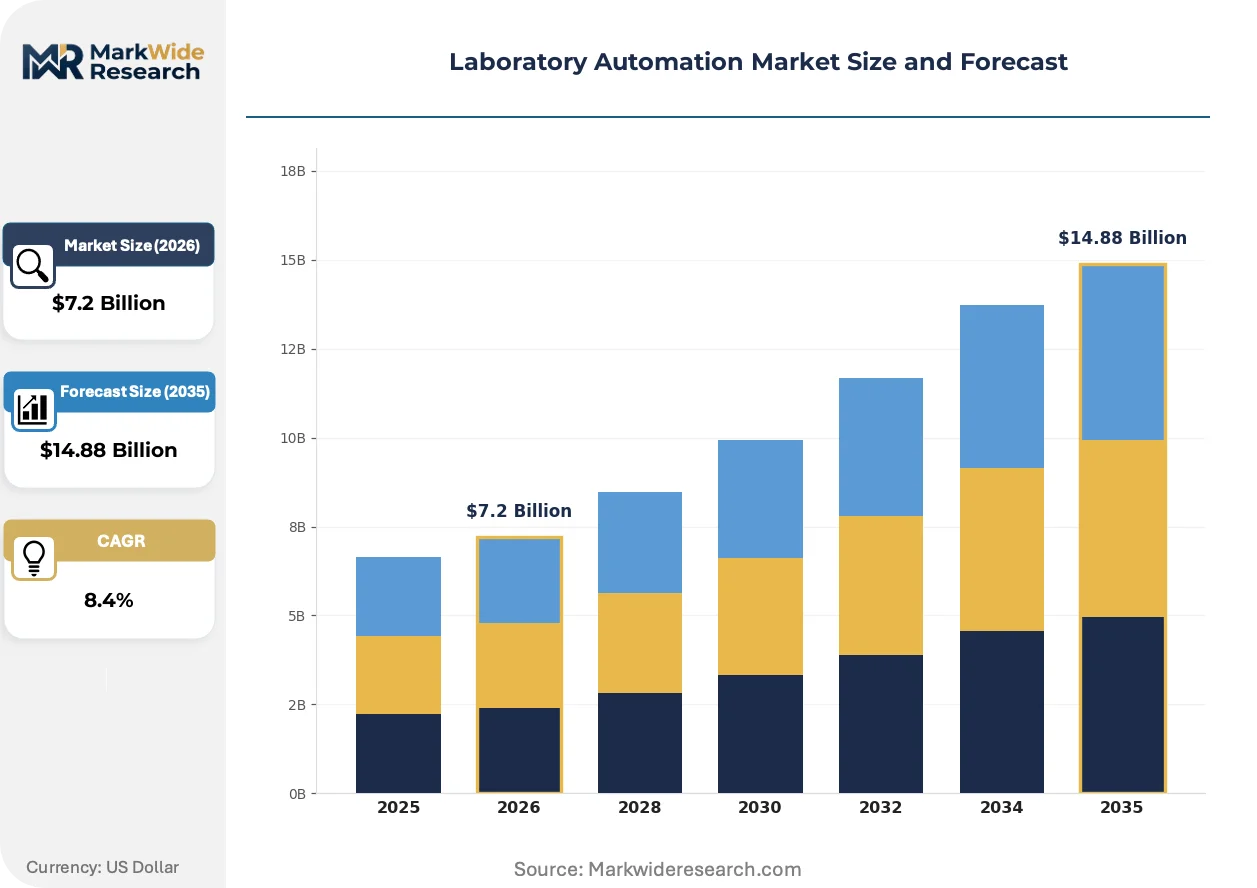
Market Dynamics
Biopharmaceutical pipeline acceleration is compressing validation timelines for automated liquid handling platforms, forcing equipment suppliers to front-load FDA 21 CFR Part 11 compliance documentation before hardware deployment.
Growth Catalysts
- FDA diagnostic platform mandates:Tightened validation requirements for clinical analyzers create replacement cycles for non-compliant legacy systems in US reference laboratories.
- Polymer microfluidic substrates:Lower-cost fabrication methods for disposable labware expand accessible automation to mid-tier research institutions previously priced out of glass-and-silicon platforms.
- Precision medicine research clusters:Concentrated investment in Germany, the United States, and China generates sustained procurement of high-throughput screening infrastructure.
Market Restraints
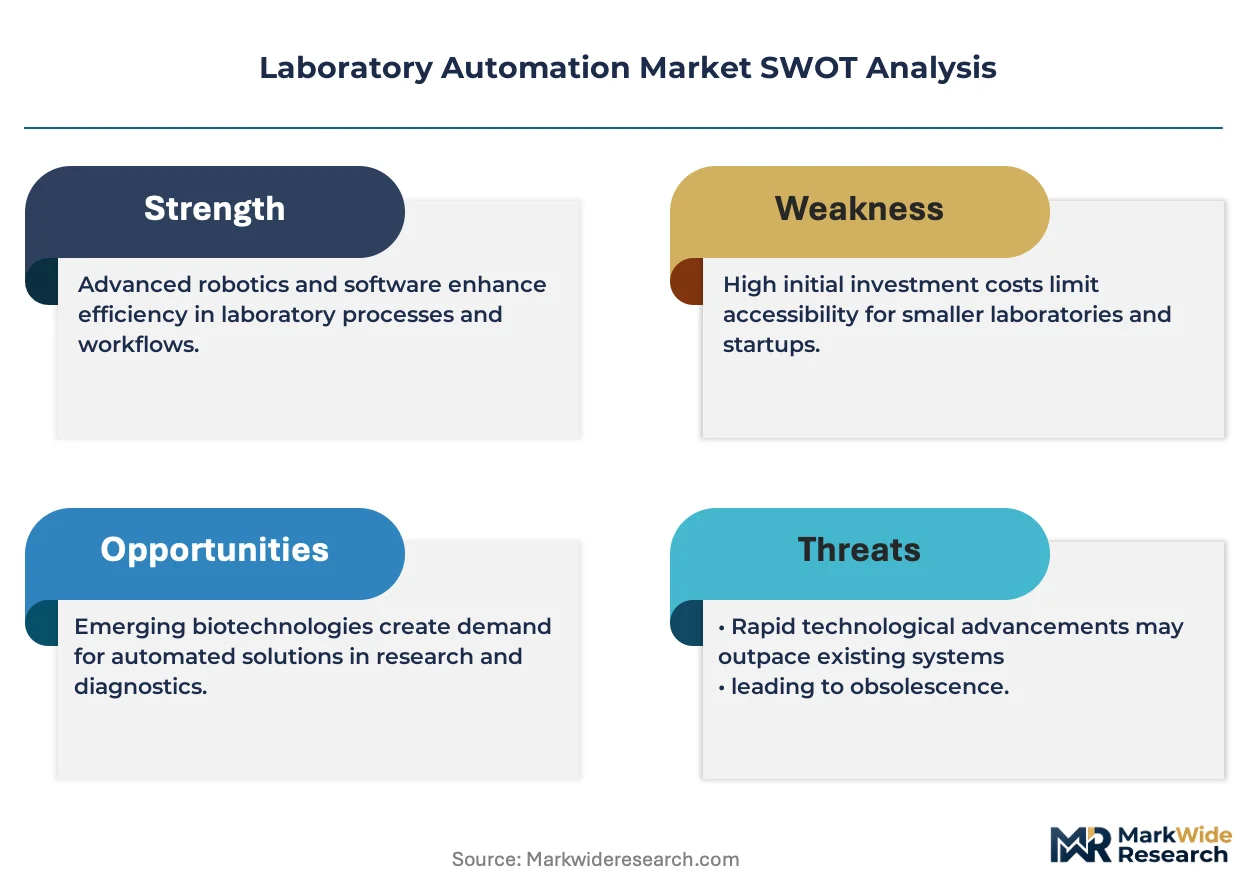
- Capital intensity barriers:Automated workstation deployment requires seven-figure upfront investment, excluding smaller contract research organizations from self-owned infrastructure.
- Specialized component concentration:Precision linear motion systems and optical sensors concentrate supply among German and Japanese component specialists, exposing lead time risk.
- Glass substrate persistence:Silicon and borosilicate glass retain dominance in applications requiring chemical inertness that polymer alternatives cannot yet match.
Strategic Opportunities
- Cloud-connected instrument proliferation:Multinational research networks generate demand for automated platforms with native data federation capabilities spanning US, EU, and Chinese jurisdictions.
- Artificial intelligence protocol optimization:Predictive maintenance algorithms reduce unplanned downtime in continuous-operation bioprocessing facilities.
- Indian pharmaceutical manufacturing:CDSCO regulatory harmonization efforts position domestic producers for export-oriented automated quality control expansion.
Industry Challenges
- Mechatronics talent scarcity:Integration of precision robotics with biological assay protocols requires hybrid skill sets that outpace vocational training pipeline output.
- Multi-jurisdiction validation complexity:Simultaneous FDA, EMA, and NMPA approval pathways extend time-to-revenue for new platform launches by eighteen to thirty-six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Automation Market |
| Market Size in 2026 | $7.2 Billion |
| Market Size in 2035 | $14.88 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Handling Systems, Robotic Systems, Automated Analyzers, Software Solutions End User: Biopharmaceutical Companies, Academic Institutions, Clinical Laboratories, Contract Research Organizations Application: Drug Discovery, Clinical Diagnostics, Genomics, Proteomics Technology: Microfluidics, Robotics, Cloud Computing, Artificial Intelligence |
| Companies Covered | Agilent Technologies, F. Hoffmann-La Roche, Thermo Fisher Scientific, PerkinElmer, Siemens Healthineers, Danaher, Abbott Laboratories, Hamilton Company, Tecan Trading, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Automation Market Strategic Shifts & Innovations
Artificial intelligence is embedding into laboratory automation at the control layer, shifting competitive advantage from hardware precision to software-driven protocol intelligence and predictive system management.
Modular liquid handling architectures are decentralizing experimental workflow design. Biopharmaceutical process development teams now reconfigure workstation layouts weekly rather than annually. Thermo Fisher and Danaher both field configurable platforms that reduce changeover downtime from days to hours. This flexibility is compressing early-phase drug screening timelines.
EMA's In Vitro Diagnostic Regulation is elevating performance documentation burdens for non-European equipment suppliers. The regulation mandates clinical evidence packages that many Asian manufacturers lack resources to assemble. US and Swiss automation vendors with established European notified body relationships are capturing share in EU clinical diagnostics procurement.
Service contract unbundling is fragmenting buyer-vendor relationships. Large pharmaceutical operators now source preventive maintenance from third-party specialists rather than original equipment manufacturers. This shift is most visible in the United States, where contract research organizations operate mixed-vendor automation fleets that resist single-source service lock-in.
Laboratory Automation Market Segmentation
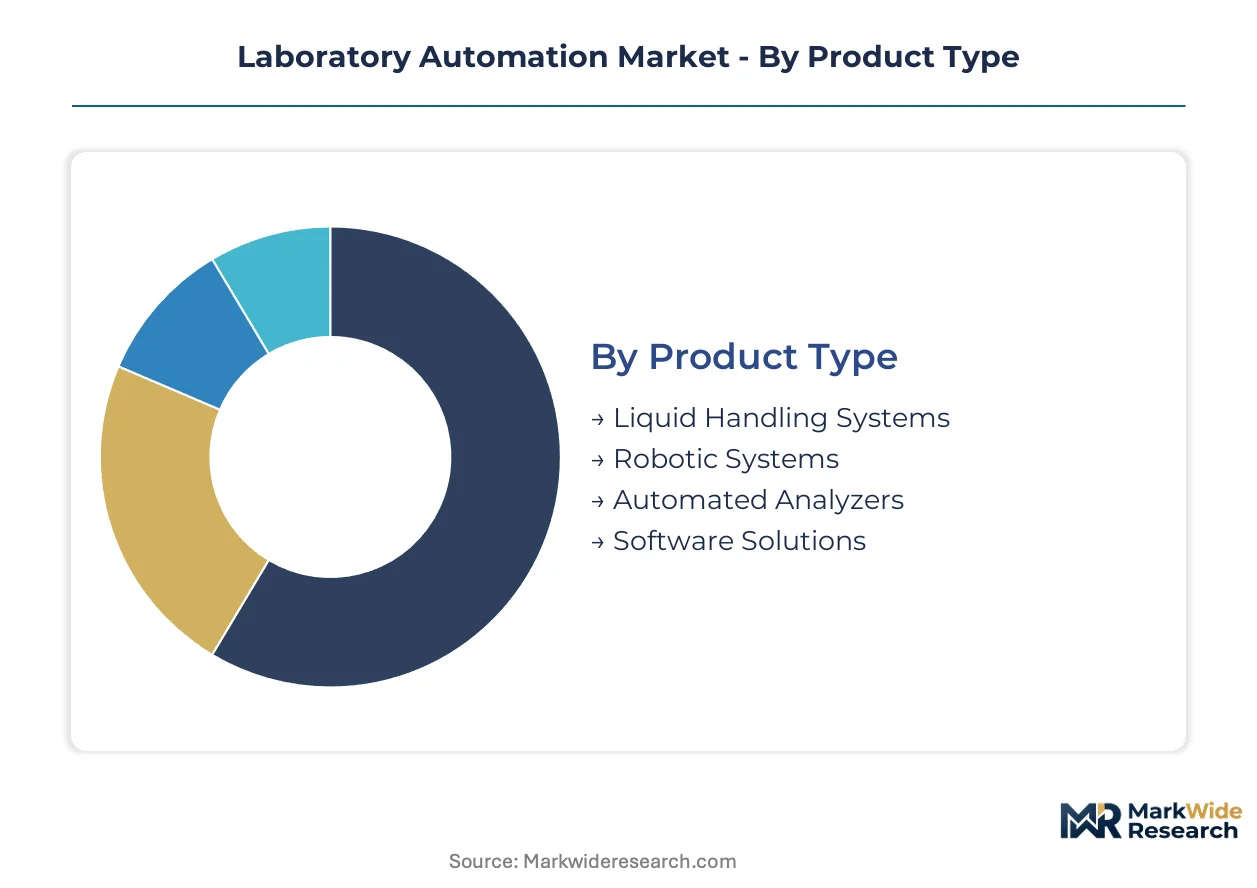
Laboratory automation vendors configure product portfolios around distinct procurement patterns. Biopharmaceutical buyers prioritize throughput and compliance documentation. Academic purchasers emphasize modular flexibility and capital efficiency. Clinical laboratories demand integrated diagnostic workflows with native regulatory validation.
Product Type:
Replacement cycles accelerate as FDA 21 CFR Part 11 documentation requirements render pre-2020 hardware obsolete in US clinical settings.
- Liquid Handling Systems:Precision pipetting workstations with sub-microliter accuracy dominate high-throughput screening installations. Demand concentrates in Germany and the United States where biopharmaceutical clusters deploy 10,000+ sample daily configurations. Polymer microfluidic disposables are displacing glass cuvettes in mid-tier research budgets.
- Robotic Systems:Articulated arm platforms integrate plate handling with incubator access for continuous cell culture monitoring. Academic institutions in China represent the fastest-expanding installed base as national precision medicine initiatives fund infrastructure expansion. Linear motion components from German and Japanese suppliers constrain delivery timelines.
- Automated Analyzers:Clinical chemistry and immunoassay platforms with native LIS connectivity serve reference laboratories.
- Software Solutions:Protocol design suites with AI-assisted optimization reduce method development cycles in bioprocessing facilities.
Liquid Handling Systems sits at the top of the volume ranking, with Software Solutions climbing the fastest.
End User:
Procurement authority varies sharply across customer types, with biopharmaceutical capital budgets dwarfing academic grant-funded purchases.
- Biopharmaceutical Companies:Integrated automation suites compress IND-enabling study timelines from months to weeks. US and Swiss headquarters locations concentrate decision-making for global deployment. Thermo Fisher and Danaher capture recurring revenue through multi-year service contracts.
- Contract Research Organizations:Mixed-vendor fleets demand interoperable software layers and third-party maintenance providers. Indian pharmaceutical manufacturing expansion positions domestic CROs for automated quality control investment as CDSCO harmonizes with ICH standards. Capital constraints exclude smaller operators from self-owned infrastructure.
- Academic Institutions:Core facility shared-access models spread capital burden across multiple principal investigators.
- Clinical Laboratories:EMA In Vitro Diagnostic Regulation compliance elevates documentation burdens for equipment selection.
Biopharmaceutical Companies generate the dominant revenue share, with Contract Research Organizations expanding most quickly.
Application:
Protocol complexity and regulatory scrutiny create divergent margin profiles across use cases.
- Drug Discovery:High-throughput screening campaigns require 24/7 operation with predictive maintenance algorithms minimizing unplanned downtime. Genomics workflows in US coastal clusters sustain premium pricing for integrated platforms. Artificial intelligence protocol optimization reduces compound library screening costs.
- Clinical Diagnostics:FDA diagnostic platform mandates force replacement of legacy systems lacking 21 CFR Part 11 electronic records validation. European reference laboratories favor US and Swiss vendors with established notified body relationships. EMA performance documentation requirements exclude many Asian suppliers.
- Genomics:Next-generation sequencing sample preparation drives demand for walkaway automation.
- Proteomics:Mass spectrometry front-end automation standardizes sample digestion and fractionation.
Drug Discovery commands the largest installed base, with Clinical Diagnostics gaining share fastest.
Technology:
Competitive advantage is migrating from mechanical precision to software-driven intelligence and predictive system management.
- Artificial Intelligence:Machine learning algorithms embedded at the control layer enable autonomous protocol optimization and anomaly detection. Cloud-connected instruments across multinational research networks generate training datasets for predictive maintenance models. Bioprocessing facilities in Germany and the United States deploy these capabilities for continuous operation.
- Microfluidics:Polymer-based substrates achieve cost structures that expand automation access to mid-tier institutions previously priced out of glass-and-silicon platforms. Chinese precision medicine research centers represent concentrated demand for disposable labware with integrated reagent storage.
- Robotics:Precision linear motion systems from specialized component suppliers create supply concentration risk.
- Cloud Computing:Native data federation capabilities span US, EU, and Chinese jurisdictional requirements for cross-border research collaboration.
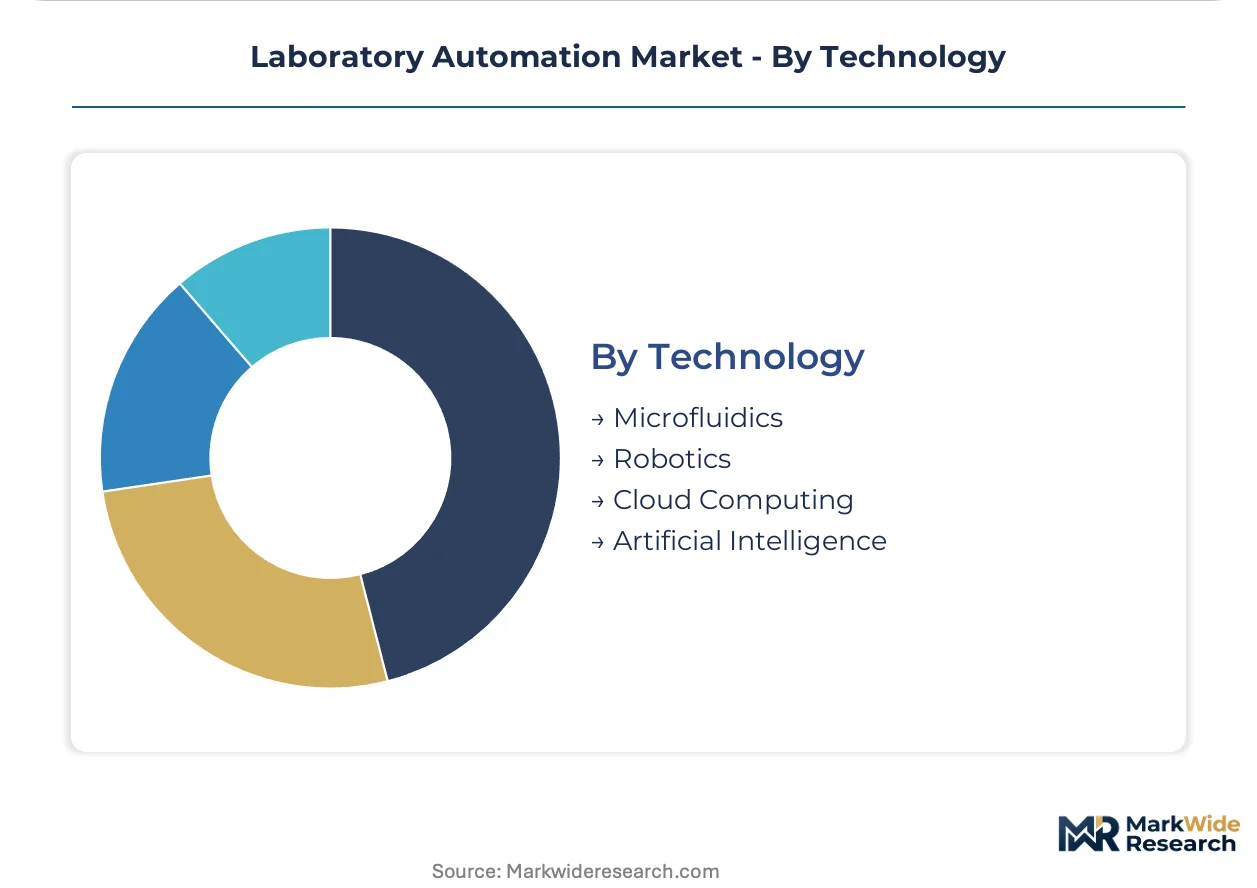
Robotics maintains the deepest installed base, with Artificial Intelligence demonstrating the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-throughput screening clusters in the United States, Germany, and China concentrate procurement of precision liquid handling infrastructure. Biopharmaceutical pipeline acceleration and diagnostic platform mandates reshape equipment deployment timelines across these markets. Regulatory validation requirements from FDA, EMA, and NMPA create divergent compliance burdens for automation vendors.
United States
FDA 21 CFR Part 11 compliance deadlines force replacement cycles for legacy diagnostic analyzers in reference laboratories. The Inflation Reduction Act provisions accelerate domestic biomanufacturing capacity expansion. Greater Boston and San Francisco Bay Area clusters sustain premium pricing for integrated automation suites serving cell therapy workflows.
Germany
EMA In Vitro Diagnostic Regulation elevates performance documentation burdens for equipment selection in European reference laboratories. The Medical Device Regulation mandates clinical evidence packages that favor established notified body relationships. Baden-Württemberg precision engineering suppliers constrain delivery timelines for linear motion components critical to robotic platforms.
China
NMPA regulatory harmonization with ICH standards positions domestic pharmaceutical manufacturers for automated quality control expansion. National precision medicine initiatives fund infrastructure deployment in research centers. Yangtze River Delta biotech clusters represent the fastest-expanding installed base for walkaway genomics sample preparation systems.
Switzerland
Swissmedic validation requirements for diagnostic platforms create procurement preference for vendors with established European regulatory documentation. The country's pharmaceutical headquarters concentration centralizes decision-making for global automation deployment. Basel-area biopharmaceutical operators compress IND-enabling study timelines through integrated liquid handling suites.
India
CDSCO regulatory harmonization efforts with ICH standards enable export-oriented automated quality control investment from domestic contract manufacturers. Production-linked incentive schemes for pharmaceutical manufacturing expand accessible automation to mid-tier research institutions. Maharashtra and Gujarat pharmaceutical manufacturing corridors concentrate demand for polymer microfluidic disposables.
Laboratory Automation Market Key Industry Players
Global majors compete with regional champions across regulatory documentation capabilities and service network density. The vendor base organizes around three tiers: integrated life sciences conglomerates with captive diagnostics distribution, specialized automation houses with precision robotics heritage, and emerging platform vendors leveraging polymer microfluidic cost structures. Consolidation pressure intensifies as FDA and EMA validation timelines extend time-to-revenue for new entrants. Strategic moves center on multi-jurisdiction regulatory pre-certification and third-party service contract capture.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Danaher occupy positions anchored by recurring revenue through multi-year service contracts and multi-product portfolio leverage. Agilent Technologies exemplifies the analytical measurement specialist archetype where precision requirements create durable customer relationships. Hamilton Company represents the precision robotics heritage segment with specialized liquid handling expertise. These three anchors demonstrate how competitive advantage migrates from hardware precision toward software-driven protocol intelligence and predictive system management.
| Leading Market Players |
|---|
| Agilent Technologies |
| F. Hoffmann-La Roche |
| Thermo Fisher Scientific |
| PerkinElmer |
| Siemens Healthineers |
| Danaher |
| Abbott Laboratories |
| Hamilton Company |
| Tecan Trading |
| Others |
Cost & Logistics Intelligence
Mechatronics engineering talent concentrated in Baden-Württemberg and Bavaria commands wage premiums that propagate through three-tier pricing structures separating FDA-validated clinical platforms from research-grade workstations and entry-level modular systems. Labor-cost differentials between German precision component specialists and Asian assembly operations create tier spreads exceeding fifty percent at equivalent performance specifications.
Pricing Analysis
Input-cost pass-through from precision linear motion systems and optical sensors anchors pricing stratification across premium, standard, and economy tiers. FDA 21 CFR Part 11 certification grade and ISO 15189 accreditation status drive price differentiation between clinical diagnostic and research-only configurations. Cost compression in the mid-tier research segment intensifies as polymer microfluidic substrates displace glass alternatives. Academic core facilities exhibit highest price sensitivity; biopharmaceutical quality control departments demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Photoresist-grade borosilicate glass and precision linear encoders rest on Japanese and German specialty component producers. German precision engineering houses, Japanese optical sensor manufacturers, and Chinese polymer substrate fabricators constitute the tripartite supplier base. Single-source vulnerability concentrates in harmonic drive actuators and sub-micron positioning stages. Distribution runs through authorized service networks with captive spare parts warehousing rather than open-channel component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory automation functions as a stable compounder underpinned by regulatory compliance mandates that force predictable replacement cycles regardless of macroeconomic conditions. FDA and EMA validation timelines create durable revenue visibility for incumbent vendors.
For Market Incumbents: Acquire cloud-native software stacks with native data federation capabilities spanning US, EU, and Chinese jurisdictional requirements. Consolidate third-party service contract providers to capture recurring revenue streams that pharmaceutical operators currently fragment across independent maintenance specialists. Defensive positioning against modular platform disruptors demands backward integration into polymer microfluidic disposable production.
For New Entrants and Emerging Players: Mid-tier contract research organizations in India represent the most penetrable buyer archetype as CDSCO harmonization with ICH standards accelerates automated quality control investment. Capital-constrained academic core facilities in China offer second entry point through polymer-based disposable labware with integrated reagent storage. Go-to-market execution should emphasize interoperable software layers that accommodate mixed-vendor fleet environments.
For Investors and Strategic Acquirers: Biopharmaceutical conglomerates with captive diagnostics distribution represent the most active acquirer category in this space. Five-to-ten year viability framing favors precision robotics heritage firms with established notified body relationships across FDA, EMA, and NMPA jurisdictions. Acquisition target archetype: specialized automation houses with validated AI protocol optimization modules. Watch NMPA regulatory harmonization velocity as inflection indicator for Chinese market expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Regulatory Pre-Certification | FDA, EMA, and NMPA parallel submissions compress time-to-revenue for new platform launches. |
| AI Protocol Optimization Module Development | Predictive maintenance algorithms reduce unplanned downtime in continuous-operation bioprocessing facilities. |
| Polymer Microfluidic Substrate Manufacturing Scale-Up | Lower-cost fabrication expands automation access to mid-tier research institutions previously priced out. |
| Third-Party Service Contract Consolidation | Captive maintenance revenue streams resist fragmentation as pharmaceutical operators unbundle OEM service relationships. |
| Cloud-Native Data Federation Platform Integration | Native cross-border compliance capabilities address multinational research network governance requirements. |
Research Approach
Direct dialogue with biopharmaceutical process development directors, clinical laboratory quality managers, regulatory affairs specialists at automation vendors, and precision component procurement leads grounded qualitative assessments. Secondary validation drew from FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, ISO 15189 accreditation databases, and customs records for linear motion system imports. Bottom-up instrumentation unit economics triangulated against top-down biopharmaceutical capital expenditure surveys.
Bottom-up modeling of liquid handling workstation deployments, robotic system installations, and software license renewals across biopharmaceutical, academic, and clinical end-use segments anchored value projections. Segmentation dimensions encompassed product type, end-user category, application area, and technology layer including AI-enabled versus conventional control architectures. CAGRs derived from regression analysis of historical procurement cycles adjusted for regulatory mandate acceleration effects. Forecast inputs incorporated precision medicine research funding trajectories and diagnostic platform replacement timelines.
Inputs from EMA notified body guidance releases and NMPA harmonization bulletins were available through the study window; gaps in real-time CDSCO implementation schedules introduce uncertainty bands for Indian market expansion velocity. Forecasts reflect documented assumptions regarding regulatory timeline adherence and polymer substrate cost reduction curves. Supply chain disruption from German-Japanese component concentration and mechatronics talent scarcity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Cloud Automation Market
Automation
Global Zig-Bee Automation Market
Automation
Global Process Automation and Instrumentation Market
Automation
Database Automation Market
Automation
Workflow Automation Market
Automation
Marketing Automation Solutions Market
Automation
US Workload Scheduling and Automation Market
Automation
Automation-As-A-Service Market
Automation
United States Laboratory Automation Market
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
Dropshipping Automation Software Market
Automation
Retail Automation Market
Automation
Global Business Process Automation Software Market
Automation
Home Automation System Market
Automation
Data Center Automation Market
Automation
Global Direct Mail Automation Software Market