
 Global Field Force Automation Market | 2026-2036
Global Field Force Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Field Force Automation Market Foresight
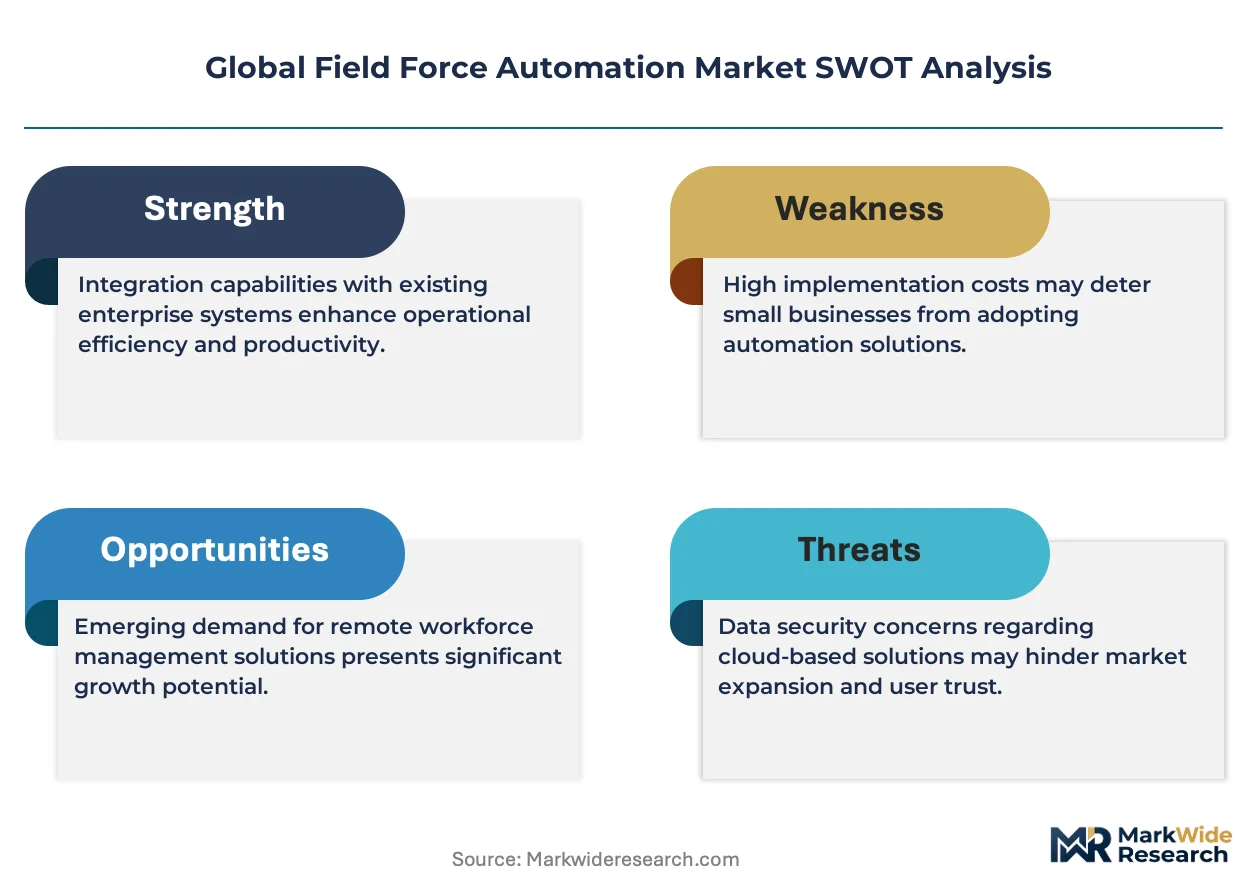
A capital-intensity divergence between cloud-native specialists and legacy ERP incumbents is rotating competitive advantage toward platform ecosystems with embedded AI. SAP SE leverages its S/4HANA field service module to anchor enterprise manufacturing clients in Germany and Japan. Salesforce, Inc. sustains dominance in telecommunications through its Service Cloud integration with 5G rollout programs across multiple continents. Microsoft Corporation competes by extending Azure IoT capabilities into edge-computing field deployments for utility infrastructure operators.
Field force automation encompasses software platforms that coordinate mobile workers through real-time scheduling, GPS-based dispatch, and offline-capable mobile applications with sub-second synchronization protocols. These systems serve industrial and commercial purposes by minimizing travel time, ensuring regulatory compliance documentation, and reducing mean-time-to-repair for critical infrastructure. Cloud-based deployment leads in new implementations due to lower upfront infrastructure requirements and faster scaling across dispersed workforces. Route optimization within the solution-type category captures concentrated margin pools as fuel costs and carbon accounting intensify client willingness to pay for algorithmic efficiency. Asset tracking is accelerating fastest among utilities and telecommunications firms managing geographically distributed equipment with predictive maintenance mandates.
The EU AI Act and GDPR impose algorithmic transparency requirements on automated scheduling and worker-rating systems deployed across European member states. India's TRAI mandates location-tracking accuracy standards for telecommunications field crews, while the CEA enforces cyber-hardening protocols for grid-connected mobile devices. ISO 55000 asset management standards and IEC 62443 industrial cybersecurity frameworks shape product certification requirements for vendors seeking utility procurement contracts. Stakeholders must monitor how emerging AI liability regulations in multiple jurisdictions redefine vendor accountability for automated dispatch decisions affecting worker safety and service-level agreements.
Market Dynamics
Cloud-native architectures are displacing on-premise field service management stacks as utilities and telecommunications operators prioritize real-time synchronization across distributed workforces. GDPR and EU AI Act compliance mandates are accelerating procurement toward vendors with embedded algorithmic transparency.
Growth Catalysts
- Grid Modernization Directives:India's CEA mandates cyber-hardened mobile devices for state utility crews, forcing digitization of legacy paper-based dispatch systems.
- 5G Network Rollouts:Telecommunications infrastructure expansion across Germany, Japan, and Brazil requires GPS-accurate crew coordination platforms with offline-capable field applications.
- ISO 55000 Certification:Asset-intensive industries in Australia and Canada now require predictive maintenance documentation standards that only integrated field automation platforms can deliver.
Market Restraints
- Semiconductor Supply Concentration:Edge-computing hardware for field devices depends on concentrated Taiwan-based foundry capacity, creating procurement bottlenecks.
- EU AI Act Compliance Costs:Algorithmic transparency requirements for automated worker scheduling impose documentation burdens that inflate implementation timelines.
- Legacy ERP Lock-in:Manufacturing clients in Germany and Japan face high switching costs from decades-old SAP deployments, slowing cloud migration velocity.
Strategic Opportunities
- India's PLI Digital Infrastructure:Production-linked incentives for domestic software development create localized vendor opportunities serving state electricity boards.
- AR-Enabled Remote Assistance:Convergence of augmented reality glasses with field service platforms allows senior technicians to guide junior crews without travel.
- Carbon Accounting Integration:Route optimization modules that document fuel savings are capturing premium pricing from European utilities under CSRD disclosure rules.
Industry Challenges
- Cybersecurity Skill Scarcity:IEC 62443 certification for industrial field devices requires scarce embedded security engineering talent, extending vendor development cycles.
- Multi-Protocol Integration:Utility operators demand seamless data flow between proprietary SCADA systems and modern mobile platforms, creating brittle custom middleware requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Field Force Automation Market |
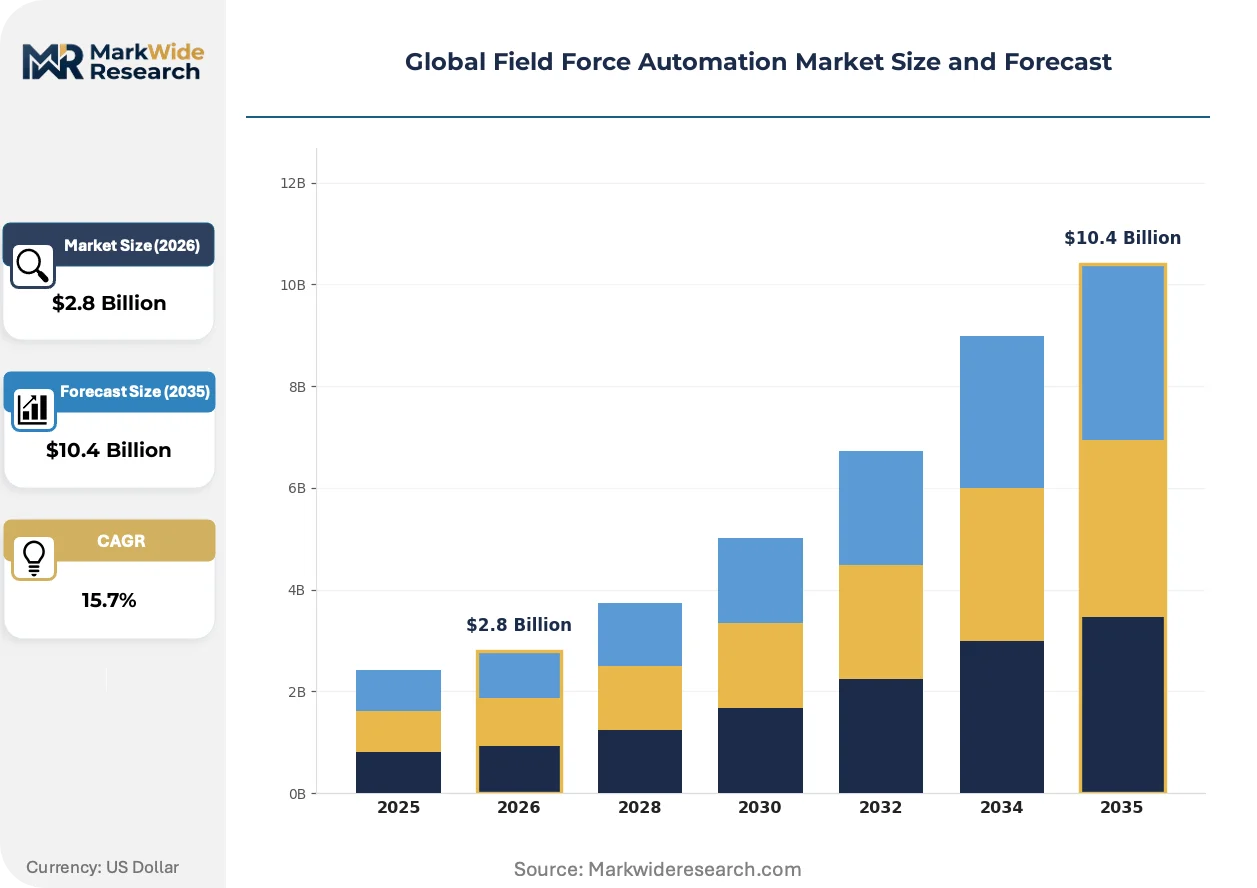
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Workforce Scheduling, Mobile Reporting, Route Optimization, Asset Tracking, Performance Analytics Application: Telecommunications, Utilities, Pest Control, Field Maintenance, Public Safety End User: Service Providers, Facility Management, Infrastructure Operators, Inspection Agencies, Supply Chain Coordinators |
| Companies Covered | SAP SE, ServiceMax, Inc., Salesforce, Inc., Trimble Inc., PTC Inc., Oracle Corporation, IFS AB, Acumatica, Inc., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Field Force Automation Market Shifts & Advancements
Edge-computing architectures are rewriting field data processing economics by enabling sub-second decision-making without cloud round-trips. Vendors are racing to embed AI inference directly into ruggedized field devices.
Embedded AI chips in ruggedized tablets and handhelds are displacing cloud-dependent dispatch algorithms for time-critical repair scenarios. Telecommunications field crews in South Korea and Australia are deploying these devices for real-time fault isolation. The shift compresses mean-time-to-repair metrics while reducing cellular data costs in remote coverage zones.
The EU AI Act's risk-classification framework is forcing vendors to document training data provenance for automated scheduling algorithms. European utilities now require algorithmic impact assessments before procurement approval. German grid operators are responding by demanding vendor-provided transparency documentation as a standard contract term.
Outcome-based service contracts are replacing perpetual software licenses among North American utilities seeking to align vendor payments with uptime metrics. Salesforce and Microsoft have restructured enterprise agreements to capture recurring revenue from performance-linked field service outcomes. This model concentrates fastest in California and Texas markets where regulatory pressure on operational expenditure transparency intensifies.
Global Field Force Automation Market Segmentation
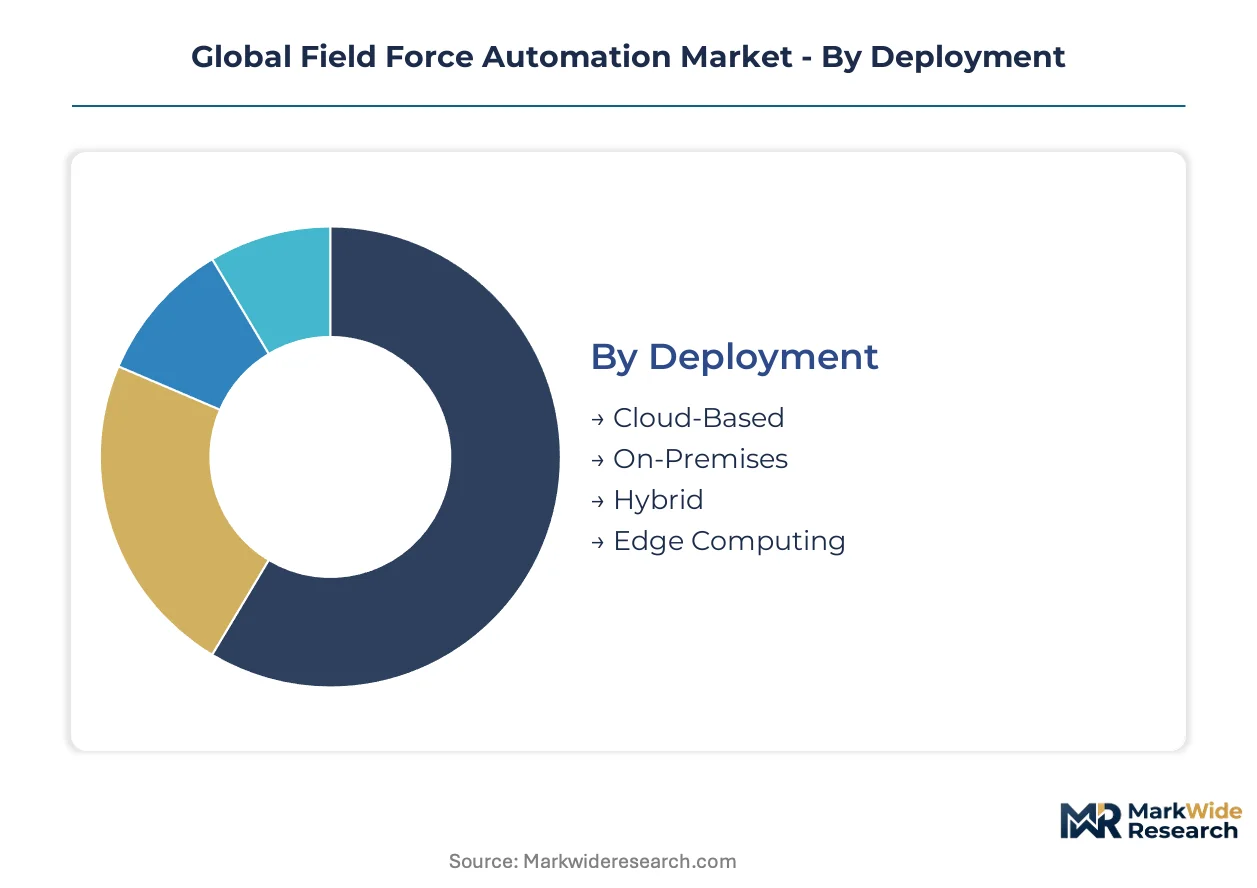
Field force automation vendors architect product portfolios around deployment economics, solution depth, and vertical compliance requirements. Segmentation choices directly determine pricing power, implementation complexity, and regulatory exposure across utility, telecommunications, and public infrastructure markets.
Deployment:
GDPR and EU AI Act algorithmic transparency mandates are tilting procurement toward architectures with embedded compliance documentation.
- Cloud-Based:Multi-tenant SaaS platforms with automatic patching and centralized audit logging dominate new utility implementations. European grid operators in Germany and France prioritize vendors with EU-hosted data residency and pre-packaged GDPR impact assessments.
- Edge Computing:Ruggedized field devices with embedded AI inference chips enable sub-second dispatch decisions without cellular backhaul. Telecommunications crews in South Korea and Australia deploy these for remote fault isolation where cloud latency risks service-level penalties.
- Hybrid:Split architectures keep sensitive worker data on-premise while routing non-critical analytics to public cloud. Japanese manufacturing clients favor this model to satisfy METI data localization guidance without sacrificing scalability.
- On-Premises:Legacy air-gapped installations persist among defense contractors and nuclear facility operators with IEC 62443 Zone 4 security requirements. High upfront capital and dedicated IT staffing limit this model to regulated critical infrastructure.
Cloud-Based handles the majority of throughput; Edge Computing is the fastest mover on share.
Solution Type:
Margin concentration follows fuel cost volatility and carbon disclosure pressure in European markets.
- Route Optimization:Algorithmic scheduling engines minimize travel distance and fuel consumption while generating auditable carbon savings documentation. CSRD-mandated Scope 1 reporting in France and Italy drives premium pricing for modules with embedded emissions calculation.
- Asset Tracking:GPS and RFID-enabled inventory visibility supports predictive maintenance workflows for geographically distributed equipment. Australian mining operators and Canadian pipeline utilities require ISO 55000-compliant audit trails that only integrated platforms deliver.
- Workforce Scheduling:Real-time dispatch coordination with union rule enforcement and fatigue management algorithms. US-based field service contractors prioritize OSHA-compliant shift-limiting features.
- Mobile Reporting:Offline-capable forms with photographic evidence capture and digital signature validation. Inspection agencies in Brazil and Mexico deploy these for regulatory documentation in cellular dead zones.
- Performance Analytics:Dashboards correlating technician efficiency with customer satisfaction and revenue per visit. Facility management firms in Singapore and Dubai use these to benchmark subcontractor performance.
Route Optimization commands the highest per-seat pricing; Asset Tracking is expanding most quickly among utilities with predictive maintenance mandates.
Application:
Vertical-specific compliance regimes fragment vendor specialization and certification requirements.
- Utilities:Grid modernization drives demand for cyber-hardened mobile platforms with CEA-mandated device hardening. Indian state electricity boards represent concentrated procurement volume under PLI-linked digitization timelines.
- Telecommunications:5G infrastructure rollouts require GPS-accurate crew coordination with offline field applications. TRAI location-tracking accuracy standards in India and equivalent mandates in Germany shape product specifications.
- Field Maintenance:Industrial asset upkeep with work-order-triggered parts procurement and warranty documentation. German automotive suppliers integrate these with existing SAP S/4HANA deployments.
- Public Safety:Emergency response coordination with encrypted radio integration and chain-of-custody evidence handling. US municipal fire departments and ambulance services drive specialized ruggedized hardware demand.
- Pest Control:Route-dense service models with chemical application logging and residential customer notification. UK and Australian operators lead adoption of customer-facing arrival-time prediction.
Utilities anchor procurement volume; Telecommunications shows the steepest expansion trajectory on infrastructure investment cycles.
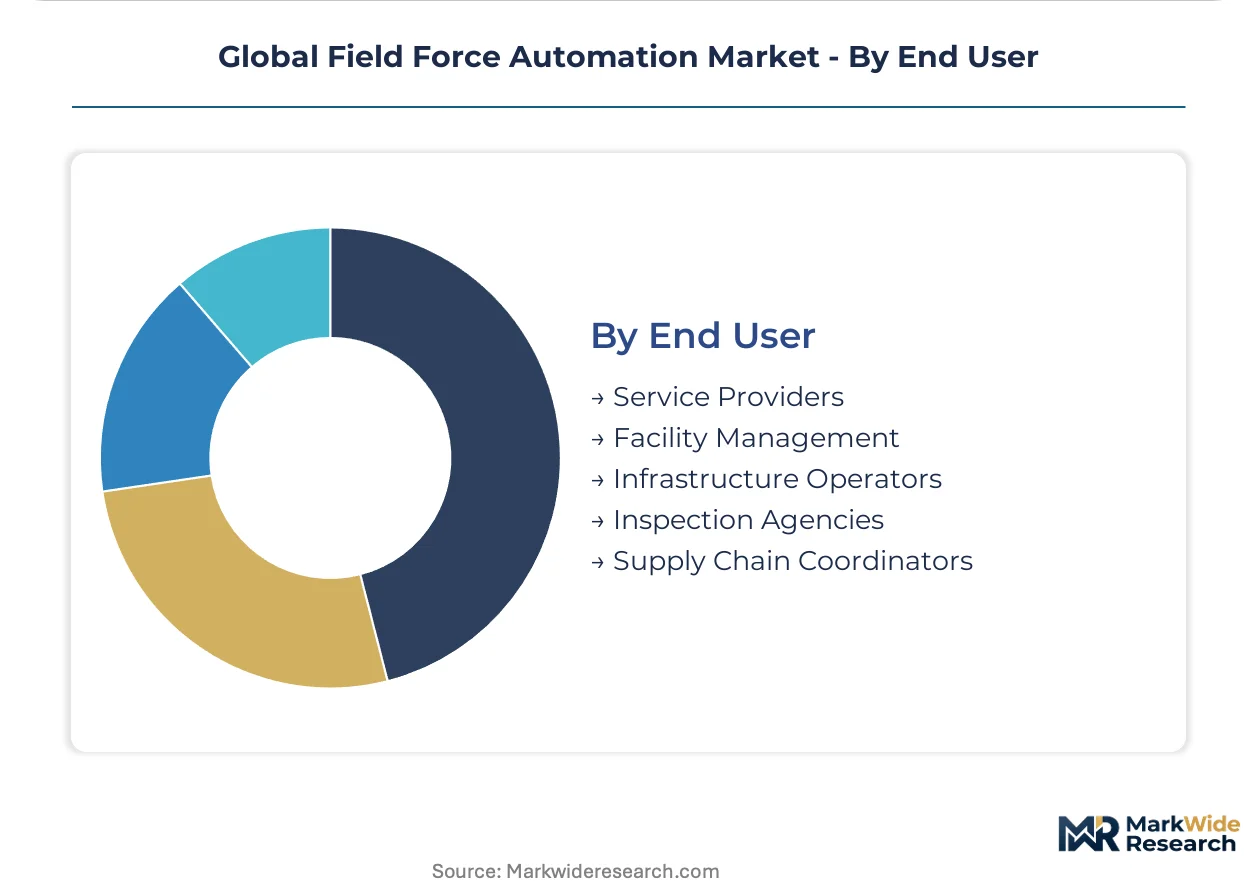
End User:
Contract structure sophistication separates price-takers from outcome-based pricing beneficiaries.
- Infrastructure Operators:Long-horizon asset owners with uptime-linked vendor payments and integrated SCADA interoperability requirements. California and Texas utilities pioneer performance-based field service contracts.
- Service Providers:Third-party maintenance contractors serving multiple clients with white-labeled customer portals and SLA tier differentiation. Indian IT services firms bundle these with domestic utility digitization projects.
- Facility Management:Multi-site property operators with subcontractor coordination and energy efficiency reporting mandates. Singaporean commercial real estate investment trusts drive adoption.
- Inspection Agencies:Regulatory compliance auditors with photographic evidence standards and tamper-proof timestamping. Brazil's ANVISA-aligned pharmaceutical inspectors and Canada's PMRA agricultural field staff require specialized mobile forms.
- Supply Chain Coordinators:Logistics hubs with last-mile delivery synchronization and proof-of-delivery capture. UAE-based port operators and Saudi logistics firms deploy these for customs documentation.
Infrastructure Operators generate the largest contract values; Service Providers are gaining share fastest through platform bundling strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Japan exceeds that in India by a factor of three, reflecting divergent procurement sophistication and regulatory stringency. European utilities pay premium rates for algorithmic transparency documentation. Indian state electricity boards prioritize volume procurement under production-linked incentive timelines.
United States
California and Texas utilities pioneer outcome-based field service contracts linking vendor payments to uptime metrics. FERC grid reliability standards and OSHA worker safety mandates shape platform certification requirements. Pacific Northwest municipalities deploy cyber-hardened mobile systems for hydroelectric maintenance crews.
Germany
Automotive suppliers and grid operators anchor demand for SAP-integrated field platforms with METI-aligned data localization. EU AI Act algorithmic impact assessments are now standard procurement terms. Bavarian manufacturing clusters enforce ISO 55000 asset documentation for predictive maintenance workflows.
India
State electricity boards under CEA modernization directives represent concentrated procurement volume for cyber-hardened mobile devices. PLI scheme subsidies for domestic software development accelerate localized vendor partnerships. Maharashtra and Gujarat utilities lead digitization of legacy paper-based dispatch systems.
Japan
Telecommunications infrastructure investment for 5G densification drives GPS-accurate crew coordination platform demand. METI data localization guidance favors hybrid cloud architectures with on-premise worker data storage. Kanto region utilities integrate field automation with existing SCADA investments.
Australia
Mining operators and pipeline utilities require ISO 55000-compliant asset tracking with predictive maintenance documentation. TGA-equivalent industrial cybersecurity standards influence procurement criteria for remote field devices. Western Australia resource projects deploy edge-computing platforms for cellular dead zone operations.
Global Field Force Automation Market Competitive Landscape
Concentration sits with enterprise software incumbents possessing established ERP integration pathways. The vendor base stratifies across three tiers: cloud-native specialists with embedded AI, legacy ERP extenders leveraging installed base relationships, and vertical-specific platforms targeting utility and telecommunications compliance requirements. Dominant competitive moves include strategic partnerships with telecommunications infrastructure vendors and geographic expansion through localized data residency offerings.
Within the legacy ERP extender tier, SAP SE and Oracle Corporation anchor enterprise manufacturing and utility relationships through deeply integrated field service modules. Salesforce, Inc. occupies a position exemplifying cloud-native platform dominance in telecommunications verticals. Microsoft Corporation represents the hybrid architecture vector, extending cloud infrastructure into edge-computing deployments for critical infrastructure operators. These three anchors collectively illustrate the competitive tension between integration depth and deployment flexibility.
| Leading Market Players |
|---|
| SAP SE |
| ServiceMax, Inc. |
| Salesforce, Inc. |
| Trimble Inc. |
| PTC Inc. |
| Oracle Corporation |
| IFS AB |
| Acumatica, Inc. |
| Microsoft Corporation |
| Others |
Supply & Pricing Matrix
Embedded AI inference chips displacing cloud-dependent dispatch algorithms are redrawing component sourcing maps toward Taiwan and South Korea while compressing margin structures for legacy software-only vendors. This substitution simultaneously elevates hardware-integrated platform pricing power and exposes buyers to semiconductor supply concentration risks.
Pricing Analysis
The customization-premium spread between configured-to-order deployments and standard SaaS tiers spans roughly three-to-one across major vendor categories. Subscription-based SaaS dominates new implementations, with price differentiation driven by ISO 55000 certification grade and vertical-specific compliance documentation depth. Pricing pressure stems from India's PLI-subsidized domestic software development accelerating localized competition. Infrastructure operators in Germany and Japan exhibit lowest price sensitivity due to uptime-linked contract structures, while Indian state electricity boards prioritize volume procurement under digitization mandates.
Supply Chain Analysis
Inbound logistics costs through Asia-Pacific trade lanes face persistent pressure from port congestion at Busan and Singapore affecting edge-computing hardware delivery timelines. Component supply concentrates in Taiwan for embedded AI chips, South Korea for advanced semiconductors, and China for ruggedized tablet assembly. Raw material dependencies span silicon wafers, lithium-ion cells for field device power, and rare earth elements for GPS modules. Single-source vulnerability around Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through direct enterprise sales teams for large utilities and telecommunications operators, supplemented by systems integrator channels for mid-market manufacturing clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The field force automation market represents a high-growth disruption anchored by the EU AI Act's algorithmic transparency mandates forcing vendor documentation investments that reshape competitive moats.
For Market Incumbents: Fortify embedded AI capabilities through backward integration into edge-computing hardware design, countering cloud-native specialists' deployment flexibility advantages. Deepen certification investments in IEC 62443 industrial cybersecurity frameworks to raise switching costs against emerging platform entrants. Prioritize SAP S/4HANA integration pathway maintenance for German and Japanese manufacturing anchor clients facing legacy ERP lock-in.
For New Entrants and Emerging Players: ISO 55000 certification fast-track programs unlock procurement access to Australian mining operators and Canadian pipeline utilities with predictive maintenance mandates. Target India's state electricity boards under CEA modernization directives as the most penetrable geography, leveraging PLI scheme subsidies for domestic software development. Pursue white-label platform partnerships with Indian IT services firms bundling field automation into utility digitization projects.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical specialists possessing utility-specific compliance certifications but lacking cloud-native scalability. Five-to-ten year viability favors platforms with embedded AI inference capabilities and outcome-based contract structuring experience. Watch for inflection signals around carbon accounting module adoption rates among European utilities under CSRD disclosure rules.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded AI Chip Integration | Taiwan semiconductor partnerships enable sub-second dispatch decisions without cellular dependency. |
| EU AI Act Compliance Documentation | Algorithmic transparency pre-packaging secures German grid operator procurement approval. |
| Outcome-Based Contract Restructuring | Uptime-linked payments align vendor economics with California utility reliability mandates. |
| India PLI Localization Partnership | Domestic software development subsidies accelerate state electricity board platform adoption. |
| AR-Enabled Remote Assistance Launch | Augmented reality convergence reduces senior technician travel for Australian mining maintenance. |
Research Methodology
Cross-validation between primary utility and telecommunications executive interviews and secondary regulatory filing analysis anchors the qualitative findings. Field service directors, grid operations managers, telecommunications infrastructure planners, and enterprise software procurement officers contributed operational perspective. Secondary sources span CEA modernization directives, EU AI Act implementation guidance, SEC 10-K software segment disclosures, and ISO 55000 certification registries. Bottom-up deployment modeling triangulates against top-down market sizing across cloud-native and legacy ERP vendor revenue disclosures.
Sensitivity analysis around cloud migration velocity and semiconductor supply assumptions shapes projection reliability across the modeling period. Segmentation dimensions include deployment architecture, solution type depth, vertical application, and end-user contract sophistication. CAGRs derive from installed base growth rates, replacement cycle timing, and pricing trajectory assumptions. Forecast inputs incorporate India's PLI scheme subsidy allocation timelines and European CSRD disclosure phase-in schedules.
Decision-makers should treat outputs as directional under sustained grid modernization investment and stable trade lane logistics assumptions; material deviation would warrant model refresh. Forecasts reflect documented base-case parameters without contingency for major regulatory reversal or supply chain disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
Global Database Automation Systems Market
Automation
Pneumatic Tube System Market
Automation
Workflow Automation Market
Automation
Automation Lifecycle Services Market
Automation
Automated Cell Block Systems Market
Automation
Process Automation Market
Automation
Hyperautomation Market
Automation
North America Home Automation Systems Market
Automation
Global Automated Sample Storage Systems Market
Automation
Asia Pacific Marketing Automation Software Market
Automation
US Workload Scheduling and Automation Market
Automation
Modular Laboratory Automation Market
Automation
North America Marketing Automation Software Market
Automation
Intelligent Remote Terminal Unit Market
Automation
Global Water Automation and Instrumentation Market