

Process Control Systems for Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Process Control Systems for Steel Market Insights
High-strength composite sensors are broadening the addressable scope for process control installations in extreme-temperature steel environments. Siemens leverages deep vertical integration in automation hardware to sustain pricing power across European mill retrofits. ABB anchors its position through dedicated R&D centers for metallurgical applications. Emerson Electric differentiates via predictive analytics platforms purpose-built for blast furnace thermal management.
Process control systems for steel encompass integrated hardware-software architectures that monitor, regulate, and optimize thermal, chemical, and mechanical parameters across primary and secondary metallurgy operations, typically managing temperatures exceeding 1,500°C and tolerances within ±0.5% for critical alloy grades. Distributed Control System deployments dominate brownfield modernization budgets, while Advanced Process Control adoption accelerates among integrated producers seeking yield optimization and energy recovery gains. Human Machine Interface investments lag in foundry segments but expand rapidly at tier-one steel manufacturers consolidating multi-site operations.
EPA emissions enforcement in the United States tightens opacity and particulate thresholds, compelling integrated mills to upgrade furnace control architectures with real-time compliance dashboards. China's MEE implements dual carbon goals through mandatory energy efficiency benchmarking, directly conditioning operating licenses on verified process control data integrity. ETS carbon pricing in Europe redirects capital toward predictive control layers that minimize scope-one emissions intensity. Stakeholders must weigh regulatory divergence across these jurisdictions when standardizing platform architectures for multinational steel portfolios.
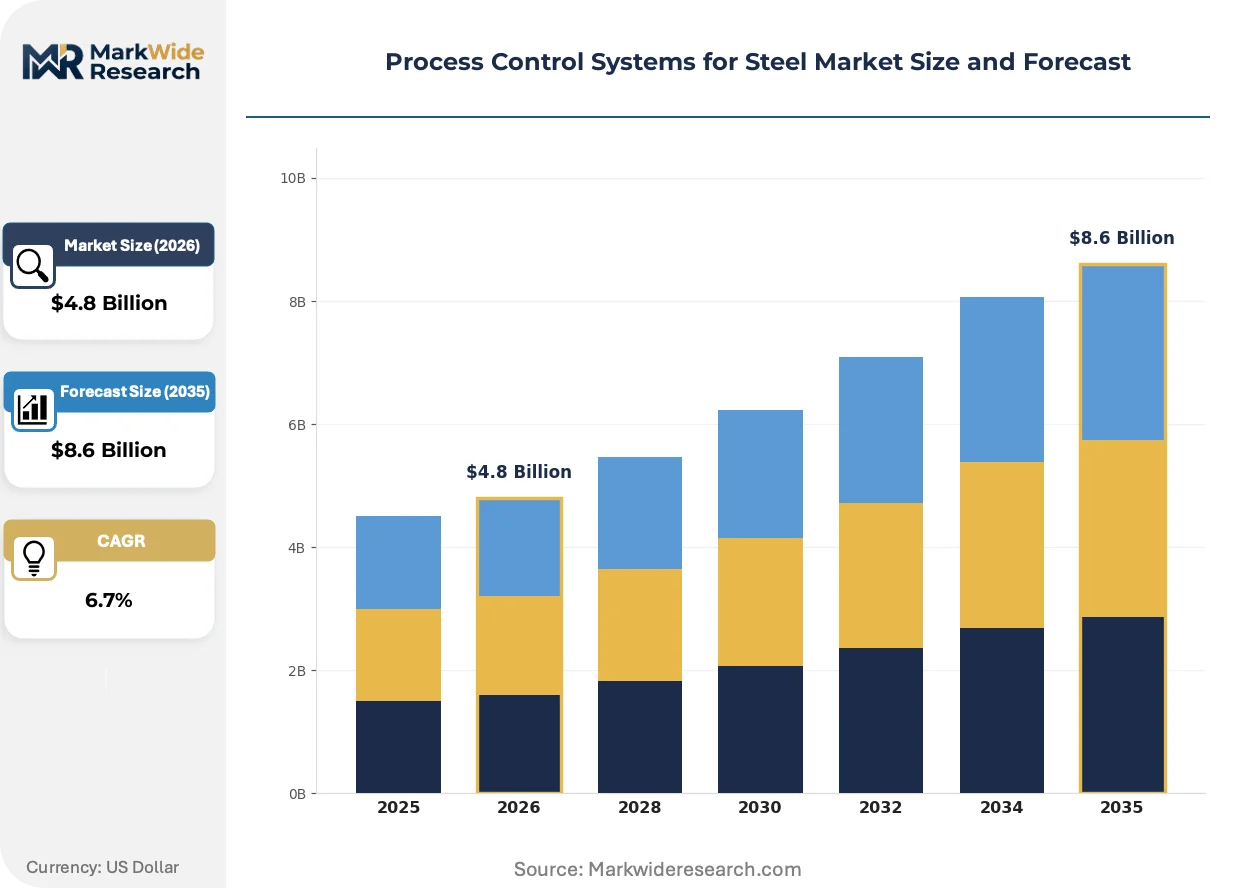
Market Dynamics
Electric arc furnace electrification is compressing thermal control tolerances while EU carbon border adjustments force integrated mills to retrofit legacy blast furnace architectures with real-time emissions tracking layers.
Growth Catalysts
- EU Green Deal decarbonization mandates:Steel producers across Germany, Poland, and Italy must install verified process control systems to maintain operating licenses under tightening scope-one emissions benchmarks.
- High-strength composite sensors:These materials now withstand temperatures exceeding 1,600°C in continuous casting zones, opening brownfield furnace retrofits previously deemed technically unfeasible.
- China's provincial mill consolidation:State-backed mergers into Hebei and Jiangsu steel groups create centralized procurement pools demanding standardized Distributed Control System architectures.
Market Restraints
- Specialized engineering talent scarcity:Metallurgical automation specialists command premiums exceeding 40% above standard industrial software engineers, constraining deployment velocity.
- Rare earth magnet supply concentration:Neodymium and dysprosium for high-temperature sensor actuators originates predominantly from Chinese refining operations, creating input vulnerability.
- Legacy DCS protocol fragmentation:Proprietary communication standards from 1990s-era installations resist seamless integration with modern Advanced Process Control overlays.
Strategic Opportunities
- India's secondary steel sector:Mini-mill operators in Gujarat and Maharashtra lack automated temperature control, presenting greenfield installation potential as BIS quality standards tighten.
- Predictive maintenance convergence:Integration of vibration analysis with thermal imaging creates bundled service offerings for continuous casting line operators seeking unplanned downtime elimination.
- EU ETS carbon price trajectory:Emissions trading scheme values above €80 per tonne redirect capital toward predictive control layers that optimize fuel injection rates in real time.
Industry Challenges
- Multi-protocol integration complexity:Brownfield mills operate mixed vendor environments where Siemens, ABB, and Yokogawa systems must synchronize without production interruption.
- Functional safety certification timelines:IEC 61511 compliance for safety instrumented systems in coke oven gas environments extends project schedules by 8-14 months.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Control Systems for Steel Market Trends and Innovations
Edge computing architectures are displacing centralized control rooms while regulatory enforcement tightens real-time data integrity requirements across major steel-producing jurisdictions.
Edge-native control nodes are decentralizing furnace thermal management by processing sensor data within 50 meters of molten metal zones. Tier-one integrated producers in South Korea and Japan deploy these systems for sub-100-millisecond response loops. This topology is decentralizing the traditional hierarchy between field instrumentation and plant-level Distributed Control Systems.
EPA opacity enforcement under the Clean Air Act compels US integrated mills to install continuous emissions monitoring with direct regulatory data feeds. Violation thresholds now trigger automatic production curtailments within 24 hours. Blast furnace operators in Indiana and Pennsylvania respond by hardening control system cybersecurity to prevent data integrity challenges during audits.
Steel buyers now unbundle hardware procurement from multi-year service contracts, compressing vendor switching cycles from seven years to three. Tier-one manufacturers in Germany and Austria favor modular Advanced Process Control licenses over perpetual Distributed Control System upgrades. This pattern concentrates in flat-rolled product segments where margin pressure from automotive OEMs transfers upstream to control system sourcing decisions.
Process Control Systems for Steel Market Segmentation
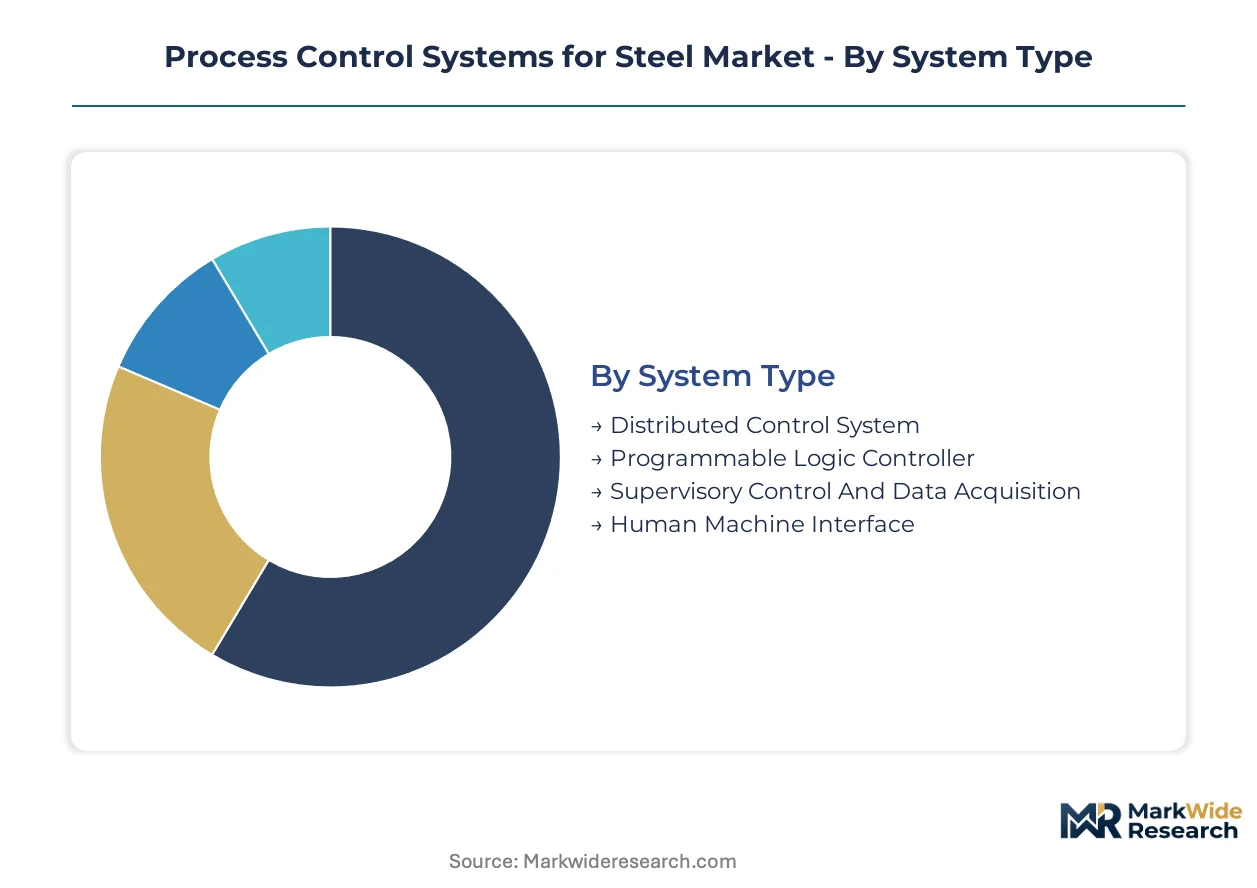
Process control architectures in steelmaking vary sharply by thermal environment and integration depth. System selection hinges on whether operators manage legacy blast furnace retrofits or greenfield electric arc furnace installations. Technology maturity, regulatory compliance layers, and workforce automation readiness further fragment procurement patterns across mill types.
System Type:
Capital intensity and brownfield integration complexity separate buyers in this category.
- Distributed Control System:Centralized hardware-software architectures coordinate multi-zone thermal parameters across integrated mill complexes. Demand clusters in China's Hebei and Jiangsu provincial consolidations where state-backed mergers mandate standardized control platforms for centralized procurement pools.
- Programmable Logic Controller:Ruggedized discrete controllers execute rapid sequencing for material handling and crane operations. Foundries in India's Gujarat secondary steel sector deploy these for cost-effective automation as BIS quality standards tighten without full DCS investment.
- Supervisory Control And Data Acquisition:Wide-area monitoring layers aggregate data across geographically dispersed furnace operations. Metal processing plants favor these for multi-site visibility without replacing field-level controllers.
- Human Machine Interface:Visualization platforms consolidate operator dashboards for complex thermal processes. Tier-one German and Austrian flat-rolled producers invest here while foundry segments lag due to simpler operational requirements.
Distributed Control System leads volumes today; Human Machine Interface is gaining share fastest.
Technology:
Control precision requirements and emissions verification demands shape technology selection.
- Analog Control:Legacy voltage-current signal architectures persist in 1990s-era installations resisting digital overlay integration. European integrated mills face EU ETS carbon pricing pressure to retire these for real-time emissions tracking capability.
- Digital Control:Binary signal processing enables precise setpoint management for critical alloy grades. South Korean and Japanese tier-one producers deploy these for sub-100-millisecond thermal response loops in continuous casting zones.
- Advanced Process Control:Model-predictive algorithms optimize yield and energy recovery across primary metallurgy. Demand concentrates among integrated producers seeking verified process control data integrity under China's MEE dual carbon benchmarking.
- Predictive Control:Forward-looking algorithms anticipate thermal disturbances before sensor detection. US blast furnace operators in Indiana and Pennsylvania adopt these under EPA opacity enforcement requiring automatic production curtailment triggers.
- Adaptive Control:Self-tuning parameters adjust to varying scrap quality in electric arc furnace operations. Polish and Italian mills install these to meet EU Green Deal scope-one emissions benchmarks while processing heterogeneous charge mixes.
Digital Control leads volumes today; Predictive Control shows the steepest expansion trajectory.
Application:
Temperature extremes and tolerance stringency differentiate application-level procurement.
- Blast Furnace Operation:Coke oven gas safety instrumented systems require IEC 61511 certification extending project timelines. US and European integrated mills retrofit these with real-time emissions dashboards under tightening particulate thresholds.
- Continuous Casting:High-strength composite sensors now withstand temperatures exceeding 1,600°C in mold and secondary cooling zones. Brownfield retrofits previously deemed unfeasible now proceed in Germany and Japan.
- Rolling Mill Automation:Thickness and profile control demands sub-micron precision for automotive OEM supply contracts. Austrian and German tier-one producers prioritize these investments as margin pressure transfers upstream from vehicle manufacturers.
- Steel Refining:Ladle metallurgy stations require precise alloy addition sequencing for high-grade specialty steels. Chinese provincial mill networks standardize these controls post-consolidation.
- Furnace Control:Thermal management spans electric arc and basic oxygen furnace architectures. Electric arc furnace electrification compresses control tolerances while EU carbon border adjustments force emissions tracking layer retrofits.
Blast Furnace Operation leads volumes today; Continuous Casting is climbing the fastest.
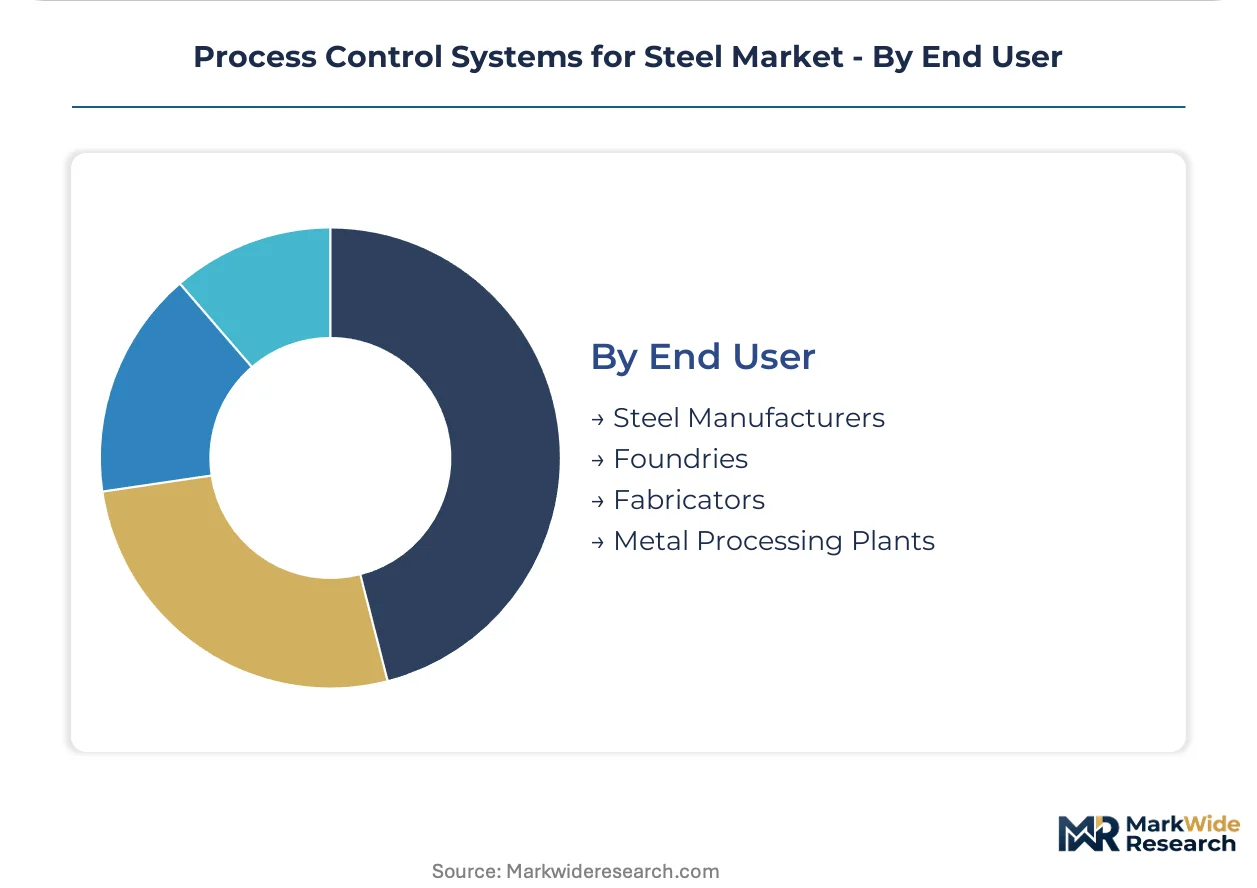
End User:
Scale economies and regulatory exposure separate procurement sophistication levels.
- Steel Manufacturers:Integrated primary producers with multi-billion-tonne capacity drive DCS and APC standardization. China's state-backed consolidations and EU Green Deal compliance investments concentrate demand here.
- Foundries:Smaller-batch ferrous casting operations prioritize cost-minimized PLC solutions. India's Gujarat and Maharashtra mini-mill operators present greenfield potential as quality standards tighten without legacy system burdens.
- Fabricators:Downstream steel processors require coordination with upstream mill scheduling systems. These buyers favor SCADA layers for supply chain visibility rather than full process control investment.
- Metal Processing Plants:Non-ferrous and specialty alloy operators adapt steel-proven control architectures for titanium and nickel superalloy production. Technical transfer from steel applications accelerates deployment here.
Steel Manufacturers lead volumes today; Foundries are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hebei and Jiangsu provincial mill networks drive the dominant share of process control system procurement. State-backed consolidation mandates standardized Distributed Control System architectures across merged steel groups. Regulatory pressure from the EU Green Deal and EPA emissions enforcement redirects investment toward real-time emissions tracking capabilities in secondary markets.
China
Hebei and Jiangsu provincial consolidations into state-backed steel groups create centralized procurement pools demanding standardized DCS platforms. The Ministry of Ecology and Environment's dual carbon goals condition operating licenses on verified process control data integrity. Tangshan and Zhangjiagang mill clusters retrofit blast furnace architectures with real-time compliance dashboards.
Germany
Integrated producers in the Ruhr region and Bavaria upgrade legacy furnace control systems under EU ETS carbon pricing above €80 per tonne. The EU Green Deal's scope-one emissions benchmarks compel ThyssenKrupp and Salzgitter to install predictive control layers. Duisburg and Bremen steelworks lead brownfield retrofits with edge-native thermal management nodes.
United States
Blast furnace operators in Indiana and Pennsylvania respond to EPA opacity enforcement with hardened cybersecurity and continuous emissions monitoring. The Clean Air Act's automatic production curtailment triggers within 24 hours of violation accelerate control system upgrades. Gary and Pittsburgh mill complexes deploy predictive analytics platforms for blast furnace thermal management.
India
Mini-mill operators in Gujarat and Maharashtra present greenfield installation potential as BIS quality standards tighten without legacy system burdens. The Bureau of Indian Standards mandates automated temperature control for secondary steel certification. Surat and Nagpur foundry clusters prioritize cost-effective PLC solutions over full DCS investment.
Japan
Tier-one integrated producers in Chiba and Kawasaki deploy edge-native control nodes for sub-100-millisecond thermal response loops in continuous casting zones. METI's energy efficiency directives accelerate Advanced Process Control adoption for yield optimization. Keihin industrial corridor mills decentralize traditional hierarchies between field instrumentation and plant-level systems.
Process Control Systems for Steel Market Competitive Landscape
Global majors compete with regional champions across automation hardware and predictive analytics platforms. The vendor structure consolidates around diversified industrial conglomerates with captive metallurgical R&D capabilities, while specialized engineering firms occupy niche protocol integration segments. Three archetypes dominate: vertically integrated automation hardware suppliers, predictive analytics platform developers, and regional system integrators with brownfield retrofit expertise. Competitive moves concentrate on strategic partnerships for edge computing deployments and technology licensing for legacy DCS protocol bridging.
Among European-based industrial conglomerates, Siemens and ABB anchor the premium-tier automation hardware segment, while Yokogawa Electric represents the Japanese specialist archetype in high-precision thermal control applications. These three exemplify divergent strategic positioning—Siemens leverages in-house production of automation hardware, ABB occupies a position through dedicated metallurgical R&D centers, and Yokogawa sits within the precision instrumentation tier for extreme-temperature steel environments.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| Honeywell International |
| Emerson Electric |
| Rockwell Automation |
| Yokogawa Electric |
| Schneider Electric |
| Mitsubishi Electric |
| Fuji Electric |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed steel producers in China anchor procurement discipline through centralized provincial consolidation mandates, compressing vendor margins while amplifying pricing leverage for standardized Distributed Control System architectures across Hebei and Jiangsu mill networks.
Pricing Analysis
Input-cost pass-through from rare earth magnet supply concentration governs sensor actuator pricing, with neodymium and dysprosium volatility feeding directly into hardware quotations. Project-based contracting dominates brownfield retrofits, while modular Advanced Process Control licenses gain share among tier-one European mills seeking yield optimization without perpetual DCS commitments. Price differentiation rests on IEC 61511 certification grade and after-sales service bundling. Cost compression in the foundry tier intensifies because mini-mill operators in India prioritize cost-minimized PLC solutions over full system investments. Steel manufacturers with multi-billion-tonne capacity exhibit least price sensitivity; Gujarat and Maharashtra secondary steel operators show highest.
Supply Chain Analysis
Dual-sourcing requirements from tier-one integrated producers mandate multi-supplier qualification for critical sensor actuators and edge computing nodes, fragmenting procurement pools. Geographic supply concentration centers on China for rare earth refining, Germany for precision automation hardware, and Japan for high-temperature composite sensors. Raw material dependencies rest on neodymium-dysprosium alloys, silicon carbide substrates, and high-grade steel enclosures. Single-source vulnerability in Chinese rare earth processing creates structural exposure. Distribution runs through authorized system integrators with brownfield retrofit expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process Control Systems for Steel Market functions as a geographic-arbitrage play: EU ETS carbon pricing above €80 per tonne redirects capital toward predictive control layers in Europe, while India's absence of legacy system burdens enables greenfield automation at lower installed cost per tonne.
For Market Incumbents: Cement metallurgical R&D center investments in Duisburg and Chiba to defend against edge-native control specialists threatening sub-100-millisecond response loops. Prioritize backward integration into high-temperature sensor production to offset rare earth magnet supply vulnerability. Lock in multi-year service contracts with China's provincial steel groups before procurement centralization completes. For New Entrants and Emerging Players: Edge-native thermal management algorithms offer technology-first wedge into continuous casting zones where legacy DCS protocols resist seamless integration. Target India's Gujarat and Maharashtra mini-mill segments for greenfield PLC installations as BIS quality standards tighten without incumbent entrenchment. Pursue predictive maintenance convergence bundling vibration analysis with thermal imaging for unplanned downtime elimination. For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with brownfield retrofit expertise and mixed-vendor protocol bridging capabilities. Long-term viability over the next decade hinges on regulatory enforcement trajectory across EPA, EU Green Deal, and China's MEE jurisdictions. Watch EU carbon border adjustment implementation timing as inflection indicator for integrated mill retrofit capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive neodymium supply secures pricing power against Chinese refining concentration. |
| Edge-Native Control Node Deployment | Sub-100-millisecond response loops displace centralized DCS hierarchies in Chiba and Kawasaki. |
| Predictive Analytics Platform Licensing | Emissions-optimized fuel injection meets EPA automatic curtailment triggers in Indiana. |
| Provincial Consolidation Partnership | Standardized DCS architectures lock in Hebei and Jiangsu procurement pools under MEE dual carbon goals. |
| Predictive Maintenance Service Bundling | Vibration-thermal convergence eliminates unplanned downtime for German flat-rolled producers. |
Research Methodology
Coverage spans China, Germany, the United States, India, and Japan, with primary inputs from each market through structured interviews with plant engineers, automation procurement leads, metallurgical R&D directors, and aftermarket service heads. Secondary validation draws from SEC filings of listed automation vendors, customs data on industrial control equipment trade flows, MEE emissions benchmarking disclosures, and EU ETS carbon price registries. Bottom-up segment sizing triangulates against top-down steel production capacity estimates.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. The analytical framework models system type, technology tier, application thermal environment, and end-user scale segmentation dimensions. CAGRs derive from regression against steel output forecasts, regulatory compliance deadline clustering, and automation budget elasticity to carbon pricing. Industry-specific inputs include electric arc furnace electrification timelines and blast furnace retrofit capex cycles.
The model holds under sustained EU Green Deal enforcement and China's dual carbon benchmarking; deviation in EPA regulatory stringency or rare earth export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.