
 Global Remote Monitoring and Control Market | 2026-2036
Global Remote Monitoring and Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Remote Monitoring and Control Market Intelligence
The shift from capital expenditure to operational expenditure models, particularly through cloud-based subscriptions, is rewriting the competitive landscape for remote monitoring systems. Schneider Electric leverages its EcoStruxure platform to capture this recurring revenue stream. Meanwhile, Siemens integrates its MindSphere IoT-as-a-service offering across its industrial automation portfolio. Honeywell International positions its Forge platform to compete on analytics and outcome-based service contracts.
Remote monitoring and control systems are integrated solutions collecting data from assets in one location to enable control actions from another. Functionality relies on SCADA protocols and IoT sensors transmitting data over wireless networks for analysis. Cloud-based deployment models dominate, offering scalability for applications like building automation and asset management. AI analytics and machine learning models represent the fastest-growing technology, enabling predictive maintenance for manufacturing plants.
Data sovereignty and security are shaped by regulations such as Europe's GDPR and the upcoming EU AI Act. In the United States, FCC rules govern wireless spectrum use for IoT devices, while industry-specific standards from bodies like the IEC define system interoperability. Vendors must navigate this complex regulatory tapestry to ensure market access and build customer trust in their data handling practices.
Market Dynamics
The convergence of operational technology (OT) from the factory floor with enterprise-level information technology (IT) is the central force shaping remote monitoring systems. This integration enables real-time data analytics, directly influencing system design and deployment strategies across industrial sectors.
Growth Catalysts
- Industrial IoT Proliferation:A greater availability of low-cost IIoT sensors provides granular data from distributed assets, enabling predictive maintenance and operational efficiency gains in manufacturing and energy sectors.
- Smart Grid Modernization:Energy utilities in countries like Germany and the United States are deploying remote monitoring to manage distributed energy resources, balance grid loads, and improve overall reliability.
- Data Security Mandates:Regulations such as Europe's GDPR compel organizations to adopt secure, compliant remote monitoring platforms, which in turn builds end-user trust and encourages wider system adoption.
Market Restraints
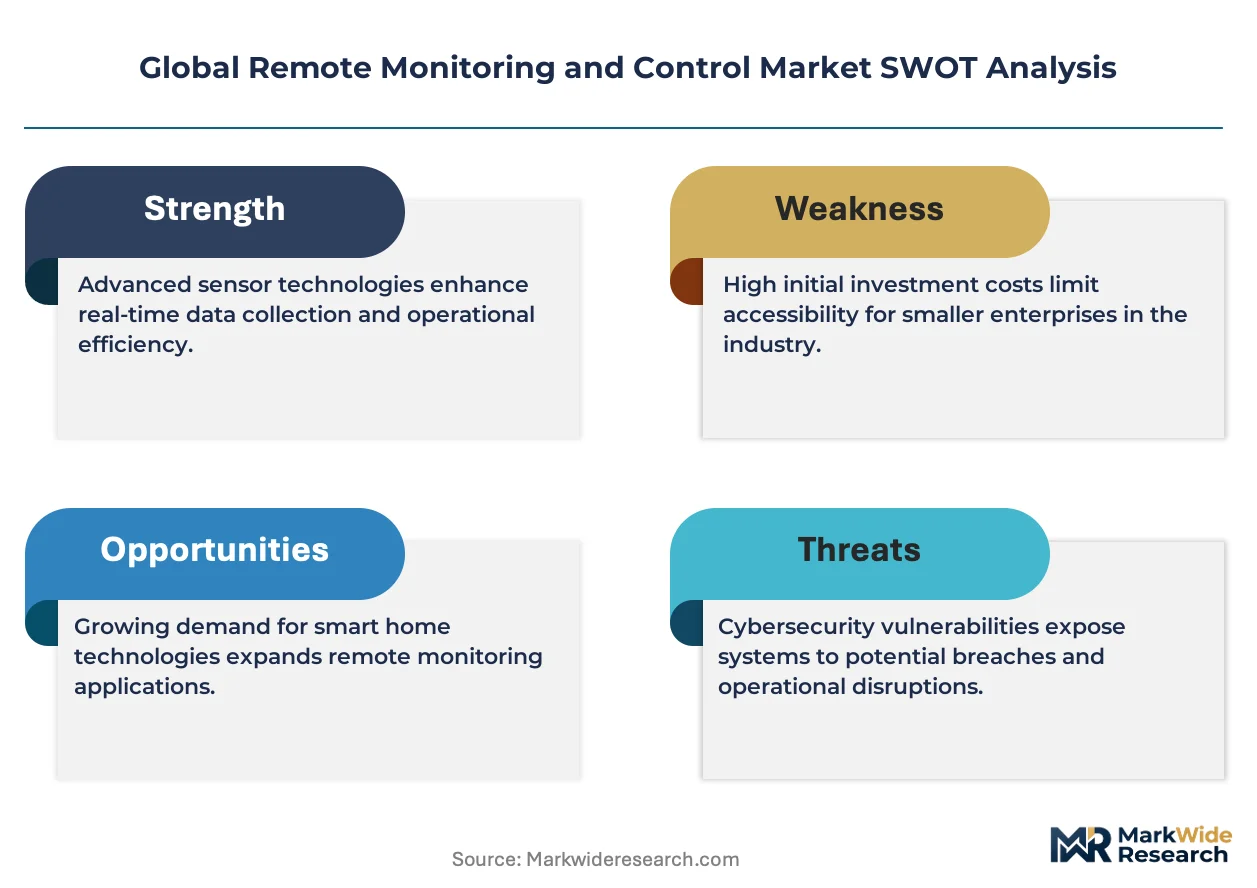
- High Initial Capital Expenditure:The cost of deploying sensors, network infrastructure, and SCADA software for large-scale industrial applications remains a significant barrier for small and medium-sized enterprises.
- Legacy System Interoperability:Integrating modern IoT-based monitoring solutions with older, proprietary operational technology equipment creates significant technical friction and implementation delays for asset owners.
- Cybersecurity Vulnerabilities:The increased connectivity of industrial control systems exposes critical infrastructure to cyber threats, creating hesitation among operators in sectors like water treatment and power generation.
Strategic Opportunities
- Predictive Maintenance-as-a-Service:Offering subscription-based analytical services that predict equipment failure for manufacturing plants represents a shift from capex-heavy sales to recurring revenue models.
- Water Management in India:Underpenetration in municipal water infrastructure provides a significant opportunity for deploying remote monitoring to reduce non-revenue water and optimize treatment processes.
- AI and Machine Learning Integration:Embedding AI algorithms directly at the network edge via edge computing can reduce data transmission costs and latency, enabling faster and more autonomous local control actions.
Industry Challenges
- Scarcity of Hybrid Skills:A shortage of professionals who possess expertise in both operational technology and data science hinders the effective implementation and analysis of advanced monitoring systems.
- Fragmented Communication Protocols:The lack of a universal standard for IIoT device communication complicates system integration, forcing vendors to support multiple protocols like MQTT and legacy SCADA standards.
- ERP System Integration:Linking operational data from remote monitoring platforms with business-level enterprise resource planning software for a unified view of operations is a persistent integration challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Remote Monitoring and Control Market |
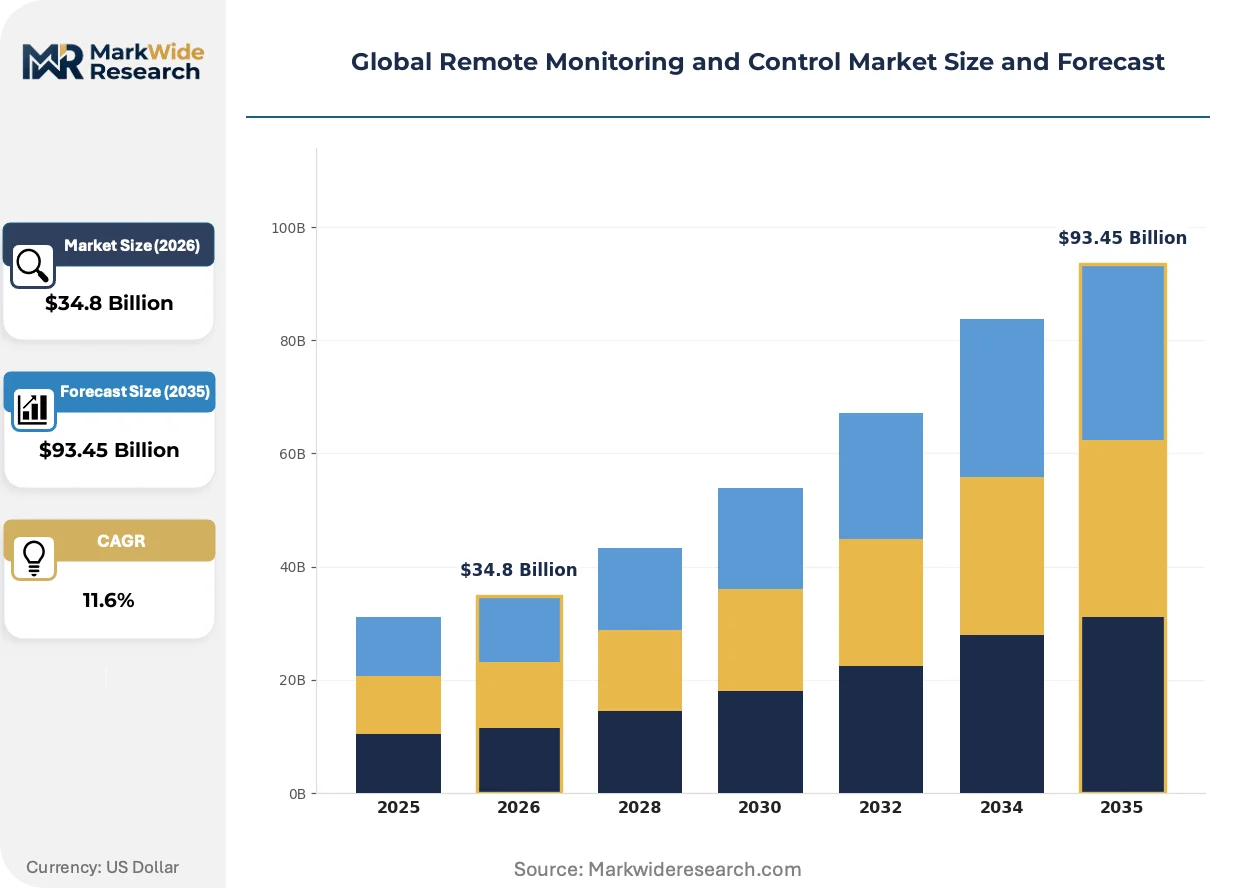
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $93.45 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Technology: IoT Sensors, SCADA Systems, Wireless Networks, AI Analytics, Machine Learning Models Application: Smart Grids, Building Automation, Asset Management, Environmental Monitoring, Agricultural Monitoring End User: Energy Providers, Facility Managers, Transportation Operators, Water Utilities, Manufacturing Plants |
| Companies Covered | Emerson Electric, Honeywell International, Schneider Electric, Siemens, ABB, Rockwell Automation, General Electric, Yokogawa Electric Corporation, Endress+Hauser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Remote Monitoring and Control Market Strategic Shifts & Innovations
A fundamental transition from passive data collection to active, intelligent control is defining the next generation of remote monitoring platforms. The emphasis is now on embedding analytics and machine learning to automate decision-making and optimize asset performance in real-time.
Edge computing, which involves processing data near its source rather than in a centralized cloud, is a key technological evolution. Manufacturing and logistics sectors are adopting edge devices to reduce latency for time-sensitive control actions. This trend is digitizing the control loop itself, moving analytical intelligence from remote data centers directly to the machine or asset.
The forthcoming EU AI Act introduces a risk-based framework for artificial intelligence systems, including those used in industrial control. It mandates transparency, human oversight, and robustness requirements for high-risk AI applications, such as those controlling critical infrastructure. System vendors targeting the European market must now design their predictive maintenance algorithms to meet these stringent compliance standards.
Customers are moving away from procuring standalone hardware and software components toward adopting integrated, platform-based ecosystems. This model displaces traditional component sales with subscription-based access to a suite of tools for data ingestion, analytics, and application development. The shift is most pronounced in building automation and smart city projects, where interoperability across multiple vendor systems is a primary requirement.
Global Remote Monitoring and Control Market Segmentation
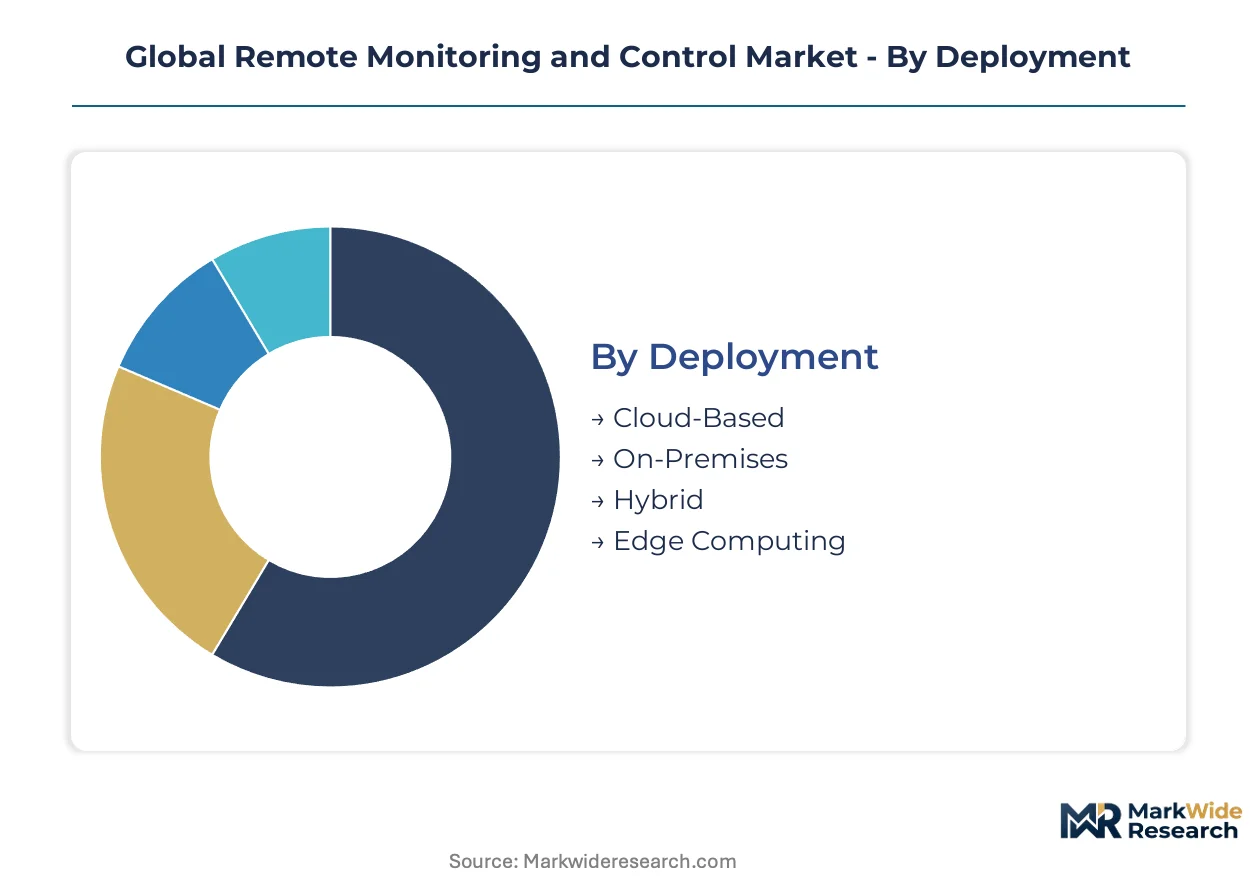
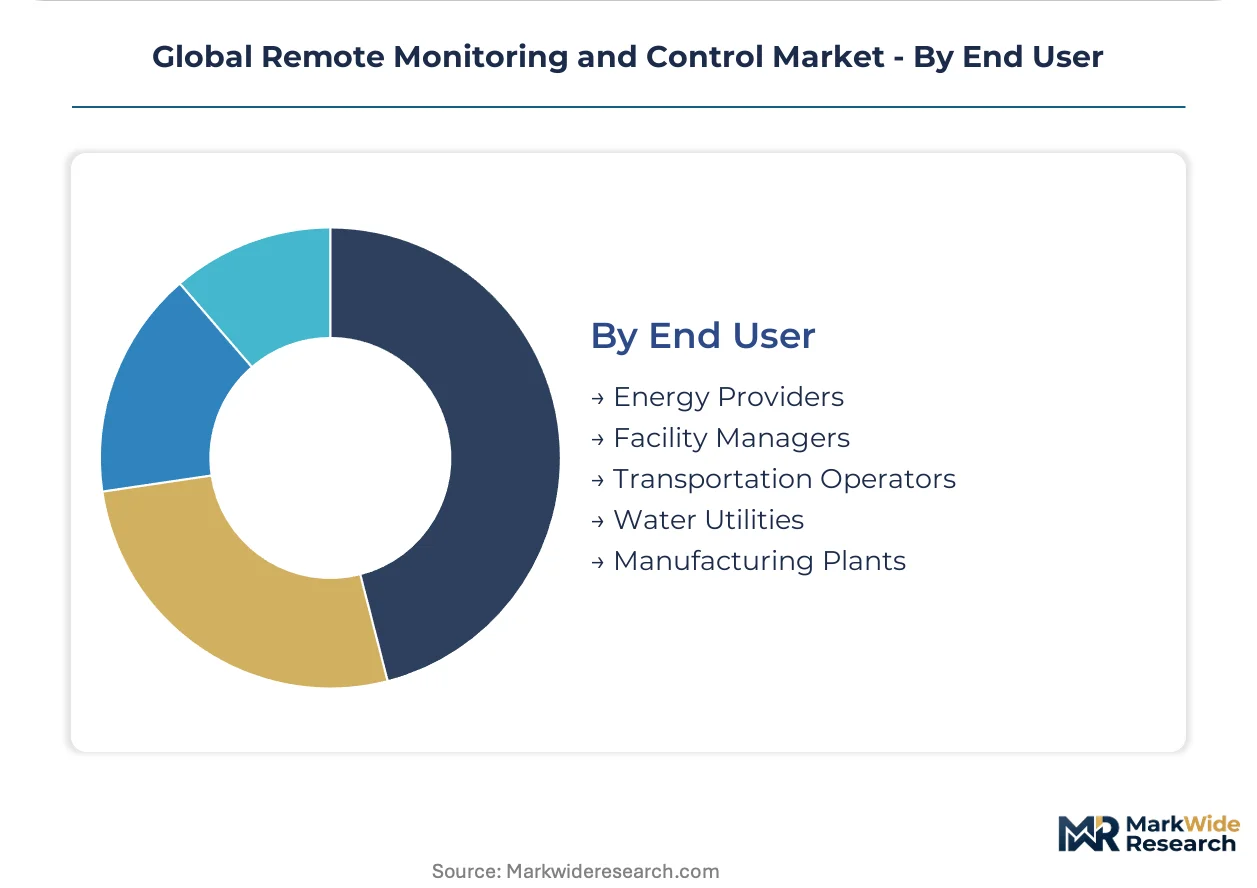
The Global Remote Monitoring and Control Market segments across diverse operational architectures and technological foundations. Understanding these distinctions allows stakeholders to tailor solutions that meet specific industrial demands, from data deployment models to end-user applications. This granular segmentation illuminates the varied pathways for market entry and value creation.
Deployment:
The spectrum of deployment models reflects diverse operational requirements across industries.
- Cloud-Based:This model leverages remote servers hosted on the internet for data storage, processing, and application delivery. It offers significant scalability and reduced upfront infrastructure costs, appealing to organizations seeking flexible and geographically dispersed monitoring solutions for building automation.
- Edge Computing:Data processing occurs closer to the source, such as on a factory floor device or a smart grid sensor. Edge computing minimizes latency and bandwidth usage for time-sensitive control actions, gaining traction in manufacturing plants and logistics where real-time decision-making is critical.
- On-Premises:Systems are installed and operated directly within the user's physical location, providing complete control over data and infrastructure. This model is preferred by organizations with strict data sovereignty requirements or existing legacy IT investments.
- Hybrid:This approach combines elements of both on-premises and cloud-based deployments, allowing organizations to maintain sensitive data locally while leveraging cloud resources for scalability.
Established volume favors On-Premises deployments; emerging adoption favors Edge Computing.
Technology:
Technology choices often reflect a balance between initial investment and long-term operational efficiency.
- AI Analytics:These advanced algorithms process large datasets from remote monitoring systems to identify patterns, predict failures, and optimize performance. AI analytics represents the fastest-growing trajectory in data interpretation, enabling predictive maintenance for complex industrial machinery.
- IoT Sensors:These devices collect real-time data from physical assets, transmitting information wirelessly to monitoring platforms. The proliferation of low-cost IIoT sensors provides granular data from distributed assets, driving efficiency gains across energy providers and manufacturing.
- SCADA Systems:Supervisory Control and Data Acquisition systems provide centralized control and monitoring of industrial processes. They form the backbone for critical infrastructure applications like water treatment and power generation.
- Wireless Networks:These communication infrastructures, including cellular, Wi-Fi, and LPWAN technologies, facilitate data transmission from remote sensors to central control points. Wireless networks enable flexible deployment in geographically dispersed environments.
- Machine Learning Models:A subset of AI, these models allow systems to learn from data without explicit programming, continuously improving their analytical capabilities. Machine learning models enhance anomaly detection and forecasting accuracy in asset management.
While SCADA Systems maintain foundational control, AI Analytics is expanding most quickly in data interpretation.
Application:
The diverse applications of remote monitoring systems address specific operational challenges across various sectors.
- Smart Grids:These applications involve monitoring and controlling electricity distribution networks to optimize energy flow, integrate renewable sources, and improve grid reliability. Energy providers in Germany and the United States utilize smart grids for distributed energy resource management.
- Asset Management:This application focuses on tracking, monitoring, and optimizing the performance and lifespan of physical assets across industries. Asset management solutions enhance operational longevity for equipment in manufacturing plants and transportation.
- Building Automation:Systems control and monitor building functions like HVAC, lighting, and security to optimize energy consumption and occupant comfort. Building automation platforms are increasingly adopted in commercial and residential properties.
- Environmental Monitoring:These applications involve collecting data on environmental parameters such as air quality, water levels, and pollution. Environmental monitoring aids regulatory compliance and resource management for water utilities.
- Agricultural Monitoring:Remote systems track crop health, soil conditions, and livestock welfare to optimize farming practices and resource utilization. Agricultural monitoring improves yield and reduces waste in large-scale farming operations.
Smart Grids drive large-scale infrastructure projects, while Building Automation offers pervasive efficiency gains in commercial settings.
End User:
End-user segments highlight the varied operational needs and regulatory environments influencing system adoption.
- Energy Providers:Utilities deploy remote monitoring to manage power generation, transmission, and distribution, especially with the integration of distributed energy resources. Energy providers in Europe prioritize grid stability and renewable energy integration.
- Manufacturing Plants:Industrial facilities use these systems for predictive maintenance, process optimization, and quality control of production lines. Manufacturing plants in the United States leverage remote monitoring for operational efficiency gains.
- Facility Managers:Professionals overseeing commercial and institutional buildings use remote systems for HVAC control, security, and energy management. Facility managers seek to reduce operational costs and enhance building performance.
- Water Utilities:Organizations responsible for water treatment and distribution employ remote monitoring to detect leaks, manage flow, and ensure water quality. Water utilities in India explore solutions to reduce non-revenue water.
- Transportation Operators:These include railway, road, and maritime operators who monitor vehicle fleets, infrastructure, and logistics for safety and efficiency. Transportation operators enhance asset tracking and predictive maintenance for critical vehicles.
Energy Providers and Water Utilities prioritize critical infrastructure resilience, whereas Manufacturing Plants seek direct operational efficiency improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government policies and incentives across several nations are driving the expansion of remote monitoring and control systems. These initiatives focus on modernizing infrastructure and enhancing industrial efficiency, creating substantial demand for advanced technological deployments. Energy transition mandates and digital transformation strategies further accelerate market growth in key geographies.
United States
Smart grid modernization and the push for operational efficiency in manufacturing plants stimulate demand for remote monitoring. FCC rules govern wireless spectrum use for IoT devices, ensuring reliable communication for critical infrastructure. In Texas, energy providers are deploying advanced systems to manage distributed energy resources and improve grid resilience.
Germany
Industrial IoT proliferation within the manufacturing sector and energy grid transformation are significant demand drivers. The EU AI Act introduces a risk-based framework for AI systems, impacting predictive maintenance algorithms. Baden-Württemberg's advanced manufacturing clusters actively integrate remote monitoring for process automation and quality control.
India
Significant opportunities exist in water management infrastructure and smart city development, driving remote monitoring adoption. The Central Electricity Authority (CEA) issues guidelines for grid management, influencing energy sector deployments. Industrial hubs in Maharashtra are implementing remote solutions to optimize asset performance and reduce operational costs.
China
Extensive industrial automation initiatives and large-scale smart manufacturing projects underpin demand for remote control systems. MIIT policies promote the development of industrial internet platforms and IoT device interoperability. The Yangtze River Delta region, a major manufacturing hub, is rapidly adopting these systems for enhanced production visibility.
Japan
Demand stems from advanced factory automation and the need to monitor aging infrastructure across various sectors. METI initiatives support the digital transformation of industries, encouraging investment in smart sensing technologies. Kanto region's high-tech manufacturing facilities leverage remote systems for precision control and predictive analytics.
Global Remote Monitoring and Control Market Key Industry Players
On the supply side, the industry is characterized by a mix of established industrial conglomerates and specialized technology providers. This structure creates a tiered competitive environment, where larger players offer integrated platforms and smaller firms focus on niche solutions. Strategic partnerships and portfolio diversification are common competitive moves among market participants.
Industrial giants such as Siemens and Honeywell International exemplify the trend towards comprehensive, platform-based offerings, integrating IoT-as-a-service with extensive automation portfolios. Schneider Electric occupies a position with its EcoStruxure platform, emphasizing recurring revenue streams through cloud-based subscriptions. These companies anchor the market with broad solutions spanning multiple applications and end-user segments.
| Leading Market Players |
|---|
| Emerson Electric |
| Honeywell International |
| Schneider Electric |
| Siemens |
| ABB |
| Rockwell Automation |
| General Electric |
| Yokogawa Electric Corporation |
| Endress+Hauser |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's extensive manufacturing capacity for IIoT sensors and network components directly influences the global pricing of remote monitoring hardware. This concentration of production drives cost efficiencies, affecting competitive pricing strategies for integrated solutions.
Pricing Analysis
Certification level (IEC standards for interoperability, EU AI Act compliance) creates the primary spread in remote monitoring system pricing, especially for critical infrastructure applications. Pricing models often combine SaaS-tiered subscriptions for platform access with project-based fees for large-scale industrial deployments. Cost compression in IIoT sensor manufacturing intensifies pricing pressure on hardware components. Small and medium-sized enterprises exhibit higher price sensitivity compared to large energy providers and manufacturing plants.
Supply Chain Analysis
Key contract manufacturers in China, particularly within the Yangtze River Delta region, hold significant capacity for IIoT sensor production and network hardware. This market draws heavily from global semiconductor foundries and specialized component suppliers for edge computing devices. Single-source vulnerability for specific industrial-grade sensors and communication modules represents a structural supply chain risk. Distribution for integrated remote monitoring solutions typically runs through direct sales teams for large enterprises and value-added resellers for broader market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Remote Monitoring and Control Market presents a defensive-moat story, primarily driven by high switching costs associated with integrating complex operational technology. Regulatory entrenchment, particularly in critical infrastructure applications, further solidifies market positions for established providers.
For Market Incumbents:
Entrench existing customer bases by expanding platform capabilities, focusing on seamless integration with legacy OT systems, and offering outcome-based service contracts. Invest in advanced cybersecurity certifications and R&D for edge AI to counter the threat from specialized analytics firms. Deepen vertical integration into critical component supply chains to mitigate single-source vulnerabilities.
For New Entrants and Emerging Players:
Build out specialized AI analytics for predictive maintenance-as-a-service, targeting underpenetrated segments like municipal water management in India. Focus on developing open-source protocol-compatible solutions to address legacy system interoperability challenges in smaller manufacturing plants. A go-to-market angle emphasizing rapid deployment and demonstrable ROI can attract small and medium-sized enterprises.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors integrated platform providers and specialized AI analytics firms with strong intellectual property in predictive maintenance. The market demonstrates strong long-term viability, driven by industrial digitalization and smart grid modernization initiatives. Acquisition targets should include edge computing specialists and companies solving fragmented communication protocol challenges. Increased clarity from regulatory bodies like the EU AI Act is a signal to watch for accelerated adoption in high-risk applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Ecosystem Expansion | Integrates diverse applications and third-party solutions, increasing switching costs for end-users. |
| Edge AI Development | Reduces latency and bandwidth costs for critical real-time control actions in manufacturing and logistics. |
| Cybersecurity Certification Investment | Builds customer trust and ensures compliance with stringent data security mandates for critical infrastructure. |
| Predictive Maintenance-as-a-Service Launch | Shifts revenue models from capital expenditure to recurring operational expenditure for manufacturing clients. |
| Smart Grid Solution Partnership | Accelerates deployment in energy utilities, supporting distributed energy resource management and grid stability. |
Research Approach
Initial hypotheses were tested against primary input from plant managers, energy utility planning officers, facility managers, and IoT solution architects. This approach combined interviews with secondary validation from SEC filings, industry association reports on IIoT standards, and government energy sector analyses. Bottom-up data aggregation from segment-specific insights was triangulated with top-down market sizing estimates.
Demand-supply balance was meticulously assessed across the analysis window, considering both technological advancements and end-user adoption patterns. The analytical framework modeled market dynamics across deployment models, technologies, applications, end-users, and regional regulatory environments. Compound Annual Growth Rates were derived from historical growth trends, projected IIoT sensor unit shipments, and anticipated smart grid investment projections.
Stress conditions across geopolitical stability and regulatory evolution were modeled; outcomes beyond these bands fall outside the analytical envelope. Forecasts reflect assumptions for IIoT standardization and industrial capital expenditure. Quarterly review of IIoT sensor prices, industrial automation investment, and regional regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Process Automation Market
Automation
Computer Numerical Control Market
Automation
Automatic Message Handling System Market
Automation
Self Bag Drop Machine Market
Automation
Dropshipping Automation Software Market
Automation
Pneumatic Tube System Market
Automation
Data Center Automation Market
Automation
Postal Automation System Market
Automation
Italy Process Orchestration Market
Automation
Automated Cell Block Systems Market
Automation
Global Warehouse Execution System Market
Automation
Global Direct Mail Automation Software Market
Automation
Industrial Vending Machines Market
Automation
Automation Light Grids Market
Automation
Database Automation Market
Automation
Middle East and Africa Workforce Management Market