
 Automatic Fire Ball Extinguisher Market | 2026-2036
Automatic Fire Ball Extinguisher Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Fire Ball Extinguisher Market Intelligence
The UL 711 certification standard for rating and fire testing of fire extinguishers is bifurcating the competitive landscape between certified and non-certified suppliers. Elide Fire Ball Pro Co., Ltd. specializes in the patented ball-type extinguisher design for specific niche applications. In contrast, established safety equipment giant Kidde leverages its extensive distribution network for a broader portfolio of fire protection products. FirePro positions its condensed aerosol technology as an alternative for enclosed spaces.
An automatic fire ball extinguisher is a self-activating suppression device designed to disperse extinguishing agents upon direct contact with a flame. These units typically contain a dry chemical powder, such as monoammonium phosphate, and are triggered by an external fuse that ignites a small charge. Powder-based types dominate the market due to their effectiveness across multiple fire classes. The commercial application segment, covering server rooms and electrical cabinets, represents a primary area of deployment, often utilizing wall-mounted or fixed installations.
Market access is governed by a complex web of regional safety certifications, including the CE marking in Europe and UL listings in the United States. In China, compliance with national GB standards for fire fighting equipment is mandatory for all products sold domestically. These regulations dictate material composition and activation reliability, creating significant barriers to entry. Vendor success depends on navigating this patchwork of standards to build a multi-regional presence.
Market Dynamics
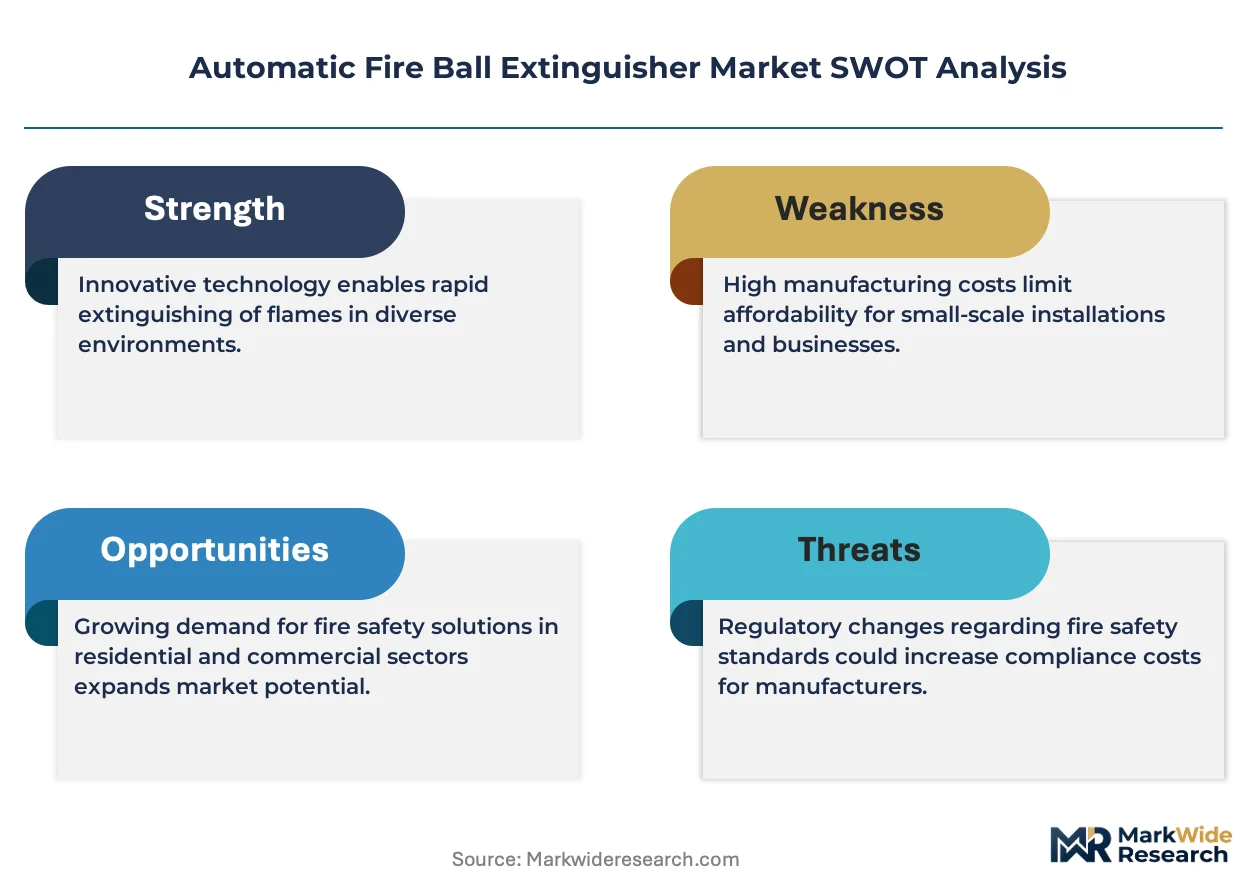
The proliferation of automated systems in unmanned industrial spaces, driven by stricter fire safety codes from bodies like the NFPA, is the central dynamic. This shifts focus from manual intervention to autonomous fire suppression for critical infrastructure protection.
Growth Catalysts
- Regulatory Mandates:Stricter fire safety codes, including standards influenced by the NFPA in the United States and CE marking requirements in Europe, compel the installation of automated suppression systems in commercial and industrial buildings.
- Industrial Automation:The expansion of unmanned facilities, particularly data centers and remote electrical substations, creates a direct need for self-activating extinguishers to protect high-value assets without human presence.
- Agent Efficacy:The versatility of dry chemical powders like monoammonium phosphate, effective against Class A, B, and C fires, allows a single product type to cover a wide range of common fire risks in diverse settings.
Market Restraints
- Limited Suppression Radius:A single fire ball unit has a defined and relatively small effective coverage area, making it unsuitable for protecting large, open-plan spaces without deploying numerous, costly devices.
- Alternative Technologies:Condensed aerosol systems and conventional sprinkler installations present viable and often preferred alternatives, particularly for enclosed server racks or entire building protection, respectively.
- Certification Complexity:The absence of a harmonized global standard forces vendors to pursue costly and time-consuming regional certifications like UL listing in the US and CE marking in Europe, creating significant entry barriers.
Strategic Opportunities
- Electric Vehicle Infrastructure:Targeting the emerging risk of thermal runaway in electric vehicle charging stations and battery energy storage systems provides a new, high-value application for localized, automatic suppression.
- Residential Market Entry:Development of direct-to-consumer sales channels for smaller, aesthetically designed units can penetrate the residential market for use in kitchens, workshops, and over electrical panels.
- Emerging Economies:Expanding into industrializing regions in Latin America and Southeast Asia, where fire safety regulations are strengthening, offers significant greenfield growth potential before markets mature.
Industry Challenges
- Counterfeit Products:The market is challenged by the influx of non-certified and counterfeit devices, which erode trust in the technology, create safety risks, and put downward price pressure on legitimate, certified products.
- End-User Education Gap:A significant hurdle is educating facility managers and end-users on the correct application, operational limitations, and maintenance requirements of ball extinguishers versus conventional fire suppression systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Fire Ball Extinguisher Market |
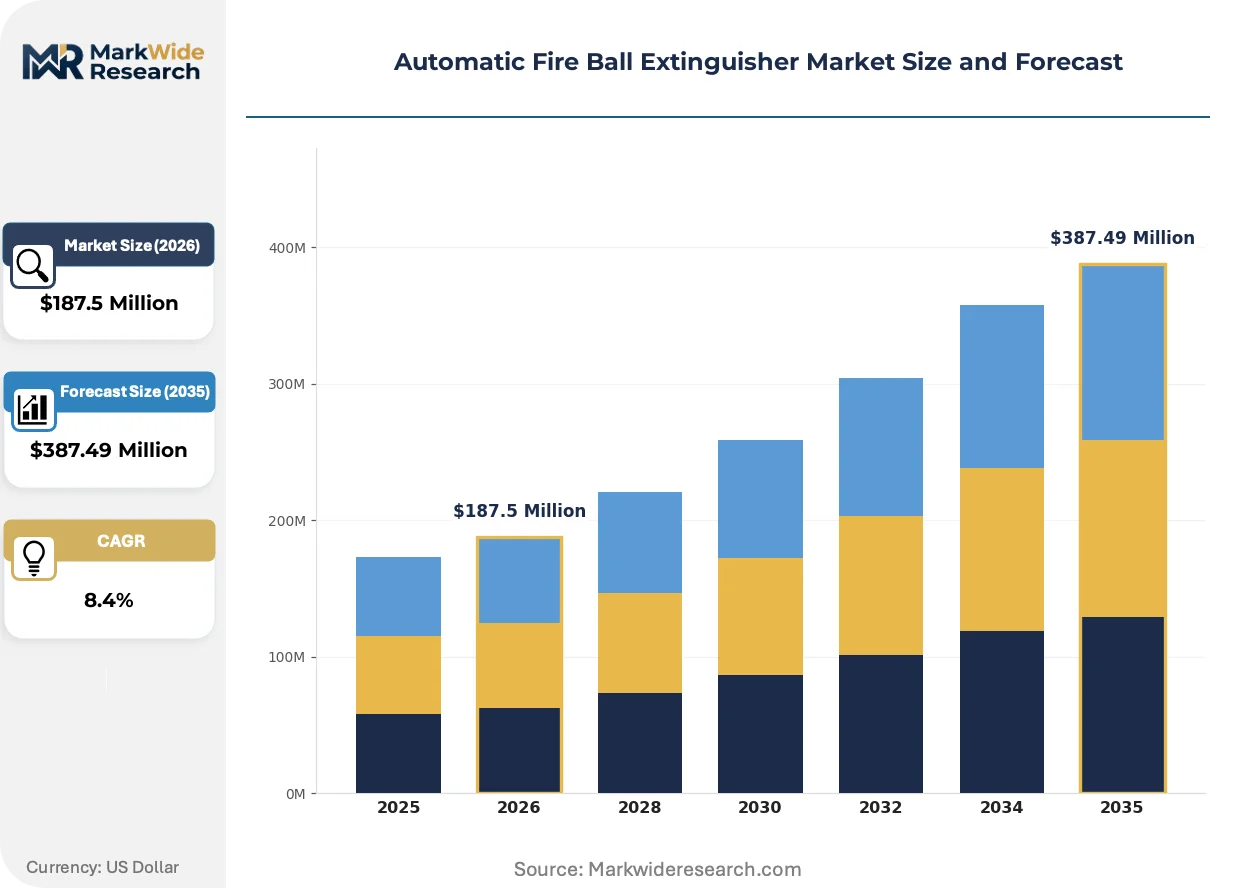
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $387.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Chemical, Water, Foam, Powder Application: Residential, Commercial, Industrial, Marine Installation: Wall-Mounted, Ceiling-Mounted, Portable, Fixed Activation Method: Manual, Automatic, Remote-Controlled, Sensor-Based |
| Companies Covered | Firetech Global, Elide Fire Ball Pro Co., Ltd., L. R. INDUSTRIES, Kidde, Minimax, Auto Fireball, Universal Fire Protection, FirePro, Firetrace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Fire Ball Extinguisher Market Strategic Shifts & Innovations
The evolution of automatic fire suppression is moving beyond simple activation towards integrated and specialized solutions. This shift prioritizes precision, data connectivity, and suitability for complex, modern fire risk environments found in high-tech industries. This approach is reshaping vendor strategy.
Smart fire balls incorporate IoT sensors and wireless communication capabilities to signal activation status and ambient temperature to a central dashboard. Operators of critical infrastructure, such as data centers and remote telecom towers, are adopting this technology for immediate remote alerts. This integration of data connectivity is decomposing the traditional separation between passive fire protection devices and active facility monitoring systems.
China's mandatory GB standards for firefighting equipment are becoming increasingly stringent, particularly regarding the material composition and activation reliability of suppression devices. This forces domestic and international manufacturers to re-engineer products specifically for the Chinese market, raising compliance costs. Consequently, non-compliant suppliers are being pushed out, while vendors with robust quality control that meets GB standards gain a significant advantage.
Buyers in the commercial sector are increasingly demanding certified, pre-engineered solutions for specific applications like electrical cabinets rather than purchasing standalone products. This pattern disrupts the model of selling generic units through broadline distributors, favoring specialist integrators who can design and install validated systems. This trend is most visible in Germany's manufacturing sector, where codes demand proven protection for automated machinery.
Automatic Fire Ball Extinguisher Market Segmentation
The automatic fire ball extinguisher market exhibits distinct segmentation across product characteristics and deployment scenarios. Understanding these segments clarifies the varied needs of end-users and the specific channels through which products reach them. Market segmentation reveals where demand concentrates and where future growth opportunities reside.
Type:
The distribution of automatic fire ball extinguishers often aligns with the specific extinguishing agent, influencing procurement channels for different fire classes.
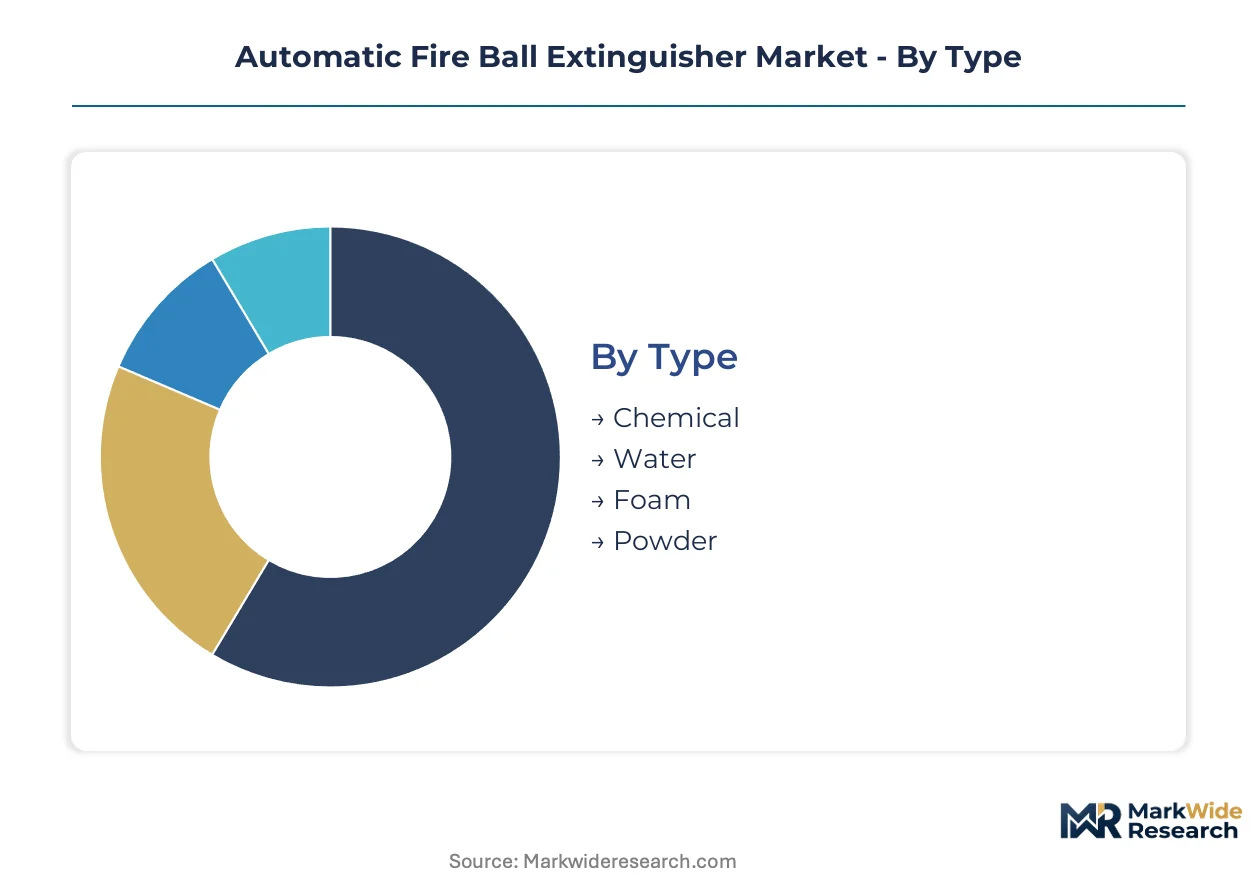
- Powder:These extinguishers typically contain monoammonium phosphate, effective against Class A, B, and C fires by smothering and chemical interruption. Demand concentrates in industrial facilities and commercial server rooms due to their broad efficacy and suitability for electrical fires.
- Chemical:Chemical agents, including various dry chemicals, interrupt the chemical reaction of a fire, offering rapid suppression for diverse fire types. This type finds significant demand in specialized manufacturing environments and chemical storage facilities, where precise extinguishing action is critical.
- Water:Water-based extinguishers cool burning materials, primarily used for Class A fires involving ordinary combustibles like wood or paper.
- Foam:Foam agents create a barrier between the fuel and oxygen, effective against Class A and B fires, often deployed in areas with flammable liquids.
By volume, Powder types lead. By growth pace, Chemical types are ahead.
Application:
Segmentation by application highlights the diverse end-use environments, each with unique fire safety requirements and procurement priorities.
- Commercial:This segment includes server rooms, electrical cabinets, and office spaces, where automated suppression protects critical infrastructure. Stricter fire safety codes influence deployment in commercial settings, particularly for unattended equipment.
- Industrial:Industrial applications cover manufacturing plants, logistics hubs, and remote substations, focusing on protecting machinery and high-value assets. The proliferation of automated systems in unmanned industrial spaces drives this segment's demand.
- Residential:Residential use targets kitchens, garages, and workshops, providing localized protection against common household fire risks.
- Marine:Marine applications involve protecting vessels and offshore platforms from fires, requiring robust solutions resistant to harsh environmental conditions.
The commercial sector holds the largest share of deployments. The industrial sector demonstrates the steepest expansion trajectory.
Installation:
The method of installation dictates deployment strategy and coverage area, reflecting varying facility designs and protection needs.
- Fixed:Fixed installations involve permanent placement of units within a specific enclosure or area, ensuring continuous, localized protection for high-risk equipment. This approach is prevalent in data centers and electrical panels, where precise targeting is essential.
- Wall-Mounted:Wall-mounted units are strategically placed on walls to cover specific areas, offering visible and accessible protection. This installation method is common in workshops and smaller commercial spaces, balancing coverage with ease of access.
- Ceiling-Mounted:Ceiling-mounted extinguishers provide overhead protection, suitable for areas where wall space is limited or where fire origination is expected from above.
- Portable:Portable units offer flexible, on-demand suppression for smaller, localized fire incidents, often used as supplementary protection.
Fixed installations account for the highest volume of units. Wall-mounted installations are gaining share quickly in new constructions.
Activation Method:
The activation mechanism defines the operational autonomy and response time of fire suppression systems, reflecting technological sophistication and safety protocols.
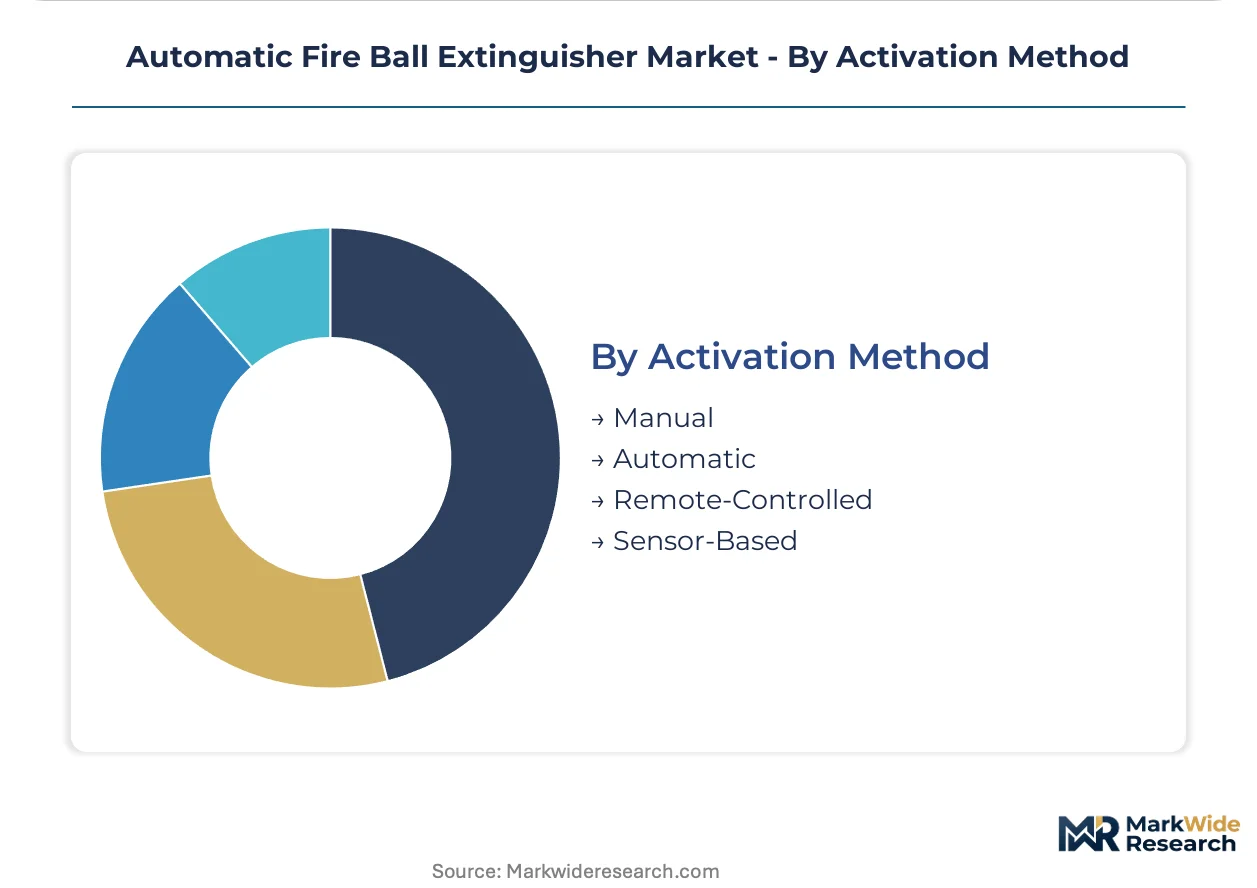
- Automatic:Automatic fire balls self-activate upon contact with flame or when ambient temperatures reach a critical threshold, enabling rapid response without human intervention. This method is crucial for protecting unmanned industrial spaces and remote infrastructure.
- Sensor-Based:Sensor-based systems utilize integrated IoT sensors to detect smoke, heat, or specific gases, triggering suppression and often sending remote alerts. This advanced method is increasingly adopted in critical infrastructure like data centers for enhanced monitoring.
- Manual:Manual activation requires direct human operation to deploy the extinguishing agent, typically found in conventional fire extinguishers.
- Remote-Controlled:Remote-controlled systems allow activation from a safe distance, often used in hazardous environments or large industrial complexes.
Automatic activation methods constitute the largest segment. Sensor-based methods are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stricter fire safety regulations globally are compelling the adoption of automatic fire ball extinguishers in critical infrastructure. These mandates, often influenced by international standards, drive demand for autonomous fire suppression solutions. Governments increasingly prioritize protection for unmanned industrial spaces and high-value assets.
Germany
Stricter fire safety codes for advanced manufacturing facilities drive demand for automated suppression. CE marking requirements and local regulations like those from the KBA (for automotive-related facilities) mandate reliable fire protection. Germany's industrial heartland, particularly in Baden-Württemberg and Bavaria, sees high adoption in automated machinery and logistics hubs.
United States
The expansion of data centers and remote electrical substations fuels demand for self-activating extinguishers. NFPA standards significantly influence fire safety protocols, requiring robust protection for critical infrastructure. Metropolitan areas like Northern Virginia and Silicon Valley, with their concentration of data centers, are key deployment zones.
China
Rapid industrialization and the proliferation of automated systems increase the need for automatic fire suppression. Compliance with national GB standards for fire fighting equipment is mandatory, reshaping product design and market entry. Manufacturing hubs in the Yangtze River Delta and Pearl River Delta are primary consumers for protecting industrial assets.
India
Strengthening fire safety regulations in industrializing regions create significant growth potential for automated solutions. The Bureau of Indian Standards (BIS) sets guidelines for fire safety equipment in commercial and industrial buildings. Major industrial corridors around Maharashtra and Gujarat are experiencing rising demand for advanced fire protection.
Automatic Fire Ball Extinguisher Market Key Industry Players
Player mix skews toward specialized manufacturers focusing on niche applications and established safety equipment providers with broad portfolios. The market structure is characterized by a blend of innovative technology developers and traditional fire safety companies. Strategic archetypes include specialized technology innovators, diversified safety product giants, and regional integrators catering to specific compliance needs. Portfolio diversification and strategic partnerships are dominant competitive moves as vendors seek to expand their market reach.
Specialists in specific fire suppression technologies include Elide Fire Ball Pro Co., Ltd., which represents companies focusing on patented ball-type extinguisher designs for niche applications. These firms often differentiate through unique activation mechanisms or extinguishing agents, targeting specific fire classes or environments. Kidde exemplifies established safety equipment giants leveraging extensive distribution networks for a broader range of fire protection products, spanning various fire safety needs across commercial and industrial sectors. FirePro positions its condensed aerosol technology as an alternative for enclosed spaces, catering to a distinct segment of the market where traditional solutions may not be optimal due to space constraints or sensitive equipment.
| Leading Market Players |
|---|
| Firetech Global |
| Elide Fire Ball Pro Co., Ltd. |
| L. R. INDUSTRIES |
| Kidde |
| Minimax |
| Auto Fireball |
| Universal Fire Protection |
| FirePro |
| Firetrace |
| Others |
Cost & Logistics Intelligence
UL 711 certification in the United States gates product entry and establishes clear price differentiation across product tiers, directly influencing supply chain qualification for manufacturers.
Pricing Analysis
Certification level (UL/CE/GB) creates the primary spread in automatic fire ball extinguisher pricing, distinguishing compliant products from non-certified alternatives. The dominant pricing structure is per-unit transactional, influenced by brand premium and the specific extinguishing agent. Pricing pressure stems from the influx of counterfeit products, which erode legitimate pricing power. The residential segment demonstrates the highest price sensitivity, while critical infrastructure buyers prioritize compliance and reliability over cost.
Supply Chain Analysis
Logistics chokepoints in key manufacturing hubs, particularly in China, underpin the supply chain for automatic fire ball extinguishers. Supply concentration for these devices draws from manufacturing centers in China, Germany, and the United States. Raw material dependencies include monoammonium phosphate, specialized external fuses, and durable casing materials. Regulatory restrictions, such as China's GB standards and Europe's CE marking, present a structural risk by mandating costly product re-engineering. Downstream distribution primarily operates through specialist integrators for commercial and industrial applications, alongside broadline distributors for residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic fire ball extinguisher market is witnessing a buyer-power shift as commercial sector purchasers consolidate demand for certified, pre-engineered solutions rather than standalone products.
For Market Incumbents: Secure multi-regional certifications to counter the influx of non-certified products and maintain market trust. Invest in specialized R&D for smart fire ball integration, leveraging IoT sensors to offer advanced monitoring capabilities. Expand application-specific solutions for high-value assets like data centers, mitigating threats from alternative suppression technologies. Strengthen channel control by partnering with specialist integrators who can design and install validated systems.
For New Entrants and Emerging Players: Lead with specialized solutions for emerging risks like electric vehicle charging stations, targeting underpenetrated application areas. Focus on developing products compliant with strengthening fire safety regulations in industrializing regions, such as Latin America and Southeast Asia. Penetrate the residential market through direct-to-consumer sales channels, offering aesthetically designed units for household use. Develop digital marketing strategies to educate end-users on product benefits and operational limitations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the smart fire ball segment, driven by IoT integration and advanced sensor technologies. The market's long-term viability is anchored in the continuous expansion of unmanned industrial spaces and stricter global fire safety codes. Target niche technology innovators specializing in condensed aerosol or sensor-based activation methods for strategic acquisition. A signal to watch is the strengthening of fire safety regulations in emerging economies, indicating greenfield growth potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Multi-Regional Certification | Ensures market access and builds trust against counterfeit products across diverse geographies. |
| Develop Smart Fire Ball Technology | Integrates IoT sensors for remote monitoring, meeting demand from critical infrastructure operators. |
| Target Electric Vehicle Infrastructure | Addresses a new, high-value application with specific thermal runaway fire risks. |
| Form Partnerships with System Integrators | Facilitates the delivery of pre-engineered, certified solutions for commercial clients. |
| Expand Direct-to-Consumer Residential Channels | Opens a new market segment for localized fire protection in households and workshops. |
Research Approach
Cross-validation between primary interviews with fire safety engineers and secondary analysis of NFPA standards anchors the qualitative findings in this study. Insights were gathered from industry stakeholders including facility managers, regulatory officials, equipment distributors, and product development leads. This primary research was triangulated with secondary data from sources like CE marking guidelines, China's national GB standards, and industrial association reports. Both bottom-up and top-down approaches were utilized to ensure comprehensive market sizing and validation.
Sensitivity analysis informed the forecasting framework, accounting for variables that could impact market trajectory over the projection horizon. The analytical framework modeled segmentation dimensions across product type, application, installation method, activation mechanism, and regional compliance requirements. Compound annual growth rates were derived from historical performance trends and projected demand drivers, including industrial automation rates and the adoption of advanced fire safety codes. Forecast inputs also included the proliferation of unmanned data centers and remote electrical substations.
Forecasts assume regulatory continuity in European CE marking and US NFPA standards; material policy shifts would require re-modeling. The analysis acknowledges potential revisions due to the emergence of superior alternative technologies or significant global economic downturns. Practitioners should keep alternative scenarios live as adoption rates for smart technologies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Suppression Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Fire Alarm and Detection System Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Fireproof Insulation Market
Fire Safety & Protection
Global Flame Arrestors Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Fire and Rescue Helmets Market