
 Fire and Rescue Helmets Market | 2026-2036
Fire and Rescue Helmets Market Size, Share, and Industry Trends Forecast 2026-2036
Fire and Rescue Helmets Market Insights
Modular helmet systems with detachable visors, communication modules, and breathing apparatus interfaces is restructuring how fire departments evaluate procurement. MSA Safety leverages its integrated safety platform to bundle respiratory and head protection, while Dräger anchors its position through deep specialization in European firefighting equipment. Honeywell competes by extending its industrial safety expertise into municipal channels with scalable manufacturing capacity.
Fire and rescue helmets are engineered protective headgear constructed from thermoset composites or high-performance polymers such as Kevlar and carbon fiber, designed to withstand impact forces, radiant heat, and electrical hazards during emergency operations. Their primary purpose is to prevent traumatic brain injury and thermal burns while enabling integrated communication and respiratory systems in hazardous environments. Structural helmets dominate municipal procurement volumes due to NFPA compliance requirements, while carbon fiber variants represent the fastest-growing material segment as departments prioritize weight reduction without sacrificing ballistic protection. Wildland configurations are gaining share in regions facing extended fire seasons, though margins remain thinner than specialized rescue units equipped with integrated thermal imaging mounts.
NFPA 1971 governs structural firefighting helmet performance in North America, while EN 443 sets equivalent benchmarks across European Union member states, and both frameworks are tightening thermal attenuation and impact resistance testing protocols. These standards directly shape manufacturer R&D priorities and create barriers for uncertified entrants seeking access to institutional procurement channels. Stakeholders must monitor evolving NFPA and EN test methodologies alongside emerging dual-certification requirements that could reshape supplier qualification timelines and inventory planning cycles.
Market Dynamics
NFPA 1971 and EN 443 standard revisions are compressing product refresh cycles and forcing manufacturers to re-engineer thermal and impact performance simultaneously, creating asymmetric pressure on R&D budgets and certification timelines.
Growth Catalysts
- NFPA 1971 Thermal Threshold Tightening:North American structural helmet replacement mandates are accelerating municipal procurement as departments face non-compliance risks with updated radiant heat attenuation requirements.
- Carbon Fiber Weight Reduction:Advanced composite manufacturing is enabling ballistic-grade protection at 15-20% lower mass, driving upgrade demand among aging firefighter demographics.
- China Fleet Modernization:Provincial fire bureaus are retiring legacy thermoplastic inventories and adopting EN 443-equivalent certified systems through centralized government procurement frameworks.
Market Restraints
- Kevlar Supply Concentration:Aramid fiber production clusters in the United States and Japan create input vulnerability for European and Asian helmet assemblers during trade friction periods.
- Dual-Certification Cost Burden:Manufacturers targeting both NFPA 1971 and EN 443 markets face duplicated testing expenses that compress margins on mid-tier product lines.
- Extended Wildland Fire Seasons:Budget reallocation toward wildland PPE at lower per-unit prices is cannibalizing structural helmet procurement volumes in fire-prone jurisdictions.
Strategic Opportunities
- India State-Level Procurement Centralization:BIS certification alignment with EN 443 is opening institutional channels as state fire services consolidate purchasing under national framework contracts.
- Integrated Thermal Imaging Mounts:Helmet-embedded camera systems converging with NFPA 1801-compliant imaging are creating premium rescue unit upgrade cycles in urban search-and-specialist departments.
- EU Green Deal Sustainable Materials Mandate:Bio-based thermoset resins and recycled carbon fiber feedstocks are qualifying for preferential procurement scoring in German and French municipal tenders.
Industry Challenges
- Composite Layup Technician Scarcity:Hand-laminated Kevlar-carbon hybrid shell production requires skilled labor pools concentrated in aging European manufacturing regions.
- NFPA 1971 Third-Party Retesting:Certification body backlog extends product launch timelines by 8-14 months, freezing inventory planning and pre-order commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire and Rescue Helmets Market |
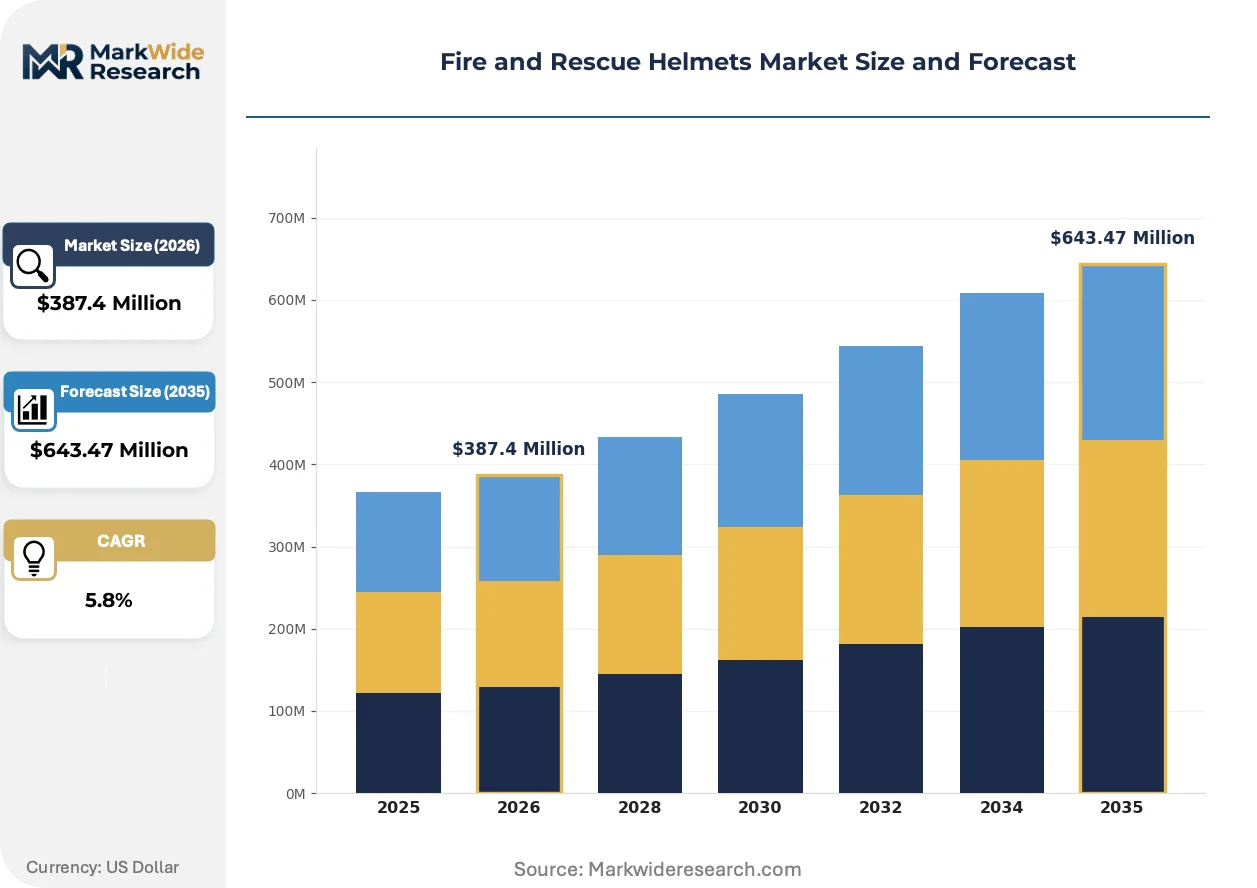
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $643.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural, Wildland, Rescue, Specialized Material: Polycarbonate, Fiberglass, Kevlar, Carbon Fiber End User: Fire Departments, Industrial, Military, Search and Rescue Feature: High Visibility, Heat Resistance, Communication System, Ventilation |
| Companies Covered | Honeywell, MSA Safety, Bullard, Dräger, VIKING Life-Saving Equipment, Rosenbauer, 3M, Avon Protection, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire and Rescue Helmets Market Trends and Innovations
Helmet architecture is fragmenting from standardized monolithic designs toward modular platforms that accommodate mission-specific attachments without full system replacement.
Additive manufacturing of titanium and polymer helmet components is decentralizing spare parts production from centralized foundries to regional service depots. Municipal fire departments with distributed station networks are piloting on-demand chin strap, retention clip, and interface bracket fabrication. This capability is decentralizing aftermarket supply chains and compressing repair turnaround times from weeks to days.
REACH chemical restriction expansions are phasing out legacy halogenated flame retardants in European helmet liner foams. Manufacturers are reformulating with phosphorus-nitrogen intumescent systems that meet EN 443 thermal criteria. German and French certification bodies are requiring additional smoke toxicity testing, extending reformulation validation cycles.
Department-level lifecycle cost modeling is displacing lowest-bid acquisition criteria in United States municipal procurement. Fire chiefs in California, Texas, and Florida are weighting 10-year total ownership costs including refurbishment, component replacement, and communication system upgrade paths. This analytical discipline favors modular platform vendors with transparent upgrade roadmaps over disposable-design competitors.
Fire and Rescue Helmets Market Segmentation
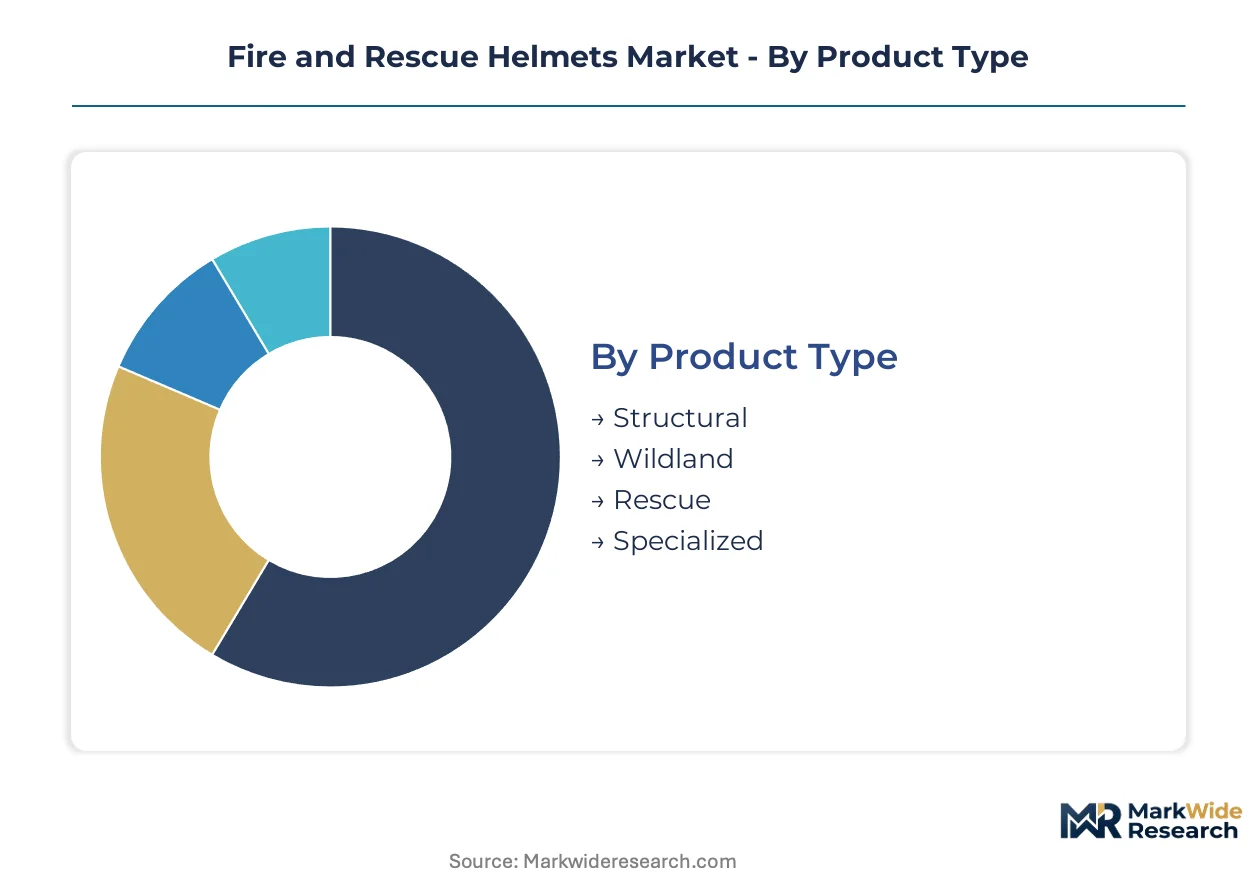
Fire and rescue helmet procurement patterns diverge sharply across mission profiles and material specifications. Manufacturers configure production lines around certification-grade requirements rather than universal platforms, creating distinct supply ecosystems for structural versus wildland configurations.
Product Type:
Supply concentration clusters around structural helmet production due to NFPA 1971 certification infrastructure and municipal procurement volume.
- Structural:Thermoset composite shells meeting NFPA 1971 radiant heat and impact specifications dominate municipal fire department procurement in the United States and Germany. Replacement cycles compress as thermal threshold standards tighten, accelerating refresh demand among aging fleet inventories.
- Wildland:Lighter configurations prioritize ventilation and extended wear comfort for prolonged fireline deployment. Demand concentrates in California, Australia, and Mediterranean Europe where extended fire seasons strain seasonal crew equipment budgets.
- Rescue:Urban search-and-specialist units require integrated thermal imaging mounts and communication interfaces.
- Specialized:Aircraft rescue and hazardous materials variants serve niche industrial and airport firefighting units.
Today's leader: Structural. Tomorrow's challenger: Wildland.
Material:
Cost tier stratification separates premium composite systems from thermoplastic alternatives across procurement channels.
- Carbon Fiber:Advanced layup manufacturing achieves ballistic-grade protection at reduced mass, commanding premium positioning in German and French municipal tenders prioritizing firefighter ergonomic safety.
- Kevlar:Aramid fiber hybrid constructions balance thermal performance with proven durability. United States and Japanese fiber production clusters create supply vulnerability for European assemblers during trade friction periods.
- Fiberglass:Legacy thermoset systems retain cost-sensitive municipal procurement share.
- Polycarbonate:Thermoplastic shells serve training and auxiliary equipment markets.
Carbon fiber configurations are expanding most quickly as departments prioritize weight reduction without sacrificing protection ratings.
End User:
Application-driven demand patterns separate institutional procurement cycles from industrial safety compliance timelines.
- Fire Departments:Municipal agencies in the United States, Germany, and China drive volume through centralized fleet modernization programs and NFPA 1971 or EN 443 compliance mandates.
- Industrial:Petrochemical and manufacturing facilities procure helmets through corporate safety budgets with shorter replacement cycles than municipal agencies.
- Military:Defense firefighting units require dual-certification systems meeting both structural firefighting and ballistic protection specifications.
- Search and Rescue:Mountain and cave rescue organizations prioritize lightweight configurations with extended battery compatibility for communication systems.
Fire departments anchor current procurement volume. Industrial safety compliance represents the steepest expansion trajectory as OSHA enforcement tightens.
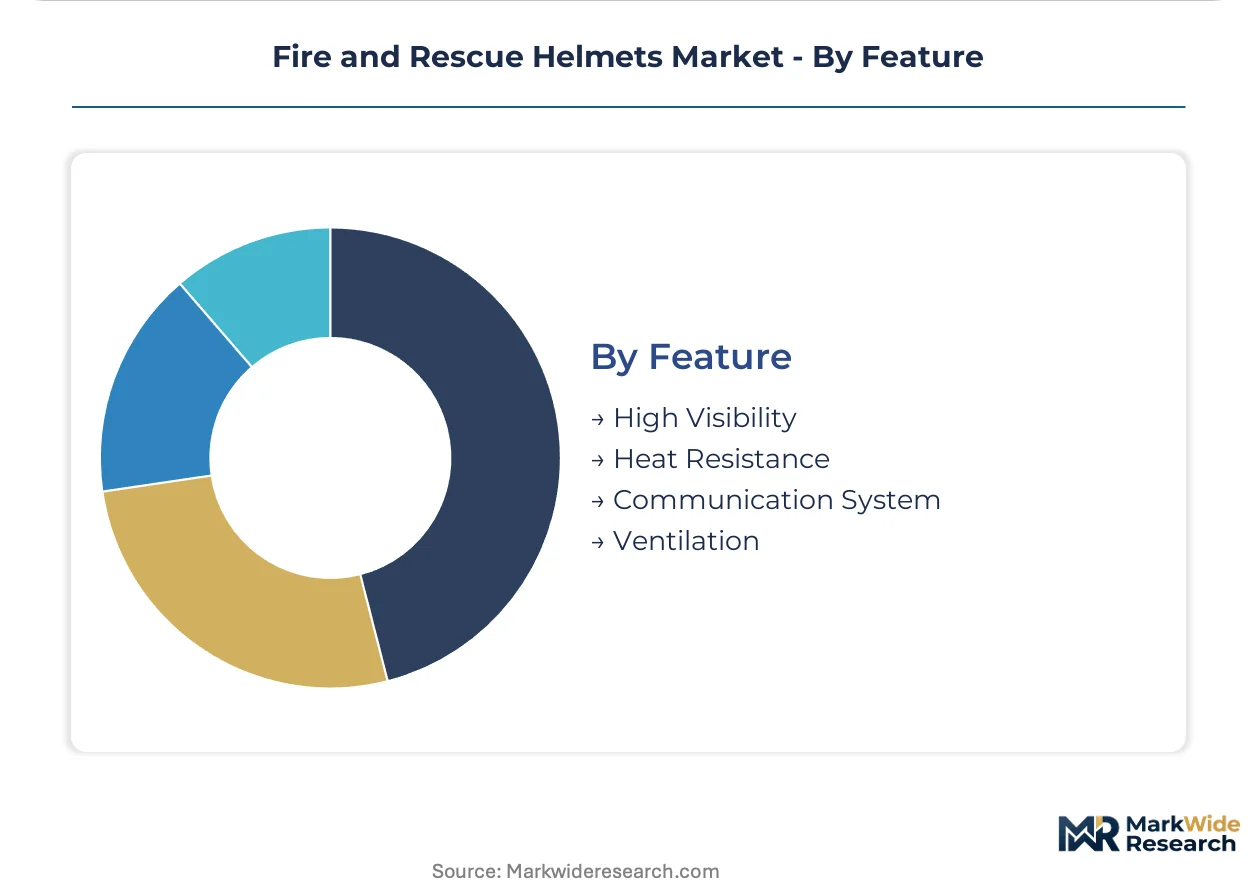
Feature:
Customer type differentiation separates specification-driven municipal buyers from feature-responsive specialist units.
- Communication System:Integrated radio and Bluetooth interfaces enable coordinated incident command in urban environments. Texas and Florida departments weight 10-year upgrade path transparency in procurement scoring.
- Heat Resistance:EN 443 thermal attenuation testing and NFPA 1971 radiant heat requirements drive liner foam reformulation as REACH restrictions phase legacy flame retardants.
- High Visibility:Retroreflective trim and photoluminescent markings support low-visibility operations.
- Ventilation:Adjustable airflow systems reduce heat stress during extended wildland deployment.
Communication integration leads current premium positioning. Heat resistance specifications are climbing fastest as regulatory thresholds tighten across European and North American certification bodies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern fire and rescue helmet manufacturing traces its industrial lineage to post-war safety equipment development in Germany and the United States, where thermoset composite fabrication techniques first achieved municipal-scale production volumes.
United States
Municipal fire departments in California, Texas, and Florida are accelerating structural helmet replacement cycles under tightening OSHA enforcement of NFPA 1971 thermal standards. The National Fire Protection Association's 2024 radiant heat attenuation amendments compress fleet refresh timelines for aging thermoplastic inventories. Pittsburgh-based manufacturing clusters supply aramid fiber composite shells to departments across the Midwest and Southeast.
Germany
EN 443 certification infrastructure anchors European helmet production, with Bavarian and North Rhine-Westphalian industrial zones hosting specialized thermoset layup facilities. The EU Green Deal's sustainable materials mandate is driving reformulation of liner foams with bio-based thermoset resins in advance of 2026 procurement scoring changes. Frankfurt and Munich municipal fire bureaus pilot modular platform acquisitions with transparent 10-year upgrade roadmaps.
China
Provincial fire services in Guangdong, Jiangsu, and Sichuan are retiring legacy thermoplastic helmet fleets through centralized government procurement frameworks aligned with EN 443-equivalent GB standards. The Ministry of Emergency Management's equipment modernization directives prioritize carbon fiber configurations for urban search-and-rescue units. Yangtze River Delta manufacturing clusters are scaling advanced composite production for domestic and export markets.
India
BIS certification alignment with EN 443 is consolidating state-level fire service purchasing under national framework contracts in Maharashtra, Gujarat, and Karnataka. The Bureau of Indian Standards' 2023 personal protective equipment amendments create compliance deadlines for municipal departments operating legacy imports. Mumbai and Ahmedabad industrial safety distributors are building inventory positions ahead of anticipated tender waves.
France
ANSM and labor inspectorate enforcement of EN 443 thermal criteria is accelerating replacement demand among Paris and Lyon metropolitan fire brigades. REACH chemical restrictions are phasing halogenated flame retardants from helmet liner formulations, extending validation cycles for phosphorus-nitrogen intumescent alternatives. Auvergne-Rhône-Alpes manufacturing regions host specialized composite technicians for hand-laminated Kevlar-carbon hybrid production.
Fire and Rescue Helmets Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and material-complexity dimensions, with NFPA 1971 and EN 443 compliance infrastructure serving as the primary tiering mechanism. The vendor base clusters around three strategic archetypes: integrated safety platform providers bundling respiratory and head protection, specialized European firefighting equipment fabricators with deep certification expertise, and industrial safety conglomerates leveraging scalable manufacturing capacity. Dominant competitive moves include vertical integration into aramid fiber supply chains and geographic expansion through dual-certification product lines targeting both North American and European procurement channels.
Among integrated safety platform providers, MSA Safety and Honeywell occupy positions exemplifying the bundling archetype, while Dräger represents the specialized European fabricator model with concentrated certification depth. These three companies anchor the competitive structure through contrasting approaches to municipal procurement engagement.
| Leading Market Players |
|---|
| Honeywell |
| MSA Safety |
| Bullard |
| Dräger |
| VIKING Life-Saving Equipment |
| Rosenbauer |
| 3M |
| Avon Protection |
| DuPont |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's sustainable materials mandate gates qualified supply and premium-tier pricing access, as bio-based thermoset resins and recycled carbon fiber feedstocks qualify for preferential procurement scoring in German and French municipal tenders. Departments lacking certified sustainable inputs face exclusion from high-margin institutional channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber configurations from Kevlar hybrids from thermoplastic alternatives. Certification grade and volume scale drive price differentiation, with NFPA 1971 and EN 443 dual-certified systems commanding substantial premiums. Cost compression in mid-tier Kevlar segments is intensifying because European assemblers face duplicated testing expenses. Training and auxiliary equipment buyers exhibit highest price sensitivity, while urban search-and-rescue units prioritize performance over unit cost.
Supply Chain Analysis
Refurbishment flows for modular helmet platforms are decentralizing aftermarket supply chains as regional service depots pilot on-demand chin strap and retention clip fabrication. Aramid fiber production clusters in the United States and Japan draw from concentrated Kevlar supply, while Yangtze River Delta facilities source carbon fiber feedstocks. Single-source vulnerability in halogenated flame retardant alternatives creates reformulation bottlenecks as REACH restrictions phase legacy inputs. Distribution runs through municipal procurement frameworks and industrial safety distributors to end-use departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Fire departments in California, Texas, and Florida are weighting 10-year total ownership costs including refurbishment and component replacement, displacing lowest-bid acquisition criteria.
For Market Incumbents: Acquire carbon fiber layup manufacturing capacity to secure input cost control against Kevlar supply concentration in United States and Japanese production clusters. Deepen certification infrastructure for dual NFPA 1971 and EN 443 compliance to defend margin position against emerging Asian assemblers. Modular platform vendors with transparent upgrade roadmaps capture procurement preference over disposable-design competitors.
For New Entrants and Emerging Players: Capture white-space in India's state-level procurement centralization as BIS certification alignment with EN 443 consolidates purchasing under national framework contracts in Maharashtra, Gujarat, and Karnataka. Target wildland configurations in Mediterranean Europe and Australia where extended fire seasons strain seasonal crew equipment budgets. Partner with regional composite fabrication facilities to bypass certification body backlog timelines.
For Investors and Strategic Acquirers: Roll-up economics work for specialized European firefighting equipment fabricators because EN 443 certification infrastructure creates durable barriers to uncertified entrants seeking institutional procurement access. Five-to-ten year viability hinges on consolidation of hand-laminated Kevlar-carbon hybrid production capabilities concentrated in aging European manufacturing regions. Monitor NFPA 1971 third-party retesting backlog durations as early signal of inventory planning friction affecting vendor cash conversion cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber Supply | Captive Kevlar sourcing mitigates trade friction exposure for European assemblers. |
| Dual-Certification Product Line Expansion | Simultaneous NFPA 1971 and EN 443 qualification opens transatlantic municipal procurement channels. |
| Modular Platform Development | Detachable visor and communication interfaces enable 10-year upgrade transparency for lifecycle cost modeling. |
| Regional Service Depot Network | Distributed additive manufacturing compresses repair turnaround from weeks to days for distributed station networks. |
| Sustainable Materials Reformulation | Phosphorus-nitrogen intumescent liner foams qualify for EU Green Deal preferential procurement scoring. |
Research Methodology
Bottom-up municipal procurement modeling reconciled against top-down composite shell production tracking forms the analytical core of this study. Primary interviews with fire chiefs, municipal procurement officers, composite manufacturing plant managers, and certification body technical directors combined with secondary validation against NFPA and EN standard documentation, customs trade data, and municipal tender databases. Triangulation across these sources ensures supply-side capacity estimates align with documented institutional demand flows.
Historical replacement cycle analysis informs projection frameworks across the modeling period. Segmentation dimensions include helmet type, material specification, end-user category, and integrated feature configuration. CAGRs derive from fitted trendlines applied to certified unit shipment data, with carbon fiber penetration rates and wildland fire season extension patterns serving as key forecast inputs.
Regulatory standard revision timelines, aramid fiber trade policy shifts, and certification body capacity constraints are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about continued NFPA 1971 and EN 443 alignment without divergence. Practitioners should monitor standard amendment publication schedules and third-party testing queue lengths for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
US Fire Alarm and Detection Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Portable Fire Extinguisher Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Fireproof Insulation Market
Fire Safety & Protection
US Fire Safety Equipment Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market