
 Civil Combustible Gas Alarm Market | 2026-2036
Civil Combustible Gas Alarm Market Size, Share, and Industry Trends Forecast 2026-2036
Civil Combustible Gas Alarm Market Insights
Cloud-connected monitoring subscriptions is realigning how alarm vendors monetize hardware deployments. Honeywell International leverages its building automation ecosystem to bundle gas detection with facility management software. MSA Safety anchors its position through R&D intensity in electrochemical sensor miniaturization. Drägerwerk competes by dominating calibration service contracts tied to industrial installations.
Civil combustible gas alarms detect methane, propane, and carbon monoxide concentrations through catalytic bead or infrared sensing elements, triggering audible and visual alerts when concentrations exceed preset thresholds to prevent explosion or asphyxiation hazards. Fixed gas detectors occupy the largest installed base across commercial kitchens and boiler rooms, though portable gas monitors represent the fastest-expanding margin pool as facility managers adopt personal protective equipment programs. Infrared technology leads premium pricing tiers due to its immunity to sensor poisoning, while catalytic bead systems sustain volume leadership in residential cost-sensitive segments.
Underwriters Laboratories certification requirements in the United States, China's GB standards administered by SAMR, and the EU's CE marking under the Gas Appliances Regulation collectively dictate sensor accuracy thresholds and electromagnetic compatibility testing. Japan's METI enforces additional earthquake-resistant mounting standards that shape product design for Pacific Rim suppliers. Stakeholders must monitor evolving interoperability mandates between gas alarms and smart building platforms before committing to hardware architectures.
Market Dynamics
Cloud-connected alarm architectures are reconfiguring vendor revenue models from one-time hardware sales toward recurring monitoring subscriptions, forcing incumbents to rebuild service capabilities around data analytics platforms.
Growth Catalysts
- China's GB standards tightening:SAMR-administered certification requirements for gas detection equipment are accelerating replacement cycles in multi-family housing developments nationwide.
- Infrared sensing immunity:Sensor poisoning resistance in infrared technology is displacing catalytic bead systems in premium commercial installations where maintenance access is costly.
- Urban corridor concentration:Dense housing stock across Germany, Japan, and the United States is creating concentrated demand pools for retrofit alarm deployments.
Market Restraints
- Electrochemical sensor supply concentration:Miniaturized sensing element production clusters in East Asian foundries, exposing procurement to single-source vulnerability.
- Calibration service lock-in:Industrial end-users face switching costs from multi-year service contracts tied to existing detector fleets.
- Silicon wafer input volatility:MEMS-based sensor fabrication depends on semiconductor substrate pricing subject to foundry capacity constraints.
Strategic Opportunities
- Residential retrofit white space:Aging housing stock in Japan's metropolitan prefectures lacks compliant methane detection, creating mandate-driven installation demand.
- Smart building interoperability mandates:Emerging BACnet and Modbus integration requirements in EU commercial construction specifications favor platform-ready alarm vendors.
- Personal protective equipment programs:Facility management adoption of portable gas monitors is opening margin pools beyond fixed detector installations.
Industry Challenges
- Cross-functional talent scarcity:Electrochemical engineering expertise must combine with IoT firmware development, compressing available hiring pools.
- Multi-jurisdiction certification timelines:Simultaneous UL, CE marking, and METI approval processes extend product launch cycles by 14-18 months.
- Legacy system integration friction:Hardwired alarm networks in existing commercial kitchens resist retrofit to wireless mesh topologies without infrastructure overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Civil Combustible Gas Alarm Market |
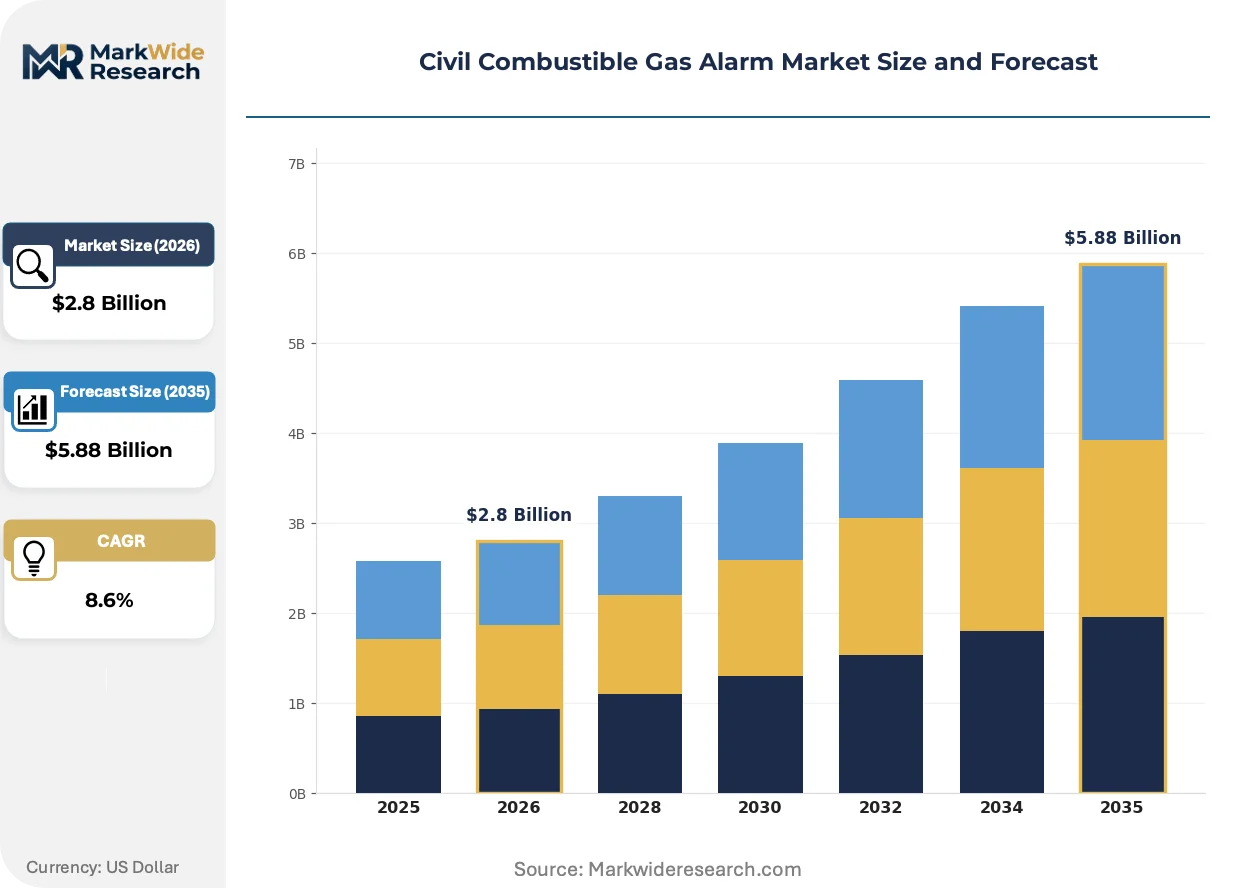
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Gas Detectors, Portable Gas Monitors, Transmitters, Controllers Technology: Catalytic Bead, Infrared, Ultrasonic, Electrochemical End User: Residential, Commercial, Industrial, Hospitality Installation Type: Wall-mounted, Ceiling-mounted, Portable, Panel-mounted |
| Companies Covered | Honeywell International, MSA Safety, Drägerwerk, Industrial Scientific, Siemens, New Cosmos Electric, Riken Keiki, Teledyne Gas & Flame Detection, SGX Sensortech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Civil Combustible Gas Alarm Market Trends and Innovations
Sensor fusion architectures and subscription monetization models are compressing traditional hardware margins while elevating software and service revenue streams across alarm vendor portfolios.
Photoelectric and catalytic bead sensing modalities are converging with edge computing capabilities in next-generation detectors, enabling localized pattern recognition without cloud dependency. Commercial kitchen operators in Germany's hospitality sector are piloting these systems to reduce false alarm rates. This convergence is compressing response latency from detection to alert from seconds to milliseconds, resetting performance benchmarks for life-safety certification.
The EU's Gas Appliances Regulation is tightening electromagnetic compatibility testing thresholds for networked alarm systems, forcing redesigns of RF transmission modules. Industrial boiler room deployments face the steepest compliance burdens under these revisions. German facility managers are responding by consolidating vendor relationships to reduce certification documentation overhead.
Facility management procurement teams are unbundling after-sales calibration from initial hardware purchases, treating sensor maintenance as a separately sourced service category. This pattern disrupts traditional bundled pricing in industrial installations. The shift is most visible across United States commercial real estate portfolios where property management platforms standardize vendor selection through centralized procurement functions.
Civil Combustible Gas Alarm Market Segmentation
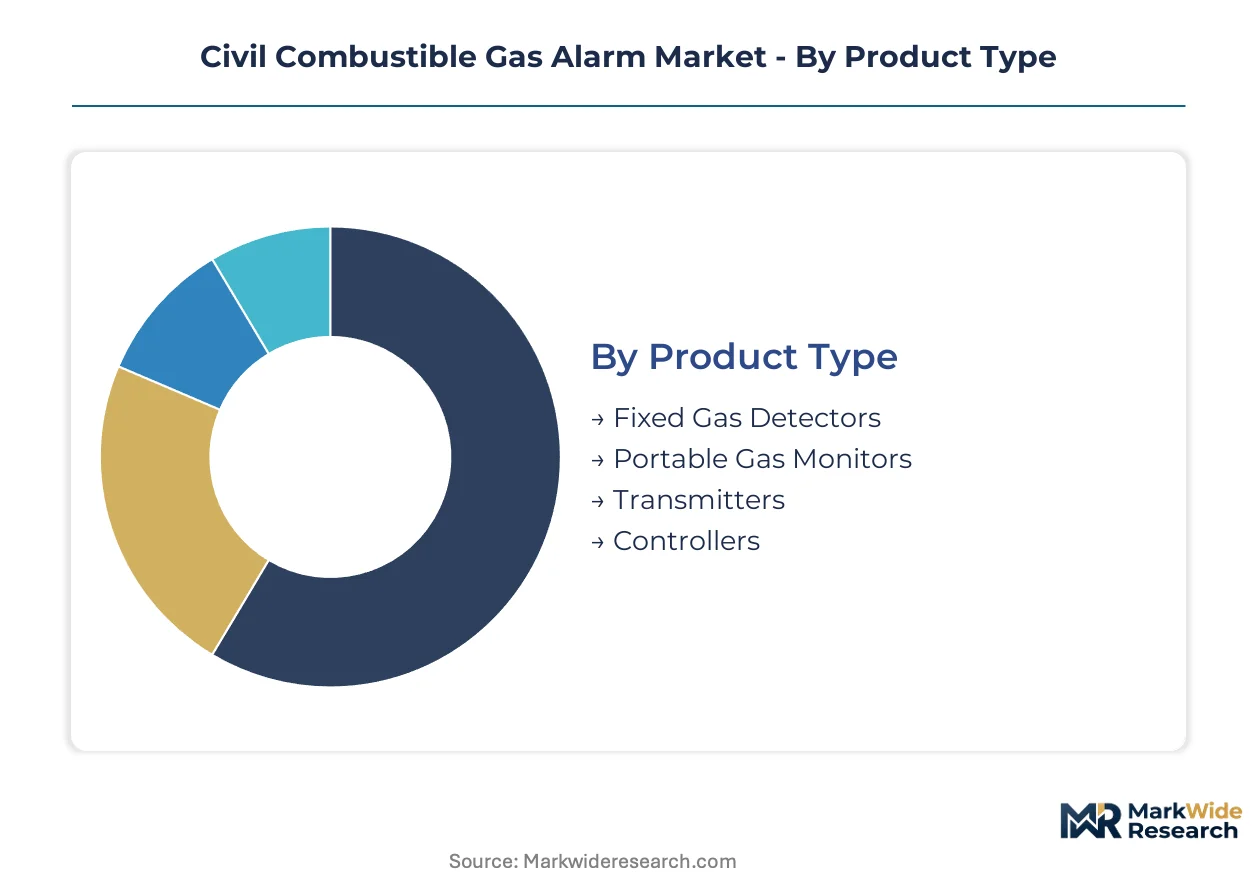
Segmentation in the civil combustible gas alarm market reveals distinct procurement patterns across product architectures, sensing technologies, and installation contexts. Buyers prioritize detection reliability, maintenance accessibility, and integration compatibility when evaluating category options.
Product Type:
Facility managers select product formats based on mobility requirements and coverage scope for their specific hazard zones.
- Fixed Gas Detectors:Permanently installed units with hardwired power and continuous monitoring capability serve commercial kitchens and boiler rooms. Germany's hospitality sector drives concentrated demand as operators retrofit aging infrastructure to meet EU Gas Appliances Regulation compliance.
- Portable Gas Monitors:Battery-powered handheld devices enable personal protective equipment programs for maintenance technicians and emergency responders. Facility management adoption across United States commercial real estate portfolios is expanding this segment most quickly as procurement teams unbundle hardware from calibration services.
- Transmitters:Signal conversion modules bridge sensor outputs to building automation systems through standardized communication protocols.
- Controllers:Centralized processing units aggregate multiple detector inputs and manage alarm relay logic for large-scale installations.
Fixed gas detectors lead on scale; portable gas monitors lead on momentum.
Technology:
Sensing modality selection hinges on target gas chemistry, environmental interference tolerance, and total cost of ownership across the operational lifecycle.
- Infrared:Non-dispersive infrared absorption spectroscopy measures gas concentration without catalytic reaction, eliminating sensor poisoning from silicones or halogenated compounds. Premium commercial installations in Japan's metropolitan prefectures favor this technology where maintenance access is constrained by dense building footprints.
- Catalytic Bead:Wheatstone bridge circuits detect combustible gas through catalytic oxidation on heated platinum filaments. Cost-sensitive residential retrofits across China's multi-family housing developments sustain volume leadership despite vulnerability to contaminant degradation.
- Ultrasonic:Acoustic leak detection identifies gas escape through pressure wave analysis without direct chemical contact.
- Electrochemical:Amperometric cells measure gas-specific redox reactions with high selectivity for toxic gas detection alongside combustible monitoring.
Catalytic bead systems dominate installation counts; infrared platforms command premium positioning.
End User:
Regulatory mandate intensity and liability exposure shape procurement sophistication across buyer categories.
- Industrial:Heavy manufacturing, petrochemical processing, and utility operations deploy enterprise-grade detection networks with centralized monitoring. Calibration service contracts tied to existing detector fleets create substantial switching costs for facility operators.
- Commercial:Office buildings, retail centers, and educational institutions prioritize BACnet and Modbus integration for smart building interoperability. EU construction specifications are accelerating platform-ready alarm adoption.
- Residential:Single-family and multi-family housing units install standalone or interconnected alarms for methane and carbon monoxide protection.
- Hospitality:Hotels, restaurants, and catering facilities face stringent commercial kitchen ventilation codes driving detector density requirements.
Industrial buyers concentrate spending power; commercial segment gains share fastest through retrofit mandates.
Installation Type:
Mounting configuration determines sensor placement optimization for gas density characteristics and spatial coverage requirements.
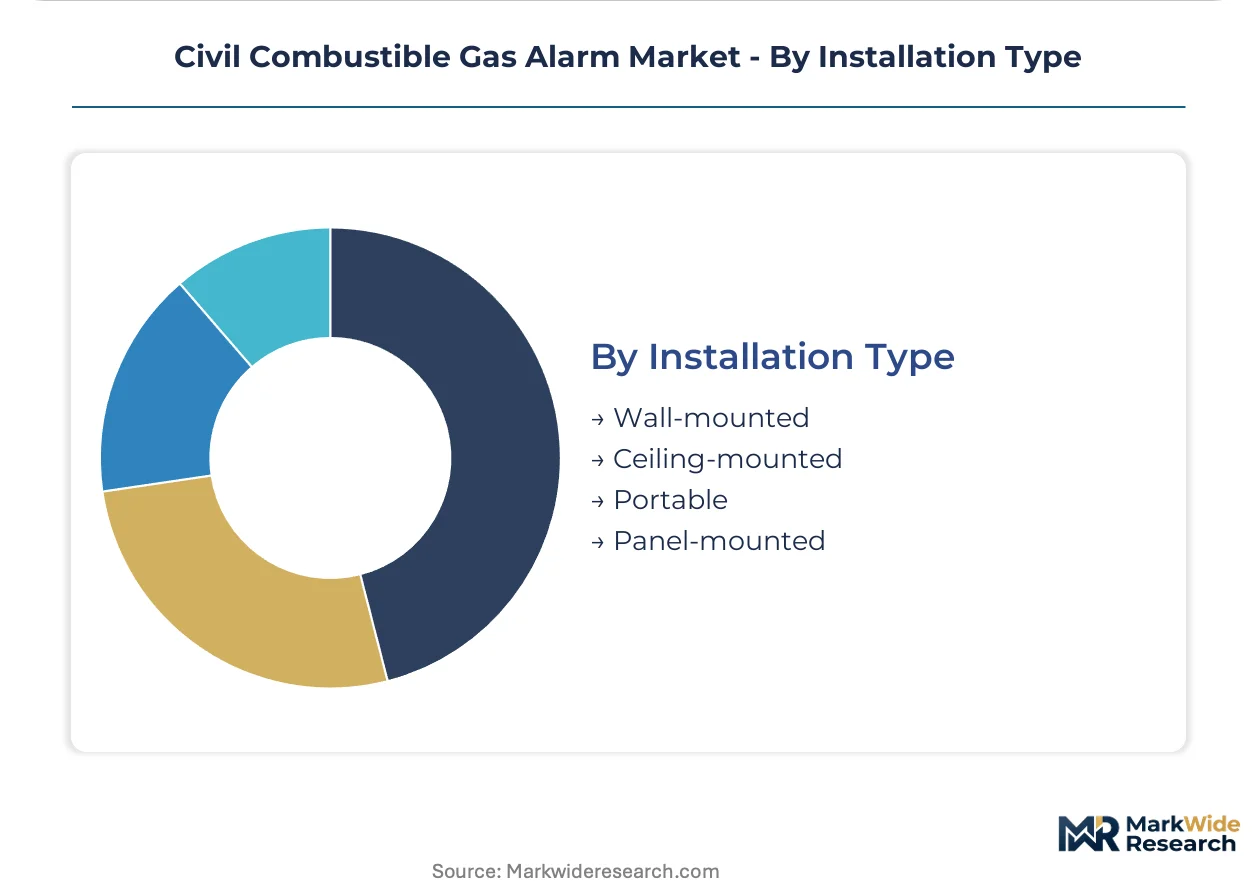
- Ceiling-mounted:Elevated positioning captures lighter-than-air gases like methane in residential and commercial applications. Japan's METI earthquake-resistant mounting standards shape bracket engineering for Pacific Rim suppliers.
- Wall-mounted:Mid-height installation serves general-purpose detection in mixed-gas environments with moderate airflow.
- Portable:Unfixed deployment enables temporary hazard assessment and confined space entry protocols.
- Panel-mounted:Rack-integrated housings consolidate control functions in industrial distributed control systems.
Ceiling-mounted units anchor residential compliance; portable configurations expand through PPE program adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's commercial kitchen retrofit mandates outpace Japan's residential compliance cycles, while China's multi-family housing standards create the largest replacement volume pool.
United States
Commercial real estate portfolios drive portable gas monitor adoption through centralized procurement platforms. OSHA enforcement of confined space entry protocols tightens calibration documentation requirements. Facility managers in Texas and California unbundle hardware purchases from service contracts, reshaping vendor relationships.
Germany
Hospitality sector operators retrofit aging kitchen infrastructure to meet EU Gas Appliances Regulation compliance deadlines. ECHA coordination with national regulators accelerates electromagnetic compatibility testing for networked alarm systems. Munich and Frankfurt facility managers consolidate vendor relationships to reduce certification overhead.
China
Multi-family housing developments in tier-one cities face accelerated replacement cycles under SAMR-administered GB standards tightening. MIIT coordination with local construction bureaus mandates smart building interoperability in new residential projects. Shanghai and Beijing developers specify platform-ready detectors for high-rise retrofits.
Japan
Metropolitan prefectures confront aging housing stock lacking compliant methane detection infrastructure. METI earthquake-resistant mounting standards shape bracket engineering requirements for Pacific Rim suppliers. Osaka and Nagoya building owners face mandate-driven installation demand for ceiling-mounted residential units.
Civil Combustible Gas Alarm Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with industrial safety conglomerates anchoring premium tiers and regional electronics fabricators capturing residential volume. The vendor base organizes around three strategic archetypes: diversified safety conglomerates with building automation ecosystems, sensor technology specialists with electrochemical miniaturization capabilities, and regional calibration service providers with industrial installation footprints. Competitive moves concentrate on strategic partnerships for smart building platform integration and backward integration into MEMS sensor fabrication.
Within the diversified safety conglomerate tier, Honeywell International and Siemens occupy positions defined by building automation ecosystem breadth. MSA Safety exemplifies the sensor technology specialist archetype through electrochemical engineering intensity. Drägerwerk anchors the calibration service provider model with industrial installation contract structures. New Cosmos Electric and Riken Keiki represent Japan-based specialists shaped by METI regulatory requirements. Industrial Scientific and Teledyne Gas & Flame Detection sit within the North American industrial safety equipment fabricator tier.
| Leading Market Players |
|---|
| Honeywell International |
| MSA Safety |
| Drägerwerk |
| Industrial Scientific |
| Siemens |
| New Cosmos Electric |
| Riken Keiki |
| Teledyne Gas & Flame Detection |
| SGX Sensortech |
| Others |
Pricing and Supply Chain Analysis
Silicon wafer spot indices cascade through MEMS sensor fabrication costs, compressing margins at catalytic bead manufacturers while amplifying pricing power for infrared specialists with captive semiconductor supply.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for electrochemical sensing elements. Three-tier pricing structure across premium infrared, standard catalytic bead, and economy residential units separates vendors by certification grade and after-sales bundling. Cost compression in standard tiers is intensifying because facility managers unbundle calibration services. Residential retrofits in China's multi-family housing developments show highest price sensitivity; industrial boiler room operators demonstrate lowest.
Supply Chain Analysis
Calibration equipment refurbishment flows from industrial end-users back to Drägerwerk and MSA Safety service centers, creating reverse-logistics revenue streams that subsidize forward hardware pricing. East Asian foundries in China, South Korea, and Japan concentrate miniaturized sensing element production. MEMS fabrication draws from silicon wafers, platinum catalyst materials, and infrared optical substrates. Single-source vulnerability in East Asian electrochemical sensor foundries poses structural risk. Distribution runs through building automation integrators and industrial safety distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Infrared sensing immunity to poisoning is shifting procurement specifications toward premium tiers that command service-anchored pricing.
For Market Incumbents: Hedge MEMS supply exposure through backward integration into semiconductor substrate sourcing or binding offtake agreements with Yangtze River Delta foundries. Fortify calibration service lock-in against unbundling pressure from United States commercial real estate procurement platforms. Prioritize BACnet and Modbus certification investment to capture EU smart building interoperability mandates.
For New Entrants and Emerging Players: China's GB standards tightening under SAMR administration opens a window for platform-ready detector vendors with integrated cloud connectivity. Japan's metropolitan prefectures present the most penetrable geography given aging housing stock and METI earthquake-resistant mounting requirements. Attack through residential retrofit channels with ceiling-mounted methane detection bundled with seismic-compliant installation services.
For Investors and Strategic Acquirers: Asymmetric upside sits with sensor technology specialists possessing electrochemical miniaturization capabilities and existing calibration service footprints. Five-to-ten year viability favors vendors bridging hardware margins toward recurring monitoring subscriptions. Watch for inflection when portable gas monitor adoption in United States facility management PPE programs accelerates beyond fixed detector replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | BACnet and Modbus compatibility secures EU commercial construction specifications. |
| MEMS Sensor Backward Integration | Captive electrochemical fabrication insulates against East Asian foundry concentration. |
| Calibration Service Unbundling | Separate sensor maintenance pricing disrupts traditional industrial bundled contracts. |
| Residential Retrofit Channel Expansion | China's GB standards tightening accelerates multi-family housing replacement demand. |
| Infrared Technology Licensing | Sensor poisoning immunity commands premium positioning in maintenance-constrained installations. |
Research Methodology
Direct dialogue with facility managers, gas detection system integrators, calibration service technicians, and SAMR certification specialists grounded qualitative findings in operational reality. Secondary validation drew from UL certification databases, METI technical standards filings, EU Gas Appliances Regulation documentation, and China customs trade records. Bottom-up unit economics triangulated against top-down construction spending forecasts.
Segment-level projections across fixed detectors, portable monitors, infrared platforms, and catalytic bead systems were generated through the analysis window. Modeled dimensions encompassed product architecture, sensing technology, end-user vertical, and installation type. CAGRs were derived from replacement cycle analysis, regulatory mandate timelines, and smart building interoperability adoption curves. Forecast inputs incorporated MEMS sensor foundry capacity utilization and commercial kitchen ventilation code enforcement intensity.
Revisions become necessary when semiconductor substrate pricing volatility exceeds historical bands or when multi-jurisdiction certification timelines extend beyond standard 14-18 month windows. Forecasts reflect assumptions regarding GB standards enforcement consistency, EU electromagnetic compatibility testing stability, and facility management procurement centralization trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Global Smoke Evacuation Systems Market
Fire Safety & Protection
Passive Fire Proofing System Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
GCC Firefighting Foam Market
Fire Safety & Protection
Fire Protection Systems Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Fire Hose Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
US Fire Alarm and Detection Market