
 Global Flame Arrestors Market | 2026-2036
Global Flame Arrestors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flame Arrestors Market Intelligence
Direct sales channels from specialist manufacturers to large engineering, procurement, and construction firms is reconfiguring how critical safety components are specified in new projects. This shift privileges suppliers with deep technical expertise and certified product lines. Emerson Electric Co. leverages its extensive process automation portfolio to bundle safety devices into larger system sales. PROTEGO Braunschweiger Flammenfilter GmbH specializes in high-performance detonation and deflagration arrestors for complex applications. Elmac Technologies Ltd competes on customized engineering solutions for specific industrial gas groups and operating pressures.
A flame arrestor is a passive safety device installed in a piping system or on a vessel opening to prevent the propagation of a flame front. The device functions by quenching the flame, typically using a metallic mesh or crimped metal ribbon element that absorbs and dissipates heat below the gas's autoignition temperature. In-line arrestors, integrated within pipelines, command a significant share of the market. Demand for high-performance detonation arrestors is expanding, particularly for applications in petrochemical processing and gas treatment facilities where ignition risks are severe.
The market's structure is heavily influenced by safety regulations like the US OSHA's Process Safety Management standards and the EU's ATEX directives. Global standards such as ISO 16852 provide a common framework for testing and certification, which facilitates international trade. These regulations directly link compliance requirements to equipment demand, making certification a primary purchasing criterion. Future equipment selection will increasingly hinge on verified performance data against specific gas groups and operational pressures, moving beyond nominal compliance.
Market Dynamics
Regulatory codification of process safety standards is the central structural force shaping the flame arrestor market. Compliance with frameworks like Europe's ATEX directives and US OSHA regulations directly translates into equipment demand, making certification the primary purchasing criterion.
Growth Catalysts
- Biofuel & LNG Expansion:New construction of biofuel production plants and liquefied natural gas (LNG) facilities, particularly in the United States and Australia, creates baseline demand for certified safety devices in all new process streams.
- Regulatory Harmonization:The adoption of global standard ISO 16852 provides a unified testing and performance framework, which simplifies international trade and allows manufacturers to access multiple markets with a single core certification.
- Process Safety Management:Stricter enforcement of process safety management rules in the petrochemical and chemical industries compels operators to upgrade or install certified flame arrestors on existing infrastructure to mitigate explosion risks.
Market Restraints
- High Input Costs:The necessity of using expensive, corrosion-resistant alloys like Hastelloy or Monel for applications involving aggressive chemicals significantly increases the capital cost of high-performance arrestors, impacting project budgets.
- Performance Degradation:In process streams with high particulate content, arrestor elements are susceptible to clogging and fouling, which degrades performance and necessitates frequent, costly maintenance cycles to ensure safety and operational uptime.
- Alternative Safety Systems:For lower-risk applications, end-users may opt for alternative safety measures such as process inerting with nitrogen or enhanced process control logic, substituting the need for a physical flame arrestor.
Strategic Opportunities
- Hydrogen Infrastructure:The build-out of a global hydrogen economy presents a significant opportunity, as pipelines, storage tanks, and fuel cells will require new flame arrestors specifically designed and certified for hydrogen's unique combustion properties.
- Smart Device Integration:Incorporating sensors to monitor pressure drop and temperature across the arrestor element allows for predictive maintenance, creating a new service-based revenue stream and enhancing plant safety through real-time monitoring.
- Emerging Petrochemical Hubs:Rapid industrialization and investment in new petrochemical and refining capacity in Southeast Asian nations provide new geographic markets for flame arrestor manufacturers beyond traditional centers of demand.
Industry Challenges
- Complex Certification Pathways:Navigating the long and costly process of obtaining certifications for multiple global standards, such as ATEX and UL, for various gas groups and device types presents a significant barrier for new market entrants.
- Retrofit Integration Complexity:Integrating modern flame arrestors into aging industrial facilities during retrofits poses a substantial engineering challenge, requiring custom fabrication and careful planning to ensure compatibility with existing piping and instrumentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flame Arrestors Market |
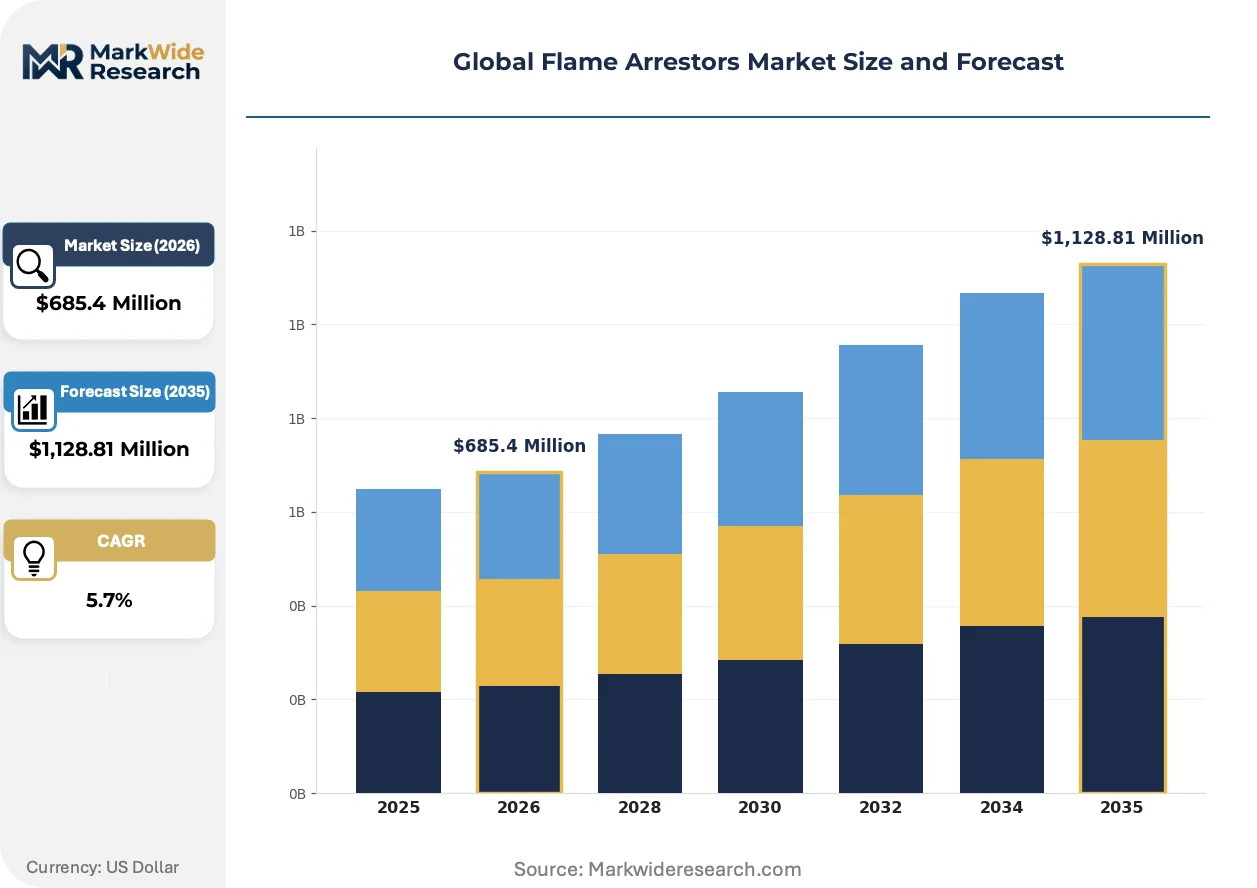
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,128.81 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Line Arrestors, End-of-Line Arrestors, Detonation Arrestors, Industrial Arrestors, Catalytic Arrestors Technology: Metallic Mesh, Ceramic Media, Packed Bed, Quench Tube, Composite Materials Application: Oilfield Equipment, Petrochemical Processing, Storage Tanks, Gas Treatment Facilities, Power Generation Units End User Industry: Refining Plants, Chemical Processing Firms, LNG Facilities, Biofuel Production, Marine Fuel Systems |
| Companies Covered | Emerson Electric Co., Pentair plc, PROTEGO Braunschweiger Flammenfilter GmbH, Elmac Technologies Ltd, The Protectoseal Company Inc., Honeywell Safety Products, Fike Corporation, Groth Corporation, TechnipFMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flame Arrestors Market Strategic Shifts & Innovations
The market is shifting from nominal compliance towards a demand for verified performance. End-users increasingly require data-backed assurance that a specific flame arrestor model will perform reliably under their exact operational pressures and process gas compositions, pushing manufacturers toward more sophisticated validation methods.
Computational Fluid Dynamics (CFD) modeling allows for the detailed simulation of flame propagation and quenching within an arrestor design. Specialist manufacturers and engineering firms adopt CFD to optimize element geometry for specific gas groups. This technology is virtualizing the costly and time-consuming process of physical prototyping and testing, accelerating the development of next-generation devices.
The European Union's ATEX directives are setting a de facto global benchmark for equipment used in potentially explosive atmospheres. This framework imposes rigorous testing, quality assurance, and documentation requirements on manufacturers wishing to access the European market. Consequently, suppliers in North America and Asia often pursue dual certification to meet both local standards and ATEX requirements.
A move toward specifying safety equipment via large Engineering, Procurement, and Construction (EPC) firms is altering purchasing behavior. This model favors manufacturers that can provide extensive technical documentation and pre-certified product lines that can be bundled into large project bids. This trend is most prominent in new large-scale energy infrastructure projects, particularly within the US Gulf Coast petrochemical corridor.
Global Flame Arrestors Market Segmentation
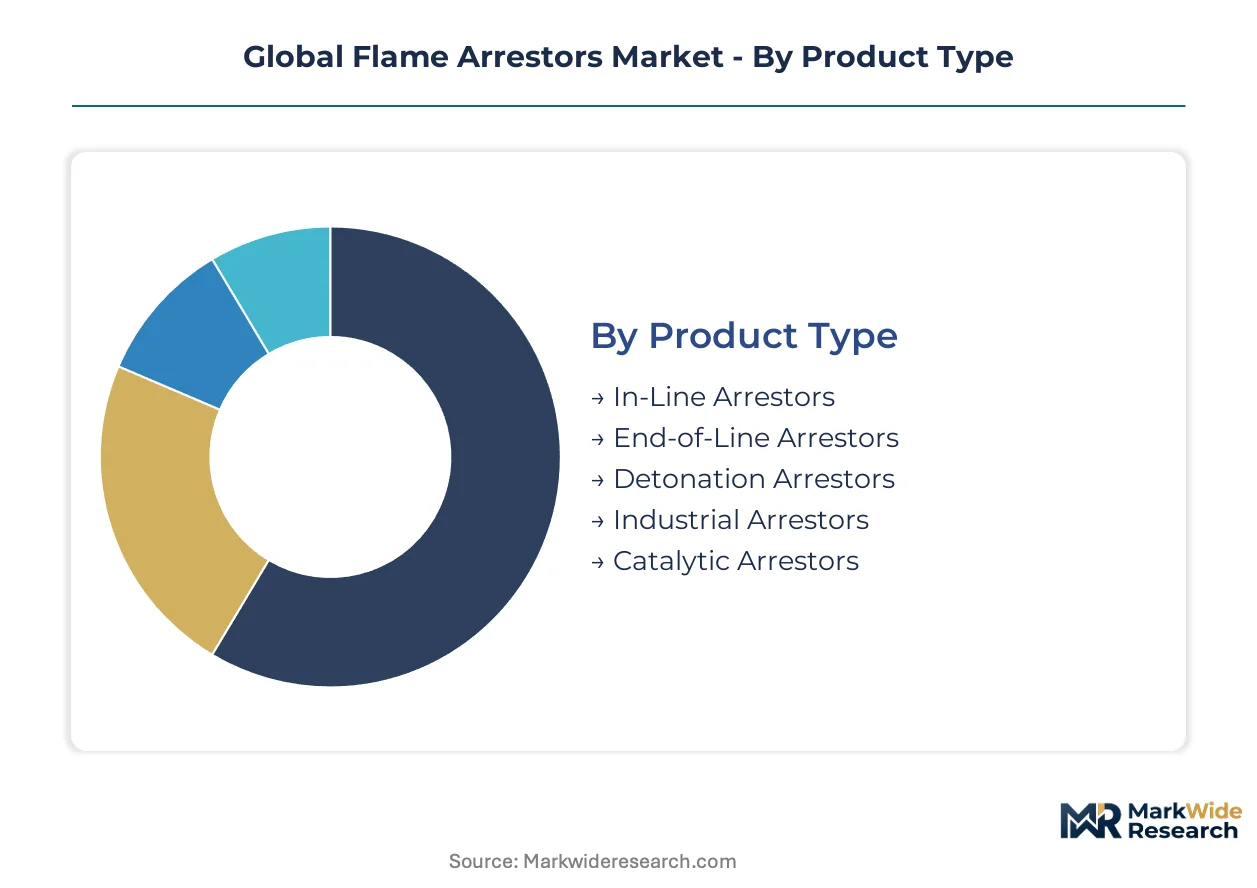
The global flame arrestors market segmentation illuminates the diverse technical requirements and application specificities driving product development and demand. Each segment reflects distinct operational challenges and regulatory compliance needs within industrial safety protocols.
Product Type:
The product type segment reflects a blend of mature, established designs and specialized, high-performance solutions addressing evolving safety requirements across various industrial settings.
- In-Line Arrestors:These devices are integrated directly into piping systems to prevent flame propagation within a pipeline. Demand concentrates in continuous process industries like petrochemicals and chemical manufacturing where system integrity is paramount.
- End-of-Line Arrestors:Installed at the atmospheric opening of a vessel or pipe, these devices prevent external ignition sources from entering the system. Their demand is robust for storage tanks containing volatile liquids, particularly in oil and gas storage facilities.
- Detonation Arrestors:Engineered to withstand and quench supersonic flame fronts, these high-performance devices are critical in applications with severe explosion risks. Petrochemical processing and gas treatment facilities in the United States Gulf Coast drive significant demand.
- Industrial Arrestors:This broad category encompasses various designs tailored for general industrial safety applications, often balancing performance with cost-effectiveness.
- Catalytic Arrestors:Specialized for environments with specific chemical reactions, these arrestors prevent flame propagation in processes involving catalytic converters or sensitive gas mixtures.
In-Line Arrestors handle the majority of throughput; Detonation Arrestors are the fastest mover on share.
Technology:
Technology choices for flame arrestors are driven by the specific operational environment and the required flame quenching efficiency for different gas groups.
- Metallic Mesh:Comprising layers of crimped metal ribbons, this traditional technology offers effective flame quenching through heat absorption and is widely used for deflagration arrestors. Demand remains consistent across general industrial safety applications due to its proven reliability.
- Ceramic Media:Utilizing porous ceramic elements, this technology provides high-temperature resistance and corrosion protection for specific chemical process streams.
- Packed Bed:Consisting of granular material, packed bed arrestors are suitable for applications with high flow rates or where specific gas compositions require a deeper quenching matrix.
- Quench Tube:Employing narrow tubes to cool and extinguish flames, quench tube designs are often found in smaller-scale applications or specialized laboratory settings.
- Composite Materials:These advanced materials combine properties like corrosion resistance, high strength, and optimized thermal conductivity for demanding applications in aggressive chemical environments. New LNG facilities in Australia increasingly specify these materials for enhanced durability.
Metallic Mesh technology maintains widespread adoption due to its reliability; Composite Materials are gaining traction for demanding applications.
Application:
Flame arrestor applications span critical industrial sectors, directly correlating with the presence of flammable gases and vapors in process streams.
- Oilfield Equipment:Flame arrestors are essential for safety on drilling rigs, production platforms, and associated infrastructure to mitigate ignition risks from hydrocarbons.
- Petrochemical Processing:This sector represents a core application area, requiring robust flame arrestors for reactors, distillation columns, and storage tanks due to the prevalence of highly volatile substances. Stricter OSHA regulations in the US drive continuous upgrades.
- Storage Tanks:Flame arrestors protect atmospheric storage tanks from external ignition sources, preventing explosions in facilities handling crude oil, refined products, and chemicals.
- Gas Treatment Facilities:Critical for natural gas processing, these facilities utilize flame arrestors in various stages to manage ignition risks associated with methane and other flammable gases. New infrastructure projects in Australia are significant demand centers.
- Power Generation Units:Flame arrestors are used in power plants, particularly those utilizing natural gas or other combustible fuels, to ensure safety within fuel supply lines and exhaust systems.
Petrochemical Processing and Gas Treatment Facilities represent the largest and most stringently regulated application areas.
End User Industry:
End-user industries dictate flame arrestor specifications based on the inherent hazards of their operations and the enforcement of specific safety standards.
- Refining Plants:These facilities are major consumers of flame arrestors, integrating them across numerous process units to manage explosion risks associated with petroleum refining.
- Chemical Processing Firms:Operating with a wide array of flammable and reactive chemicals, these firms require diverse flame arrestor types tailored to specific gas groups and operating conditions. European ATEX directives heavily influence purchasing decisions.
- LNG Facilities:The expanding global liquefied natural gas infrastructure necessitates high-performance flame arrestors for storage, regasification, and distribution terminals.
- Biofuel Production:New biofuel plants, particularly in the United States, create demand for certified flame arrestors to manage ignition risks from ethanol and other combustible organic compounds.
- Marine Fuel Systems:Flame arrestors are crucial for safety in marine vessels, protecting fuel tanks and ventilation systems from flashback and ignition in confined spaces.
Refining Plants drive consistent demand for replacement units; LNG Facilities represent a significant source of new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power for flame arrestors exhibits asymmetry, with European manufacturers often commanding higher margins due to rigorous ATEX certification requirements, while developing markets prioritize cost-effectiveness and local sourcing. This dynamic shapes procurement strategies for global projects, influencing where critical safety components are specified and manufactured. Demand for certified devices consistently rises across industrialized and emerging economies.
United States
New liquefied natural gas (LNG) facilities and biofuel production plants drive significant demand for flame arrestors in the United States. OSHA's Process Safety Management standards mandate stringent safety protocols for existing and new infrastructure. The Gulf Coast petrochemical corridor, from Texas to Louisiana, represents a major concentration of demand for high-performance detonation arrestors.
Germany
Germany represents a core market for high-performance flame arrestors, driven by its advanced chemical processing and industrial manufacturing sectors. The European Union's ATEX directives impose strict compliance requirements, influencing product design and certification across the continent. Bavarian industrial clusters frequently specify specialized arrestors for complex hazardous environments.
Australia
New natural gas infrastructure projects, particularly in Western Australia, are creating substantial demand for advanced flame arrestors. The country's safety regulations, often harmonized with international standards, require robust solutions for LNG and gas treatment facilities. The Pilbara region's energy projects necessitate durable and certified safety equipment for remote operations.
India
India's expanding petrochemical and refining capacity fuels a growing market for flame arrestors, driven by rapid industrialization. The Bureau of Indian Standards (BIS) sets national requirements for industrial safety equipment, ensuring local compliance. Emerging petrochemical hubs along the west coast, including Gujarat, are significant centers for new installations.
Global Flame Arrestors Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical safety devices within larger process control architectures. The market structure is tiered, with global engineering firms specifying certified products from established manufacturers. Strategic archetypes include full-solution providers offering bundled systems, high-performance specialists focusing on complex applications, and regional manufacturers competing on cost and local service. Dominant competitive moves include strategic partnerships with EPC firms and continuous portfolio diversification into new gas groups.
Within the high-performance specialist tier, PROTEGO Braunschweiger Flammenfilter GmbH exemplifies deep technical expertise in detonation and deflagration arrestors for demanding applications. Elmac Technologies Ltd. occupies a position centered on customized engineering solutions tailored to specific industrial gas groups and operating pressures. Emerson Electric Co. represents the broader process automation and control segment, leveraging its extensive portfolio to bundle safety devices into larger system sales for global projects.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Pentair plc |
| PROTEGO Braunschweiger Flammenfilter GmbH |
| Elmac Technologies Ltd |
| The Protectoseal Company Inc. |
| Honeywell Safety Products |
| Fike Corporation |
| Groth Corporation |
| TechnipFMC |
| Others |
Cost & Logistics Intelligence
Bavarian industrial clusters, home to specialized flame arrestor manufacturers, concentrate technical expertise which influences downstream pricing power for high-performance units. This concentration means that complex, certified devices often command premium prices, especially when integrated into large-scale energy projects.
Pricing Analysis
Configured-to-order pricing for specialized flame arrestors contrasts with more standardized per-unit transactional pricing for general industrial applications. Price differentiation stems from rigorous ATEX certification levels and the degree of customized engineering required for specific gas groups. Pricing pressure stems from the necessity of expensive, corrosion-resistant alloys, impacting project budgets for high-performance devices. Petrochemical and LNG facilities prioritize certified performance over cost, exhibiting lower price sensitivity compared to general industrial end-users.
Supply Chain Analysis
Export controls on advanced materials and specialized manufacturing equipment limit the global flow of high-performance flame arrestor components. Geographic supply concentrates in Germany, the United Kingdom, and the United States, where manufacturers possess the necessary technical expertise and certification infrastructure. The supply chain draws from specialized raw materials, including corrosion-resistant alloys like Hastelloy and Monel, and high-quality crimped metallic ribbons. A structural risk involves the complex and costly certification pathways, which restrict the pool of qualified suppliers. Distribution runs primarily through direct sales channels from specialist manufacturers to large engineering, procurement, and construction firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents an early-cycle expansion story, driven by the continuous global build-out of biofuel production and LNG facilities, necessitating new safety equipment installations.
For Market Incumbents:
Harden technical expertise in high-performance detonation arrestors, particularly for hydrogen applications, to secure future market share. Invest in advanced materials R&D and smart device integration to counter the threat of performance degradation from fouling. Leverage extensive process automation portfolios to bundle safety devices into larger system sales, reinforcing channel control with EPC firms. Pursue dual certification for ATEX and ISO 16852 to access multiple international markets efficiently.
For New Entrants and Emerging Players:
Build out specialized product lines targeting the nascent hydrogen infrastructure market, focusing on unique combustion properties. Target underpenetrated emerging petrochemical hubs in Southeast Asian nations with cost-effective, certified solutions. Develop a go-to-market angle centered on computational fluid dynamics (CFD) modeling capabilities to accelerate product development and validation for specific gas groups. Focus on niche applications requiring advanced ceramic media or composite materials for aggressive chemical environments.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized manufacturers with deep technical expertise and robust certification portfolios, indicating long-term viability over the next 5-10 years. Acquisition targets should include high-performance specialists in detonation arrestors or companies with patented technologies for hydrogen applications. The signal to watch is increased M&A activity among smaller, specialized arrestor manufacturers, indicating market consolidation and value creation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Hydrogen-Specific R&D | This initiative positions manufacturers for the emerging hydrogen economy's unique combustion properties. |
| Expand ATEX and ISO 16852 Certification | Dual certification facilitates international trade and meets stringent regulatory requirements for global projects. |
| Develop Smart Arrestor Devices | Integrating sensors enables predictive maintenance and new service-based revenue streams for plant operators. |
| Form EPC Partnership Alliances | Collaborating with large engineering firms secures critical specification in new large-scale energy infrastructure projects. |
| Localize Production in Southeast Asia | Establishing regional manufacturing facilities addresses demand from rapid industrialization and new petrochemical capacity. |
Research Approach
A standing panel of process safety engineers, EPC procurement managers, flame arrestor design specialists, and refinery operations directors provided ongoing calibration for market trends. This primary input was rigorously combined with secondary validation from ISO 16852 standards documents, OSHA incident reports, ATEX certification databases, and industry association publications. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy.
The scenario-bracketing framework integrated various market dynamics over the projection horizon to model diverse outcomes. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived from historical data analysis and projected future demand, incorporating industry-specific forecast inputs like biofuel production capacity expansion plans and LNG terminal construction schedules.
Practitioners should monitor major shifts in global energy policy or unforeseen technological breakthroughs for early signals of market redirection. Forecasts reflect assumptions documented through extensive research and expert consensus. Material shifts in regulatory enforcement or new material science developments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Passive Fire Proofing System Market
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
US Fire Alarm and Detection Market
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Fire Protection Systems Market
Fire Safety & Protection
Fire Rated Cables Market