
 Global Fixed Firefighting Misting System Market | 2026-2036
Global Fixed Firefighting Misting System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fixed Firefighting Misting System Market Analysis
Aftermarket service revenue is rewriting profit expectations across the fixed firefighting misting value chain. FOGTEC Brandschutz GmbH & Co. KG leverages its German engineering base to dominate high-pressure pump refurbishment and nozzle recalibration contracts. Marioff Corporation anchors its position through captive supply of HI-FOG stainless steel tubing and proprietary orifice manufacturing. Tyco Fire Protection Products extends its reach via Johnson Controls' building automation integration, bundling misting activation with HVAC and access control networks.
Fixed firefighting misting systems discharge pressurized water or additives through specialized nozzles at droplet sizes below 1000 microns, creating high surface-area vaporization that displaces oxygen and absorbs radiant heat. The technology serves critical fire suppression roles where water damage minimization matters, including data halls, turbine enclosures, and heritage structures. Water mist systems lead product type revenue due to regulatory preference for fluorine-free alternatives, while hybrid systems combining mist with inert gas represent the fastest-growing category as battery energy storage installations proliferate. Industrial facilities anchor end-user demand, though marine applications command premium pricing through Lloyd's Register and DNV certification requirements.
The EU F-Gas Regulation and REACH chemical restrictions are accelerating fluorinated suppressant phase-outs across European industrial sites. The US National Fire Protection Association NFPA 750 standard and Factory Mutual Global data sheet approvals govern nozzle spacing, water supply duration, and system activation protocols in North American commercial buildings. China's GB standards and Ministry of Emergency Management fire safety directives mandate fixed misting in subway stations and large-scale energy storage compounds. Stakeholders must monitor evolving lithium-ion battery test protocols and emerging aerosol-mist hybrid certifications to anticipate specification shifts before they harden into tender requirements.
Market Dynamics
The EU F-Gas Regulation phase-down is collapsing fluorinated suppressant architectures across European industrial sites, redirecting specification authority toward water-based misting systems with demonstrable thermal runaway containment capabilities. Battery energy storage installations now mandate fixed misting as primary protection, creating specification cascades into data centers and marine engine rooms.
Growth Catalysts
- EU F-Gas Regulation:The phased reduction of hydrofluorocarbon availability forces facility operators in Germany, France, and the Netherlands to retrofit machinery spaces with water mist suppression before 2030 deadlines.
- Battery Energy Storage Systems:Thermal runaway propagation testing under UL 9540A is mandating fixed misting in lithium-ion enclosures across utility-scale installations in California and Texas.
- Data Center Fire Codes:NFPA 75 and insurance underwriter requirements for minimal water damage are specifying high-pressure misting over traditional sprinkler systems in hyperscale facilities.
Market Restraints
- High-Pressure Pump Concentration:German and Italian specialist manufacturers control precision ceramic plunger pump supply, creating single-source vulnerability for system integrators outside Europe.
- Stainless Steel Tubing Costs:316L seamless tubing for marine certification commands 40% premium over carbon steel alternatives, compressing margins in commercial building segments.
- NFPA 750 Spacing Requirements:Strict nozzle density mandates for Class B hazards increase water supply and pump capacity requirements beyond retrofit feasibility in legacy structures.
Strategic Opportunities
- India Industrial Corridors:BIS fire safety mandates for pharmaceutical and semiconductor manufacturing zones in Gujarat and Karnataka are creating first-mover specification windows for misting system providers.
- Aerosol-Mist Hybrid Systems:Converging condensed aerosol generators with fine water mist offers dual suppression chemistry for battery enclosures with limited water supply.
- Marine Retrofit Cycles:Lloyd's Register and DNV certification updates for cruise ship engine rooms are accelerating replacement of CO2 systems with water mist across Mediterranean and Baltic fleets.
Industry Challenges
- Hydraulic Calculation Expertise:System design requires specialized computational fluid dynamics capability to model droplet transport in complex geometries, constraining qualified engineering capacity.
- Multi-Standard Certification Burden:Simultaneous Factory Mutual, VdS, and LPCB approval processes extend product launch timelines by 18-24 months for new nozzle geometries.
- Legacy Building Integration:Retrofitting high-pressure piping into occupied commercial structures requires phased shutdown coordination that conflicts with continuous operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fixed Firefighting Misting System Market |
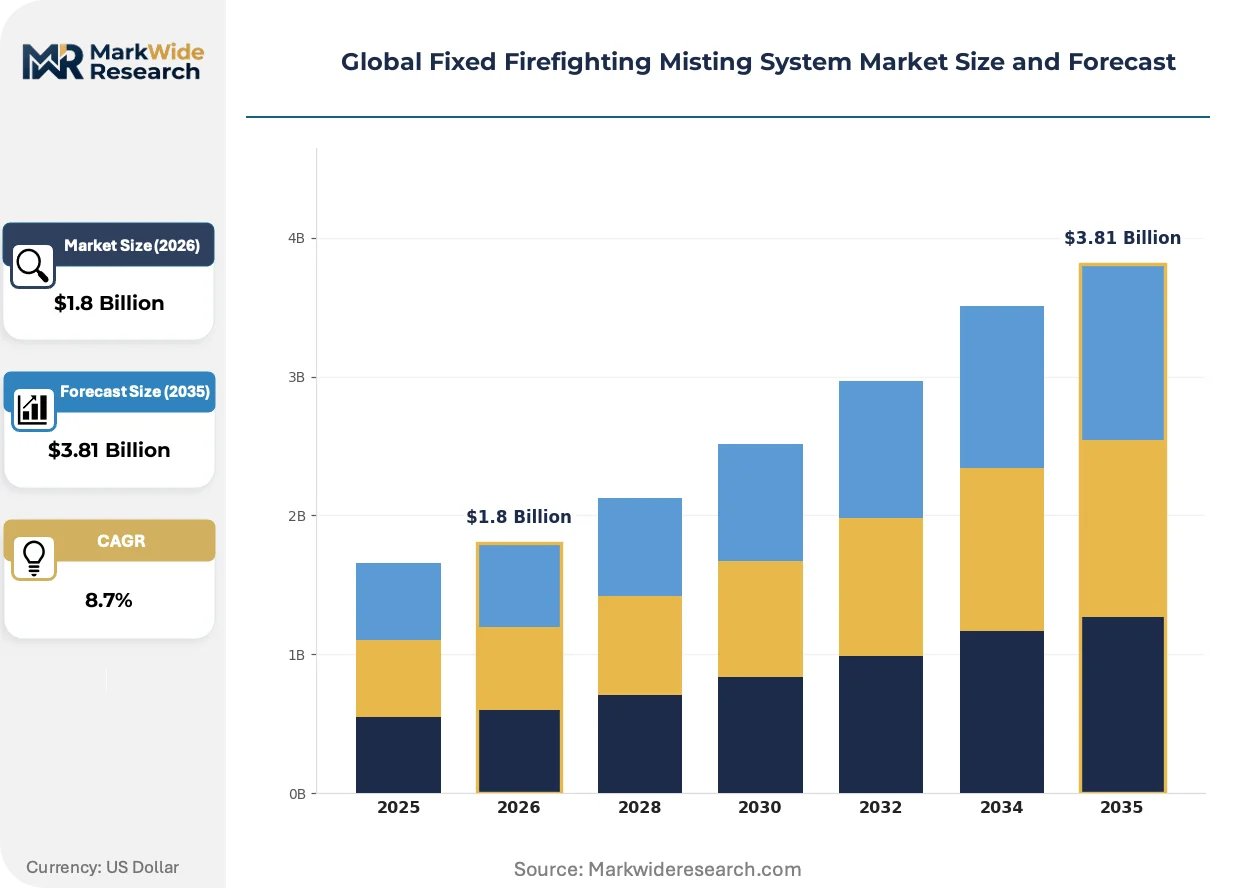
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Mist Systems, Foam Systems, Chemical Agent Misting, Hybrid Systems End User: Industrial Facilities, Commercial Buildings, Oil & Gas, Marine Applications Installation Type: Fixed Installation, Portable Installation, Retrofit Installation, Integrated Systems Application: Fire Protection, Dust Control, Environmental Projects, Special Hazards |
| Companies Covered | FOGTEC Brandschutz GmbH & Co. KG, Marioff Corporation, Tyco Fire Protection Products, Danfoss Fire Safety A/S, Ultra Fog Global Service, Johnson Controls, Swastik Synergy Engineering, Water Mist Systems Inc., SFFECO Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fixed Firefighting Misting System Market Emerging Trajectories
Fixed firefighting misting technology is converging with battery safety engineering and building automation systems, creating specification environments where suppression performance must demonstrate thermal runaway containment under standardized test protocols.
Ultrafine water mist below 50 microns is collapsing the performance gap between water-based and chemical suppression for Class B flammable liquid hazards. Offshore platform operators in the North Sea are specifying these systems for turbine enclosures previously protected by foam. The technology is collapsing insurance premium differentials between water mist and legacy CO2 installations.
REACH chemical restrictions are eliminating per- and polyfluoroalkyl substances from fluorinated suppressant formulations, forcing reformulation investments by European chemical suppliers. Industrial facility operators in Belgium and Sweden face accelerated replacement timelines for existing halocarbon systems. Battery manufacturers are responding by embedding water mist nozzles directly into pack enclosures during assembly.
Specification authority is migrating from mechanical contractors to fire protection engineers with battery safety credentials. Engineering-procurement-construction firms are displacing traditional distributor networks for utility-scale energy storage projects. This concentration is most visible in Germany, where TÜV-certified system designers now control tender specifications for industrial battery compounds.
Global Fixed Firefighting Misting System Market Segmentation
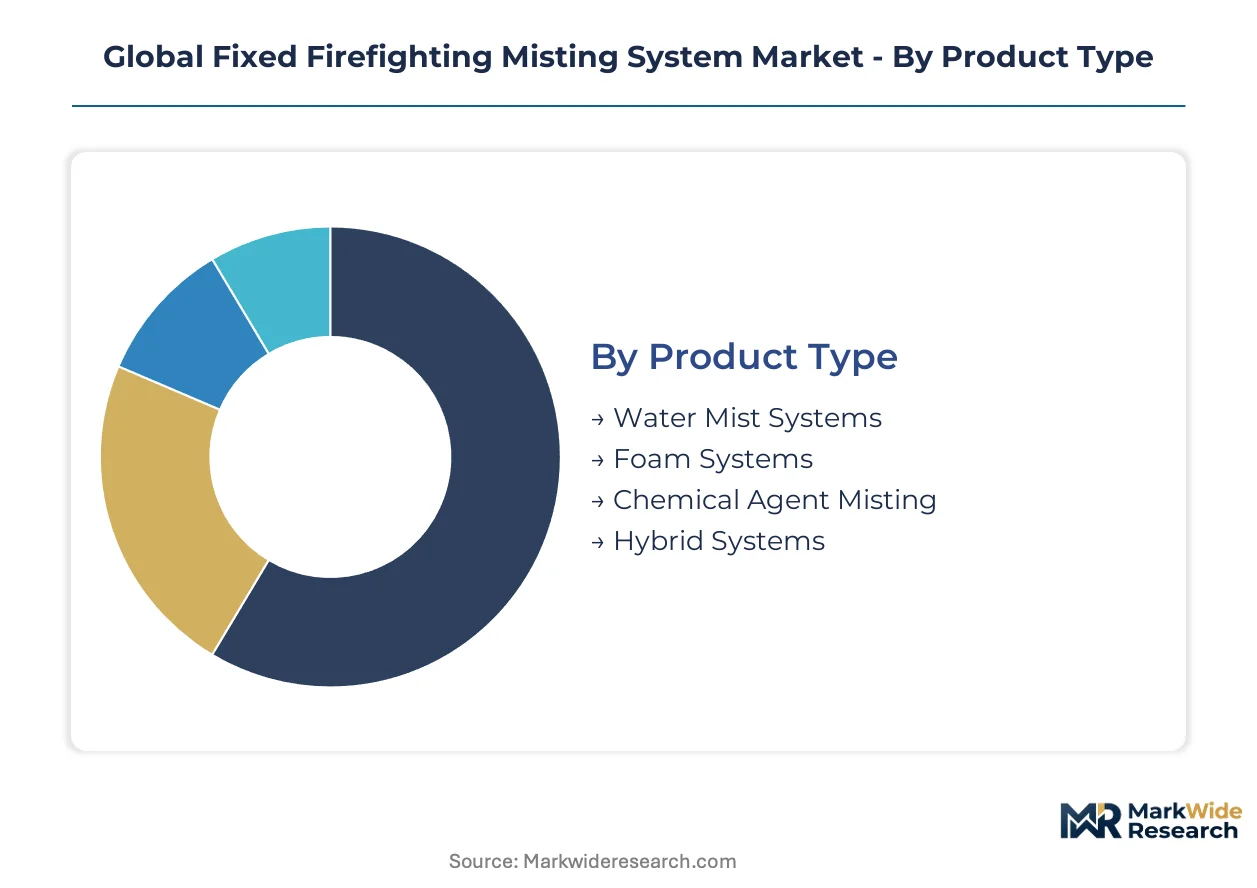
Segmentation in fixed firefighting misting systems reveals distinct procurement cycles and specification authority patterns. Product type selection determines engineering complexity, while end-user verticals dictate certification requirements and replacement timelines. Understanding these segment dynamics exposes where margin concentrates versus where volume flows.
Product Type:
Replacement cycles vary dramatically across suppression chemistries, with hardware refresh timelines stretching from five years for basic water mist to fifteen years for certified marine hybrid installations.
- Water Mist Systems:Pure water discharge through high-pressure pumps at 80-200 bar creates sub-1000 micron droplets for oxygen displacement and cooling. Data centers in Germany and hyperscale facilities in Virginia specify these systems under NFPA 750 and VdS guidelines to minimize water damage to electronics. EU F-Gas Regulation compliance is redirecting chemical suppressant budgets toward water-based architectures.
- Hybrid Systems:Combined water mist with inert gas or condensed aerosol generators addresses thermal runaway in battery energy storage enclosures. Utility-scale installations in California and Texas mandate this configuration under UL 9540A testing protocols. Marine engine rooms across Lloyd's Register-certified fleets are retrofitting CO2 systems with hybrid mist-inert gas combinations.
- Foam Systems:Aqueous film-forming foam integrated with misting nozzles serves flammable liquid hazards in oil storage terminals.
- Chemical Agent Misting:Fluorine-free clean agent formulations delivered through misting hardware protect heritage structures and museums with minimal residue.
Water mist systems dominate installed base. Hybrid systems are where expansion concentrates.
End User:
Specification authority migrates toward engineering-procurement-construction firms in capital-intensive verticals, while commercial buildings retain traditional mechanical contractor channels.
- Industrial Facilities:Manufacturing plants, turbine enclosures, and machinery spaces require VdS or Factory Mutual-approved systems with demonstrated Class B hazard performance. German automotive plants and semiconductor fabrication facilities in Gujarat anchor procurement volume under BIS fire safety mandates. Continuous operations demand redundant pump skids and zoned activation to limit production disruption.
- Marine Applications:Cruise ship engine rooms, offshore platforms, and naval vessels command premium pricing through Lloyd's Register, DNV, and Bureau Veritas certification. North Sea platform operators are specifying ultrafine mist below 50 microns for turbine protection previously served by foam. 316L stainless steel tubing and marine-grade pumps create 40% cost premiums over land-based equivalents.
- Oil & Gas:Refinery process units and storage terminals integrate misting with deluge systems for hydrocarbon fire protection.
- Commercial Buildings:Office towers and retail complexes specify mid-pressure systems where insurance underwriters drive upgrade decisions.
Industrial facilities anchor procurement volume. Marine applications capture the steepest margin expansion.
Installation Type:
Project delivery mode determines margin structure, with integrated systems bundling long-term service contracts while retrofits carry execution risk premiums.
- Fixed Installation:Permanent high-pressure pump skids, stainless steel distribution networks, and zoned control valves designed into new construction. Greenfield data centers in Ashburn and industrial corridors in Karnataka embed these systems during structural steel erection. Factory acceptance testing at manufacturer facilities precedes site commissioning.
- Retrofit Installation:Phased insertion of misting infrastructure into occupied buildings with limited shutdown windows. Legacy commercial structures in Frankfurt face NFPA 750 spacing constraints that expand water supply requirements beyond feasible pump room footprints. Coordination with facility managers and phased evacuation protocols extend project timelines.
- Portable Installation:Mobile pump units and temporary nozzle arrays for construction site protection and event coverage.
- Integrated Systems:Misting activation hardwired into building automation networks with HVAC interlock and access control integration.
Fixed installation commands the largest project pipeline. Retrofit installation presents the most constrained engineering challenge.
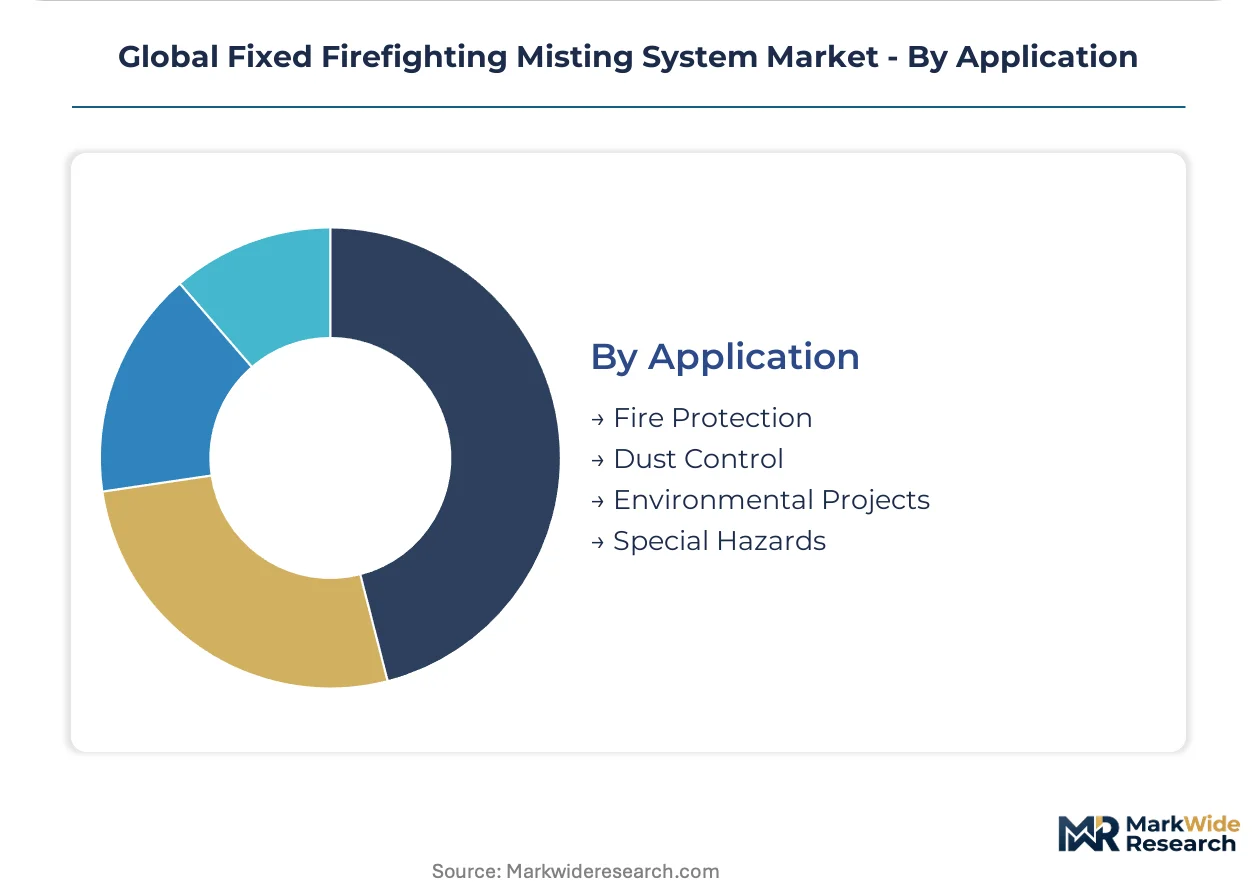
Application:
Functional use case determines droplet size specification, with fire protection demanding the finest atomization and dust control tolerating coarser spray patterns.
- Fire Protection:Primary suppression function across Class A, B, and C hazards with nozzle spacing and water density governed by NFPA 750, VdS 3188, and GB standards. Battery energy storage thermal runaway containment is the fastest-emerging specification driver, with UL 9540A test protocols mandating specific activation sequences and duration requirements. Heritage building protection in Belgium and Sweden prioritizes minimal water discharge to limit structural damage.
- Special Hazards:Transformer vaults, archive storage, and aviation hangars with unique fuel loading and occupancy profiles. Airport authorities in Dubai and Singapore specify misting for aircraft hangars where foam discharge creates environmental compliance burdens. Archives and libraries in the Netherlands deploy systems under cultural heritage protection directives.
- Dust Control:Suppression of combustible dust clouds in grain handling, woodworking, and metal processing facilities.
- Environmental Projects:Odor control and cooling applications at waste treatment and industrial process sites.
Fire protection absorbs the majority of specification engineering hours. Special hazards applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States exhibit the lowest price elasticity, absorbing 40% premiums for marine-certified 316L stainless steel tubing and redundant pump skids. Price sensitivity concentrates in India's emerging industrial corridors and China's commercial building retrofit segments, where mid-pressure systems compete on total installed cost.
Germany
Automotive plants in Bavaria and semiconductor fabrication facilities in Saxony anchor procurement volume for high-pressure water mist systems. The EU F-Gas Regulation mandates hydrofluorocarbon phase-outs by 2030, redirecting chemical suppressant budgets toward water-based architectures. Stuttgart and Munich engineering clusters host TÜV-certified system designers who now control tender specifications for industrial battery compounds.
United States
Utility-scale battery energy storage installations in California and Texas mandate fixed misting under UL 9540A thermal runaway testing protocols. NFPA 750 governs nozzle spacing and water supply duration in hyperscale data centers across Virginia's Loudoun County. Factory Mutual Global approvals remain the gatekeeper for commercial building insurance underwriting in Chicago and New York high-rises.
China
Subway stations in Beijing and Shanghai and large-scale energy storage compounds in Guangdong operate under GB standards and Ministry of Emergency Management directives mandating fixed misting. Domestic pump manufacturers in Jiangsu and Zhejiang challenge German and Italian specialists on cost but lag on precision ceramic plunger technology. Tier-1 cities drive specification authority while inland provinces prioritize retrofit feasibility.
India
Pharmaceutical and semiconductor manufacturing zones in Gujarat and Karnataka operate under BIS fire safety mandates creating first-mover specification windows. Industrial corridor development in Maharashtra attracts system integrators seeking volume scale despite compressed margins. Mumbai and Pune facility managers prioritize phased installation to limit production disruption during retrofit cycles.
United Arab Emirates
Aircraft hangars at Dubai and Abu Dhabi airports specify misting systems where foam discharge creates environmental compliance burdens under local civil aviation authority directives. Offshore platform operators in the Arabian Gulf evaluate ultrafine mist below 50 microns for turbine protection. Premium pricing tolerance reflects Lloyd's Register certification requirements for marine applications.
Global Fixed Firefighting Misting System Market Vendor Landscape
Capability concentration sits with German and Italian precision pump specialists; scale advantage sits with building automation conglomerates bundling misting into integrated fire safety networks. The vendor base stratifies across three tiers: captive tubing and nozzle manufacturers, independent high-pressure pump fabricators, and systems integrators sourcing commoditized components. Dominant competitive moves include backward integration into stainless steel distribution networks and technology licensing agreements that accelerate multi-standard certification timelines.
Within the German engineering tier, FOGTEC Brandschutz GmbH & Co. KG exemplifies the precision refurbishment and recalibration specialist model. Marioff Corporation occupies a position as the captive supply archetype for proprietary stainless steel tubing and orifice manufacturing. Tyco Fire Protection Products, operating through Johnson Controls' building automation infrastructure, represents the integration-focused competitor bundling misting activation with HVAC and access control networks.
| Leading Market Players |
|---|
| FOGTEC Brandschutz GmbH & Co. KG |
| Marioff Corporation |
| Tyco Fire Protection Products |
| Danfoss Fire Safety A/S |
| Ultra Fog Global Service |
| Johnson Controls |
| Swastik Synergy Engineering |
| Water Mist Systems Inc. |
| SFFECO Global |
| Others |
Supply Flow & Price Mechanics
Undercapacity in precision ceramic plunger pump manufacturing across German and Italian specialist facilities is tightening supplier leverage and elevating pricing power for certified high-pressure components. This utilization squeeze propagates through system integrator margins while redirecting procurement budgets toward extended service contracts that lock in aftermarket revenue streams.
Pricing Analysis
Aftermarket service contracts spanning pump refurbishment, nozzle recalibration, and extended warranty coverage drive lifetime value capture across the value chain. Three-tier pricing structure across marine-certified premium, industrial standard, and commercial economy levels segments buyers by certification burden and material specification. Cost compression in mid-pressure commercial segments is intensifying because domestic Chinese pump manufacturers challenge European specialists on landed cost. Data center operators in Virginia exhibit the lowest price sensitivity, absorbing premiums for redundant pump skids, while commercial building retrofit projects in India prioritize total installed cost minimization.
Supply Chain Analysis
Extended payment terms from 60 to 90 days and supply-chain finance facilities anchored in German engineering clusters are stabilizing working capital for precision component fabricators. Manufacturing concentration in Germany, Italy, and China shapes component availability, with Jiangsu and Zhejiang pump producers expanding share in cost-sensitive segments. The supply chain draws from 316L stainless steel feedstock, precision ceramic plungers, and proprietary orifice geometries. Single-source vulnerability around high-pressure ceramic plunger technology presents structural risk. Distribution runs through engineering-procurement-construction firms in utility-scale energy storage, traditional mechanical contractors in commercial buildings, and shipyard integrators in marine retrofit cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed firefighting misting systems sit in early-cycle expansion as battery energy storage thermal runaway mandates cascade specification authority from traditional mechanical contractors toward fire protection engineers with battery safety credentials.
For Market Incumbents: Pre-empt specification migration by embedding nozzle arrays directly into battery pack enclosures during OEM assembly, capturing design-in authority before tender issuance. Deepen backward integration into 316L seamless tubing production to defend margin position against stainless steel cost volatility. Accelerate TÜV and Factory Mutual multi-standard certification pipelines to outpace 18-24 month approval timelines that constrain competitor product launches. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where fire code evolution lags European mandates but insurance underwriter pressure is intensifying. India's pharmaceutical and semiconductor manufacturing zones under BIS mandates offer first-mover specification windows before incumbent service networks entrench. Pursue technology licensing agreements with established nozzle or pump specialists to compress certification timelines and accelerate market entry. For Investors and Strategic Acquirers: Capital is best deployed toward precision refurbishment specialists with captive TÜV-certified service networks and recurring revenue concentration in high-pressure pump overhaul. Long-term viability hinges on positioning upstream of battery energy storage buildout cycles rather than downstream commoditized installation. Monitor UL 9540A thermal runaway test protocol evolution as the critical inflection signal for specification authority shifts and hardware refresh demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Tubing | Captive 316L supply secures marine certification compliance and defends margin against raw material volatility. |
| Multi-Standard Certification Acceleration | Parallel VdS, Factory Mutual, and LPCB approvals compress 18-24 month timelines and preempt competitor entry. |
| Battery Pack Design-In Partnerships | OEM nozzle integration during assembly captures specification authority before EPC tender issuance. |
| Aftermarket Service Network Expansion | High-pressure pump refurbishment contracts generate recurring revenue insulated from new project cyclicality. |
| Aerosol-Mist Hybrid System Development | Dual chemistry configurations address water-limited battery enclosures under evolving UL 9540A protocols. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented specification shifts and code evolution. The research team conducted structured discussions with fire protection engineers, EPC procurement leads, battery safety consultants, marine classification surveyors, and aftermarket service directors. Secondary sources included NFPA 750 technical committee minutes, UL 9540A test reports, VdS certification databases, EU F-Gas Regulation implementation guidance, and Factory Mutual Global data sheet approvals. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers produces volume and value estimates.
Calibration against historical certification timelines, pump shipment records, and installed base replacement cycles validates projection assumptions across the analysis window. The forecast framework models product type, end-user vertical, installation mode, and application function as core segmentation dimensions, with regional regulatory cluster as an additional industry-specific layer. CAGRs derive from penetration rate analysis in battery energy storage and data center verticals, cross-referenced with EU F-Gas phase-down compliance deadlines and marine retrofit cycle timing.
Practitioners should monitor lithium-ion battery test protocol revisions, stainless steel alloy price movements, and Lloyd's Register certification updates for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Fire and Rescue Helmets Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
Fire Alarm and Detection System Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
Africa Fire Suppression Market