
 Fireproof Insulation Market | 2026-2036
Fireproof Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Fireproof Insulation Market Analysis
Market Context
Mineral wool is shifting from legacy industrial applications into commercial and residential envelopes as architects prioritize non-combustible assemblies. Owens Corning leverages its fiberglass manufacturing scale to supply batts and rigid boards across North American distribution networks. Rockwool International A/S anchors European project pipelines with stone wool systems certified to EN 13501-1 Reaction to Fire classes. Johns Manville specializes in engineered mineral wool for high-temperature industrial processes, sustaining margins through technical specification rather than commodity competition.
Technical Definition and Segment Structure
Fireproof insulation encompasses materials engineered to resist ignition, inhibit flame propagation, and maintain structural integrity at elevated temperatures, typically rated by ASTM E84 flame spread index or EN 13501-1 reaction-to-fire classification. Manufacturers produce these materials through melt-spinning of basalt or slag for mineral wool, drawing molten glass for fiberglass, or foaming polyisocyanurate precursors for intumescent polyurethane systems. Mineral wool dominates volume in commercial buildings and industrial facilities where regulatory codes mandate non-combustible assemblies, while spray foam applications in residential retrofits attract faster growth despite higher per-unit costs. Rigid boards command premium positioning in curtain wall and rainscreen applications where dimensional stability and compressive strength determine specification.
Regulatory Frame and Outlook
The U.S. Department of Energy and ICC building codes shape product testing requirements through ASTM E136 non-combustibility and NFPA 285 assembly-level fire propagation standards, while the EU Green Deal and F-Gas Regulation compound thermal-performance mandates with low-global-warming-potential blowing-agent restrictions for foam products. China's Ministry of Emergency Management enforces GB 8624 classification standards that restrict combustible insulation above specified building heights. Stakeholders must monitor divergence between regional test methods and harmonization efforts under ISO 1182 and ISO 1716, as certification complexity directly determines market access costs and competitive positioning.
Market Dynamics
Building code harmonization across jurisdictions is compressing specification cycles and forcing manufacturers to certify products simultaneously under ASTM E84, EN 13501-1, and GB 8624 standards. This regulatory layering is raising fixed compliance costs and advantaging multi-plant operators with in-house testing laboratories.
Growth Catalysts
- EU Energy Performance of Buildings Directive:The directive mandates simultaneous fire-safety and thermal-efficiency upgrades, forcing commercial retrofits to specify non-combustible insulation assemblies.
- Urban high-rise construction:China's tier-one cities are driving A-grade material specification as updated GB fire codes restrict combustible materials above 24 meters.
- Mineral wool melt-spinning:Advances in basalt fiber processing are lowering production costs and expanding stone wool availability for residential envelope applications.
Market Restraints
- Slag and basalt input volatility:Raw material costs for mineral wool fluctuate with steel production cycles and volcanic aggregate availability.
- Blowing-agent restrictions:The EU F-Gas Regulation and state-level hydrofluorocarbon phase-downs in California and Washington are constraining spray foam formulation options.
- Rock wool respiratory hazard classification:IARC monograph findings on respirable crystalline silica content are triggering additional workplace exposure controls and liability premiums.
Strategic Opportunities
- India's building stock expansion:The Bureau of Indian Standards is developing fire-performance test protocols, creating first-mover advantage for certified suppliers ahead of mandatory implementation.
- Prefabricated panel integration:Offsite construction methods are creating demand for factory-integrated insulation with pre-certified assembly ratings.
- Green building certification convergence:LEED v5 and BREEAM alignment on embodied carbon metrics is favoring mineral wool with recycled content and regional material sourcing.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel testing under ASTM, EN, and GB protocols extends product launch cycles by 18-24 months.
- Fire-test engineer scarcity:Qualified professionals capable of interpreting NFPA 285 assembly results and modeling flame propagation are concentrated among a handful of consulting firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fireproof Insulation Market |
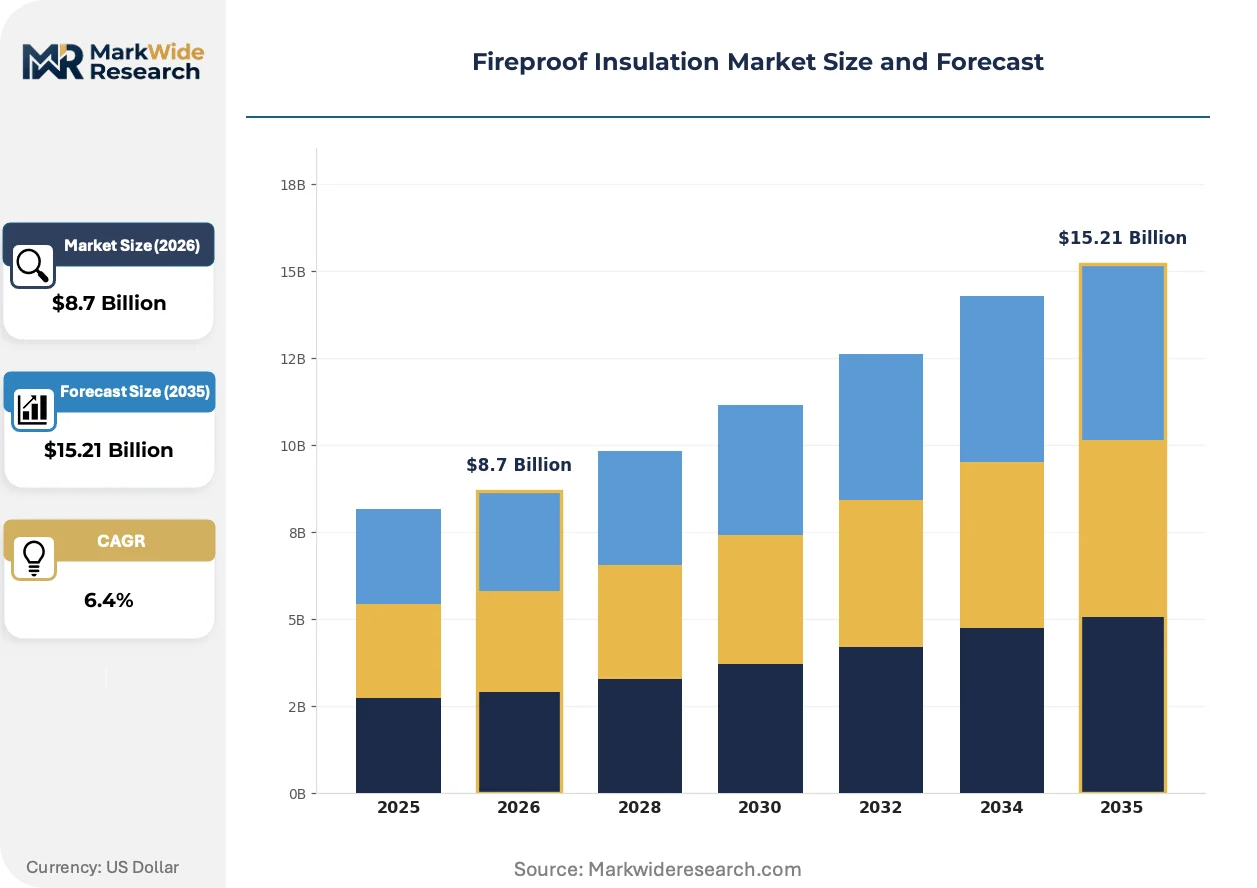
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
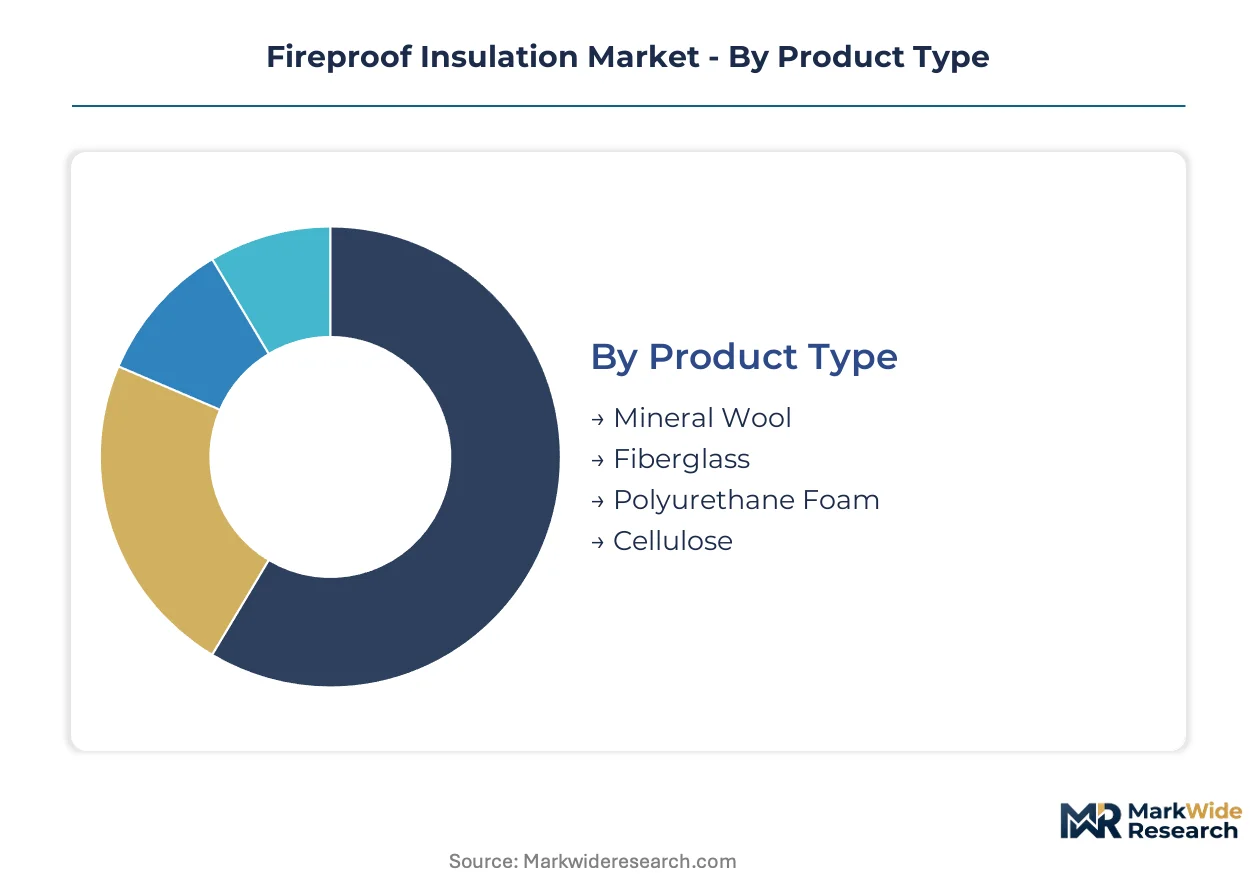
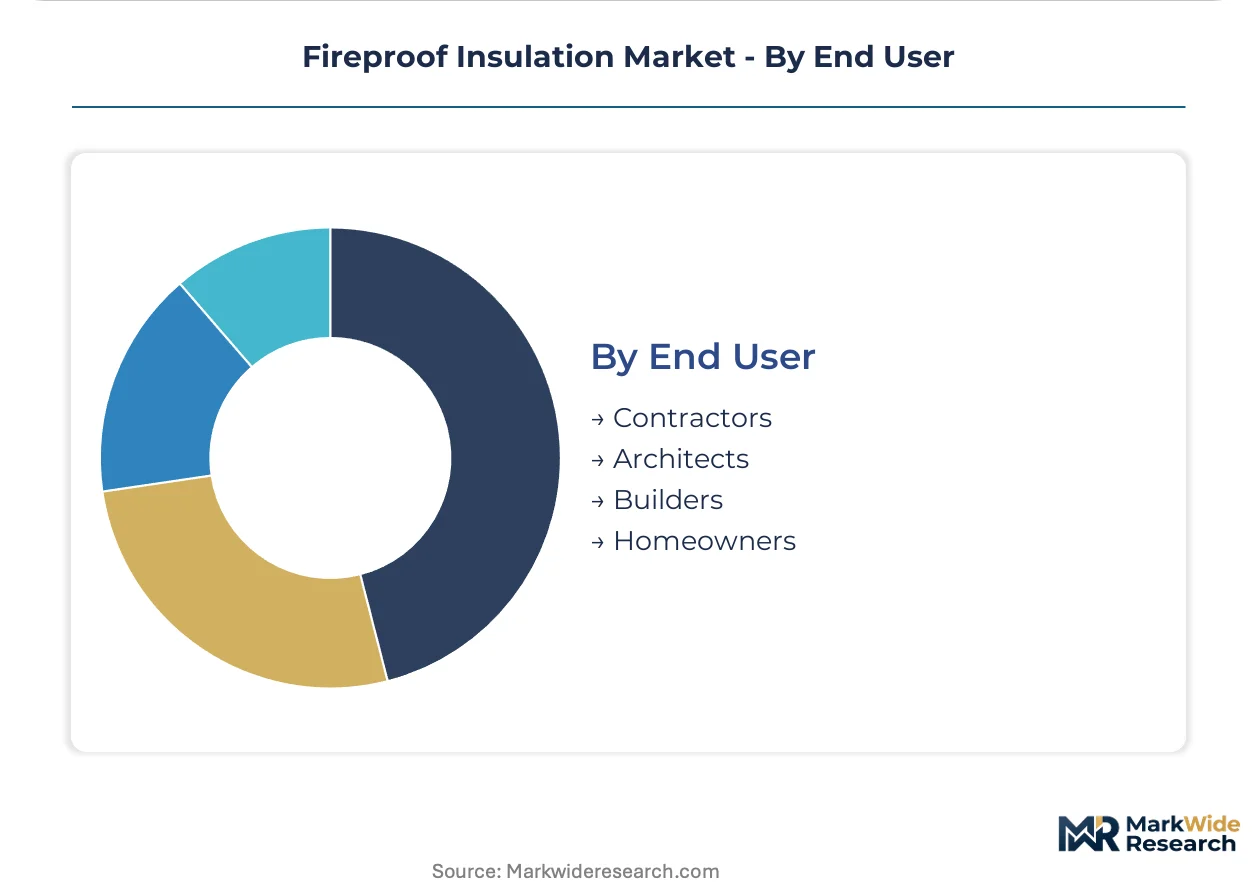
| Segmentation | Product Type: Mineral Wool, Fiberglass, Polyurethane Foam, Cellulose Application: Commercial Buildings, Residential Buildings, Industrial Facilities, Transportation Form: Batts, Rigid Boards, Spray Foam, Blankets End User: Contractors, Architects, Builders, Homeowners |
| Companies Covered | Knauf Insulation, Kingspan Group, Rockwool International A/S, Paroc Group, Etex Group, Owens Corning, Johns Manville, GAF, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fireproof Insulation Market Emerging Trajectories
Product development is pivoting from standalone thermal performance to integrated fire-structural-hygrothermal systems. Manufacturers are embedding sensors and pursuing digital certification pathways to compress specification-to-installation timelines.
Aerogel composites are decentralizing high-performance insulation access. These silica-based materials deliver R-values per inch exceeding traditional mineral wool by 40 percent. Aerospace and data center operators are specifying aerogel blankets for space-constrained envelope retrofits. The technology is decentralizing premium thermal performance from aerospace niche applications into commercial building mechanical rooms and curtain wall spandrels.
The EU F-Gas Regulation is forcing polyurethane foam reformulation. Manufacturers must transition to hydrofluoroolefin or hydrocarbon blowing agents with lower global warming potential. This shift compresses profit margins for commodity spray foam producers while advantaging European operators with captive HFO supply agreements. Rigid board segments in Germany and France are absorbing compliance costs through specification in high-value rainscreen assemblies.
Specification authority is migrating from general contractors to fire-protection engineers. Large commercial projects in the United States now require certified fire-modeling documentation before insulation submittal approval. This shift compresses distributor influence and lengthens pre-construction consultation phases. The pattern is most visible in California and New York where local amendments to the International Building Code trigger enhanced peer review requirements.
Fireproof Insulation Market Segmentation
Fireproof insulation specification diverges sharply across building types, regulatory environments, and installation constraints. Understanding these segment boundaries reveals where manufacturers must certify products versus where commodity positioning suffices.
Product Type:
Buyers differentiate by combustibility rating, thermal performance, and structural integrity under fire exposure.
- Mineral Wool:Melt-spun basalt and slag fibers achieve non-combustible classification under ASTM E136 and EN 13501-1 A1 standards. Demand concentrates in China's tier-one cities where GB 8624 A-grade mandates apply to high-rises above 24 meters, compressing specification windows for foreign suppliers lacking domestic certification.
- Fiberglass:Drawn molten glass delivers cost-competitive thermal resistance with flame spread indices below 25. Commercial retrofits across the United States specify Owens Corning and Johns Manville batts for wall cavity applications where ICC codes mandate tested assemblies.
- Polyurethane Foam:Closed-cell spray and rigid board systems achieve high R-values per inch but face reformulation pressure from EU F-Gas Regulation hydrofluorocarbon restrictions.
- Cellulose:Recycled paper fiber treated with borates offers lowest material cost but requires ignition-barrier protection in attic applications.
Volume sits with mineral wool; growth tilts toward fiberglass as North American commercial retrofits accelerate.
Application:
Regulatory stringency and liability exposure vary dramatically across building categories, reshaping procurement authority.
- Commercial Buildings:Curtain wall, rainscreen, and mechanical room applications demand certified assembly ratings under NFPA 285. Fire-protection engineers in California and New York now control submittal approval, extending pre-construction phases.
- Residential Buildings:Single-family and low-rise multifamily construction favor cost-optimized batt and loose-fill systems. Homeowner demand for spray foam retrofits is climbing fastest in states with aggressive energy codes.
- Industrial Facilities:High-temperature process equipment and pipe insulation specify engineered mineral wool with service temperatures exceeding 650°C. Technical specification sustains margins through performance guarantees rather than commodity competition.
- Transportation:Marine, aerospace, and rail applications require lightweight, space-constrained solutions. Aerogel blankets are gaining share in these sectors where R-value density determines specification.
Commercial buildings absorb the highest certification costs; residential retrofits offer steepest expansion trajectory.
Form:
Installation method dictates labor economics, waste generation, and field-adjustment flexibility.
- Batts:Pre-cut fiberglass and mineral wool segments dominate residential wall cavity and attic applications. Standardized dimensions reduce field cutting and accelerate crew productivity.
- Rigid Boards:Polyisocyanurate and mineral wool boards command premium positioning in curtain wall spandrels and rainscreen applications where compressive strength and dimensional stability are non-negotiable.
- Spray Foam:On-site chemical reaction enables seamless air barrier integration but requires certified applicator networks and triggers heightened OSHA respiratory protection protocols.
- Blankets:Flexible mineral wool rolls conform to irregular industrial equipment surfaces. Pipe and vessel insulation in petrochemical facilities specifies these forms for thermal cycling resistance.
Batts and rigid boards capture current volume; spray foam is expanding most quickly despite regulatory headwinds.
End User:
Specification authority and risk tolerance diverge across the construction value chain.
- Contractors:Value-engineering pressure drives substitution toward lowest-code-compliant options. Distributor relationships and just-in-time delivery capability determine supplier selection.
- Architects:Design-phase authority over fire-rated assemblies is migrating to specialized fire-protection engineers on large commercial projects, compressing traditional insulation specification influence.
- Builders:Production homebuilders prioritize SKU reduction and national distribution coverage. Regional material sourcing requirements in LEED v5 and BREEAM are favoring suppliers with recycled content verification.
- Homeowners:DIY retrofit demand concentrates in states with utility rebate programs and aggressive energy codes. Online educational content is shifting preference toward spray foam despite higher installed costs.
Contractors move the highest tonnage; architects retain premium positioning power in complex commercial envelopes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the highest tonnage of fireproof insulation as urban high-rise construction accelerates, while commercial retrofit programs in the United States and Germany are tightening non-combustible material specifications simultaneously.
United States
Commercial building retrofits in California and New York are accelerating mineral wool and fiberglass specification as state-level amendments to the International Building Code trigger enhanced fire-safety reviews. The Department of Energy and ICC building codes shape product testing through ASTM E136 and NFPA 285 standards. Los Angeles and New York City construction pipelines concentrate demand for certified assembly ratings in curtain wall applications.
China
Urban high-rise construction in Shanghai, Beijing, and Shenzhen is driving A-grade non-combustible material specification as updated GB 8624 fire codes restrict combustible insulation above 24 meters. The Ministry of Emergency Management enforces classification standards that compress specification windows for foreign suppliers lacking domestic certification. Yangtze River Delta and Pearl River Delta construction clusters dominate volume procurement for residential and commercial envelopes.
Germany
Rainscreen and curtain wall retrofits in Berlin, Munich, and Hamburg are absorbing rigid mineral wool boards as the EU Energy Performance of Buildings Directive tightens thermal-efficiency and fire-safety requirements simultaneously. The F-Gas Regulation compounds mandates with low-global-warming-potential blowing-agent restrictions for foam products. Industrial construction in North Rhine-Westphalia sustains demand for high-temperature engineered mineral wool systems.
India
Building stock expansion in Maharashtra and Gujarat is creating specification opportunities as the Bureau of Indian Standards develops fire-performance test protocols ahead of mandatory implementation. Commercial and residential construction in Mumbai and Ahmedabad concentrates early adoption of certified non-combustible insulation assemblies. First-mover suppliers are establishing certification pathways before regulatory deadlines crystallize.
United Kingdom
Post-Grenfell regulatory reforms are accelerating non-combustible insulation specification in London, Birmingham, and Manchester high-rise remediation programs. The Building Safety Regulator enforces stricter gateway compliance for higher-risk buildings. Southeast England construction clusters are prioritizing EN 13501-1 A1-classified stone wool systems for cladding replacement projects.
Fireproof Insulation Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with mineral wool producers holding concentrated positions in commercial and industrial applications while fiberglass suppliers compete on scale in residential retrofits. The vendor base organizes into three strategic archetypes: integrated building materials conglomerates with multi-product insulation portfolios, pure-play mineral wool specialists with vertical control over basalt and slag inputs, and regional fiberglass fabricators serving distributor networks. Dominant competitive moves include capacity expansion in China and India to capture high-rise construction demand, and strategic partnerships with fire-protection engineering firms to compress specification-to-approval timelines.
Within the integrated conglomerate tier, Saint-Gobain and Etex Group exemplify diversified positioning across multiple insulation chemistries and geographies. Among pure-play mineral wool specialists, Rockwool International A/S and Paroc Group occupy positions anchored by EN 13501-1 certification depth and basalt fiber processing expertise. Owens Corning represents the scale-driven fiberglass archetype with North American distribution network density. These three archetypes—conglomerate, pure-play, and scale fabricator—capture distinct risk-reward profiles across regulatory stringency and construction cycle exposure.
| Leading Market Players |
|---|
| Knauf Insulation |
| Kingspan Group |
| Rockwool International A/S |
| Paroc Group |
| Etex Group |
| Owens Corning |
| Johns Manville |
| GAF |
| Saint-Gobain |
| Others |
Supply Flow & Price Mechanics
Melt-spinning automation in basalt fiber processing is compressing production economics while concentrating supply among operators with captive slag sourcing agreements in China and Germany. This technology transition simultaneously lowers unit costs for stone wool and raises barriers for second-tier producers lacking integrated raw material access.
Pricing Analysis
Volume concentrates in commodity mineral wool batts where Chinese producers compete on scale, while margins concentrate in certified rigid boards for curtain wall applications where NFPA 285 assembly ratings command premium positioning. Price differentiation hinges on EN 13501-1 A1 certification depth and regional manufacturing proximity to construction clusters. Pricing pressure stems from EU F-Gas Regulation compliance costs forcing polyurethane foam reformulation. Residential retrofit contractors exhibit highest price sensitivity; commercial fire-protection engineers prioritize certification over cost.
Supply Chain Analysis
Direct-to-contractor channels handle high-volume batt distribution through national building-material distributors, while specification-driven rigid board sales flow through fire-protection engineering consultants. Supply concentrates in China, Germany, and the United States. Basalt and blast furnace slag feed mineral wool production; isocyanate precursors and blowing agents supply polyurethane systems. Single-source vulnerability sits with HFO blowing-agent supply agreements controlled by European chemical conglomerates. Distribution runs through multi-brand distributors with certified installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward control over basalt and slag inputs to defend margin position against raw material volatility and certification cost inflation.
For Market Incumbents: Anticipate regulatory layering by establishing in-house testing laboratories capable of simultaneous ASTM E84, EN 13501-1, and GB 8624 certification. Prioritize capacity expansion in China's Yangtze River Delta to capture A-grade specification demand. Defend against aerogel displacement in data center and aerospace niches by embedding fire-structural sensors in premium mineral wool systems. For New Entrants and Emerging Players: Launch via prefabricated panel partnerships where factory-integrated insulation bypasses field-certification complexity. Target India's Maharashtra and Gujarat construction corridors ahead of Bureau of Indian Standards mandatory fire-performance implementation. Penetrate through aerogel composite distribution for space-constrained mechanical room retrofits where R-value density trumps installed cost. For Investors and Strategic Acquirers: Exit pathways concentrate in conglomerate acquisition of pure-play mineral wool specialists with EN 13501-1 certification depth and basalt fiber processing expertise. Five-to-ten year viability favors operators with integrated slag sourcing and multi-plant geographic diversification. Monitor GB 8624 enforcement consistency in China's tier-one cities as inflection indicator for A-grade material demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Sourcing | Captive supply of volcanic aggregate secures cost position against steel cycle volatility in mineral wool production. |
| Multi-Jurisdiction Certification Investment | Parallel ASTM, EN, and GB testing capability compresses product launch cycles by 18-24 months for commercial projects. |
| Prefabricated Panel Partnership | Factory-integrated insulation with pre-certified assembly ratings bypasses field complexity in offsite construction methods. |
| Aerogel Composite Distribution | Silica-based blanket distribution decentralizes premium thermal performance into commercial building mechanical rooms. |
| Fire-Protection Engineering Alliance | Strategic partnerships with NFPA 285 modeling specialists compress specification-to-approval timelines in California and New York. |
Methodological Framework
Multi-period observation of GB 8624 enforcement patterns, EU Energy Performance of Buildings Directive implementation timelines, and ASTM E84 certification backlogs anchored the trend analysis, supplemented by interviews with plant managers at mineral wool production facilities, fire-protection engineers specifying NFPA 285 assemblies, procurement leads at commercial general contractors, and technical R&D directors at insulation manufacturers. Secondary validation drew from customs and trade data tracking basalt and slag flows, SEC 10-K filings of listed building materials conglomerates, ACC and Cefic industry reports, and building permit databases in Shanghai, Beijing, and Shenzhen. Bottom-up volume estimates triangulated against top-down construction spending allocations.
The input-output matrix framed demand as a function of commercial retrofit square footage, high-rise construction permits above 24 meters, and industrial process equipment investment cycles. Segmentation dimensions modeled include product chemistry, combustibility rating tier, application envelope type, installation form factor, and end-user procurement authority. CAGRs were derived from elasticity-adjusted construction forecasts and regulatory mandate implementation schedules. Forecast inputs incorporated F-Gas Regulation compliance cost trajectories and aerogel manufacturing scale-up curves.
Regulatory enforcement variance, raw material price spikes, and construction cycle downturns are the dominant revision risks to baseline projections. Forecasts reflect assumptions regarding GB 8624 A-grade mandate consistency, EU Green Deal thermal-efficiency timeline adherence, and mineral wool respiratory hazard classification stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
Africa Fire Suppression Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
US Fire Alarm and Detection Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Fire Door Market
Fire Safety & Protection
Fire Alarm and Detection System Market