
 Fire Alarm and Detection System Market | 2026-2036
Fire Alarm and Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Alarm and Detection System Market Intelligence
Modular detector-platform bundling is expanding buyer choice across the fire alarm and detection system landscape. Honeywell International Inc. leverages its building-automation ecosystem to bundle detection with HVAC and access control. Siemens AG anchors European specification channels through EN 54-certified addressable platforms. Hochiki Corporation specializes in photoelectric sensor miniaturization for constrained retrofit environments.
Fire alarm and detection systems comprise sensor arrays, control panels, notification appliances, and communication interfaces engineered to detect smoke, heat, or combustion byproducts and initiate occupant warning and suppression activation. Photoelectric smoke detectors now dominate new specifications due to superior smoldering-fire response and reduced nuisance-alarm rates versus ionization predecessors. Addressable systems command premium positioning through individual device identification and diagnostic granularity, while wireless segments capture retrofit share where conduit installation proves cost-prohibitive. Multi-sensor detectors represent the fastest-expanding technology category by fusing optical, thermal, and carbon-monoxide sensing in single housings.
NFPA 72 in the United States, EN 54 across European Union member states, and local fire-prevention bureau standards in China collectively mandate detection coverage, response thresholds, and system survivability. These frameworks create replacement cycles for non-compliant legacy infrastructure and bar uncertified products from public-sector procurement. Stakeholders must monitor evolving smart-building integration standards and cyber-resilience requirements as connected fire systems become default specifications in commercial construction.
Market Dynamics
Addressable system architecture is displacing conventional hardwired panels across commercial construction, compressing installation labor and enabling granular diagnostics that legacy infrastructure cannot match. This technological inflection is restructuring procurement specifications and maintenance contracts simultaneously.
Growth Catalysts
- NFPA 72 compliance mandates:US facility managers face replacement deadlines for non-compliant conventional systems in high-rise structures, accelerating panel upgrade cycles.
- Photoelectric sensor miniaturization:Shrinking optical chamber dimensions enables retrofit deployment in heritage buildings with constrained ceiling cavities and aesthetic preservation requirements.
- China municipal fire codes:Networked detection mandates for buildings exceeding 24 meters are driving procurement volumes in tier-one and tier-two urban construction markets.
Market Restraints
- Semiconductor input volatility:Addressable system controllers depend on specialized analog-to-digital converters with concentrated foundry supply in East Asian manufacturing clusters.
- Copper and rare-earth magnet costs:Notification appliance manufacturing faces raw material price instability affecting horn-strobe assembly economics.
- Ionization detector phase-out:Regulatory bans on radioactive americium-241 sources are stranding inventory and forcing accelerated R&D redirection for legacy product lines.
Strategic Opportunities
- India smart-city infrastructure:Urban redevelopment projects in Mumbai and Delhi present first-mover positioning for wireless mesh detection networks in informal settlement upgrading.
- Multi-sensor convergence:Fusing optical, thermal, and carbon-monoxide sensing in single housings creates premium pricing tiers for healthcare and data center verticals.
- Cloud-based monitoring services:Remote diagnostic platforms enable recurring revenue streams and displace traditional inspection-dependent maintenance relationships.
Industry Challenges
- EN 54 certification timelines:European market entry requires extended third-party testing protocols that delay product launches by 8-14 months.
- Cybersecurity integration complexity:Connected fire systems must satisfy IEC 62443 industrial security standards while maintaining legacy backward compatibility.
- Addressable protocol fragmentation:Proprietary communication buses from incumbent manufacturers create interoperability barriers for multi-brand system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Alarm and Detection System Market |
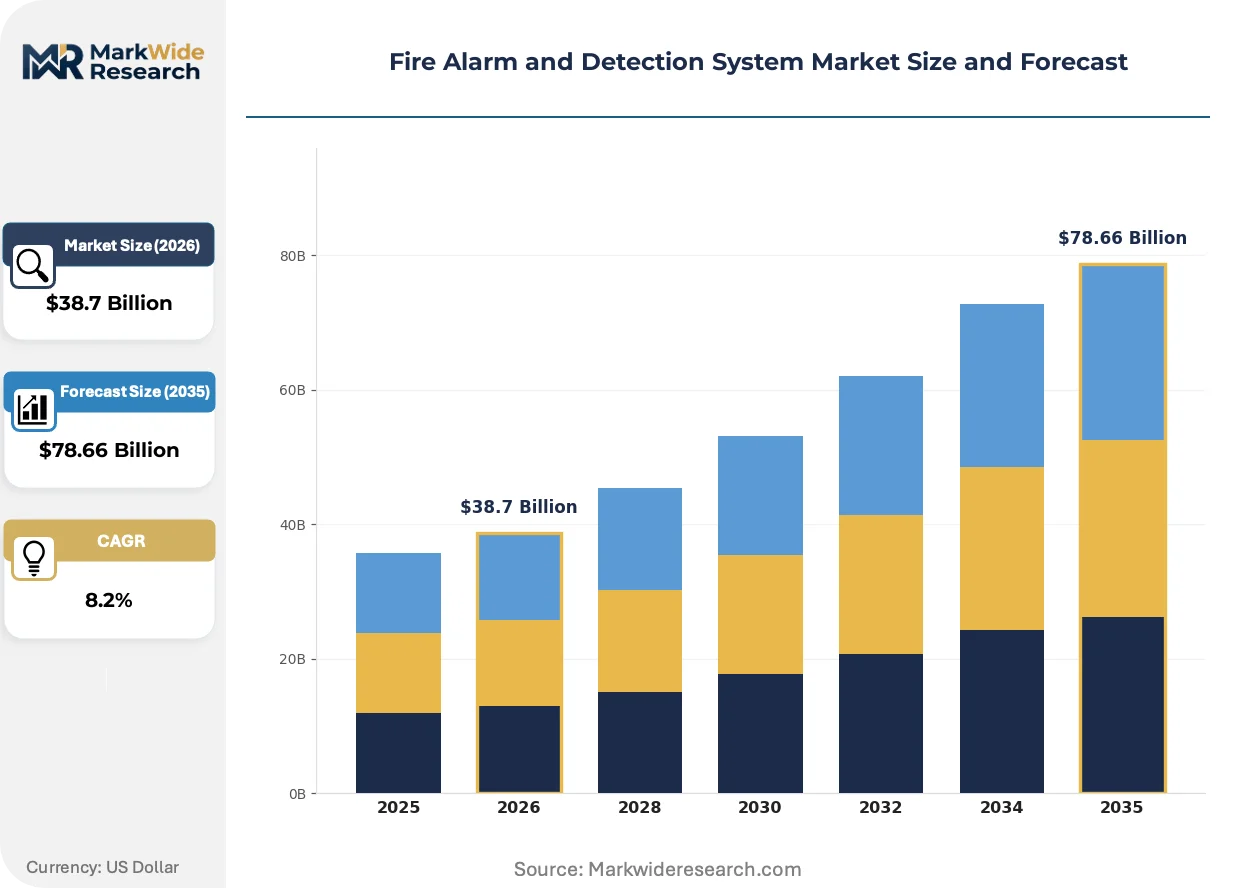
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $78.66 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Systems, Addressable Systems, Wireless Systems, Hybrid Systems Technology: Ionization Smoke Detectors, Photoelectric Smoke Detectors, Heat Detectors, Multi-Sensor Detectors End User: Residential, Commercial, Industrial, Institutional Installation Type: New Installations, Retrofitting, Expansion, Upgrade |
| Companies Covered | Robert Bosch GmbH, Hochiki Corporation, Honeywell International Inc., Apollo Fire Detectors Ltd., Gentex Corporation, Johnson Controls International plc, Halma plc, Schneider Electric, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Alarm and Detection System Market Strategic Shifts & Innovations
Wireless mesh networking is dissolving the infrastructure cost barrier that previously constrained detection system expansion into retrofit environments. This connectivity shift is reshaping competitive positioning around installation speed rather than hardware specification alone.
Photoelectric smoke detection is overtaking ionization technology in new commercial specifications due to superior smoldering-fire response and reduced nuisance-alarm rates. Hotel chains and senior living operators are specifying optical-only platforms to minimize evacuation disruption and liability exposure. The transition is compressing demand for legacy ionization inventory and redirecting manufacturing capacity toward refined optical chamber designs.
EN 54-23 visual alarm device standards across European Union member states are mandating minimum light output and flash rates for notification appliances. Manufacturers must redesign strobe optics and driver circuits to achieve certification, raising production costs but creating specification barriers for uncertified imports. German and French public-sector procurement channels now require documented EN 54-23 compliance for contract eligibility.
Facility managers are unbundling inspection and maintenance contracts from initial equipment procurement, treating fire system upkeep as a distinct spend category with separate vendor evaluation. This purchasing pattern is disrupting traditional manufacturer-captive service models and opening entry points for specialized third-party maintenance providers. The shift is most pronounced in UK commercial real estate, where property management companies consolidate multi-site portfolios under independent service contracts.
Fire Alarm and Detection System Market Segmentation
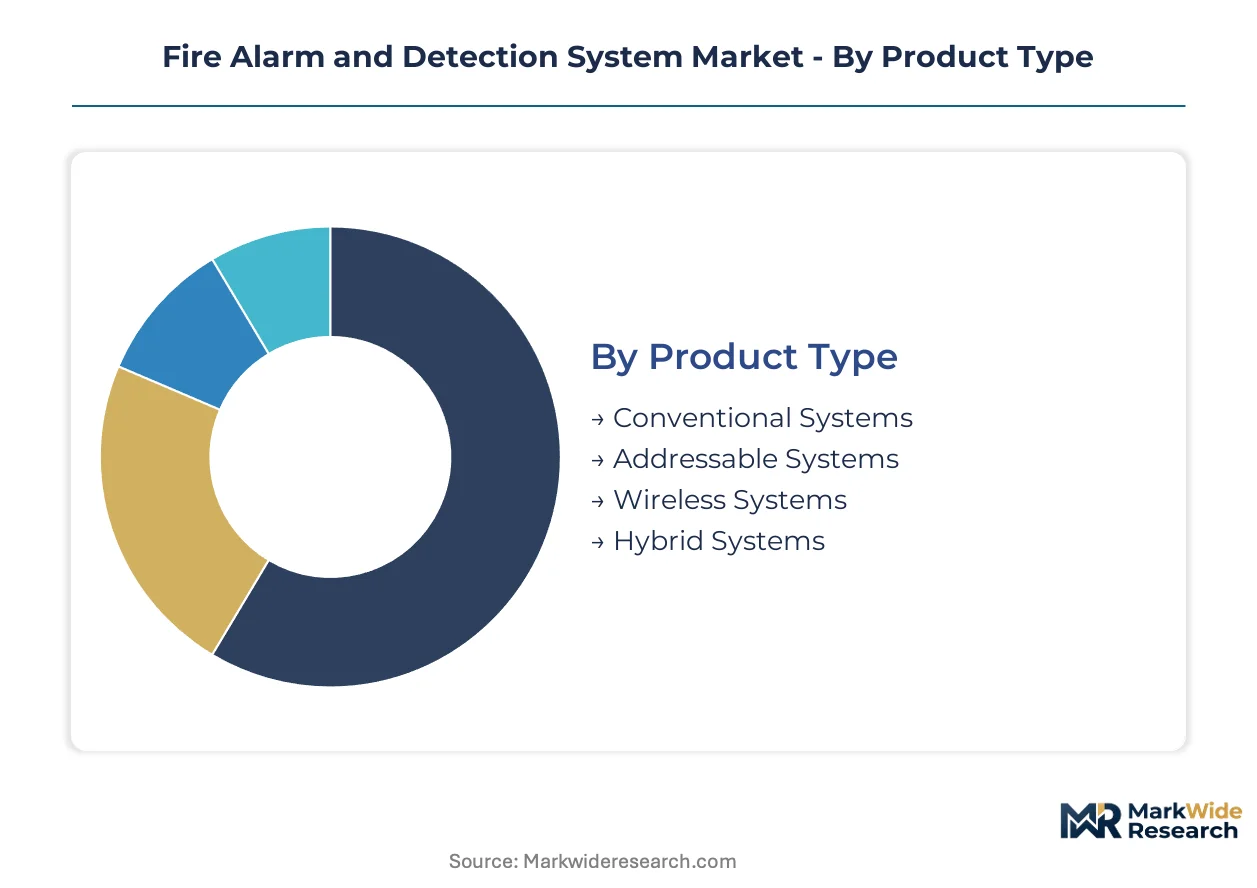
Segmentation reveals how procurement specifications diverge across building types and regulatory environments. Understanding these divides clarifies where technology premiums command pricing power versus where commodity competition dominates.
Product Type:
Addressable systems capture premium positioning through individual device diagnostics, while conventional systems retain volume share in cost-sensitive smaller buildings.
- Conventional Systems:Hardwired zone-based architecture groups multiple detectors into single notification circuits. Demand concentrates in India and Southeast Asia where municipal codes in tier-two cities still permit non-addressable installations in structures below 15 meters.
- Addressable Systems:Digital communication protocols enable individual device identification and fault isolation at the control panel. Commercial high-rise construction in China and replacement mandates under NFPA 72 in the United States are accelerating procurement for this architecture.
- Wireless Systems:Radio-frequency mesh networks eliminate conduit installation in heritage building retrofits.
- Hybrid Systems:Combines wired backbone with wireless extensions for phased facility upgrades.
Today's leader: Addressable Systems. Tomorrow's challenger: Wireless Systems.
Technology:
Photoelectric platforms dominate new specifications as ionization technology faces regulatory phase-out across multiple jurisdictions.
- Photoelectric Smoke Detectors:Optical chamber designs detect smoldering fires through light-scatter measurement with reduced nuisance-alarm rates versus ionization predecessors. Hotel operators in France and senior living chains in Germany are specifying optical-only platforms to minimize evacuation liability.
- Multi-Sensor Detectors:Fused optical, thermal, and carbon-monoxide sensing in single housings. Healthcare facilities in Japan and data centers in Singapore are driving specification for this category due to false-alarm immunity requirements.
- Ionization Smoke Detectors:Americium-241 based detection faces regulatory bans in EU member states and several US jurisdictions.
- Heat Detectors:Fixed-temperature and rate-of-rise variants serve kitchen and industrial environments where smoke detection triggers excessive false alarms.
Photoelectric Smoke Detectors hold installed base dominance. Multi-Sensor Detectors are climbing the fastest.
End User:
Commercial verticals absorb technology premiums while residential procurement remains price-elastic and specification-light.
- Commercial:Office towers, retail complexes, and hospitality properties mandate addressable architectures with central monitoring integration. China's 24-meter building height threshold for networked detection is concentrating procurement in Shanghai and Shenzhen commercial construction.
- Institutional:Hospitals, universities, and government facilities require redundant signaling paths and survivable system architecture. EN 54 compliance mandates across Germany, France, and Italy structure procurement specifications for this segment.
- Industrial:Manufacturing plants and warehousing operations prioritize heat and flame detection over smoke sensing in high-dust environments.
- Residential:Single-family and multi-family dwellings drive volume through standalone battery-powered devices with minimal integration requirements.
Commercial commands margin concentration. Institutional is gaining specification complexity fastest.
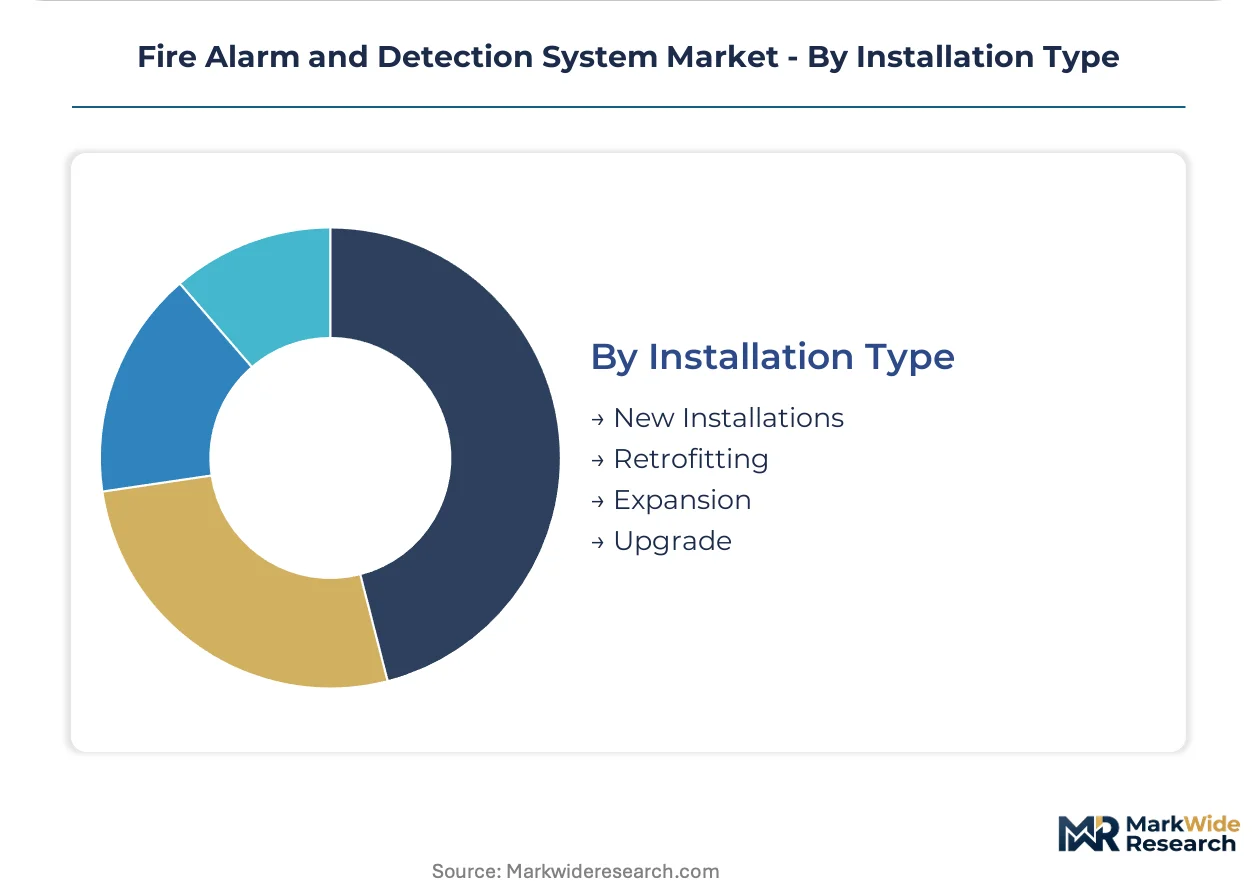
Installation Type:
New construction specifies integrated systems while retrofitting demands wireless and surface-mount solutions that minimize structural disruption.
- New Installations:Greenfield construction embeds detection infrastructure during framing and MEP rough-in. Addressable system deployment in China's tier-one urban construction markets exemplifies this pattern.
- Retrofitting:Wireless mesh and surface-mount addressable devices penetrate heritage buildings where conduit installation is prohibited. UK commercial real estate and Parisian Haussmann-era structures illustrate this application.
- Expansion:Modular panel capacity upgrades accommodate building additions without full system replacement.
- Upgrade:Legacy conventional-to-addressable conversions driven by NFPA 72 compliance deadlines in US high-rise structures.
New Installations anchor revenue scale. Retrofitting is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fire detection technology first achieved industrial scale in the United States during the 1970s with the commercialization of ionization sensors, establishing regulatory frameworks that subsequently diffused to European and Asian markets.
United States
NFPA 72 compliance deadlines for high-rise structures are accelerating panel replacement cycles in Chicago and New York commercial towers. OSHA workplace safety inspections now incorporate fire system survivability assessments in manufacturing facilities. Dallas-Fort Worth metroplex construction is absorbing addressable system volumes for new office development.
Germany
EN 54-23 visual alarm device standards are mandating minimum light output specifications for strobe optics in Frankfurt and Munich commercial properties. The country's federal building code requires redundant signaling paths in healthcare and institutional facilities. Stuttgart industrial corridor demand concentrates on heat detection systems for high-dust manufacturing environments.
China
Municipal fire codes mandating networked detection in buildings exceeding 24 meters are concentrating procurement in Shanghai and Shenzhen commercial construction. The Ministry of Emergency Management enforces GB standards compliance for imported detection equipment. Beijing-Tianjin-Hebei urban agglomeration is deploying wireless mesh systems in heritage district retrofits.
Japan
METI building energy efficiency guidelines are driving integration of fire detection with building automation systems in Tokyo commercial towers. JIS standards certification requirements structure procurement specifications for domestic and imported equipment. Osaka-Kobe industrial zone demand prioritizes multi-sensor detectors for semiconductor fabrication facilities.
India
BIS certification mandates for imported fire safety equipment are creating entry barriers for uncertified addressable systems in Mumbai commercial construction. The country's national fire service directorate is updating model building codes for smart-city infrastructure projects. Delhi-NCR urban redevelopment is absorbing wireless detection networks in informal settlement upgrading.
Fire Alarm and Detection System Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and building-automation integration capability. The vendor base stratifies into three tiers: diversified industrial conglomerates with captive building-technology ecosystems, specialized fire-safety pure-plays with concentrated R&D investments, and regional assemblers serving price-elastic procurement channels. Dominant competitive moves include technology licensing partnerships for addressable protocol compatibility and backward integration into sensor component manufacturing.
Within the diversified conglomerate tier, Honeywell International Inc. and Siemens AG exemplify positioning through building-automation ecosystem integration. Hochiki Corporation occupies a specialist position focused on optical sensor refinement. Robert Bosch GmbH and Johnson Controls International plc anchor the premium-tier vector through multi-technology portfolios spanning detection, suppression, and building management systems. Apollo Fire Detectors Ltd. represents the pure-play specialist archetype with concentrated European specification channel presence.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Hochiki Corporation |
| Honeywell International Inc. |
| Apollo Fire Detectors Ltd. |
| Gentex Corporation |
| Johnson Controls International plc |
| Halma plc |
| Schneider Electric |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
EN 54 certification depth splits the vendor base into premium specification channels and commodity procurement tiers, with certified addressable platforms commanding hardware premiums and multi-year service bundling while uncertified imports compete on unit economics in cost-sensitive developing markets. This bifurcation concentrates margin capture among vertically integrated building-automation conglomerates and forces regional assemblers toward price-driven volume plays.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors transaction economics, with EN 54-23 visual alarm certification and NFPA 72 compliance status serving as primary price differentiation drivers. Price erosion runs through conventional panel segments as ionization detector phase-outs strand legacy inventory and compress replacement-cycle margins. Commercial high-rise procurement teams exhibit lowest price sensitivity due to insurance and liability exposure, while residential standalone device buyers drive commodity competition.
Supply Chain Analysis
Refurbishment flows for addressable control panels and detector modules are emerging as secondary supply channels, particularly in European markets with extended producer responsibility frameworks. Manufacturing concentrates in China, Germany, and Japan, with specialized analog-to-digital converter fabrication anchored in Taiwanese foundries. Copper and rare-earth magnet dependencies create raw material cost volatility for notification appliance assembly. Single-source vulnerability in semiconductor inputs threatens addressable system controller availability. Distribution runs through specification-influenced channels including fire safety engineering consultants and building-automation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specification premiums are hardening across the analysis window as municipal code enforcement tightens and insurance underwriters reward compliant system architecture. This late-cycle quality story rewards vendors with certification depth and penalizes commodity positioning.
For Market Incumbents: Anticipate wireless protocol fragmentation disrupting proprietary addressable bus architectures by investing in open-standard compatibility layers and backward integration into photoelectric sensor component manufacturing. Defend specification channel relationships through EN 54-23 pre-certification of next-generation visual alarm devices before competitors complete testing protocols. For New Entrants and Emerging Players: Heritage building retrofit contractors represent an underserved buyer archetype with unconsolidated procurement and limited incumbent loyalty. Wireless mesh detection networks in UK commercial real estate and Parisian Haussmann-era structures offer the most penetrable application entry point. Pursue direct specification relationships with fire safety engineering consultants rather than competing through distributor price lists. For Investors and Strategic Acquirers: Consolidation pressure builds where EN 54 certification timelines and R&D intensity outpace mid-cap balance sheet capacity. Five-to-ten year viability favors specialists with captive sensor technology and cloud-based monitoring service revenue streams. Monitor municipal fire code adoption trajectories in India and Southeast Asian tier-two cities for inflection signals on wireless system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EN 54-23 Pre-Certification Investment | Accelerates European market entry before 8-14 month testing delays constrain competitors. |
| Wireless Mesh Protocol Development | Captures heritage retrofit share where conduit installation proves cost-prohibitive. |
| Cloud-Based Monitoring Service Launch | Converts transactional hardware sales into recurring revenue streams. |
| Photoelectric Sensor Backward Integration | Reduces semiconductor input vulnerability and protects margin structure. |
| Smart-Building Automation Partnership | Positions detection systems within integrated HVAC and access control ecosystems. |
Research Approach
Direct dialogue with fire safety engineering consultants, facility management directors, municipal fire code enforcement officers, and building-automation procurement leads grounded qualitative findings in operational reality. Secondary validation drew from NFPA 72 compliance documentation, EN 54-23 certification registries, Chinese GB standards filings, and customs trade data on detector component imports. Bottom-up installation volume estimates and top-down construction spending allocations were triangulated to cross-validate market sizing.
Bottom-up modeling segmented procurement by building height thresholds, regulatory compliance status, and technology architecture preference across the projection horizon. Segmentation dimensions included product type, detection technology, end-user vertical, and installation context. CAGRs were derived from regression analysis against construction permit data and replacement-cycle assumptions. Industry-specific inputs incorporated semiconductor lead time volatility and copper price index trajectories.
Inputs from certification body testing schedules and municipal code adoption timelines were available through the study window; gaps in informal settlement retrofit penetration data introduce uncertainty bands around India wireless system forecasts. Practitioners should monitor EN 54-23 enforcement consistency across EU member states and NFPA 72 high-rise compliance deadline adherence for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Europe Fire-Resistant Glass Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Fire and Rescue Helmets Market
Fire Safety & Protection
North America Fire Extinguisher Market
Fire Safety & Protection
GCC Firefighting Foam Market