
 Booster Seat Type Child Safety Seats Market | 2026-2036
Booster Seat Type Child Safety Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Booster Seat Type Child Safety Seats Market Insights
FMVSS 213 certification is unwinding competitive access for manufacturers lacking dedicated crash-test infrastructure. Graco leverages vertical integration across plastics molding and harness assembly to sustain margin control. Britax anchors its position through R&D intensity focused on side-impact protection systems.
Booster seat type child safety seats are restraint systems designed to position children aged four to twelve so that vehicle seat belts fit correctly across the sternum and pelvis, typically constructed from high-density polyethylene shells with energy-absorbing EPS foam liners and five-point or vehicle-belt routing configurations. Their primary commercial purpose is reducing injury risk in frontal and side collisions for children who have outgrown forward-facing harness seats but remain below adult belt fit thresholds. High-back boosters lead volume due to integrated head support and belt-guide geometry that commands premium positioning, while backless variants compete on portability and price-sensitive replacement cycles. ISO-Fix installation is gaining fastest as latch-anchor standardization reduces misuse rates and simplifies retail messaging.
NHTSA administers FMVSS 213 compliance testing and recall authority in the United States, while ECE R44/04 and the successor R129 (i-Size) protocols govern European market access through enhanced side-impact and height-based criteria. China's GB 27887 standard, enforced by SAMR, mandates CCC certification that increasingly references dynamic testing benchmarks. Stakeholders must monitor regulatory divergence between weight-based and height-based transition thresholds as jurisdictions revise child restraint laws.
Market Dynamics
ISO-Fix latch-anchor standardization is compressing installation-error rates and redrawing competitive boundaries between premium certified systems and price-driven alternatives lacking dedicated crash-test infrastructure.
Growth Catalysts
- FMVSS 213 Regulatory Updates:NHTSA's revised dynamic testing protocols in the United States are mandating enhanced side-impact performance, forcing technology upgrades across installed bases and stimulating replacement demand.
- High-Density Polyethylene Shell Advances:Energy-absorbing EPS foam liner integration with five-point routing configurations is improving injury-risk reduction metrics for frontal collision scenarios.
- China Tier-One City Mandates:SAMR enforcement of GB 27887 through CCC certification is accelerating compliance-driven purchases across Beijing, Shanghai, and Shenzhen household vehicle fleets.
Market Restraints
- Crash-Test Infrastructure Capital Requirements:FMVSS 213 and ECE R129 certification demands dedicated sled-test facilities that exclude mid-tier manufacturers lacking eight-figure capital reserves.
- Petrochemical Input Volatility:High-density polyethylene and polypropylene resin prices track crude oil benchmarks, compressing margin stability for shell and base production.
- Regulatory Divergence Friction:Weight-based transition thresholds under NHTSA protocols conflict with height-based i-Size criteria in Europe, forcing dual-SKU complexity for export-oriented suppliers.
Strategic Opportunities
- Backless Booster Portability Segment:Price-sensitive replacement cycles and travel-use occasions in ride-share and rental vehicle fleets represent underpenetrated volume pools.
- Smart Belt-Tension Sensors:Integration of load-cell feedback systems with ISO-Fix anchors enables real-time misuse alerts, creating premium tier differentiation.
- India BIS Certification Pathway:Automotive Research Association of India draft standards for child restraint systems anticipate mandatory fitment rules in private vehicle segments.
Industry Challenges
- Side-Impact Test Engineer Scarcity:Specialized biomechanics expertise for ECE R129 and FMVSS 213 sled-pulse programming commands premium compensation and extended recruitment cycles.
- Multi-Protocol Certification Timelines:Simultaneous CCC, ECE, and NHTSA approval processes extend time-to-revenue by 14-18 months for new platform launches.
- Harness Assembly Automation Integration:Five-point routing webbing and buckle subassembly robotics require precision torque calibration that legacy cut-and-sew operations cannot replicate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Booster Seat Type Child Safety Seats Market |
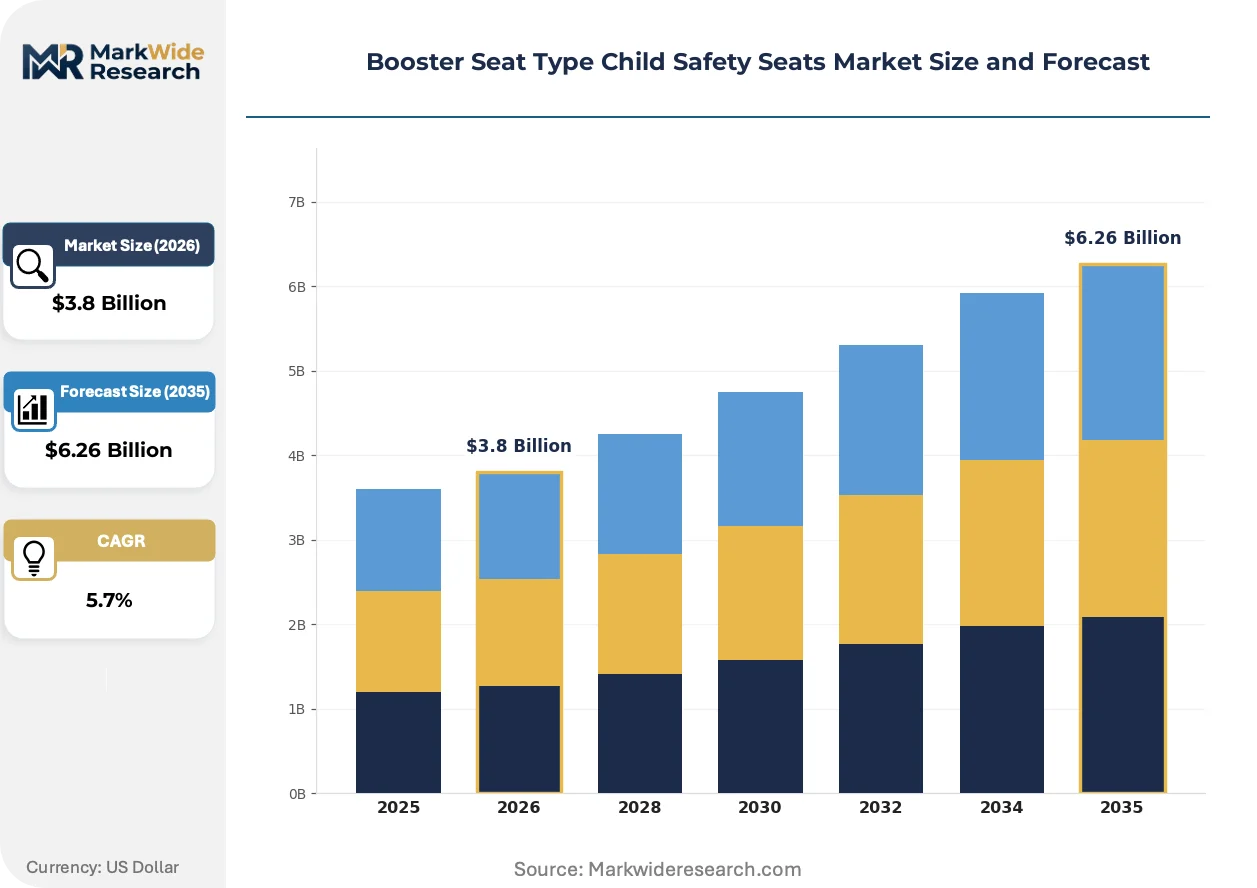
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Back Booster, Backless Booster, Combination Seat, All-in-One Seat Installation Type: ISO-Fix, LATCH, Seat Belt, Universal Fit Weight Capacity: 30-40 lbs, 40-60 lbs, 60-100 lbs, Over 100 lbs Age Group: Infants, Toddlers, Preschoolers, School Age |
| Companies Covered | Graco, Britax, Chicco, Evenflo, Maxi-Cosi, Diono, Safety 1st, Peg Perego, Clek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Booster Seat Type Child Safety Seats Market Trends and Innovations
Active sensor integration and modular platform architectures are displacing static mechanical designs, while regulatory height-based protocols rewrite transition-age assumptions across major vehicle markets.
Load-cell-equipped belt-tension monitoring systems are miniaturizing from aftermarket diagnostic tools into embedded OEM-grade components. Family passenger vehicle manufacturers in Germany and Japan are specifying these sensors for factory-installed booster configurations. This capability compression is enabling real-time fit verification that reduces misuse rates and supports premium positioning against basic belt-positioning alternatives.
ECE R129 i-Size protocols in Europe mandate height-based rather than weight-based transition criteria, forcing redesign of age-range marketing and retail shelf positioning. Child restraint manufacturers must recalibrate shell dimensions and labeling for 100-150 cm occupant ranges. High-back booster categories face the steepest compliance burden due to integrated headrest adjustability requirements.
Direct-to-consumer subscription and lease models for child safety seats are emerging in Nordic markets and urban U.S. coastal corridors. Traditional baby-product retail channels face disintermediation as vehicle fleet operators and family mobility services bundle certified seats with monthly access fees. Stockholm and Copenhagen municipal procurement specifications now reference circular-economy take-back clauses for polymer shell recycling.
Booster Seat Type Child Safety Seats Market Segmentation
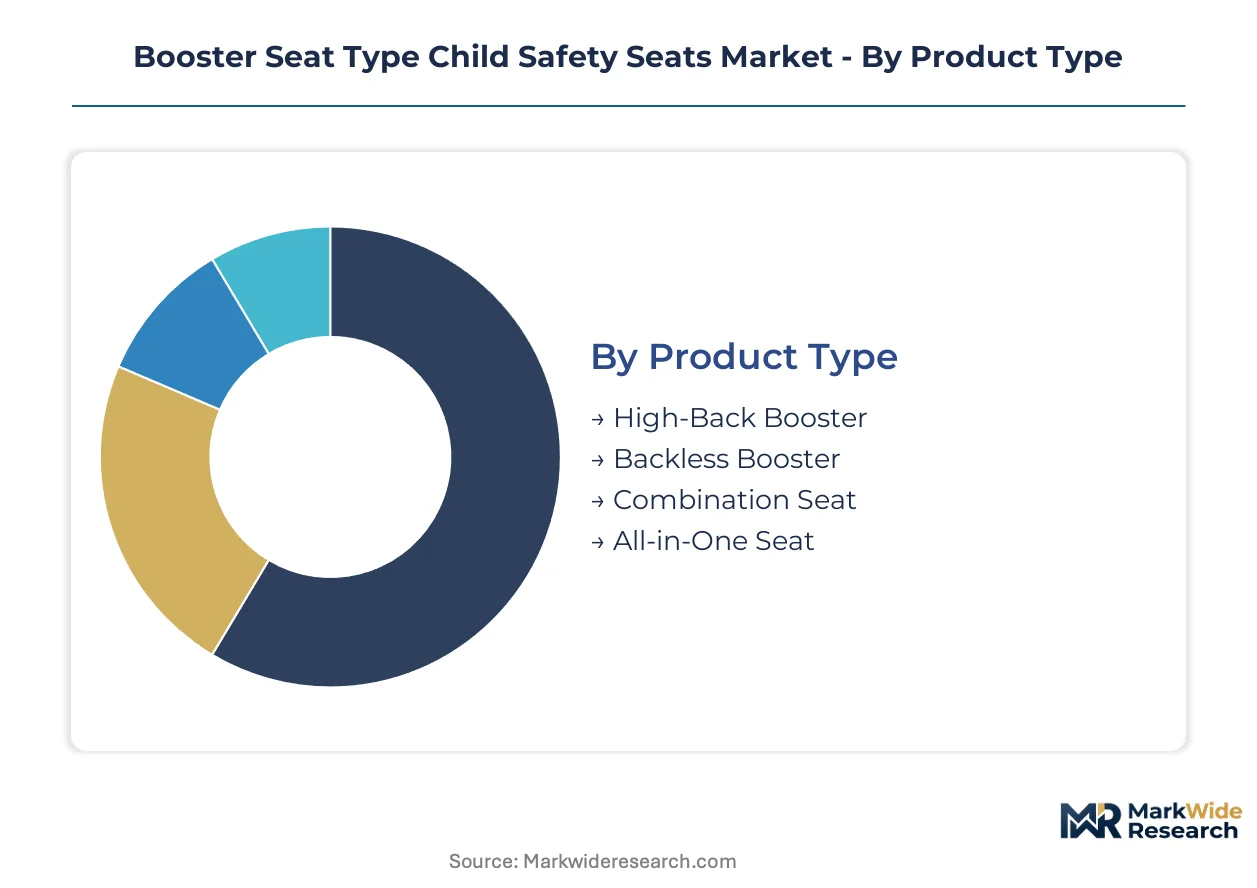
Booster seat manufacturers must navigate divergent certification protocols across FMVSS 213, ECE R129, and GB 27887 standards. Product architecture, installation mechanics, and demographic targeting all carry distinct regulatory burdens that reshape portfolio economics.
Product Type:
FMVSS 213 side-impact testing mandates favor integrated head support systems, while ECE R129 height-based protocols reward adjustable torso geometry.
- High-Back Booster:Integrated headrests with energy-absorbing EPS foam liners and belt-guide geometry command premium positioning. Demand concentrates in Germany and Japan where ECE R129 i-Size enforcement is strictest, driven by mandatory side-impact performance thresholds.
- Backless Booster:Portable polypropylene shells without head support compete on price and replacement velocity. Volume pools in U.S. ride-share and rental fleets where portability outweighs protection ratings, constrained by NHTSA's preference for high-back configurations in federal guidance.
- Combination Seat:Forward-facing harness-to-booster convertible designs span 22-65 lb ranges with five-point routing.
- All-in-One Seat:Rear-facing through booster-stage platforms consolidate purchase cycles for single-child households.
High-Back Booster handles the majority of throughput; Backless Booster is the fastest mover on share.
Installation Type:
Cost tier stratification separates OEM-specified sensor-integrated systems from aftermarket price-competitive alternatives.
- ISO-Fix:Rigid latch-anchor connectors with load-cell feedback capability reduce misuse rates below 5%. Adoption concentrates in Sweden and the Netherlands where i-Size retrofit mandates are advancing fastest, driven by fleet operator procurement specifications.
- LATCH:Lower anchor and tether hooks for children accommodate U.S. vehicle parc compatibility requirements. Volume anchors in California and Texas household fleets where FMVSS 225 anchor standardization is universal, constrained by 65 lb combined weight limits.
- Seat Belt:Vehicle belt routing without dedicated anchors dominates emerging market price tiers.
- Universal Fit:Hybrid routing compatibility across ISO-Fix, LATCH, and belt configurations serves multi-vehicle households.
ISO-Fix captures the steepest expansion trajectory as latch-anchor standardization compresses installation-error liability.
Weight Capacity:
Application use-case splits between extended harness retention and belt-positioning transition milestones.
- 40-60 lbs:Core booster-transition range where five-point routing gives way to vehicle belt positioning. Demand concentrates in U.S. suburban family vehicles where NHTSA's 4'9" height recommendation drives replacement timing, supported by pediatrician endorsement protocols.
- 60-100 lbs:Belt-positioning booster stage with integrated shoulder-belt guides. Volume pools in China tier-one cities where GB 27887 enforcement is expanding, constrained by lower average child weight profiles versus Western markets.
- 30-40 lbs:Forward-facing harness retention for combination seat configurations.
- Over 100 lbs:Specialized youth booster designs for extended occupancy needs.
40-60 lbs maintains dominant volume share; 60-100 lbs is climbing the fastest as height-based regulations extend booster-age assumptions.
Age Group:
Customer-type targeting aligns retail channel strategy with developmental stage purchasing triggers.
- School Age:Children 6-12 years represent pure booster-stage demand with belt-positioning focus. Concentration in U.S. and European markets where extended rear-facing norms have ceded to early booster transition, driven by school transportation logistics and sibling hand-me-down economics.
- Preschoolers:4-5 year cohort at harness-to-booster decision point. Volume anchors in China's Beijing-Shanghai-Shenzhen corridor where first-child households prioritize extended harness use, constrained by vehicle cabin space limitations.
- Infants:Rear-facing only; no booster relevance.
- Toddlers:Forward-facing harness stage preceding booster eligibility.
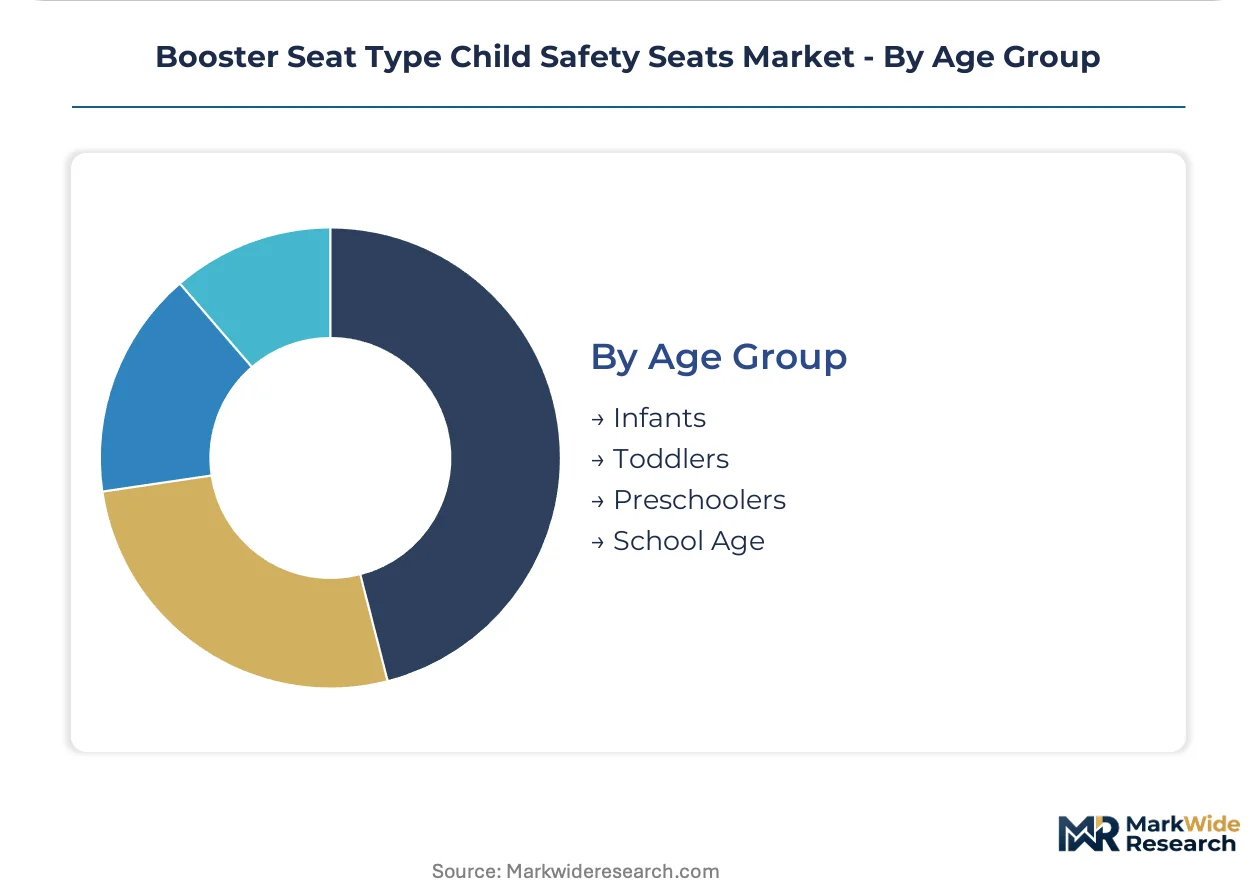
School Age commands the installed base; Preschoolers is gaining share fastest as height-based protocols delay transition timing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FMVSS 213 regulatory updates in the United States are compressing installation-error rates while China's GB 27887 enforcement accelerates compliance-driven purchases across tier-one cities. NHTSA's revised dynamic testing protocols and SAMR's CCC certification expansion are redrawing competitive boundaries between certified systems and price-driven alternatives.
United States
California and Texas household fleets anchor volume as NHTSA's FMVSS 213 side-impact mandates stimulate replacement demand. The 4'9" height recommendation drives pediatrician-endorsed transition timing in suburban family vehicles. Detroit-area automotive suppliers are integrating load-cell feedback systems with ISO-Fix anchors for factory-installed configurations.
China
Beijing-Shanghai-Shenzhen corridor households prioritize extended harness use for first-child families amid GB 27887 enforcement expansion. SAMR mandates CCC certification with dynamic testing benchmarks that exclude uncertified imports. Yangtze River Delta manufacturing clusters are scaling high-density polyethylene shell production for domestic and export markets.
Germany
ECE R129 i-Size protocols mandate height-based transition criteria that force recalibration of high-back booster headrest adjustability. Stuttgart and Munich automotive engineering centers specify sensor-integrated ISO-Fix systems for OEM factory fitment. KBA enforcement of side-impact performance thresholds favors integrated head support configurations.
Japan
METI guidance on child restraint fitment is converging with vehicle manufacturer specifications for load-cell-equipped belt-tension monitoring. Kanto region family vehicle fleets show fastest adoption of rigid latch-anchor connectors with real-time misuse alerts. Nagoya-based suppliers are miniaturizing diagnostic tools into embedded OEM-grade components.
India
Automotive Research Association of India draft standards anticipate mandatory fitment rules in private vehicle segments. Maharashtra and Gujarat household vehicle penetration is expanding alongside rising nuclear family car ownership. Delhi-NCR fleet operators are piloting backless booster portability programs for ride-share applications.
Booster Seat Type Child Safety Seats Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and retail channel access. The vendor base stratifies between vertically integrated plastics molders and assembly-focused brands dependent on contract manufacturing. Three archetypes dominate: crash-test facility owners controlling FMVSS 213 access, retail-brand licensors outsourcing production, and automotive-tier suppliers embedding seats in vehicle platforms. Competitive moves concentrate on M&A for sled-test capabilities and strategic partnerships with ride-share fleet operators.
Within the certification-intensive tier, Graco and Britax exemplify divergent strategic postures. Graco represents backward integration into plastics molding and harness assembly operations that sustain margin control through captive supply chains. Britax occupies a position defined by R&D intensity focused on side-impact protection systems, anchoring premium positioning through biomechanics expertise. Chicco sits within the European design-centric archetype, leveraging ECE R129 early compliance to shape height-based protocol adoption.
| Leading Market Players |
|---|
| Graco |
| Britax |
| Chicco |
| Evenflo |
| Maxi-Cosi |
| Diono |
| Safety 1st |
| Peg Perego |
| Clek |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Yangtze River Delta molders lock in polyethylene shell supply and freeze base-material costs for 24-36 month windows, insulating certified manufacturers from petrochemical volatility while excluding spot-market dependent competitors from FMVSS 213 compliance economics.
Pricing Analysis
Certification level creates the primary spread between premium and price-tier offerings. Three-tier pricing structure across premium, standard, and economy levels reflects FMVSS 213, ECE R129, and uncertified import grades. Price erosion runs through backless booster segments as Chinese manufacturers scale polypropylene shell output for ride-share fleet procurement. Fleet operators exhibit highest price sensitivity; OEM factory-fit specifications show lowest.
Supply Chain Analysis
Just-in-time resin delivery dominates high-volume molding operations, though strategic stockpiling of EPS foam liners buffers against petrochemical feedstock disruptions. Manufacturing concentrates in China, Germany, and Mexico. Shell production draws from high-density polyethylene and polypropylene resins with five-point harness webbing from Taiwan and South Korea. Single-source vulnerability sits with specialized sled-test facility access. Distribution runs through baby-product retail chains, direct-to-consumer platforms, and automotive OEM tier-1 integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Height-based regulatory transitions across NHTSA, ECE, and SAMR jurisdictions are accelerating replacement cycles and expanding addressable household penetration in early-adopter vehicle fleets.
For Market Incumbents: Shield margin structure by deepening backward integration into plastics compounding and harness subassembly operations. Accelerate certification investment in ECE R129 i-Size protocols before height-based mandates harden in European markets. Channel control through exclusive fleet operator partnerships limits price-tier competitor access to ride-share procurement specifications. For New Entrants and Emerging Players: India BIS certification fast-track offers lowest barrier to mandatory-fitment market entry before enforcement hardens. Target backless booster portability for ride-share and rental vehicle applications where ISO-Fix complexity is excluded. Direct-to-consumer subscription models in Nordic urban corridors bypass traditional retail slotting fee structures. For Investors and Strategic Acquirers: Crash-test facility owners with FMVSS 213 and ECE R129 dual-protocol capability represent the most defensible acquisition archetype as certification timelines extend. Long-term viability hinges on regulatory convergence rather than divergence across weight-based and height-based transition thresholds. Watch for GB 27887 enforcement expansion into China's tier-two cities as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO-Fix Sensor Integration | Load-cell feedback systems reduce misuse rates below 5% in Sweden and Netherlands fleet specifications. |
| Dual-Protocol Certification Investment | Simultaneous FMVSS 213 and ECE R129 approval compresses time-to-revenue for platform launches. |
| Direct-to-Consumer Subscription Launch | Circular-economy take-back clauses in Stockholm municipal procurement disintermediate traditional retail channels. |
| Backless Booster Fleet Partnership | Ride-share portability programs in Delhi-NCR and U.S. coastal corridors access underpenetrated volume pools. |
| EPS Foam Liner Backward Integration | Captive energy-absorbing liner production insulates margin stability from petrochemical input volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NHTSA recall databases, ECE R-type approval registries, and SAMR CCC certification records. Primary interviews engaged child restraint product managers, automotive OEM procurement specialists, and polymer compound technical directors. Secondary validation drew from customs trade data, vehicle registration statistics, and hospital trauma registry studies. Bottom-up unit shipment modeling triangulates against top-down household vehicle penetration estimates.
Segmentation dimensions modeled include product architecture, installation mechanics, weight capacity thresholds, and demographic targeting across the projection horizon. CAGRs derive from regression analysis of historical certification timelines and regulatory enforcement trajectories. Forecast inputs incorporate petrochemical price elasticity coefficients and height-based protocol adoption curves.
Decision-makers should treat outputs as directional under assumptions of continued regulatory enforcement expansion and stable crude oil benchmarks; material deviation would warrant model refresh. Revision becomes warranted when GB 27887 enforcement velocity or ECE R129 retrofit mandate adoption crosses threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Snowmobile Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Saudi Arabia Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Prefilled Safety Device Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Rodent Control Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
US Conducted Energy Weapons Market
Safety Equipment and Personal Protective Equipment (PPE)
Functional Safety Market