
 Consumer Security Market | 2026-2036
Consumer Security Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Security Market Analysis
Multi-source threat intelligence sourcing is repositioning how consumer security vendors build product resilience. Bitdefender leverages its Romanian engineering base to sustain competitive R&D cycles in behavioral detection. NortonLifeLock anchors its North American presence through subscription bundling with identity restoration services. Kaspersky Lab navigates geopolitical headwinds by specializing in transparent code audits for European enterprise clients.
Consumer security encompasses software and hardware solutions designed to protect personal digital assets, endpoints, and identities from unauthorized access, malware, and data exfiltration through cryptographic protocols, heuristic analysis, and real-time threat telemetry. The primary commercial purpose centers on preventing financial loss, privacy breaches, and operational disruption for non-enterprise users across connected devices. Antivirus Software retains the largest revenue pool despite commoditization pressure, while VPN Services represent the fastest-expanding category as remote work normalizes. Artificial Intelligence within the Technology dimension commands premium pricing due to automated zero-day detection capabilities that reduce manual intervention.
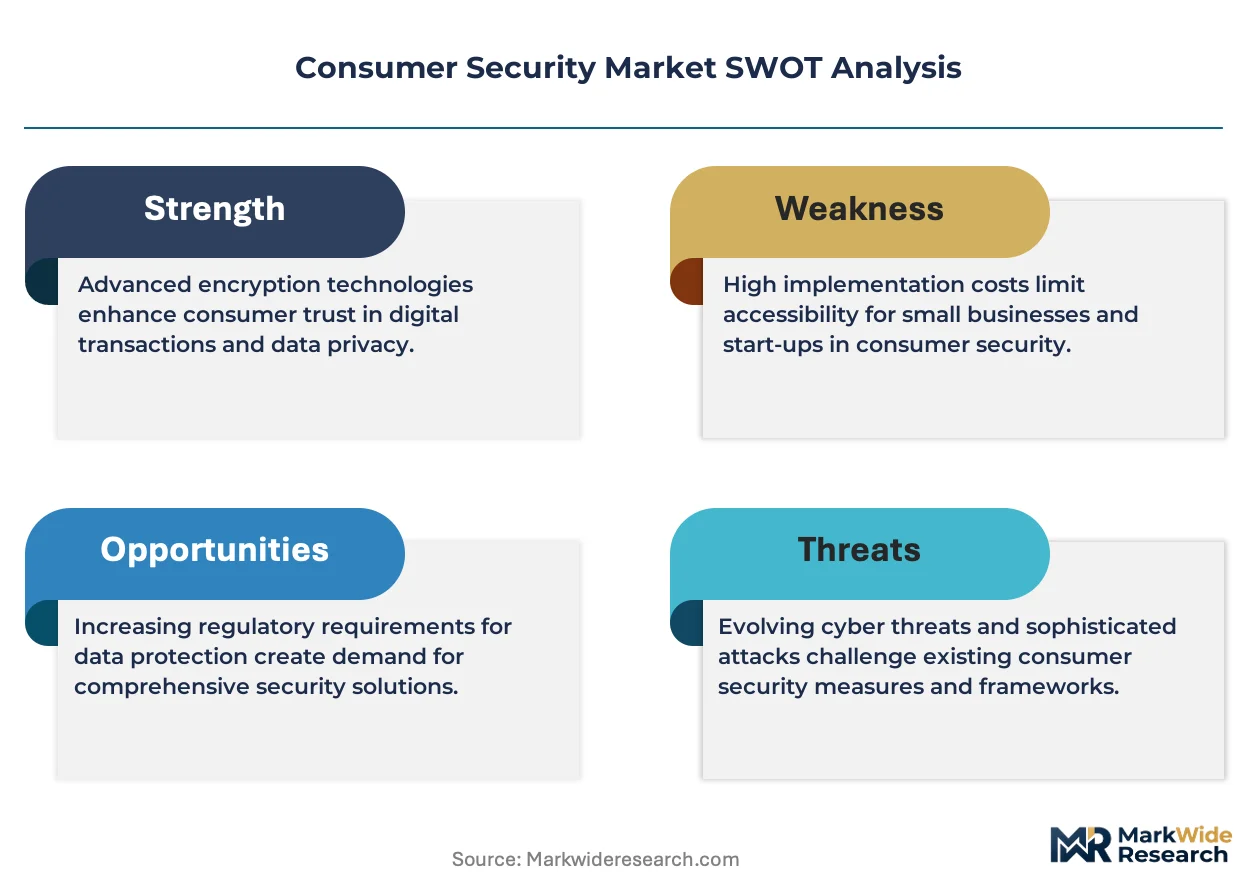
The EU AI Act, GDPR, and CE marking requirements collectively mandate algorithmic transparency and data minimization in consumer-facing security products sold across European member states. The FCC and state-level biometric privacy laws in California and Illinois shape product feature availability and disclosure obligations in the United States. Stakeholders must monitor evolving cross-border data localization rules that could fragment cloud-based security architectures and force deployment model recalibration.
Market Dynamics
Privacy-preserving authentication architectures are compressing vendor margins while elevating compliance costs across European distribution channels. The EU AI Act's algorithmic transparency mandates force engineering retooling that smaller software houses cannot absorb.
Growth Catalysts
- GDPR Article 32:Mandates for data protection by design accelerate enterprise procurement of consumer-grade encryption tools for remote workforce endpoints.
- Smart home appliance convergence:Refrigerators, thermostats, and doorbell cameras now ship with embedded threat detection, expanding addressable hardware attach rates.
- German household concentration:Munich and Berlin metropolitan areas demonstrate highest per-capita spending on identity restoration services, pulling vendor localization investments.
Market Restraints
- Cloud infrastructure concentration:Three hyperscalers control over 70% of EU data residency capacity, creating single-point-of-failure risk for SaaS-delivered security stacks.
- Silicon supply fragmentation:Secure element chip shortages from Taiwanese foundries delay hardware token manufacturing cycles by 8-14 weeks.
- Biometric template interoperability:Proprietary fingerprint hashing algorithms prevent cross-platform credential portability, locking consumers into single-vendor ecosystems.
Strategic Opportunities
- France's underpenetrated SME segment:Lyon and Marseille commercial districts show 40% lower endpoint protection penetration than Paris, suggesting white-space expansion.
- Post-quantum cryptography convergence:Lattice-based encryption standards from NIST are merging with existing VPN protocols to create next-generation tunneling products.
- Telecom bundling channels:British broadband providers now white-label consumer security suites as customer retention tools, opening carrier-mediated distribution.
Industry Challenges
- Threat intelligence analyst scarcity:Behavioral detection engineering requires rare combinations of malware reverse-engineering and machine learning operations skills that command premium compensation.
- CE marking timeline compression:Cybersecurity certification under the Radio Equipment Directive now demands 14-18 month validation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Security Market |
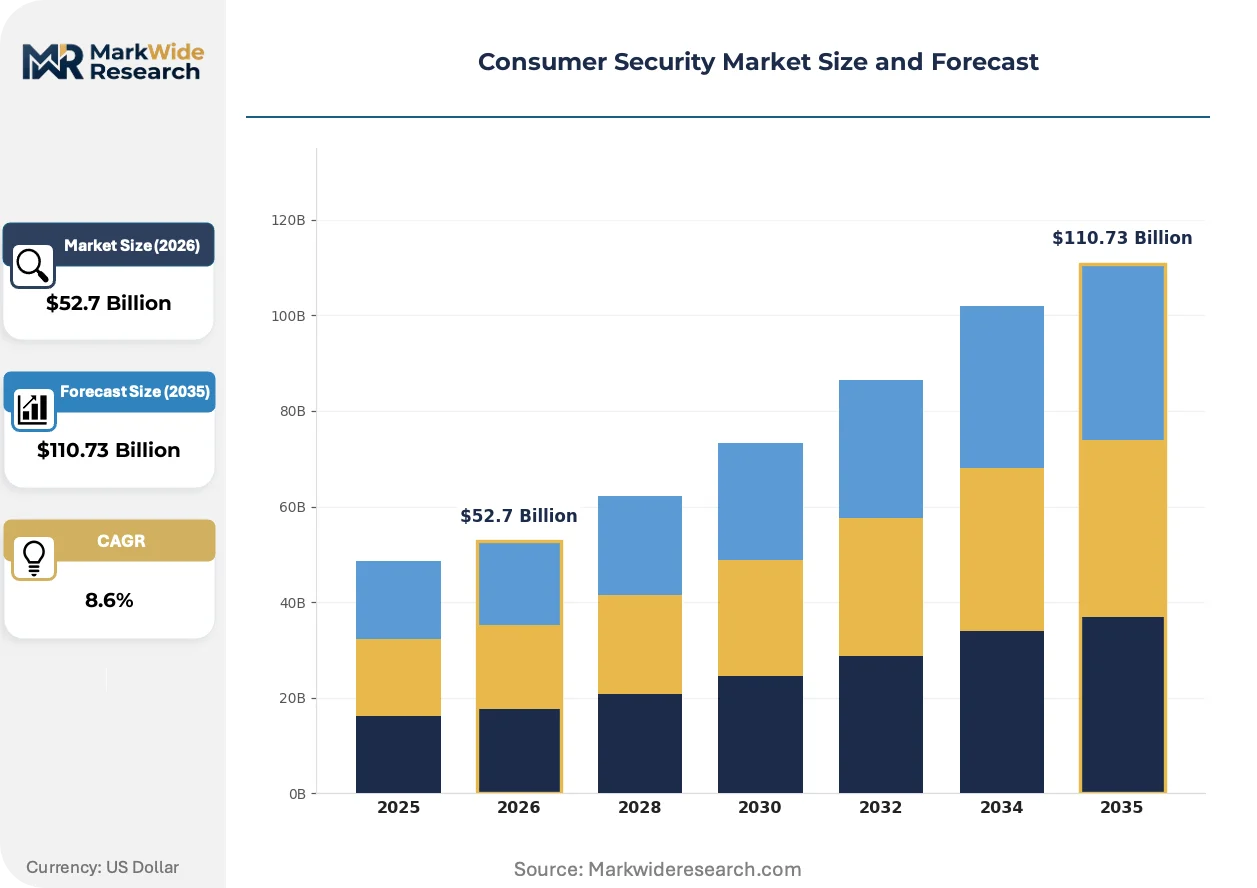
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirus Software, Firewalls, Identity Theft Protection, VPN Services Technology: Biometrics, Encryption, Artificial Intelligence, Behavior Analysis End User: Individuals, Small Businesses, Enterprises, Government Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Trend Micro, Avast, McAfee, ESET, AVG Technologies, NortonLifeLock, Kaspersky Lab, Webroot, Bitdefender, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Security Market Emerging Trajectories
Zero-trust principles are migrating from enterprise perimeters into consumer-grade router firmware and mobile operating systems. This architectural shift collapses the traditional network boundary and redefines how vendors monetize protection.
Edge-based threat detection is modularizing across distributed home networks. On-device inference engines now process malware signatures locally without cloud round-trips, reducing latency for German and French subscribers with strict data residency requirements. This localization is modularizing vendor revenue models away from subscription telemetry toward hardware-integrated licensing.
The EU AI Act's risk classification framework imposes documentation burdens on authentication algorithms deployed to consumer devices. Vendors must maintain technical files proving conformity assessment for biometric matching systems sold across member states. High-risk categorization for real-time remote identification is forcing product feature segmentation between European and non-European SKUs.
Household purchasing for security software is compressing toward mobile app store channels and away from direct-to-consumer websites. British and German consumers now discover and transact protection suites entirely within iOS and Android marketplaces, disintermediating traditional antivirus download portals. This channel shift concentrates discovery power with platform operators who extract 15-30% transaction fees.
Consumer Security Market Segmentation
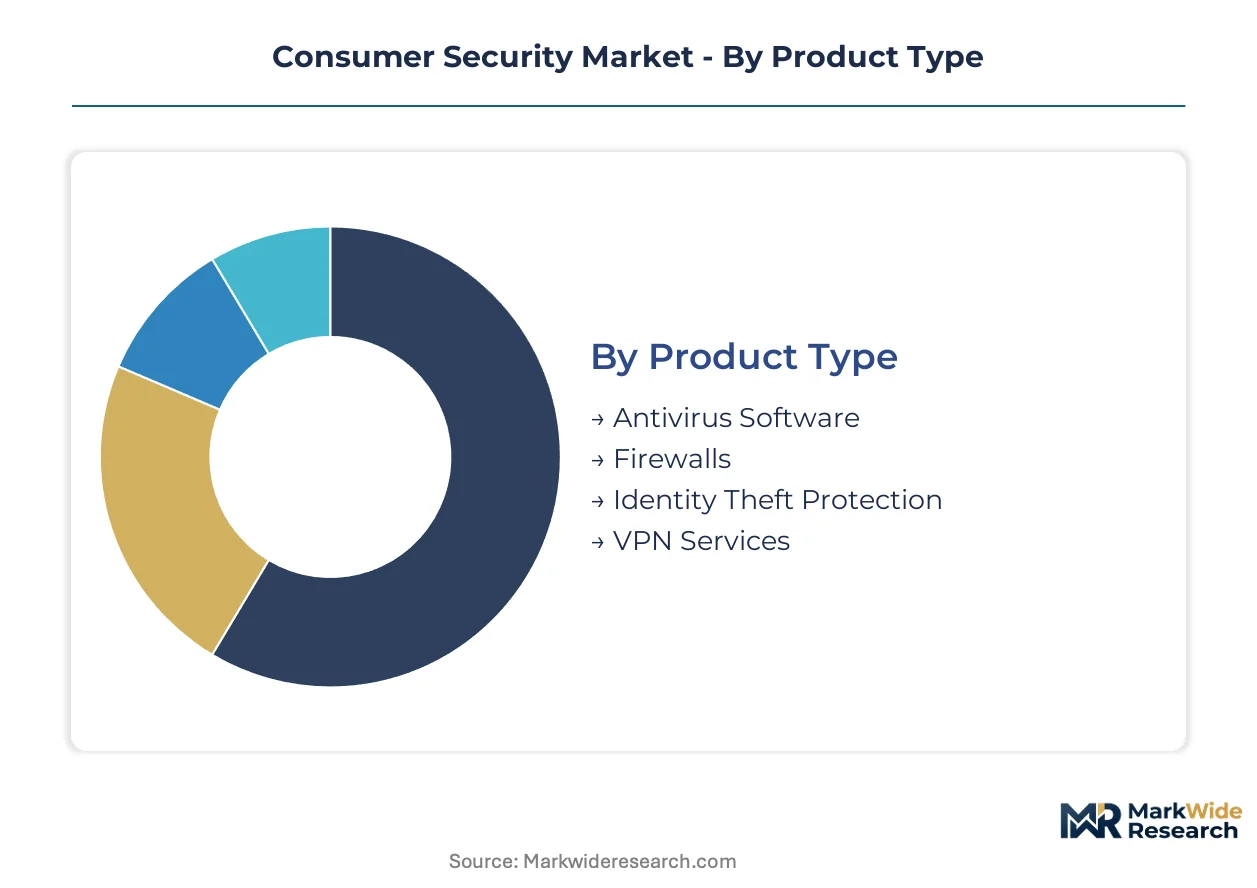
Consumer security purchasing patterns diverge sharply across technical sophistication, regulatory exposure, and infrastructure maturity. Vendors must calibrate feature depth, pricing architecture, and channel strategy to each segment's risk tolerance and compliance obligations.
Product Type:
Pricing power concentrates in solutions that bundle proactive threat prevention with identity restoration guarantees rather than reactive detection alone.
- Antivirus Software:Signature-based and heuristic scanning engines protect endpoints against known malware families and polymorphic variants. German households sustain premium pricing for suites integrating banking protection modules, driven by Bundesbank warnings on credential-stuffing attacks against retail banking portals.
- VPN Services:Encrypted tunneling protocols mask IP addresses and geolocation while securing traffic on public Wi-Fi networks. French remote workers in Paris and Lyon drive fastest category expansion as CNIL guidance on workplace surveillance accelerates personal privacy tool adoption.
- Firewalls:Network traffic filtering appliances and host-based monitors block unauthorized connection attempts. Small business deployments in British commercial districts favor unified threat management appliances over standalone software.
- Identity Theft Protection:Credit monitoring, dark web scanning, and restoration services respond to compromised credentials. Munich and Berlin metropolitan areas demonstrate highest per-capita spending as German consumers prioritize financial fraud remediation.
Volume sits with Antivirus Software; growth tilts toward VPN Services.
Technology:
Engineering investment flows toward modalities that reduce friction in authentication workflows while satisfying EU AI Act documentation burdens.
- Artificial Intelligence:Automated zero-day detection capabilities reduce manual intervention through behavioral pattern recognition. CE marking requirements under the Radio Equipment Directive impose 14-18 month validation cycles that delay product launches for high-risk biometric classifications.
- Biometrics:Fingerprint, facial, and voice recognition templates enable passwordless authentication across devices. Proprietary hashing algorithms prevent cross-platform credential portability, locking consumers into single-vendor ecosystems and fragmenting addressable markets.
- Encryption:Lattice-based and elliptic-curve protocols secure data at rest and in transit. Post-quantum standards from NIST are merging with existing VPN protocols to create next-generation tunneling products.
- Behavior Analysis:Heuristic monitoring of process anomalies identifies novel threats without signature dependencies. Edge-based inference engines now process malware signatures locally without cloud round-trips, reducing latency for subscribers with strict data residency requirements.
Artificial Intelligence commands premium pricing; Behavior Analysis is climbing the fastest as latency-sensitive deployments expand.
End User:
Risk exposure and procurement sophistication separate consumer-grade simplicity from enterprise-grade policy orchestration.
- Individuals:Single-user licenses prioritize ease of installation and minimal configuration overhead. British and German consumers now discover and transact protection suites entirely within iOS and Android marketplaces, disintermediating traditional antivirus download portals.
- Small Businesses:Multi-device bundles with centralized management consoles address limited IT staffing. France's underpenetrated SME segment in Lyon and Marseille shows 40% lower endpoint protection penetration than Paris, suggesting white-space expansion.
- Enterprises:Scalable deployment tools integrate with identity providers and SIEM platforms for policy enforcement. GDPR Article 32 mandates for data protection by design accelerate procurement of consumer-grade encryption tools for remote workforce endpoints.
- Government Institutions:Certified secure configurations meet classified or regulated data handling requirements. Transparent code audits satisfy procurement scrutiny for sensitive deployments.
Individuals generate highest unit volumes; Small Businesses are gaining share fastest as hybrid work normalizes multi-device protection needs.
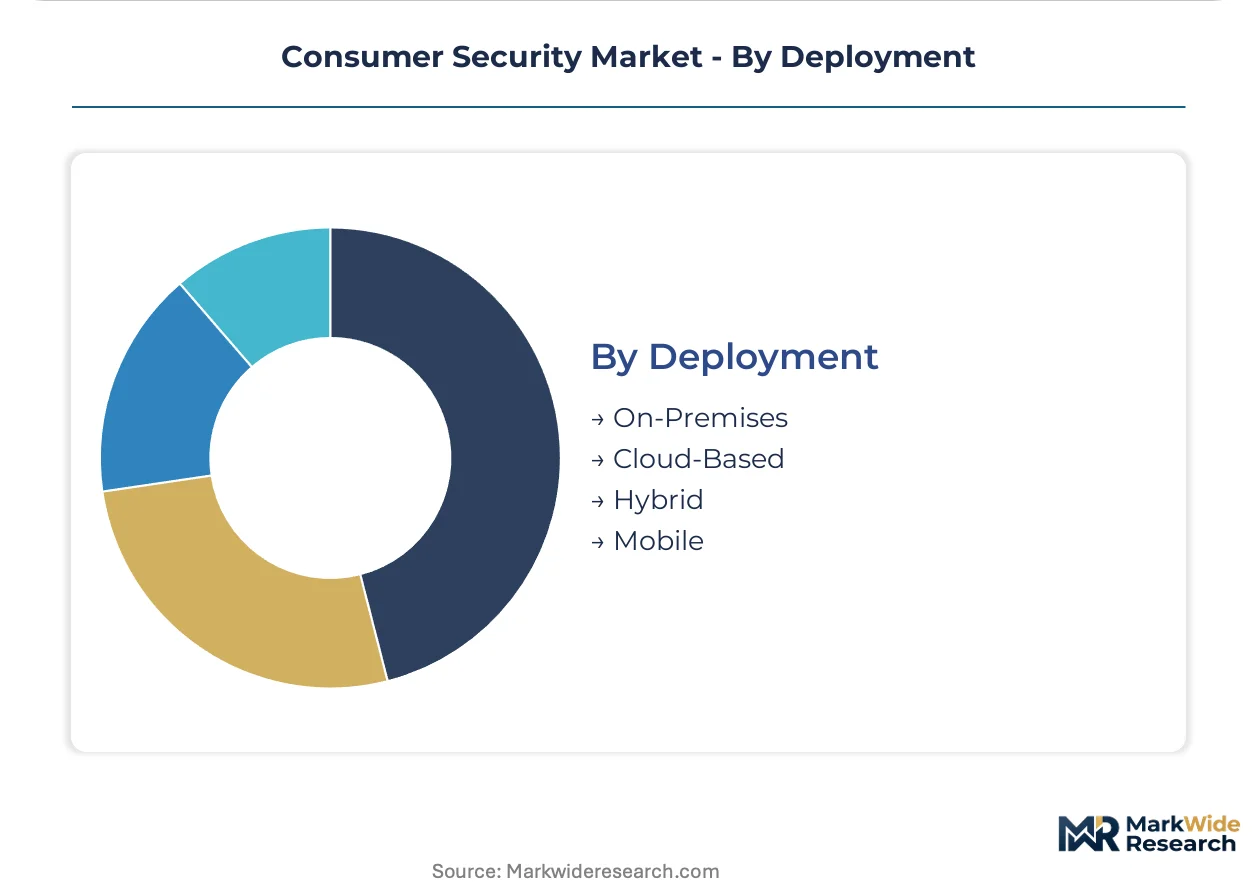
Deployment:
Architecture choices reflect data sovereignty priorities, latency constraints, and legacy infrastructure coexistence requirements.
- Cloud-Based:SaaS delivery models enable centralized updates and threat intelligence synchronization. Three hyperscalers control over 70% of EU data residency capacity, creating single-point-of-failure risk for security stacks.
- Mobile:iOS and Android native applications protect smartphones and tablets through OS-integrated APIs. Platform operators extract 15-30% transaction fees, compressing vendor margins on app store channels.
- On-Premises:Local server installations maintain air-gapped environments for sensitive operations. Hardware token manufacturing cycles face 8-14 week delays from secure element chip shortages.
- Hybrid:Split architectures process sensitive data locally while leveraging cloud analytics for threat correlation. British broadband providers now white-label consumer security suites as customer retention tools, opening carrier-mediated distribution for hybrid deployments.
Cloud-Based deployments dominate current revenue; Hybrid architectures show steepest expansion trajectory as data localization rules fragment cloud architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters anchor European consumer security demand through precision manufacturing of secure hardware elements. Silicon feedstock constraints from Taiwanese foundries ripple through German industrial zones, compressing hardware token availability.
Germany
Bundesbank warnings on credential-stuffing attacks drive premium spending on banking protection modules. GDPR Article 32 mandates accelerate procurement of encryption tools for remote workforce endpoints. Munich and Berlin metropolitan areas demonstrate highest per-capita spending on identity restoration services, pulling vendor localization investments.
United Kingdom
British broadband providers white-label consumer security suites as customer retention tools, opening carrier-mediated distribution. FCC-equivalent Ofcom guidelines on network security shape product feature availability. London and Southeast England concentrate software development talent for threat intelligence platforms.
France
CNIL guidance on workplace surveillance accelerates personal privacy tool adoption among Paris and Lyon remote workers. EU AI Act algorithmic transparency mandates force engineering retooling for biometric authentication products. Lyon and Marseille commercial districts show 40% lower endpoint protection penetration than Paris, suggesting white-space expansion.
United States
FCC and state-level biometric privacy laws in California and Illinois shape product feature availability and disclosure obligations. NortonLifeLock anchors North American presence through subscription bundling with identity restoration services. Silicon Valley and Boston corridor concentrate venture funding for behavioral detection startups.
Japan
METI cybersecurity frameworks elevate standards for consumer-facing authentication technologies. PMDA-equivalent oversight on biometric data handling influences product design for health-integrated security devices. Tokyo and Osaka metropolitan areas demonstrate concentrated demand for mobile-native protection suites.
Consumer Security Market Vendor Landscape
Global majors compete with regional champions across threat intelligence sourcing and behavioral detection engineering. The vendor base stratifies into three tiers: integrated platform providers, specialized endpoint specialists, and hardware-anchored security fabricators. Strategic archetypes include telemetry-heavy SaaS operators, privacy-preserving authentication architects, and telecom-coupled distribution players. Dominant competitive moves encompass strategic partnerships with hyperscale cloud providers and portfolio diversification into identity restoration services.
Within the integrated platform tier, NortonLifeLock and Bitdefender exemplify divergent geographic anchoring strategies. Kaspersky Lab occupies a position navigating geopolitical headwinds through transparent code audit specialization. Trend Micro and McAfee represent scale-driven archetypes with extensive patent portfolios. ESET and Avast sit within the European engineering-focused cluster emphasizing heuristic detection capabilities.
| Leading Market Players |
|---|
| Trend Micro |
| Avast |
| McAfee |
| ESET |
| AVG Technologies |
| NortonLifeLock |
| Kaspersky Lab |
| Webroot |
| Bitdefender |
| Others |
Supply Flow & Price Mechanics
Secure element chip pricing from Taiwanese foundries cascades through hardware token manufacturing into three-tier pricing structure across premium, standard, and economy levels for consumer authentication devices. German and British vendors absorb 8-14 week production delays by tiering warranty coverage and identity restoration guarantees rather than discounting base software licenses.
Pricing Analysis
Warranty bundling separates premium suites with unlimited identity restoration from economy tiers with bare detection-only coverage. Subscription SaaS models dominate, with price differentiation driven by CE marking certification level and AI-powered behavioral detection depth. Pricing pressure stems from platform operators extracting 15-30% transaction fees on mobile app store channels. Small businesses in France show highest price sensitivity, while Munich metropolitan households accept premium banking protection modules with minimal negotiation.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and the United Kingdom operate hub-and-spoke patterns for hardware token fulfillment. Secure element chip fabrication concentrates in Taiwan, South Korea, and Japan, with raw material dependencies on silicon feedstock, rare earth substrates, and cryptographic co-processor components. Single-source vulnerability from Taiwanese foundry concentration creates supply chain risk for EU data residency-compliant hardware. Distribution runs through telecom carrier partnerships and direct-to-consumer mobile marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consumer security vendors face a vertical-integration race to control upstream secure hardware fabrication and downstream identity restoration service delivery. Players capturing both ends capture pricing power that pure software competitors cannot match.
For Market Incumbents: Anticipate biometric template interoperability mandates from the EU AI Act by engineering cross-platform credential portability before regulatory deadlines force retooling. Secure exclusive distribution through British broadband provider white-label partnerships to lock out challenger brands. Invest in backward integration into secure element sourcing to insulate margins from Taiwanese foundry volatility. For New Entrants and Emerging Players: French SME segments in Lyon and Marseille commercial districts offer lowest competitive density for endpoint protection penetration. Target mobile-native discovery entirely within iOS and Android marketplaces to bypass incumbent-controlled direct download portals. Lead with post-quantum cryptography VPN positioning to differentiate from legacy encryption incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor European engineering-focused specialists with transparent code audit capabilities and heuristic detection IP. Long-term viability over a multi-year horizon hinges on compliance engineering depth rather than marketing spend efficiency. Monitor CE marking timeline compression under the Radio Equipment Directive as inflection indicator for product launch velocity advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Integration | NIST lattice-based standards merge with VPN protocols to create next-generation tunneling products. |
| Telecom Carrier Partnership | British broadband providers white-label suites as customer retention tools, opening carrier-mediated distribution. |
| Edge-Based Threat Detection Localization | On-device inference engines process malware signatures locally for German and French data residency requirements. |
| Biometric Authentication Certification | EU AI Act documentation burdens force technical file maintenance for high-risk biometric matching systems. |
| Identity Restoration Service Bundling | Munich and Berlin metropolitan areas demonstrate highest per-capita spending on financial fraud remediation coverage. |
Methodological Framework
Multi-period observation of threat intelligence platform deployments and CE marking certification timelines anchored the trend analysis, supplemented by interviews with consumer security engineering directors, telecom carrier product managers, GDPR compliance officers, and mobile platform policy leads. Secondary validation drew from EU AI Act implementation guidance, ENISA threat landscape reports, SEC filings of publicly traded vendors, and hyperscaler cloud security capex disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrix modeling connected endpoint protection penetration rates, smart home device attach rates, and identity restoration service adoption to generate volume and value outputs across the projection horizon. Segmentation dimensions included product type, technology modality, end-user sophistication tier, and deployment architecture. CAGRs derived from regression analysis of historical subscription renewal patterns and hardware replacement cycles, incorporating GDPR Article 32 procurement acceleration effects and silicon supply fragmentation constraints.
Revisions become necessary when secure element chip shortages extend beyond current manufacturing cycle estimates or when cross-border data localization rules fragment cloud architectures beyond modeled scenarios. Forecasts reflect documented assumptions on regulatory timeline adherence and threat actor sophistication trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Signal Jammer Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
Europe Security Screening Market
Security and Surveillance
Security Services Market
Security and Surveillance
Urban Security Screening Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
Russian Intelligent Eavesdropping Detection System Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Night Vision Binoculars Market
Security and Surveillance
Underwater Security (Systems and Services) Market
Security and Surveillance
Full Body Scanner Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Home Security Solution Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Shock Sensor Market