
 Global Fire Control System Market | 2026-2036
Global Fire Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fire Control System Market Foresight
Naval Forces is rotating toward integrated fire control suites as the fastest-growing buyer archetype, displacing legacy ground-system procurement cycles. BAE Systems plc anchors British naval modernization through its Artisan radar-linked fire control architecture. Leonardo S.p.A. dominates Italian and export naval turret integrations. Rheinmetall AG competes in German land-naval hybrid systems with its Trackmaster platform.
A fire control system computes ballistic solutions, sensor fusion, and weapon release timing through radar, electro-optical, and infrared subsystems operating at millisecond refresh rates for real-time targeting accuracy. Naval Fire Control leads system type demand as surface combatant fleets modernize, while Electro-Optical technology captures the fastest expansion due to passive targeting advantages in contested electromagnetic environments. Missile Fire Control concentrates margin pools where integration complexity justifies premium pricing.
FDA standards govern thermal imaging component exports, REACH restricts hazardous materials in electro-optical coatings, and ISO 9001 certification gates supplier eligibility for NATO procurement frameworks. The EU AI Act's risk classification for autonomous targeting functions is reshaping product development roadmaps. Stakeholders must monitor how emerging electromagnetic spectrum denial tactics alter sensor technology investment priorities.
Market Dynamics
Integrated fire control suites are displacing standalone targeting systems across NATO naval modernization programs, compressing procurement cycles and forcing subsystem vendors toward bundled architectures.
Growth Catalysts
- EU Green Deal defense industrial provisions:Accelerated modernization timelines across European surface combatant fleets mandate fire control suite replacements.
- Electro-optical sensor fusion:Passive targeting advantages in contested electromagnetic environments drive naval procurement priorities.
- South Korea:Expanding indigenous destroyer programs create sustained demand for missile fire control integration.
Market Restraints
- Indium gallium arsenide detector supply:Concentrated sourcing from Asian foundries creates electro-optical subsystem vulnerability.
- REACH hazardous material restrictions:Coating reformulation requirements extend electro-optical manufacturing timelines.
- Legacy analog interface persistence:Retrofit compatibility demands fragment R&D allocation across digital-analog hybrid architectures.
Strategic Opportunities
- Unmanned surface vessel integration:Autonomous targeting architectures open new platform categories for fire control vendors.
- German naval expansion:F126 frigate program and submarine fleet renewal create multi-year procurement windows.
- AI-enabled predictive maintenance:Convergence of machine learning with fire control diagnostics enables service revenue expansion.
Industry Challenges
- Millisecond-latency software engineering:Real-time ballistic computation talent scarcity constrains development velocity.
- NATO STANAG certification timelines:Interoperability testing protocols extend product qualification cycles by 18-24 months.
- Electromagnetic spectrum denial adaptation:Rapid adversary countermeasure evolution forces continuous sensor algorithm redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fire Control System Market |
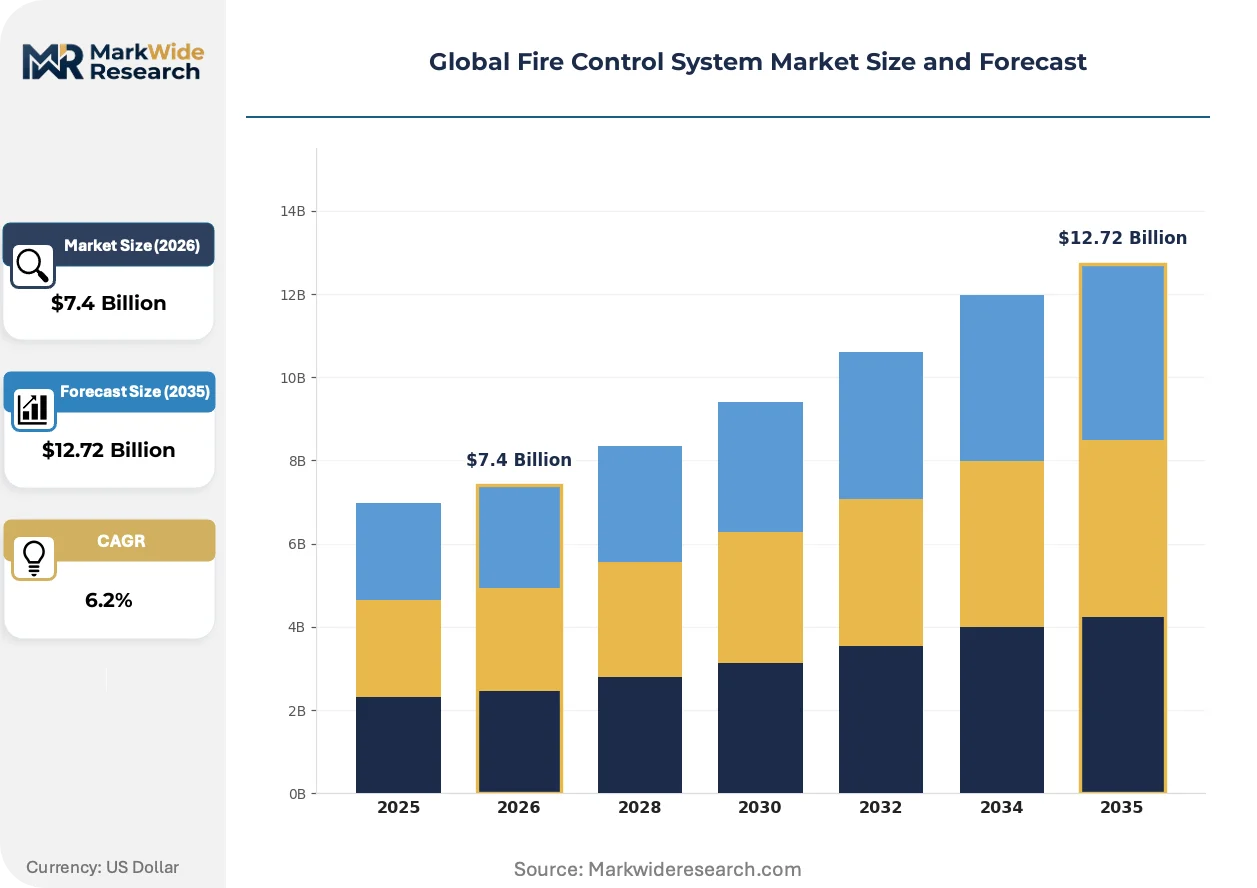
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Anti-Aircraft Fire Control, Naval Fire Control, Airborne Fire Control, Artillery Fire Control, Missile Fire Control Technology: Radar-Based, Electro-Optical, Infrared, Laser, Acoustic Detection Application: Military Defense, Coastal Surveillance, Border Security, Facility Protection, Disaster Management End User: Defense Forces, Homeland Security, Naval Forces, Airport Authorities, Fire Brigades |
| Companies Covered | Leonardo S.p.A., RTX Corporation, BAE Systems plc, Thales Group, Rheinmetall AG, Lockheed Martin Corporation, Northrop Grumman Corporation, ASELSAN A.S., Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fire Control System Market Shifts & Advancements
Fire control architecture is pivoting from hardware-centric to software-defined targeting, enabling faster threat response and reducing platform-specific engineering overhead.
Multi-spectral electro-optical/infrared fusion is displacing standalone radar-dependent targeting across surface combatant fleets. Naval procurement offices in Germany and South Korea are mandating passive sensor redundancy for electromagnetic contested operations. This displacement is compressing margins for pure-play radar vendors while elevating electro-optical integrators.
REACH compliance deadlines are forcing coating chemistry transitions in infrared detector housings. ECHA substance restriction expansions require electro-optical manufacturers to reformulate thermal management materials ahead of 2027 implementation. German and Italian suppliers are accelerating alternative material qualification to maintain NATO export eligibility.
Buyer concentration among NATO naval procurement offices is consolidating supplier relationships around multi-year platform contracts. Traditional component vendors face disintermediation as prime contractors internalize fire control integration. This pattern is most visible in British Type 26 and Australian Hunter-class programs where BAE Systems anchors verticalized supply structures.
Global Fire Control System Market Segmentation
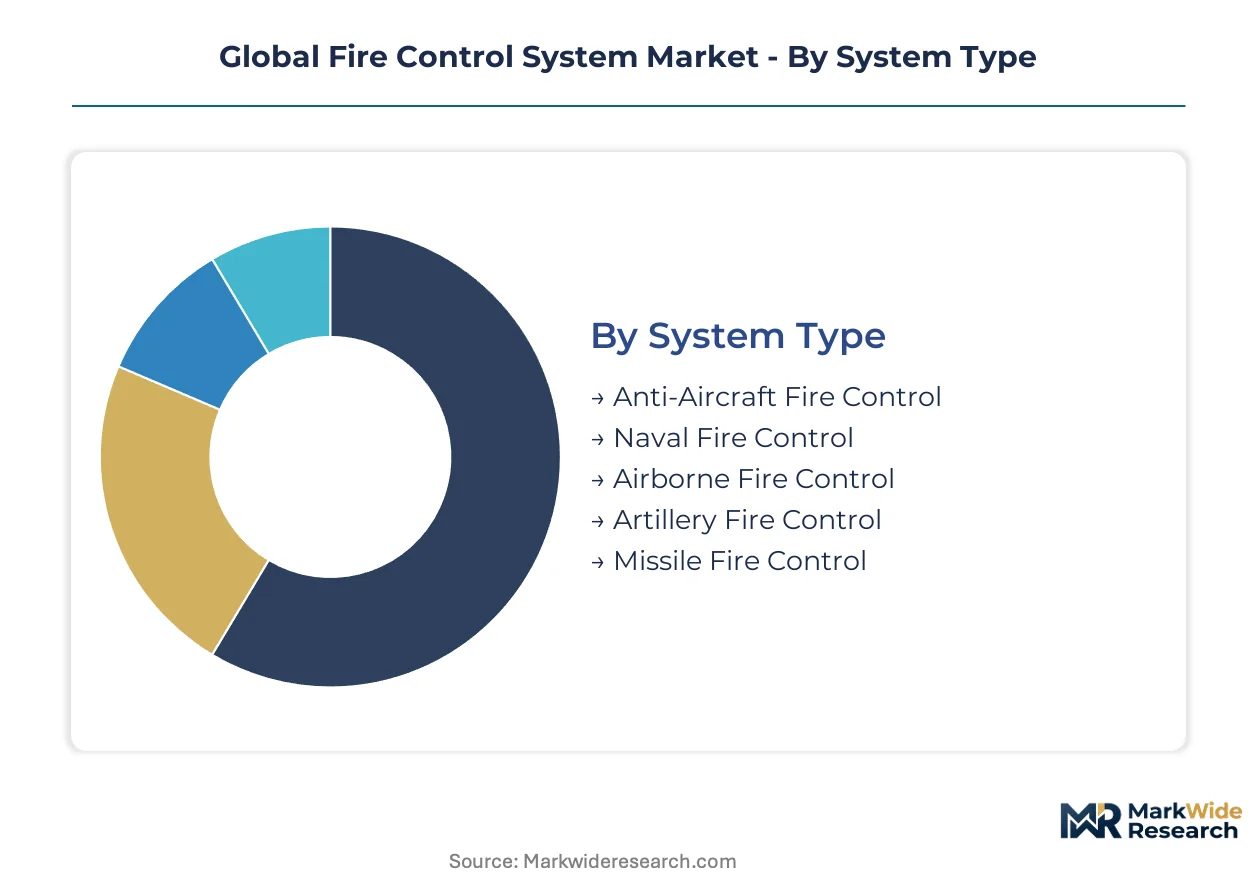
Fire control system procurement channels diverge sharply across military, homeland security, and civilian infrastructure buyers, with each channel imposing distinct certification requirements and integration standards. Understanding these segment boundaries reveals where subsystem vendors can bypass prime contractor capture versus where bundled architectures dominate.
System Type:
Channel distribution varies by combat domain—naval programs flow through shipyard primes, artillery systems through land forces procurement offices, while missile fire control concentrates in specialized defense agencies with direct vendor relationships.
- Naval Fire Control:Integrated combat management systems for surface combatants requiring radar-electro-optical fusion at millisecond refresh rates. Procurement concentrates in German F126 frigate and South Korean KDDX destroyer programs where electromagnetic contested operations mandate passive sensor redundancy.
- Missile Fire Control:High-complexity ballistic computation architectures for surface-to-air and anti-ship missile integration. South Korea's indigenous destroyer programs and NATO vertical launch system upgrades concentrate demand where integration complexity justifies premium subsystem vendor access.
- Anti-Aircraft Fire Control:Radar-directed gun systems for point defense against aerial threats.
- Airborne Fire Control:Fighter and helicopter targeting suites with severe weight and power constraints.
- Artillery Fire Control:Ground-based ballistic computation for self-propelled howitzer and rocket artillery platforms.
By volume, Naval Fire Control leads. By growth pace, Missile Fire Control is ahead.
Technology:
Cost tier stratification separates mature radar architectures from emerging electro-optical investments, with infrared and laser systems occupying intermediate price-performance positions.
- Electro-Optical:Passive targeting through visible-light and near-infrared sensors operating without electromagnetic emission. Demand concentrates in German and Italian naval modernization where REACH coating compliance deadlines accelerate alternative material qualification.
- Radar-Based:Active radio-frequency detection and tracking with all-weather capability. Legacy dominance persists in ground-based air defense and artillery spotting where NATO STANAG interoperability requirements extend procurement cycles.
- Infrared:Thermal imaging for night operations and low-signature target acquisition.
- Laser:Designation and rangefinding for precision-guided munitions.
- Acoustic Detection:Passive listening arrays for counter-battery and underwater threat localization.
Electro-Optical systems command the steepest expansion trajectory as electromagnetic denial tactics proliferate. Radar-Based technology retains the largest installed base.
Application:
Customer type determines specification intensity—military defense demands full-spectrum hardening while civilian applications prioritize cost containment and rapid deployment.
- Military Defense:Full-spectrum fire control for combined arms operations requiring NATO interoperability certification. United States, Germany, and South Korea concentrate procurement where electromagnetic spectrum denial adaptation drives continuous algorithm redevelopment.
- Coastal Surveillance:Maritime domain awareness integrating radar and electro-optical sensors for shoreline protection. EU Green Deal defense industrial provisions accelerate European modernization timelines.
- Border Security:Fixed and mobile installations for frontier monitoring and interdiction.
- Facility Protection:Critical infrastructure defense against drone and standoff threats.
- Disaster Management:Emergency response coordination with degraded communications.
Military Defense absorbs the highest absolute investment. Coastal Surveillance is climbing the fastest as maritime sovereignty disputes intensify.
End User:
Supply concentration aligns with procurement consolidation—naval forces channel spending through shipyard primes while homeland security agencies maintain broader vendor access.
- Naval Forces:Surface combatant and submarine fleet modernization through integrated combat system procurement. British Type 26 and Australian Hunter-class programs demonstrate verticalized supply structures where prime contractors internalize fire control integration.
- Defense Forces:Army and air force artillery, air defense, and armored vehicle programs with fragmented subsystem vendor relationships.
- Homeland Security:Border and critical infrastructure protection with lighter certification requirements.
- Airport Authorities:Counter-drone and perimeter defense for civilian aviation facilities.
- Fire Brigades:Emergency response targeting for hazardous material incidents.
Naval Forces dominate absolute procurement value. Homeland Security is gaining share fastest as critical infrastructure protection budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naval Forces procurement concentrates in five national markets where surface combatant modernization drives fire control suite demand. United States, Germany, South Korea, United Kingdom, and Italy absorb the majority of integrated combat system investment.
United States
The US Navy's DDG(X) next-generation destroyer program and Aegis combat system upgrades sustain missile fire control procurement. FCC spectrum allocation rules govern radar subsystem frequency licensing for domestic suppliers. Procurement flows through prime contractors clustered around Washington DC and Norfolk naval bases.
Germany
F126 frigate construction and submarine fleet renewal create multi-year demand windows for electro-optical integration. REACH coating compliance deadlines from ECHA accelerate alternative material qualification for infrared detector housings. Industrial activity concentrates in North Rhine-Westphalia and Bavaria where Rheinmetall anchors land-naval hybrid system development.
South Korea
Indigenous KDDX destroyer programs and expanding surface combatant fleets sustain missile fire control integration demand. MFDS certification requirements govern military subsystem export eligibility. Seoul-Incheon corridor hosts prime contractor engineering centers for combat management system development.
United Kingdom
Type 26 frigate and Dreadnought submarine programs drive integrated fire control suite procurement through BAE Systems-led verticalized supply structures. Ministry of Defence procurement frameworks mandate UK industrial content thresholds. Glasgow shipyards and Portsmouth naval base anchor combat system integration activity.
Italy
Naval turret modernization and export-oriented frigate programs concentrate demand with Leonardo-anchored supply relationships. EU AI Act risk classifications for autonomous targeting functions reshape product development timelines. La Spezia and Genoa naval industrial clusters host electro-optical subsystem engineering.
Global Fire Control System Market Competitive Landscape
Player mix skews toward defense prime contractors with verticalized combat system integration capabilities. Tier structure separates platform-owning integrators from subsystem specialists. Three archetypes dominate: radar-electro-optical fusion specialists, missile fire control integrators, and naval combat management system primes. Competitive dynamics center on multi-year platform contract capture and NATO STANAG certification acceleration.
Within the naval combat management tier, BAE Systems plc, Leonardo S.p.A., and Rheinmetall AG exemplify distinct national anchoring strategies. BAE Systems occupies a position representing British verticalized supply structures. Leonardo exemplifies Italian turret integration specialization with export market orientation. Rheinmetall sits within the German land-naval hybrid system archetype. RTX Corporation and Thales Group represent transnational scale players spanning multiple combat domains. Lockheed Martin Corporation and Northrop Grumman Corporation anchor US-centric missile fire control integration. ASELSAN A.S. and Saab AB exemplify emerging supplier national champions with NATO interoperability focus.
| Leading Market Players |
|---|
| Leonardo S.p.A. |
| RTX Corporation |
| BAE Systems plc |
| Thales Group |
| Rheinmetall AG |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| ASELSAN A.S. |
| Saab AB |
| Others |
Supply & Pricing Matrix
NATO STANAG certification gates supplier eligibility while simultaneously stratifying price tiers across fire control subsystem vendors. REACH coating compliance deadlines from ECHA impose parallel qualification burdens that compress margins for electro-optical manufacturers while elevating certified integrators. Procurement offices in Germany and South Korea exploit this dual gating mechanism to extract pricing concessions from component suppliers seeking platform contract access.
Pricing Analysis
Next-generation software-defined fire control architectures command substantial premiums over legacy hardware-centric systems, while prior-generation analog-digital hybrid platforms face accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified integrators from regional suppliers and uncertified component vendors. Price differentiation hinges on ISO 9001 certification tier and millisecond-latency performance guarantees. Cost compression in electro-optical subsystems is intensifying because indium gallium arsenide detector supply constraints force buyers toward alternative sensor technologies. Homeland security agencies exhibit highest price sensitivity due to budget fragmentation, while naval procurement offices demonstrate lowest sensitivity given mission-critical performance requirements.
Supply Chain Analysis
Germany and Italy anchor electro-optical subsystem engineering for NATO surface combatant programs, while South Korea concentrates indigenous destroyer combat management system development. Supply chains draw from specialized Asian foundries for indium gallium arsenide detectors, German optics manufacturers for precision lens assemblies, and Italian turret integrators for naval gun fire control. Single-source vulnerability pervades infrared detector substrate supply where concentrated Asian sourcing creates electro-optical manufacturing bottlenecks. Distribution runs through shipyard primes for naval programs, land forces procurement offices for artillery systems, and specialized defense agencies for missile fire control integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among NATO naval procurement offices, with British Type 26 and Australian Hunter-class programs demonstrating how prime contractor verticalization fragments subsystem vendor access. This consolidation pattern forces suppliers toward bundled architecture partnerships or niche specialization.
For Market Incumbents: Consolidate sensor fusion capabilities through backward integration into electro-optical component manufacturing, reducing exposure to indium gallium arsenide supply bottlenecks. Lock in multi-year platform contracts with German F126 and South Korean KDDX programs before REACH compliance deadlines reshape supplier qualification pools. Prioritize NATO STANAG certification acceleration as a defensive moat against emerging electro-optical specialists.
For New Entrants and Emerging Players: Lead with unmanned surface vessel fire control architectures where autonomous targeting requirements bypass incumbent prime contractor relationships. Coastal surveillance applications present the most penetrable segment given lighter certification requirements and fragmented buyer structures. Pursue direct relationships with homeland security agencies rather than competing for naval platform contracts.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates divesting non-core fire control divisions amid portfolio rationalization pressures. Long-term viability centers on software-defined targeting capabilities where recurring algorithm update revenue supersedes one-time hardware sales. Monitor EU AI Act implementation timelines as the critical inflection signal for autonomous targeting function valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Electro-Optical Sensor Fusion Development | Passive targeting redundancy addresses electromagnetic spectrum denial tactics in German and Italian naval programs. |
| NATO STANAG Certification Acceleration | Interoperability qualification compresses competitor entry timelines by 18-24 months in platform contracts. |
| Software-Defined Targeting Architecture | Millisecond-latency algorithm updates enable recurring service revenue from Aegis combat system upgrades. |
| Indium Gallium Arsenide Supply Diversification | Alternative detector material qualification mitigates concentrated Asian foundry sourcing vulnerability. |
| Unmanned Surface Vessel Integration | Autonomous fire control suites open new platform categories beyond traditional surface combatant procurement. |
Research Methodology
Cross-validation between defense procurement database analysis and prime contractor engineering disclosures anchors the qualitative findings in this study. Primary interviews with naval program managers, electro-optical subsystem engineers, NATO interoperability certification officers, and shipyard procurement directors combined with secondary validation from SEC 10-K filings, EU defense industrial strategy documents, and South Korean MFDS certification records. Bottom-up and top-down triangulation reconciled segment-level demand patterns with aggregate budget allocation data across the United States, Germany, and South Korea.
Sensitivity analysis tested forecast robustness against alternative scenarios for electromagnetic spectrum denial adaptation speed and REACH coating compliance implementation timelines. The analytical framework modeled demand across system type, technology generation, application intensity, and end-user procurement channel throughout the projection horizon. CAGRs derived from polynomial trend fitting to historical procurement cycles adjusted for platform replacement acceleration under EU Green Deal provisions. Industry-specific inputs included German F126 frigate construction schedules and South Korean KDDX destroyer program milestones.
Forecasts assume regulatory continuity in REACH substance restrictions and EU AI Act risk classifications; material policy shifts would require re-modeling electro-optical manufacturing cost structures and autonomous targeting development roadmaps. Specific risks that could revise projections include indium gallium arsenide supply disruption, NATO STANAG protocol revision, or electromagnetic countermeasure breakthrough altering sensor technology investment priorities. Recalibration cycles align with material shifts in naval procurement budget allocations and coating chemistry qualification milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market
Fire Safety & Protection
Portable Fire Extinguisher Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Global Smoke Evacuation Systems Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Fire Protection Systems Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Europe Fire-Resistant Glass Market