
 Body Armor and Personal Protection Market | 2026-2036
Body Armor and Personal Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Body Armor and Personal Protection Market Insights
Aftermarket refurbishment and upgrade services is reconfiguring margin pools away from initial equipment sales across the body armor value chain. BAE Systems plc sustains its position through captive supply of ceramic plate substrates and integrated platform contracting with NATO-aligned militaries. Point Blank Enterprises Inc. specializes in domestic law enforcement channels, leveraging NIJ-certified manufacturing facilities in Florida and Connecticut to control lead times for municipal police departments.
Body armor and personal protection encompasses wearable ballistic-resistant garments, hard armor inserts, and extremity protection engineered to defeat specific threat levels measured by V50 ballistic limits and backface deformation standards under NIJ 0101.06 protocols. Kevlar and Ultra-High Molecular Weight Polyethylene dominate soft armor applications where multi-hit flexibility and weight reduction determine procurement decisions, while ceramic plates command premium positioning in military plate carrier systems due to superior armor-piercing round defeat capability. Military Operations anchors volume demand through multi-year defense procurement cycles, though Private Security represents the fastest-expanding application segment as executive protection details and critical infrastructure guards adopt law-equivalent protection standards.
The US National Institute of Justice, the European Committee for Standardization through EN 1063 ballistic standards, and the US Occupational Safety and Health Administration collectively shape product compliance burdens, testing costs, and cross-border market access conditions for manufacturers. The EU AI Act and emerging CSRD reporting requirements are extending traceability mandates to defense supply chains, compelling material suppliers to document carbon intensity across Dyneema and aramid fiber production. Stakeholders must monitor divergence between US NIJ revision timelines and European standardization harmonization efforts to anticipate certification-driven product redesign cycles.
Market Dynamics
Federal defense procurement cycles and municipal police modernization programs are tightening performance-to-weight ratios for next-generation ballistic solutions, compressing supplier lead times while elevating certification compliance costs across the value chain.
Growth Catalysts
- NIJ Protocol Revisions:The US National Institute of Justice is tightening backface deformation benchmarks under NIJ 0101.06, forcing vest redesigns that favor advanced polyethylene and ceramic composite suppliers.
- Military Plate Carrier Modernization:NATO-aligned defense ministries are procuring lighter hard armor inserts capable of multi-hit armor-piercing defeat, expanding addressable demand for ceramic substrate manufacturers.
- Private Security Standardization:Executive protection details and critical infrastructure guards are adopting law-equivalent NIJ certification levels, extending procurement volumes beyond traditional military and police channels.
Market Restraints
- Aramid Fiber Supply Concentration:Dyneema and Kevlar production capacity clusters in the United States and Netherlands, exposing buyers to single-source disruption risk during geopolitical friction.
- CSRD Traceability Burden:The EU Corporate Sustainability Reporting Directive mandates carbon intensity documentation across aramid fiber supply chains, elevating compliance costs for European market access.
- Soft Armor Substitution Ceiling:Ultra-High Molecular Weight Polyethylene faces inherent V50 ballistic limits against armor-piercing threats, constraining penetration into military plate carrier applications.
Strategic Opportunities
- Aftermarket Refurbishment Services:Municipal police departments are extending vest service life through NIJ-certified reconditioning programs, creating recurring revenue streams independent of new equipment sales.
- EU AI Act Supply Chain Extension:Defense material suppliers can capture premium positioning by documenting AI-driven manufacturing traceability ahead of mandated CSRD reporting deadlines.
- Extremity Protection Undersupply:Ballistic helmets and limb protection remain underpenetrated relative to torso armor across private security and corrections segments, offering white space for specialized entrants.
Industry Challenges
- NIJ Certification Timeline Compression:Testing backlog at approved ballistics laboratories extends product launch cycles, delaying revenue recognition for redesigned vest platforms.
- Multi-Material Integration Complexity:Combining ceramic plates with polyethylene backers requires specialized bonding processes that few domestic manufacturers have perfected at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Armor and Personal Protection Market |
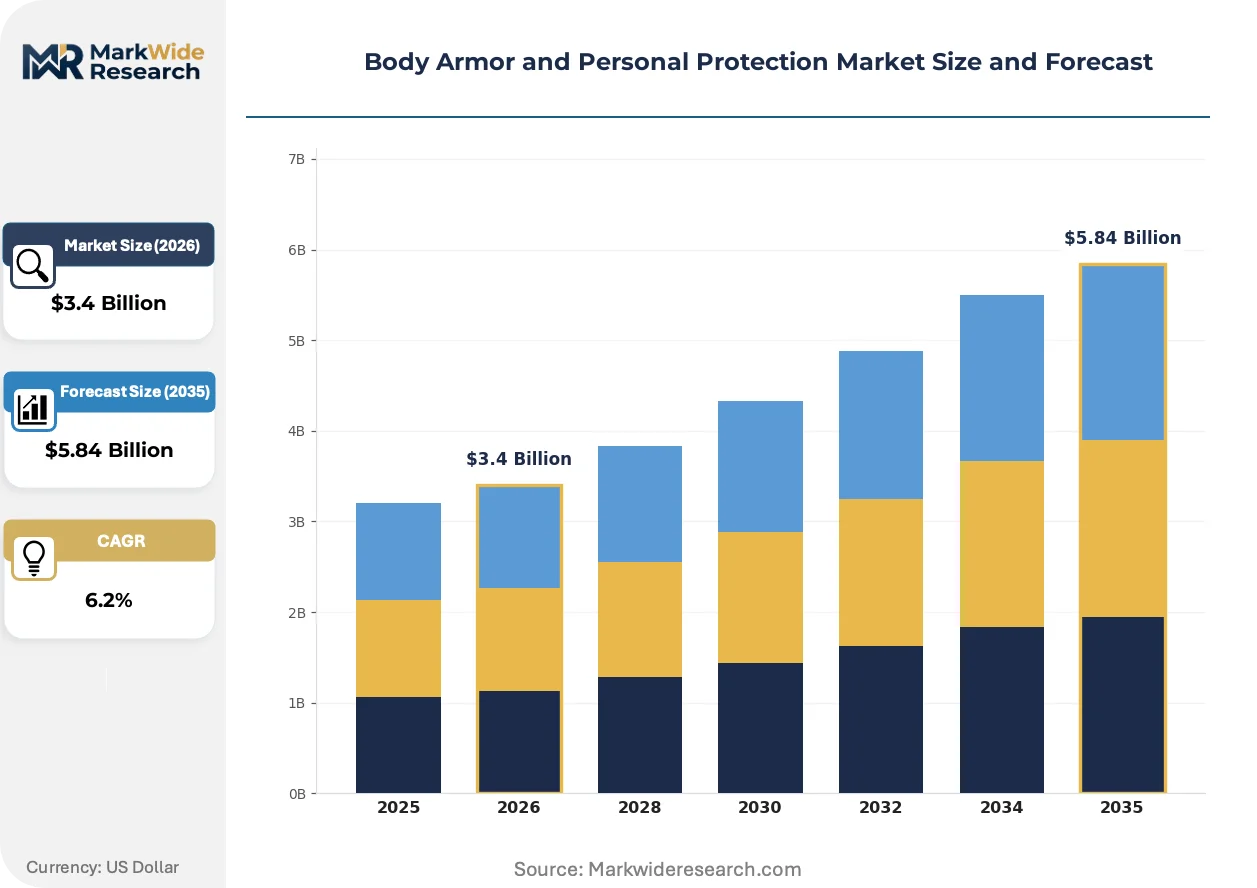
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Vests, Plate Carriers, Tactical Helmets, Riot Shields, Protective Gloves Material Type: Kevlar, Dyneema, Ceramic Plates, Steel Plates, Ultra-High Molecular Weight Polyethylene Application: Military Operations, Law Enforcement, Private Security, Correctional Facilities, Emergency Response End User: Armed Forces, Police Departments, Security Agencies, Firefighters, Disaster Relief Teams |
| Companies Covered | BAE Systems plc, Point Blank Enterprises Inc., Safariland LLC, DuPont de Nemours, Inc., Honeywell International Inc., Avon Protection plc, 3M Company, Ceradyne, Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Armor and Personal Protection Market Trends and Innovations
Material science convergence and regulatory traceability mandates are restructuring how ballistic protection is engineered, certified, and procured across military and law enforcement channels.
Ultra-High Molecular Weight Polyethylene is hybridizing with ceramic strike faces in next-generation plate carriers, delivering armor-piercing protection at weights below traditional pure-ceramic systems. US Army and Marine Corps procurement offices are accelerating field trials of these hybrid configurations. The technology is compressing the performance gap between soft and hard armor categories, forcing suppliers to reposition around integrated system contracting rather than component sales.
The EU AI Act is extending algorithmic transparency requirements to defense supply chains, compelling manufacturers to document automated quality control processes in Dyneema and aramid fiber production. European Committee for Standardization harmonization efforts are incorporating these traceability protocols into EN 1063 ballistic standard revisions. Military exporters targeting NATO-aligned European ministries must retrofit production documentation systems to maintain certification eligibility.
Municipal police departments are consolidating procurement through state-level cooperative purchasing agreements, reducing vendor count while standardizing NIJ certification tier requirements. Florida and Connecticut manufacturing clusters are capturing disproportionate share by co-lating production with these consolidated buying pools. The concentration is marginalizing smaller regional suppliers unable to meet volume and lead time thresholds set by multi-agency contracts.
Body Armor and Personal Protection Market Segmentation
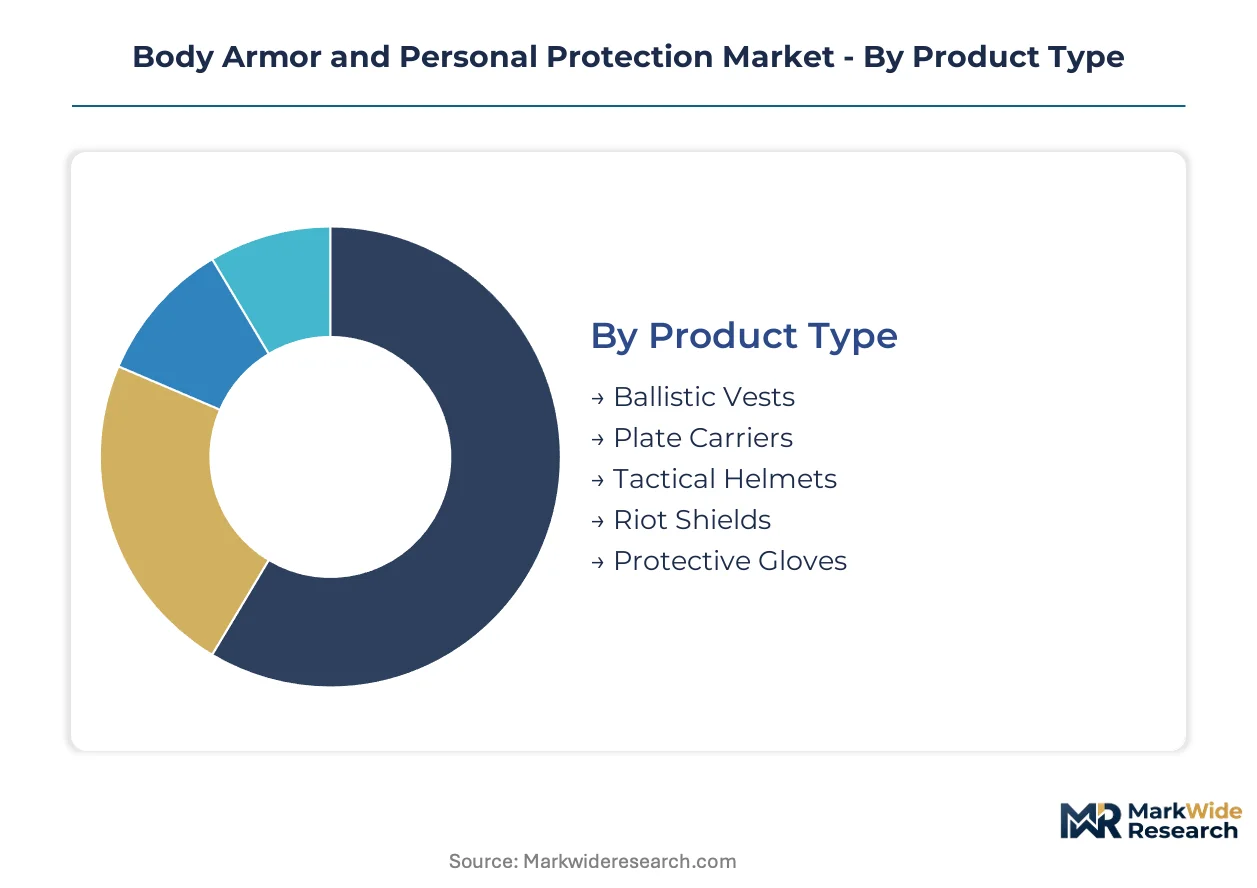
Segmentation reveals divergent service intensity and procurement rhythms across the body armor value chain. Aftermarket refurbishment economics favor certain product categories over others, while material selection directly determines certification compliance burdens and replacement cycles.
Product Type:
After-sales service intensity varies dramatically by product category, with vest systems requiring periodic NIJ recertification and plate carriers demanding strike face replacement programs.
- Ballistic Vests:Soft armor garments constructed from woven aramid or polyethylene fibers designed to defeat handgun and fragmentation threats. Police departments in the United States concentrate procurement here, driven by municipal modernization programs and officer safety mandates. By volume, Ballistic Vests leads. By growth pace, Plate Carriers is ahead.
- Plate Carriers:Modular tactical platforms accepting hard armor inserts, engineered for military and specialized law enforcement applications. NATO-aligned defense ministries are procuring lighter configurations capable of multi-hit armor-piercing defeat, expanding addressable demand for ceramic substrate integration.
- Tactical Helmets:Ballistic-resistant head protection systems rated against fragmentation and handgun threats. United States Army and Marine Corps field trials are accelerating adoption of enhanced cut designs with integrated communications mounting.
- Riot Shields:Transparent polycarbonate or composite barriers for crowd control and corrections environments. Correctional facilities and municipal police departments in Florida and Connecticut manufacturing clusters standardize procurement through state cooperative purchasing agreements.
- Protective Gloves:Cut-resistant and impact-protective hand coverage for tactical and emergency operations. Private security details and critical infrastructure guards are adopting law-equivalent protection standards, extending volumes beyond traditional channels.
Replacement cycles compress toward five-year vest service life mandates, while plate carrier platforms persist through modular upgrade paths.
Material Type:
Cost tier stratification separates premium ceramic solutions from standard aramid and economy steel alternatives, with polyethylene occupying a converging middle position.
- Kevlar:Aramid fiber with high tensile strength and thermal stability, dominant in legacy soft armor applications. Production capacity clusters in the United States expose buyers to single-source disruption risk during geopolitical friction.
- Dyneema:Ultra-high molecular weight polyethylene fiber offering superior strength-to-weight ratios versus aramid alternatives. The Netherlands production base faces EU CSRD traceability mandates requiring carbon intensity documentation across supply chains.
- Ceramic Plates:Alumina, silicon carbide, or boron carbide strike faces bonded to composite backers for armor-piercing threat defeat. Military plate carrier modernization programs in the United States and NATO-aligned European ministries command premium positioning.
- Steel Plates:Economical hard armor alternative with multi-hit durability but weight penalties. Budget-constrained correctional facilities and private security operations accept performance trade-offs for procurement cost reduction.
- Ultra-High Molecular Weight Polyethylene:Advanced polymer competing with Dyneema in soft armor and hybrid plate applications. Inherent V50 ballistic limits against armor-piercing threats constrain penetration into military plate carrier segments despite weight advantages.
Material selection locks buyers into specific certification pathways and supplier relationships for product lifecycles.
Application:
Customer type diversity spans institutional defense procurement and fragmented private security contracting, with diverging compliance and volume requirements.
- Military Operations:Volume demand anchor through multi-year defense procurement cycles with integrated platform contracting requirements. United States federal defense budgets sustain predictable order flows for NIJ-certified and STANAG-compliant systems.
- Law Enforcement:Municipal police modernization programs tightening performance-to-weight ratios for next-generation ballistic solutions. State-level cooperative purchasing agreements in Florida and Connecticut are consolidating vendor counts while standardizing certification tier requirements.
- Private Security:Executive protection details and critical infrastructure guards adopting law-equivalent protection standards. This segment is expanding most quickly as non-state actors professionalize threat response capabilities.
- Correctional Facilities:Riot control and stab-resistant protection for corrections officers. Procurement concentrates in state cooperative agreements with emphasis on durability and cost containment over ballistic performance.
- Emergency Response:Ballistic protection for firefighters and disaster relief personnel operating in volatile environments. Post-incident procurement patterns favor rapid deployment capabilities over optimized specifications.
Military and law enforcement applications dominate current revenue, while private security is climbing the fastest.
End User:
Volume concentration among armed forces and police departments contrasts with fragmented security agency procurement, shaping supplier go-to-market strategies.
- Armed Forces:United States Department of Defense and NATO-aligned ministries procuring through multi-year indefinite delivery contracts. Performance specifications prioritize armor-piercing defeat and multi-hit survivability over weight minimization.
- Police Departments:Municipal agencies consolidating procurement through state cooperative purchasing agreements. Lead time compression and certification compliance costs are elevating barriers for smaller regional suppliers.
- Security Agencies:Private sector executive protection and facility security operations. Standardization around NIJ certification levels is extending procurement volumes beyond traditional military and police channels.
- Firefighters:Emergency services adopting ballistic protection for active threat incidents. Interagency coordination with police departments drives specification alignment rather than independent procurement.
- Disaster Relief Teams:Federal and state emergency management assets requiring rapid-deployment protective equipment. Surge procurement patterns favor established suppliers with domestic manufacturing capacity.
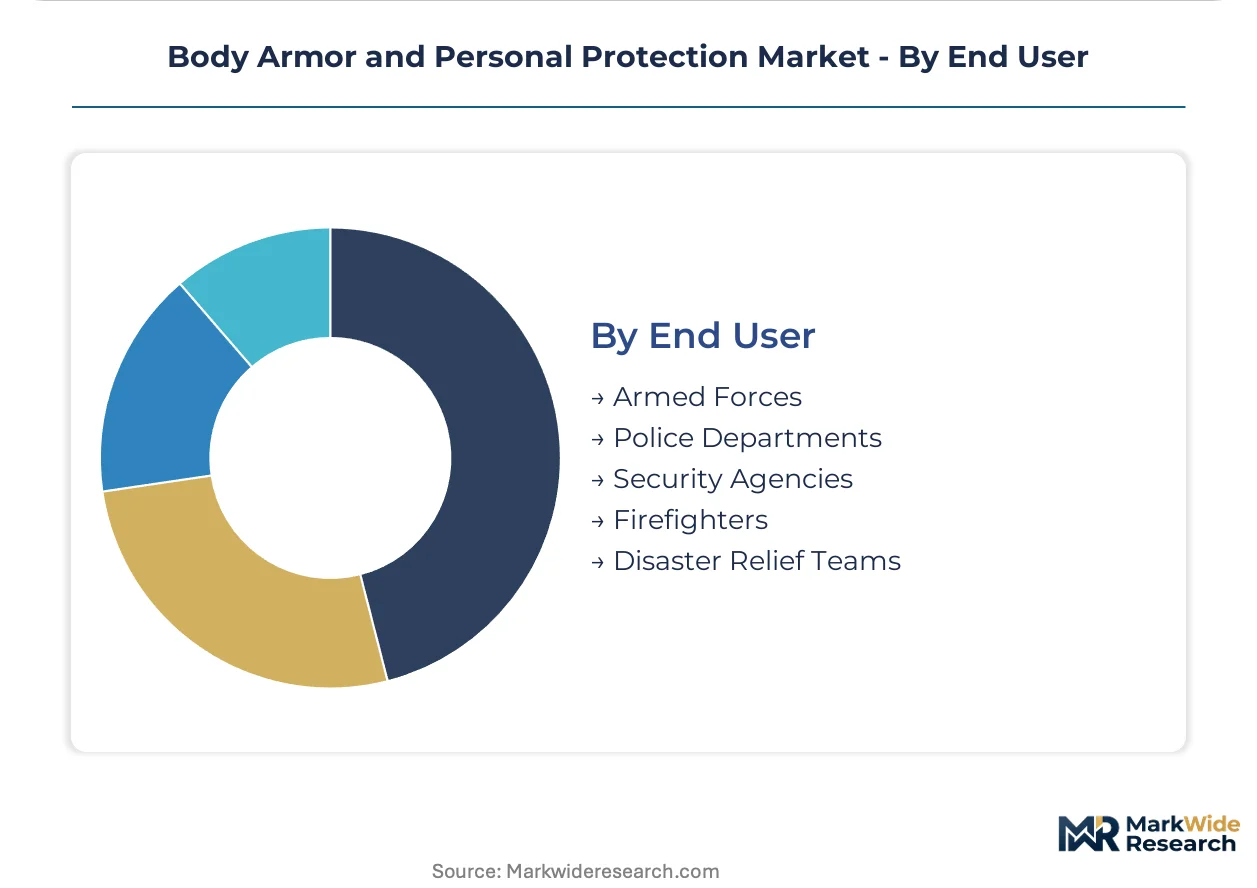
Armed forces anchor procurement volumes, yet security agencies are gaining share fastest as protection standards professionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aramid fiber production clusters in the United States and Netherlands concentrate supply-side leverage for body armor manufacturers serving NATO-aligned defense ministries and municipal police agencies.
United States
Federal defense procurement cycles and municipal police modernization programs drive sustained demand for NIJ-certified ballistic solutions. The National Institute of Justice revises 0101.06 protocols to tighten backface deformation benchmarks. Florida and Connecticut manufacturing clusters control lead times for state cooperative purchasing agreements consolidating multi-agency contracts.
Germany
NATO defense ministries procure lighter hard armor inserts through multi-year platform contracts prioritizing multi-hit armor-piercing defeat. The European Committee for Standardization harmonizes EN 1063 ballistic standards with emerging EU AI Act traceability mandates. Industrial concentration in North Rhine-Westphalia and Bavaria supports integrated ceramic substrate manufacturing for export to European security forces.
United Kingdom
Armed forces procurement through the Ministry of Defence emphasizes STANAG-compliant plate carrier systems for expeditionary operations. UK regulatory alignment with EU CSRD reporting requirements extends carbon intensity documentation to Dyneema and aramid fiber imports. Greater London and Midlands manufacturing bases serve domestic police modernization and private security standardization trends.
Netherlands
Dyneema ultra-high molecular weight polyethylene production anchors European soft armor supply chains for law enforcement and private security channels. EU Corporate Sustainability Reporting Directive mandates compel carbon intensity disclosure across fiber production facilities. Eindhoven-region industrial clusters integrate automated quality control systems to satisfy emerging algorithmic transparency requirements under the EU AI Act.
France
Domestic security forces and export markets for African peacekeeping operations sustain demand for hybrid ceramic-polyethylene plate configurations. ANSM and CNIL oversight extends to defense supply chain documentation as EU regulatory frameworks deepen. Île-de-France and Auvergne-Rhône-Alpes manufacturing concentrations support NATO-aligned defense procurement and corrections facility modernization programs.
Body Armor and Personal Protection Market Competitive Landscape
Integrated platform contractors and specialized domestic suppliers split the market between multi-year defense procurement cycles and municipal police channels requiring compressed lead times. The vendor base concentrates around three strategic archetypes: captive ceramic substrate producers, NIJ-certified manufacturing specialists, and diversified materials science conglomerates. Competitive positioning hinges on backward integration into fiber production and state-level cooperative purchasing alignment.
Among UK-based integrated defense contractors, BAE Systems plc exemplifies the captive supply archetype through ceramic plate substrate production. Point Blank Enterprises Inc. and Safariland LLC occupy positions within the NIJ-certified specialist tier, leveraging domestic manufacturing footprints to serve municipal police procurement consolidation. DuPont de Nemours, Inc. represents the materials science conglomerate archetype, with Kevlar aramid fiber production anchoring soft armor supply relationships across military and law enforcement segments.
| Leading Market Players |
|---|
| BAE Systems plc |
| Point Blank Enterprises Inc. |
| Safariland LLC |
| DuPont de Nemours, Inc. |
| Honeywell International Inc. |
| Avon Protection plc |
| 3M Company |
| Ceradyne |
| Rheinmetall AG |
| Others |
Pricing and Supply Chain Analysis
The Port of Rotterdam logistics corridor carries Dyneema fiber shipments from Netherlands production facilities to United States assembly plants, with freight cost volatility amplifying margin pressure for polyethylene-backed vest manufacturers while ceramic plate suppliers in Florida and Connecticut exploit geographic proximity to state cooperative purchasing agreements for price premium capture.
Pricing Analysis
NIJ 0101.06 certification dictates the pricing tier structure across the body armor value chain, with three-tier pricing structure across premium, standard, and economy levels separating STANAG-compliant military systems from municipal police NIJ Level IIIA vests and budget correctional steel plate alternatives. Price differentiation hinges on certification grade and volume scale, with state cooperative purchasing agreements compressing per-unit costs for aggregated municipal orders. Cost compression in standard-tier soft armor is intensifying because Dyneema supply concentration exposes buyers to single-source disruption premiums. Correctional facilities exhibit highest price sensitivity, accepting steel plate weight penalties for procurement cost reduction, while NATO defense ministries demonstrate lowest sensitivity, prioritizing multi-hit armor-piercing defeat capability.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for aramid fiber distributors serving domestic law enforcement channels. Geographic supply concentration clusters in United States, Netherlands, and Germany, with Kevlar production anchored in Virginia and Dyneema fiber extrusion tethered to Heerlen facilities. Raw material dependencies center on alumina substrates for ceramic strike faces, ultra-high molecular weight polyethylene resin, and aramid fiber precursors. Single-source vulnerability persists in boron carbide ceramic feedstock. Distribution runs through state-level cooperative purchasing agreements consolidating multi-agency contracts in Florida and Connecticut manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal defense procurement cycles are entering an upswing phase as NATO-aligned ministries accelerate plate carrier modernization programs, positioning the body armor market for cyclical recovery driven by multi-year platform contracting renewal.
For Market Incumbents: Pre-empt polyethylene hybrid displacement by deepening captive ceramic substrate production and securing NIJ recertification capacity ahead of protocol revision deadlines. Ceramic plate suppliers should expand bonding process R&D to defend against emerging hybrid configuration entrants. State cooperative purchasing alignment in Florida and Connecticut manufacturing clusters remains the priority channel control lever. For New Entrants and Emerging Players: Establish a beachhead in extremity protection undersupply, specifically ballistic helmets and limb protection for private security details adopting law-equivalent standards. Tactical helmet integration with communications systems represents the most penetrable white space. Go-to-market execution should target corrections facility procurement officers through state cooperative agreement participation rather than direct municipal police competition. For Investors and Strategic Acquirers: NIJ-certified manufacturing specialists with state cooperative purchasing alignment present the most compelling acquisition profile for exposure to municipal police modernization cyclicality. Long-term viability across the analysis window rests on backward integration into fiber production or ceramic substrate supply. The signal to watch is NIJ testing laboratory backlog duration as inflection indicator for revenue recognition timing compression.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Polyethylene Hybrid R&D Investment | Captures NATO defense ministry procurement shifting toward lighter multi-hit armor-piercing defeat systems. |
| NIJ Recertification Service Expansion | Creates recurring revenue streams from municipal police vest service life extension mandates. |
| State Cooperative Purchasing Alignment | Secures volume allocation through Florida and Connecticut multi-agency contract consolidation. |
| EU CSRD Traceability Documentation | Maintains European market access for Dyneema and aramid fiber suppliers under emerging carbon intensity mandates. |
| Extremity Protection Product Launch | Addresses ballistic helmet and limb protection undersupply in private security and corrections segments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NIJ certification databases, defense procurement records, and EU regulatory filings through structured interviews with ballistic laboratory directors, municipal police procurement officers, ceramic substrate plant managers, and private security operations executives. Secondary validation drew from STANAG compliance documentation, state cooperative purchasing agreement records, and customs trade data for aramid fiber and ceramic plate imports. Bottom-up vest and plate carrier volume estimates triangulated against top-down defense budget allocation analysis.
Forecast inputs include military procurement cycle timing, municipal police modernization program phasing, and private security standardization adoption curves across the projection horizon. Segmentation modeling incorporated product type, material composition, application channel, and end-user archetype dimensions. CAGRs derived from regression analysis against historical defense spending patterns and certification-driven replacement cycle compression. Industry-specific inputs encompassed NIJ protocol revision implementation schedules and EU AI Act traceability mandate rollout sequencing.
Sensitivities concentrate around NIJ testing laboratory capacity constraints, geopolitical disruption to Netherlands Dyneema production, and NATO defense budget reallocation. Forecasts reflect documented assumptions regarding procurement cycle continuity and certification harmonization timelines. Material shifts in United States federal defense appropriations or European standardization divergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Night Vision Goggles Market
Personal Safety
Pepper Sprays Market
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
Smart Home Safety Market
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Fall Detection System Market
Personal Safety
Road Safety Market
Personal Safety
Child Leash Market
Personal Safety
Personal Safety Alarms Market
Personal Safety
Bulletproof Vest Market
Personal Safety
China Travel Safety Kits Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Global Personal Emergency Response Systems (PERS) Market
Personal Safety
Global Fall Protection Market
Personal Safety
Global Self Defense Products Market
Personal Safety
Concealable Vest Market