
 Global Flame Detector Market | 2026-2036
Global Flame Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flame Detector Market Analysis
The EU ATEX directive is shifting compliance burdens toward third-party notified-body certification for flame detectors deployed in explosive atmospheres. Honeywell International leverages its TÜV Rheinland-certified manufacturing lines to sustain premium positioning across European petrochemical sites. Johnson Controls anchors its portfolio through in-house production of multi-spectrum infrared sensors. Siemens competes on SIL 2 and SIL 3 rated architectures that dominate German utility contracts.
A flame detector is a specialized optical sensor that identifies combustion by analyzing electromagnetic radiation emitted in specific spectral bands, typically ultraviolet at 185-260 nanometers or infrared at 4.35 micrometers corresponding to carbon dioxide resonance. These devices serve as primary fire suppression triggers in environments where conventional smoke detectors fail due to airflow, dust, or chemical vapor interference. Infrared detectors occupy the largest revenue pool given their immunity to solar radiation and suitability for outdoor hydrocarbon processing. Combination UV-IR units represent the fastest-expanding category as operators seek false-alarm reduction in high-value facilities. The oil and gas end-user segment commands the deepest margin pools due to mandatory blowout prevention protocols.
The US Occupational Safety and Health Administration mandates flame detection under 29 CFR 1910 for process safety management of highly hazardous chemicals, while the EU Machinery Directive enforces CE-marked conformity for fire safety components placed on the European market. China's SAMR implements GB standards that require flame detector calibration traceability for chemical plant licensing. Stakeholders must monitor divergence between IEC 61508 edition revisions and national adoptions when certifying products for multi-region deployment.
Market Dynamics
The flame detector market is undergoing structural compression as multi-spectrum infrared technology absorbs demand from single-band UV systems, while IEC 61508 SIL certification requirements harden procurement criteria across petrochemical and utility verticals.
Growth Catalysts
- Oil and gas facility expansion:Middle Eastern process safety budgets are widening procurement windows for flame detection systems at new refinery and LNG export terminals.
- ATEX directive enforcement:The EU's tightened explosive atmosphere certification is mandating third-party notified-body validation for all new installations in chemical processing zones.
- Multi-spectrum sensor adoption:Combination UV-IR units are penetrating high-value facilities where false-alarm reduction justifies premium hardware expenditure.
Market Restraints
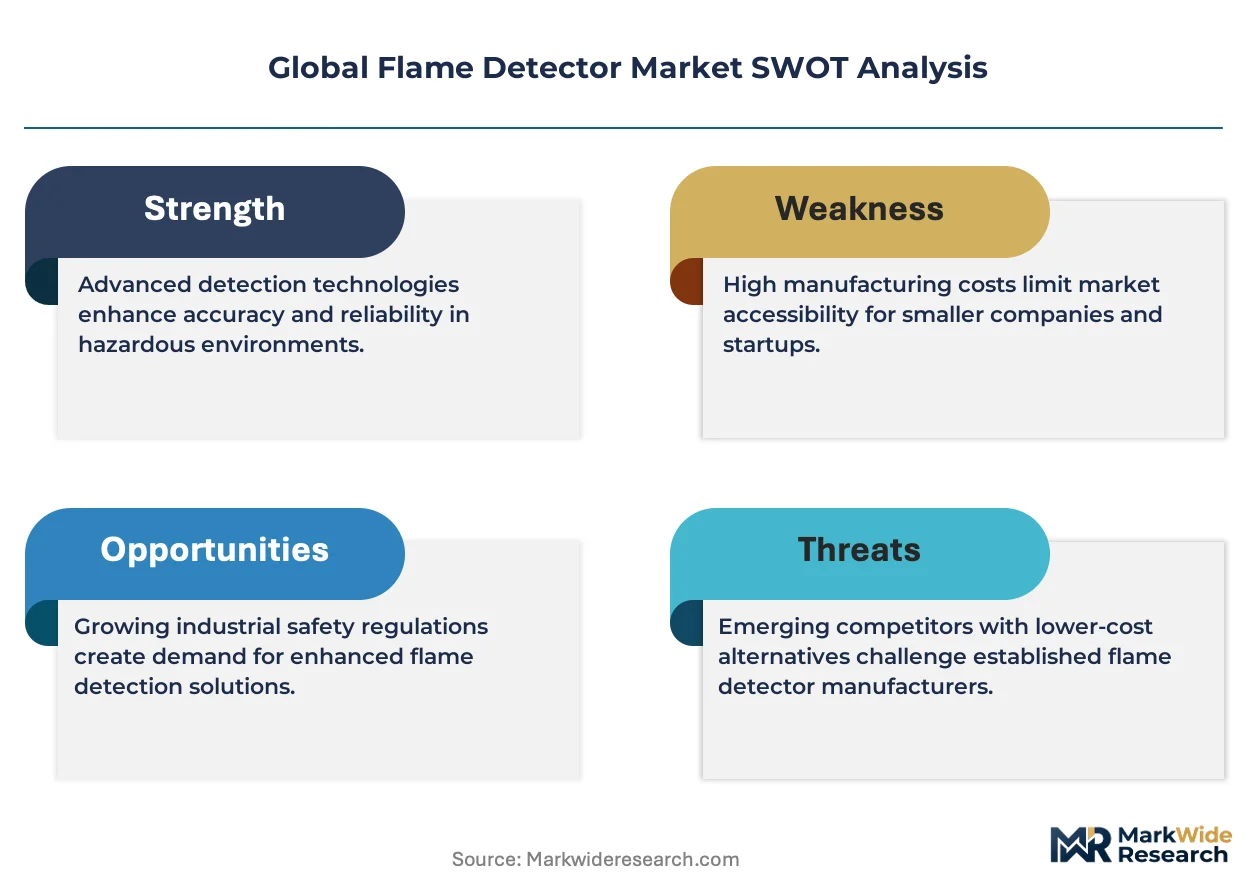
- Indium gallium arsenide supply concentration:Specialty infrared detector substrate production concentrates in limited East Asian foundries, creating input cost volatility for sensor manufacturers.
- Solar radiation interference in UV-only systems:Single-band ultraviolet detectors face technical disqualification from outdoor hydrocarbon applications, constraining addressable demand.
- Calibration traceability mandates:China's SAMR GB standards impose recurring compliance burdens that extend sales cycles and elevate total cost of ownership.
Strategic Opportunities
- Carbon capture facility greenfield:Emerging CO2 compression and sequestration sites require flame detection for supercritical process streams, opening application white space outside traditional hydrocarbon processing.
- Wireless sensor integration:Converging IIoT connectivity with optical flame detection enables remote monitoring architectures that bypass legacy cable infrastructure costs.
- Data center battery storage:Lithium-ion thermal runaway protection is emerging as a non-traditional end-use for infrared flame detection in grid-scale energy storage installations.
Industry Challenges
- SIL 3 functional safety engineering talent:Certified systems architects capable of IEC 61508-compliant hardware and software development remain scarce relative to project pipeline demand.
- Legacy control system integration:Brownfield petrochemical sites require protocol translation layers to connect modern digital flame detectors to analog-era distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flame Detector Market |
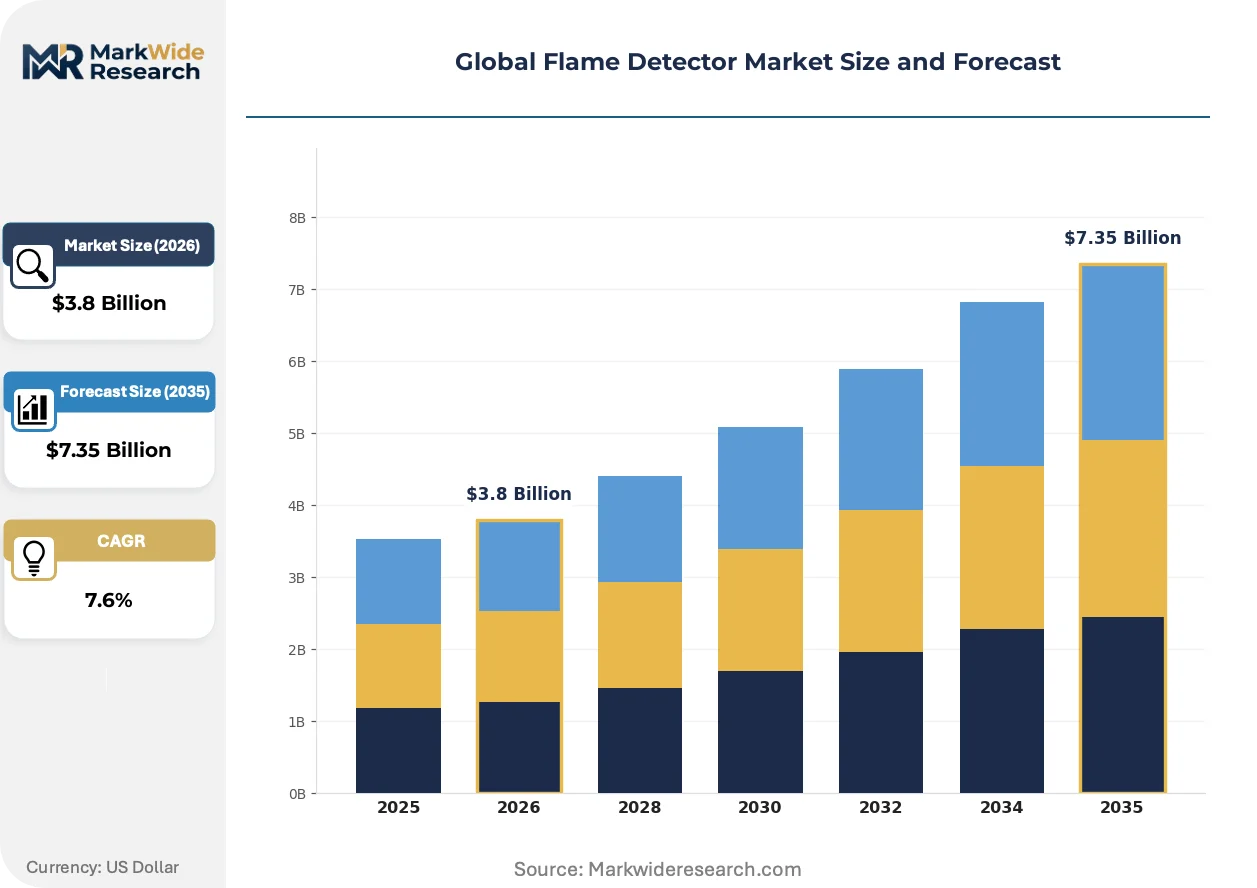
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Detectors, Ultraviolet Detectors, Combination Detectors, Visual Detectors Installation Type: Wall Mounted, Ceiling Mounted, Portable, Fixed End User: Oil & Gas, Manufacturing, Automotive, Aerospace Application Area: Industrial Facilities, Commercial Buildings, Marine, Mining |
| Companies Covered | Honeywell International, Johnson Controls, Siemens, Halma plc, Emerson Electric Co., MSA Safety, Teledyne Technologies, Robert Bosch, Hochiki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flame Detector Market Emerging Trajectories
Sensor fusion architectures and edge-computing analytics are redefining flame detection performance benchmarks, while regulatory harmonization efforts create competitive moats around certified suppliers.
Multi-spectrum infrared detection is absorbing market share from legacy ultraviolet systems by combining 4.35-micrometer CO2 resonance sensing with hydrocarbon-specific spectral signatures. Offshore platform operators and arid-region refineries are adopting these units fastest, prioritizing immunity to solar radiation and sandstorm particulate interference over hardware cost minimization.
REACH chemical registration requirements in Europe are forcing reformulation of optical coating materials used in flame detector lenses and windows. Manufacturers must substitute legacy fluoropolymer treatments with compliant alternatives, compressing margins on entry-tier product lines while certified suppliers capture specification-driven premiums in German utility and Rhine petrochemical contracts.
Specification engineers at major oil and gas operators are consolidating vendor lists around integrated fire and gas safety platforms. Bundled detection, suppression, and control systems are displacing point-product procurement, favoring suppliers with in-house production across sensor, controller, and actuator categories. This concentration is most visible in Middle Eastern national oil company tender processes, where single-source accountability clauses now dominate technical evaluation criteria.
Global Flame Detector Market Segmentation
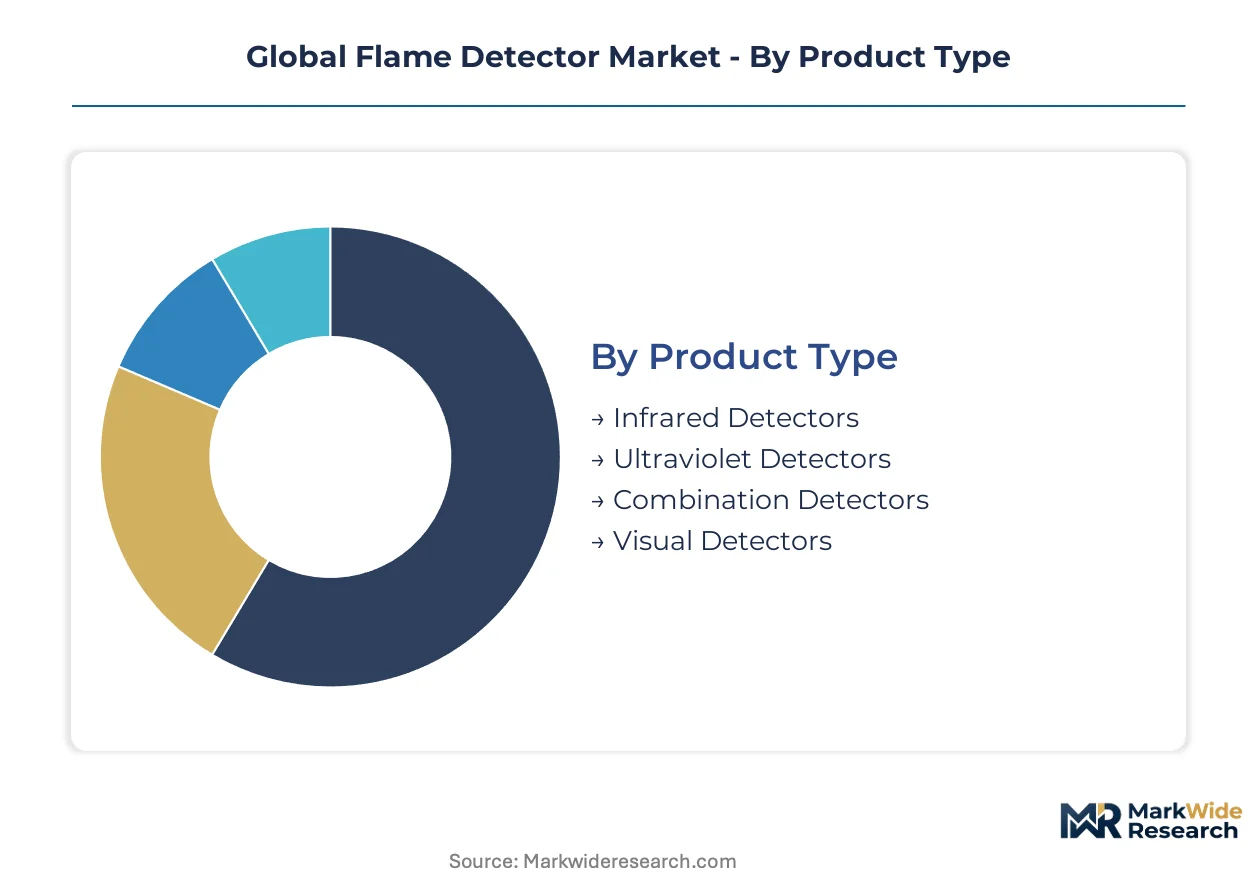
Flame detector procurement hinges on matching spectral detection capabilities to environmental hazards, with certification requirements varying sharply across explosive atmosphere zones and industrial verticals. Specification engineers weight SIL ratings, ATEX zones, and optical immunity when segmenting vendor shortlists.
Product Type:
Certification burdens concentrate in multi-spectrum architectures requiring IEC 61508 SIL 2 or SIL 3 validation, while single-band systems face narrowing approval pathways under tightened EU explosive atmosphere directives.
- Infrared Detectors:These sensors target the 4.35-micrometer CO2 resonance band with immunity to solar radiation and sandstorm interference. Arid-region refineries in Saudi Arabia and UAE specify these units for outdoor hydrocarbon processing, driven by false-alarm reduction mandates in national oil company tender protocols.
- Combination Detectors:UV-IR fusion architectures cross-validate flame signatures across ultraviolet and infrared spectra to eliminate nuisance alarms. German petrochemical complexes along the Rhine prioritize these units for high-value process units where unplanned shutdowns incur severe economic penalties.
- Ultraviolet Detectors:Single-band 185-260 nanometer sensors suit indoor applications with controlled lighting.
- Visual Detectors:CCTV-based flame recognition systems supplement optical detection in perimeter security roles.
Infrared Detectors sits at the top of the volume ranking, with Combination Detectors climbing the fastest.
Installation Type:
Deployment architecture determines cabling costs, maintenance access, and integration complexity with legacy distributed control systems.
- Fixed:Hardwired permanent installations dominate greenfield refinery and LNG terminal construction. Middle Eastern process safety budgets at new export facilities specify fixed units with SIL 3-rated safety instrumented systems, reflecting mandatory blowout prevention protocols.
- Portable:Battery-operated units serve turnaround maintenance and temporary hot-work permits. US OSHA 29 CFR 1910 process safety management inspections drive rental demand at Texas and Louisiana chemical complexes during unit outages.
- Wall Mounted:Vertical surface deployment suits perimeter monitoring and equipment shelter protection.
- Ceiling Mounted:Overhead installation addresses pooling vapor detection in enclosed process areas.
Fixed captures the largest installed base, with Portable gaining share fastest in maintenance-contract rental channels.
End User:
Vertical-specific hazard profiles dictate spectral selection, with hydrocarbon processing commanding the most stringent functional safety requirements.
- Oil & Gas:Upstream, midstream, and downstream operations require flame detection across drilling platforms, pipelines, and refining units. SAMR GB standards in China mandate calibration traceability for chemical plant licensing, extending sales cycles but locking in premium supplier relationships.
- Manufacturing:Chemical, pharmaceutical, and food processing plants deploy detectors for solvent handling and thermal process protection. REACH chemical registration in Europe forces optical coating reformulation, compressing margins on entry-tier products while certified suppliers capture specification premiums.
- Automotive:Paint shop solvent detection and battery thermal runaway protection represent emerging applications.
- Aerospace:Hangar fueling operations and engine test facilities require specialized high-speed detection.
Oil & Gas dominates revenue concentration, with Manufacturing expanding most quickly through carbon capture and hydrogen processing adjacencies.
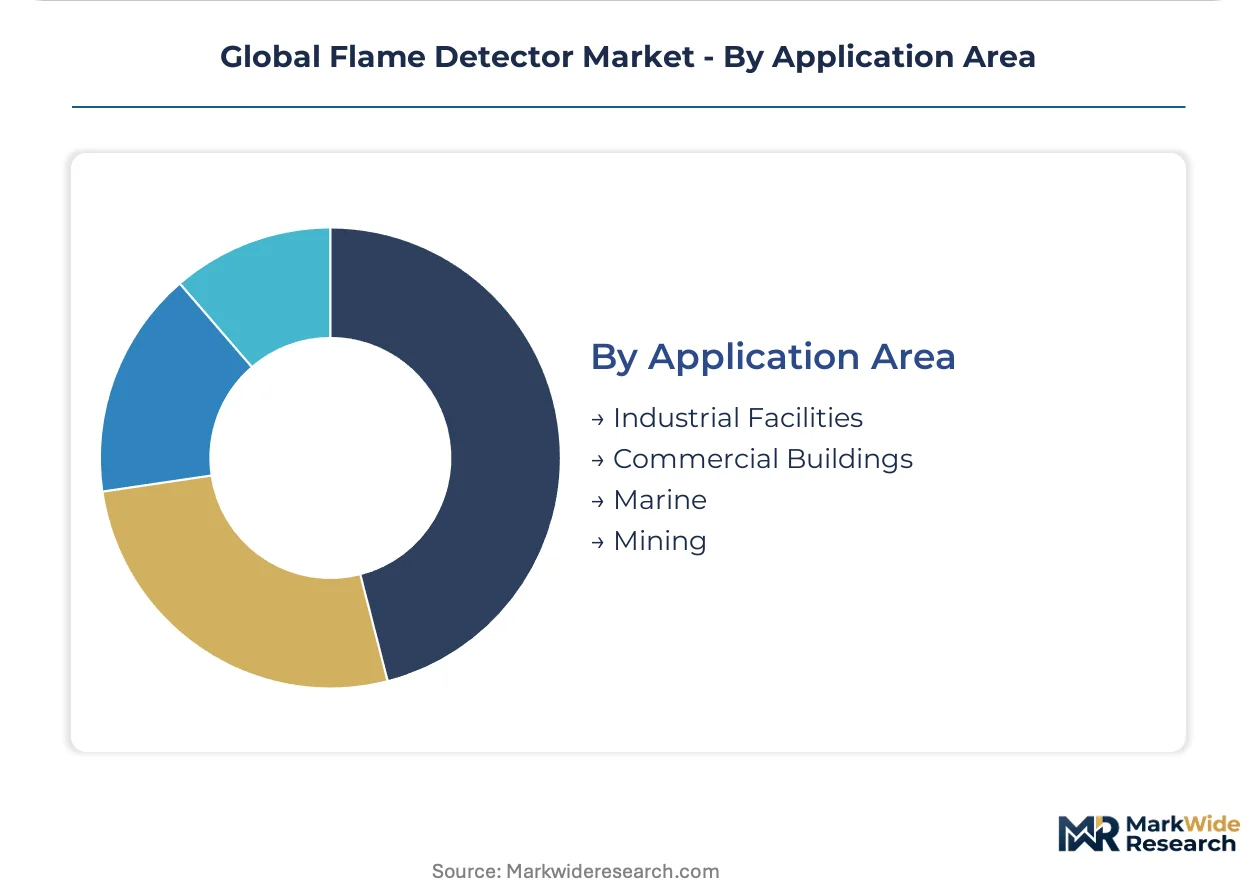
Application Area:
Environmental exposure severity separates indoor commercial deployments from heavy-industrial specifications requiring marine-grade enclosures and mining-dust sealing.
- Industrial Facilities:Petrochemical complexes, power generation, and heavy manufacturing represent the core demand pool. IEC 61508 edition divergence between national adoptions complicates multi-region certification for suppliers targeting German utility and Rhine chemical contracts simultaneously.
- Marine:Offshore platforms and LNG carriers require explosion-proof housings with salt-spray corrosion resistance. North Sea and Gulf of Mexico operators specify these units fastest, prioritizing equipment reliability in remote maintenance environments.
- Commercial Buildings:Warehouses, data centers, and battery storage facilities adopt infrared detection for lithium-ion thermal runaway protection.
- Mining:Underground coal and metal operations face combustible dust atmospheres requiring specialized sensor sealing.
Industrial Facilities holds the deepest specification requirements, with Marine showing steepest expansion trajectory in floating LNG and offshore wind service vessel markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional safety engineering talent concentrates in Germany's industrial belt and the US Gulf Coast, anchoring specification authority for flame detection procurement in petrochemical and utility verticals.
United States
OSHA 29 CFR 1910 process safety management mandates drive procurement at Texas and Louisiana chemical complexes. The EPA coordinates with state regulators on refinery flare monitoring requirements. Houston anchors the deepest specification engineering pool for SIL-rated safety instrumented systems.
Germany
TÜV Rheinland-certified manufacturing lines sustain premium positioning for ATEX-compliant flame detectors. The EU Machinery Directive enforces CE-marked conformity for fire safety components placed on the European market. Petrochemical complexes along the Rhine prioritize combination UV-IR units for high-value process units.
China
SAMR GB standards mandate flame detector calibration traceability for chemical plant licensing. The Ministry of Emergency Management tightens process safety enforcement at coal-to-chemical facilities. Yangtze River Delta refineries modernize fire protection systems with multi-spectrum infrared architectures.
Saudi Arabia
National oil company tender protocols prioritize false-alarm reduction mandates for outdoor hydrocarbon processing. The Saudi Standards, Metrology and Quality Organization aligns explosive atmosphere certification with EU ATEX frameworks. Jubail Industrial City hosts expanding procurement windows at new refinery and LNG export terminals.
United Arab Emirates
Process safety budgets widen at Abu Dhabi National Oil Company downstream expansion projects. The Emirates Authority for Standardization and Metrology enforces product conformity for fire safety equipment. Ruwais refinery complex specifications concentrate demand for SIL 3-rated flame detection systems.
Global Flame Detector Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-tiered market segments. The vendor base stratifies around three structural archetypes: diversified industrial technology groups with integrated fire and gas platforms, pure-play safety equipment specialists with deep SIL engineering capabilities, and component-focused sensor manufacturers supplying upstream detection modules. Competitive moves concentrate on strategic partnerships for IIoT connectivity integration and portfolio diversification into adjacent gas detection and suppression systems.
Among diversified industrial technology groups, Honeywell International and Siemens exemplify the integrated platform approach, anchoring specification authority through bundled detection, suppression, and control system offerings. Johnson Controls occupies a position within the fire safety specialist tier, representing the pure-play archetype with concentrated expertise in multi-spectrum infrared sensor architectures.
| Leading Market Players |
|---|
| Honeywell International |
| Johnson Controls |
| Siemens |
| Halma plc |
| Emerson Electric Co. |
| MSA Safety |
| Teledyne Technologies |
| Robert Bosch |
| Hochiki |
| Others |
Supply Flow & Price Mechanics
Procurement consolidation around bundled fire and gas safety platforms is forcing component suppliers to absorb integration costs or cede specification authority to integrated platform vendors, compressing margins on unbundled sensor modules while amplifying pricing power for certified system architects. This dynamic concentrates value capture in German and Middle Eastern tender processes where single-source accountability clauses dominate technical evaluation criteria.
Pricing Analysis
The bundled-versus-unbundled service split separates three distinct pricing tiers: integrated platform providers command premium positioning through SIL 3-rated safety instrumented system bundling, pure-play sensor manufacturers compete on per-unit transactional pricing for replacement modules, and rental-service operators price portable units through project-based maintenance contracts. Price differentiation rests on IEC 61508 certification grade and after-sales calibration traceability service levels. Pricing pressure stems from REACH-mandated optical coating reformulation, which compresses margins on entry-tier product lines. Manufacturing and chemical processing verticals exhibit highest price sensitivity due to procurement volume scale, while oil and gas national oil companies prioritize false-alarm reduction over hardware cost minimization.
Supply Chain Analysis
Indium gallium arsenide substrate supply rests on concentrated East Asian specialty foundries, with Japan, South Korea, and Taiwan anchoring wafer production for multi-spectrum infrared detector fabrication. Optical coating materials draw from German and US specialty chemical producers, while explosion-proof housing machining concentrates in Chinese and German metalworking clusters. Single-source vulnerability in indium gallium arsenide wafer supply creates input cost volatility for sensor manufacturers. Distribution runs through authorized safety system integrators serving petrochemical complexes, with direct OEM relationships dominating national oil company procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where IEC 61508 edition divergence between national adoptions perpetually refreshes certification barriers and sustains demand for engineering-intensive validation services.
For Market Incumbents: Lock in specification authority by deepening captive supply of multi-spectrum infrared sensor modules and securing TÜV Rheinland-certified manufacturing line expansion. Threat substitution from wireless IIoT sensor architectures demands proactive protocol integration investments. Channel control through exclusive safety system integrator partnerships defends against pure-play sensor commoditization. For New Entrants and Emerging Players: Fire and gas safety system integrators represent the most accessible channel partners for penetrating carbon capture facility greenfield specifications. White-space targets include lithium-ion thermal runaway protection in grid-scale battery storage installations and supercritical CO2 compression flame detection. A go-to-market angle anchored in SAMR GB standards compliance accelerates licensing traction at Yangtze River Delta refineries. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play safety equipment specialists possessing deep SIL engineering capabilities and established notified-body relationships. Long-term viability hinges on regulatory harmonization complexity persisting across IEC 61508 national adoption cycles. Acquisition targets should demonstrate embedded specification authority in German utility or Rhine petrochemical procurement channels. The inflection indicator to monitor is wireless sensor integration adoption rates in Middle Eastern national oil company tender protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Spectrum Sensor Platform Launch | UV-IR fusion architectures penetrate German petrochemical complexes seeking false-alarm elimination. |
| Notified-Body Certification Investment | TÜV Rheinland validation sustains premium positioning across ATEX-mandated European installations. |
| Wireless IIoT Integration Partnership | Remote monitoring architectures bypass legacy cable infrastructure at Saudi refinery expansions. |
| Backward Integration into InGaAs Substrates | Captive wafer supply mitigates East Asian foundry concentration risk for infrared detector production. |
| Carbon Capture Application Development | Supercritical CO2 stream detection opens specification white-space outside traditional hydrocarbon processing. |
Methodological Framework
Bottom-up oil and gas facility modeling reconciled against top-down sensor manufacturer production tracking forms the analytical core of this study. Primary interviews with process safety managers at petrochemical complexes, fire protection engineers at EPC contractors, procurement leads at national oil companies, and certification specialists at notified bodies combined with secondary validation from IEC 61508 registration databases, ATEX certification records, SAMR GB standards filings, and SEC 10-K disclosures from diversified industrial technology groups. Triangulation between demand-side procurement pipeline analysis and supply-side capacity announcements ensures dimensional consistency.
Input-output matrix framing connects flame detector unit shipments to end-use facility construction and modernization cycles across the projection horizon. Segmentation dimensions modeled include product type, installation architecture, end-use vertical, application environment severity, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to verified base-year estimates, with cross-checks against safety instrumented system investment disclosures and process safety budget allocations. Industry-specific forecast inputs incorporate national oil company tender pipeline tracking and carbon capture facility development database monitoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IEC 61508 edition revision timing, indium gallium arsenide supply disruption events, and divergence between EU ATEX and emerging market explosive atmosphere certification alignment. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution elasticity between detection technologies. A small set of named triggers—including wireless sensor standardization breakthroughs and REACH chemical registration scope expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Fire Suppression Equipment Market
Fire Safety & Protection
Fire Door Market
Fire Safety & Protection
Global Fixed Firefighting Misting System Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Global Flame Arrestors Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market