
 Global Fire Extinguisher Cylinders Market | 2026-2036
Global Fire Extinguisher Cylinders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fire Extinguisher Cylinders Market Analysis
China's Yangtze River Delta manufacturing corridor is rewriting regional supply dynamics for high-pressure containment vessels. Worthington Industries leverages its North American steel forming expertise to sustain long-term OEM contracts with multinational safety equipment brands. Luxfer Group anchors European demand through specialized aluminum alloy cylinder production for aviation and marine applications. Everest Kanto Cylinders dominates South Asian markets with cost-optimized steel designs tailored to tropical corrosion environments.
Fire extinguisher cylinders are seamless or welded pressure vessels engineered to withstand internal pressures between 8.7 and 27.6 bar depending on agent type, manufactured through deep drawing, spinning, or filament winding processes to store and discharge suppressant media on demand. Steel variants occupy the bulk of industrial procurement due to proven durability and lower unit economics, while aluminum and composite alternatives capture premium segments where weight reduction determines deployability. The stored-pressure configuration leads volume across commercial and residential installations, whereas water mist systems represent the fastest-expanding product category driven by clean-agent regulatory preferences in data center and heritage building applications.
NFPA 10 standards in the United States, EN 3 certification requirements enforced by EU member state notified bodies, and India's BIS IS 15683 framework collectively dictate cylinder wall thickness, hydrostatic testing protocols, and agent compatibility specifications that determine market access. China's GB 4351 national standards and NMPA fire product conformity assessment create additional compliance layers for imported equipment. Stakeholders must monitor evolving PFAS restrictions under REACH and state-level clean-agent mandates that will force material and suppressant reformulation across multiple certification regimes.
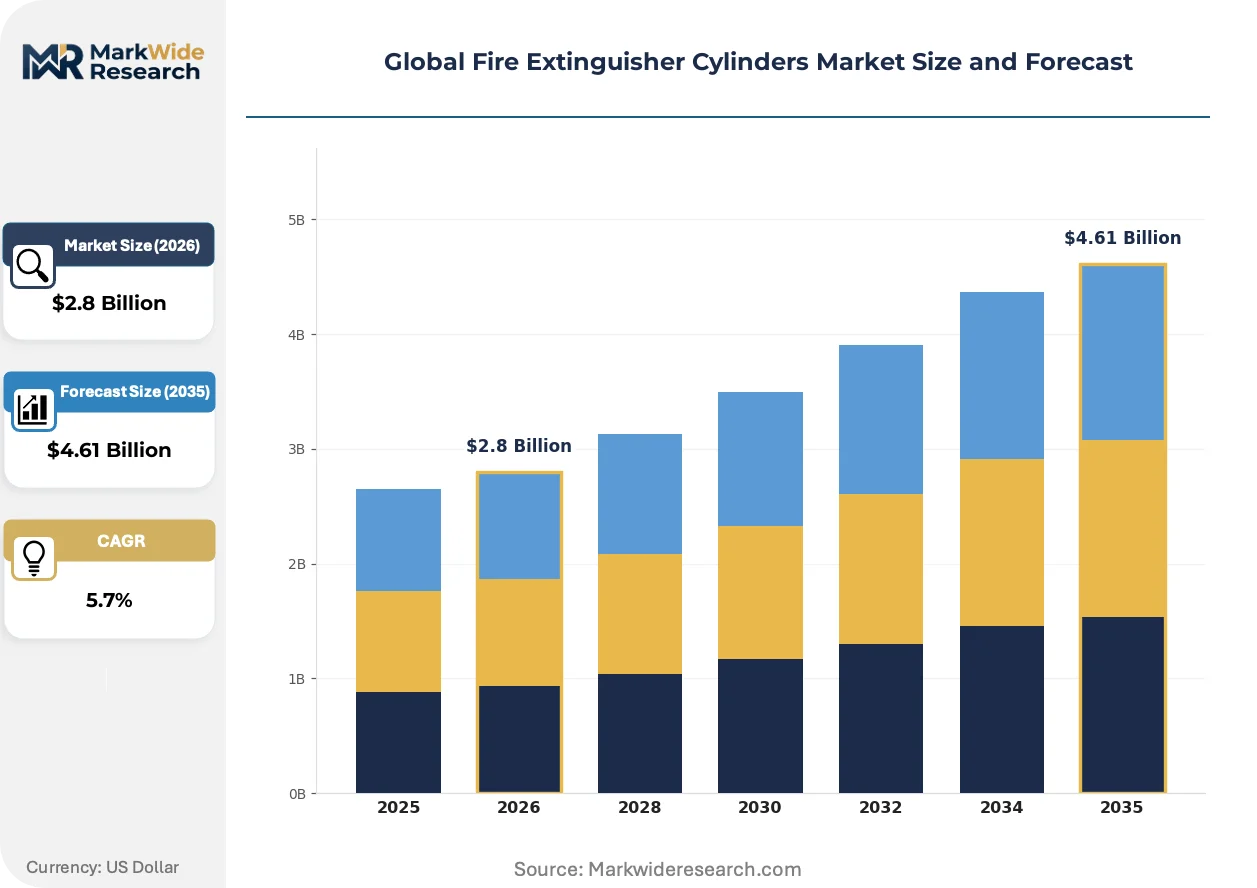
Market Dynamics
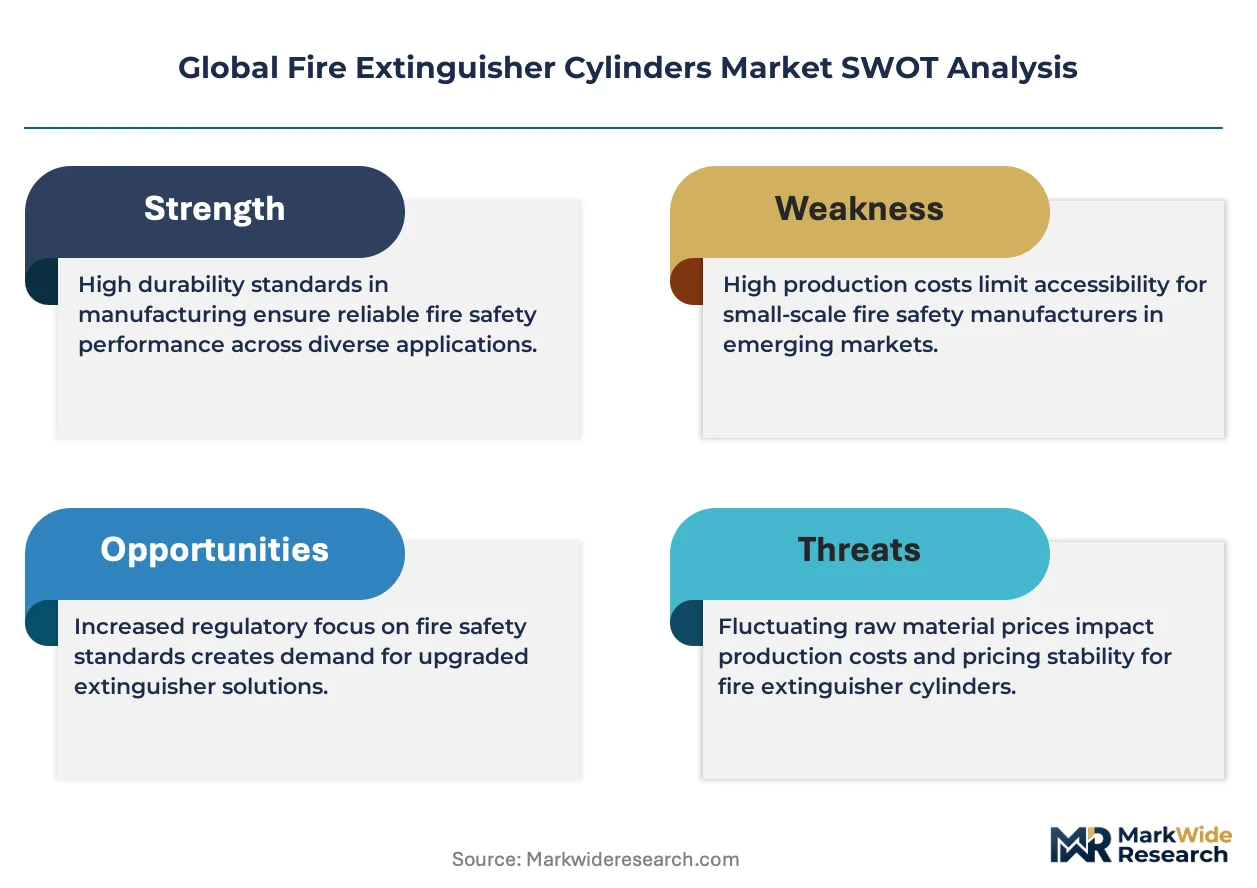
Stringent hydrostatic testing mandates across multiple certification regimes are forcing cylinder manufacturers to retool production lines and absorb elevated compliance costs, compressing margins for non-specialized producers.
Growth Catalysts
- NFPA 10 Retrofit Mandates:US commercial building codes are accelerating replacement cycles for aging steel cylinders in high-occupancy structures.
- Data Center Water Mist Conversion:Clean-agent preferences in hyperscale facilities are driving premium aluminum and composite cylinder procurement.
- India BIS Localization:Pressure equipment rules are redirecting procurement toward domestic manufacturing capacity.
Market Restraints
- Steel Price Volatility:Hot-rolled coil fluctuations directly impact unit economics for welded cylinder producers.
- REACH PFAS Restrictions:Clean-agent reformulation timelines are creating certification gaps for existing cylinder inventories.
- Composite Material Cost Premium:Filament-wound carbon fiber cylinders remain priced above steel alternatives for industrial buyers.
Strategic Opportunities
- Indonesia Industrial Expansion:Manufacturing zone development is creating first-mover positioning for localized cylinder assembly.
- Aviation Lightweight Mandates:Aluminum alloy cylinders for aircraft galleys and cargo holds represent premium segment expansion.
- Marine IMO Compliance:SOLAS fire safety updates are driving fleet-wide cylinder replacement across commercial shipping.
Industry Challenges
- Hydrostatic Testing Technician Shortage:Certified pressure vessel inspectors are concentrated in legacy manufacturing regions.
- Multi-Jurisdiction Certification Lag:Simultaneous EN 3, GB 4351, and BIS approvals extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fire Extinguisher Cylinders Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stored Pressure, Water Mist, Foam, Powder Material: Steel, Aluminum, Composite, Plastic End User: Residential, Commercial, Industrial, Automotive Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Luxfer Group, Worthington Industries, Valpro, Everest Kanto Cylinders, Beijing Tianhai Industry, Faber Industries, CIMC ENRIC, Rama Cylinders, Quantum Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fire Extinguisher Cylinders Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reshape cylinder specification priorities across end-use verticals.
Filament-wound composite cylinders are hybridizing pressure containment architectures by embedding carbon fiber layers around aluminum liners. Data center operators and aviation maintenance teams are specifying these hybrids for weight-critical installations. The technology is hybridizing procurement criteria by merging performance metrics from both metallic and non-metallic vessel categories.
REACH PFAS restrictions are forcing suppressant chemistry reformulation across EU member states. Cylinder manufacturers must validate agent compatibility with new fluorine-free formulations before market release. Marine and heritage building applications are most affected, with notified bodies extending certification review periods.
Buyer consolidation among multinational safety equipment distributors is compressing supplier negotiation cycles. Regional cylinder producers are losing direct access to end-user specifications as procurement centralizes under integrated safety service contracts. This concentration is most visible in China's coastal manufacturing provinces where facility managers now contract bundled fire protection systems rather than discrete cylinder purchases.
Global Fire Extinguisher Cylinders Market Segmentation
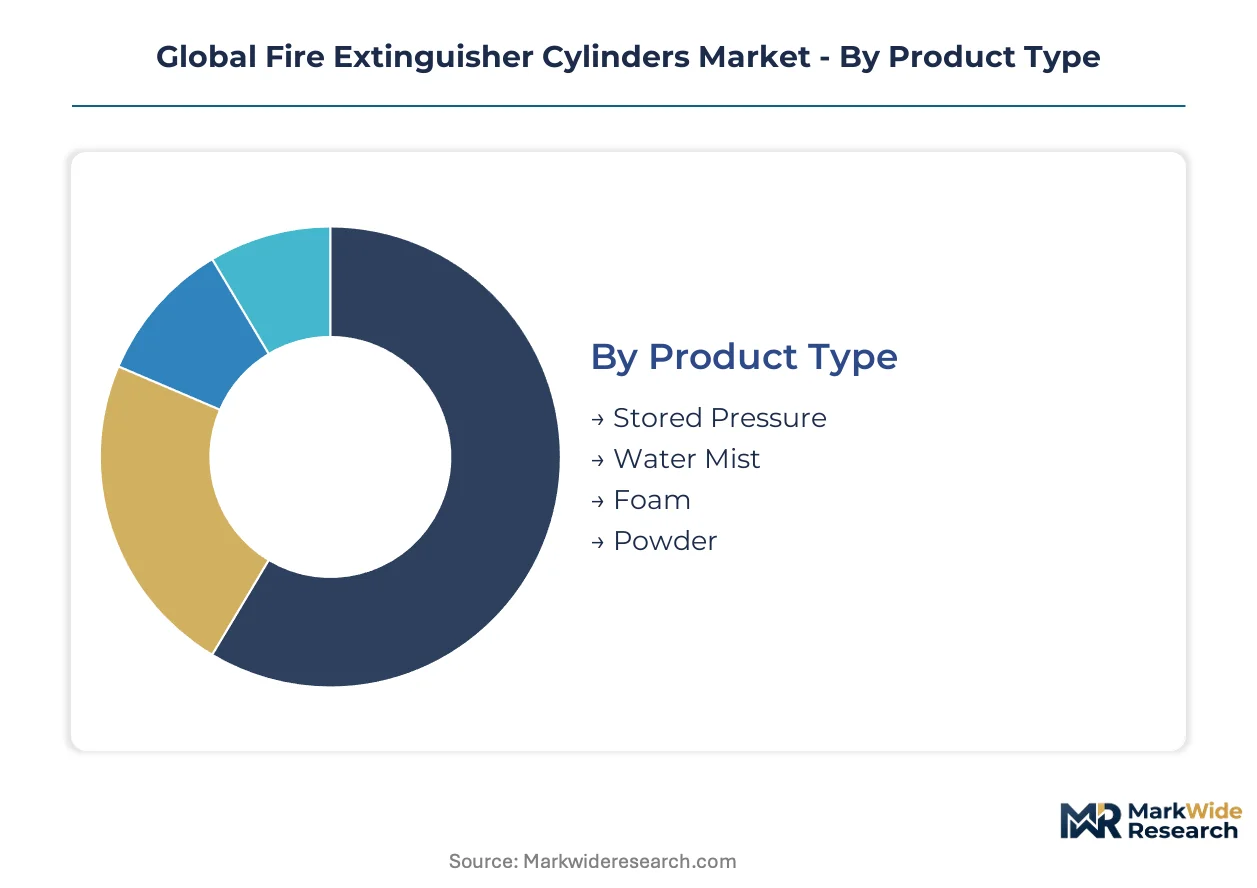
Fire extinguisher cylinder procurement patterns diverge sharply across pressure configurations, material specifications, and end-use environments. Certification requirements and weight constraints fragment demand into distinct technical tiers that reshape supplier positioning.
Product Type:
Mature stored-pressure systems anchor commercial procurement while emerging water mist technologies capture regulatory-driven retrofit cycles.
- Stored Pressure:Nitrogen-charged steel vessels dominate high-occupancy buildings under NFPA 10 replacement mandates. US commercial property managers source these for cost-predictable maintenance contracts in retail and hospitality infrastructure.
- Water Mist:Fine-droplet suppression systems require aluminum or composite cylinders rated for higher operating pressures. Data center operators in Singapore and Frankfurt specify these for clean-agent compliance without electrical equipment damage.
- Foam:AFFF-compatible cylinders face REACH PFAS reformulation timelines.
- Powder:ABC dry chemical systems retain dominance in Indian industrial corridors.
Stored Pressure retains volume leadership; Water Mist holds the steepest expansion curve.
Material:
Cost tiers separate commodity steel procurement from premium lightweight alternatives where transportability determines specification.
- Steel:Hot-rolled coil construction delivers proven hydrostatic durability for industrial fixed installations. Southeast Asian manufacturing zones favor welded steel variants under BIS and GB 4351 cost pressures.
- Aluminum:Seamless extruded alloys reduce weight by 40% for aviation galley and marine deck applications. European aviation maintenance providers specify Luxfer Group alloys under EASA continuing airworthiness programs.
- Composite:Filament-wound carbon fiber over aluminum liners commands 3x steel pricing.
- Plastic:Polymer-lined vessels serve limited residential and vehicle markets.
Steel commands absolute unit volume; Aluminum climbs fastest in premium mobility segments.
End User:
Customer type segmentation reflects divergent certification burdens and replacement cycle economics across built environments.
- Residential:Compact stored-pressure steel cylinders dominate single-family retrofits. Indian urban housing complexes drive procurement under amended National Building Code fire safety clauses.
- Commercial:Mixed-occupancy structures require multi-agent capability with centralized inspection protocols. German TÜV and US OSHA inspection regimes accelerate replacement demand in aging office stock.
- Industrial:Heavy-process facilities specify corrosion-resistant coatings for chemical exposure.
- Automotive:Vehicle integration demands compact lightweight designs.
Commercial installations generate the highest replacement frequency; Industrial contracts yield the longest procurement cycles.
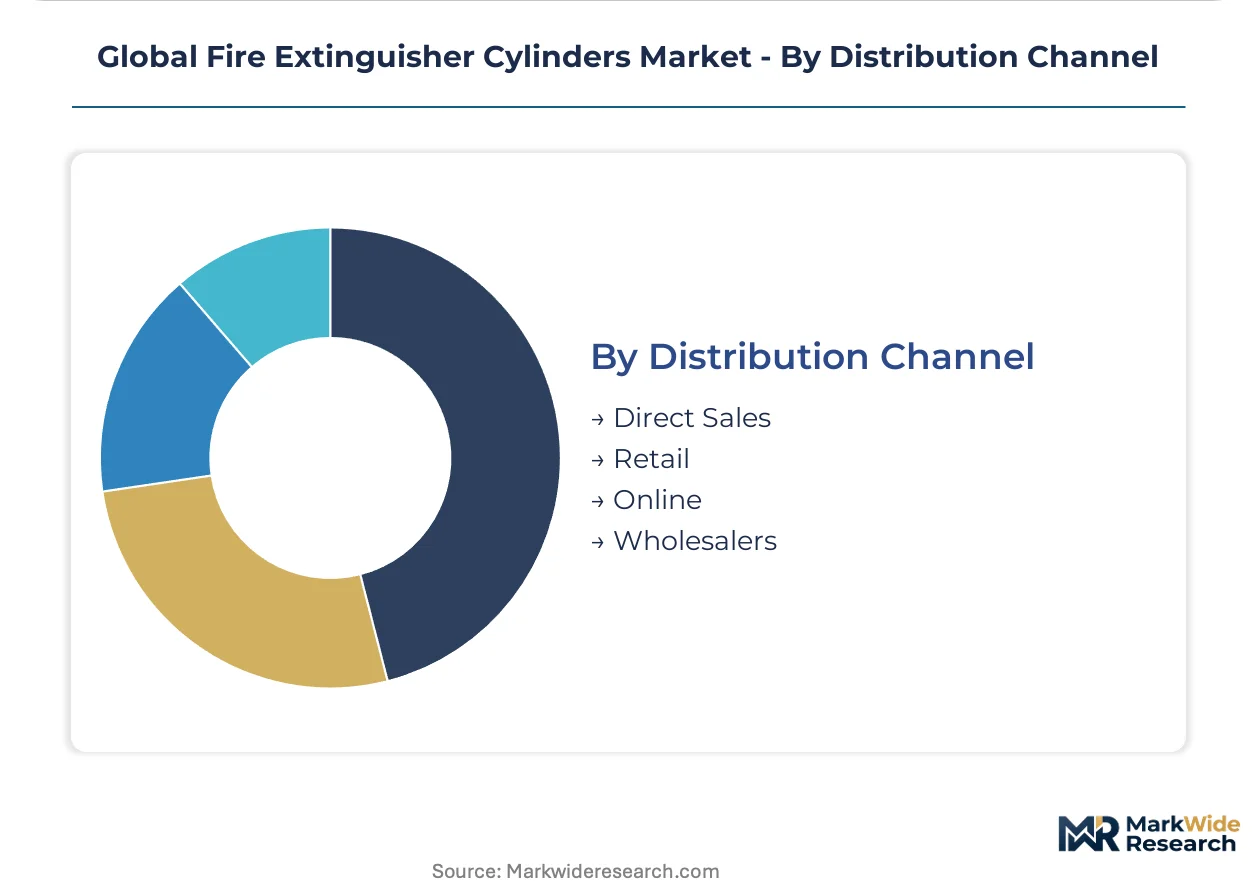
Distribution Channel:
Supply concentration shapes margin capture across direct OEM relationships versus fragmented retail access.
- Direct Sales:Multinational safety equipment distributors consolidate cylinder procurement under integrated service contracts. China's Yangtze River Delta facility managers now source through bundled fire protection agreements rather than discrete vessel purchases.
- Retail:Hardware and safety equipment stores serve residential and small commercial replacement demand.
- Online:E-commerce platforms penetrate price-sensitive replacement markets.
- Wholesalers:Regional distributors stock standardized steel cylinders for contractor fulfillment.
Direct Sales captures the largest contract value; Online channels gain share fastest in residential replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cylinder fabrication clusters concentrate in steel-producing regions with proximity to pressure equipment certification bodies. Manufacturing investments track enforcement intensity of NFPA, EN, and BIS hydrostatic testing mandates across industrial corridors.
United States
NFPA 10 retrofit mandates in high-occupancy commercial buildings accelerate steel cylinder replacement cycles. OSHA inspection protocols drive procurement centralization under integrated safety service contracts. Texas and Ohio manufacturing zones host deep-drawing capacity serving North American OEM demand.
China
GB 4351 national standards and NMPA conformity assessment create compliance layers for domestic and imported equipment. Yangtze River Delta facility managers source bundled fire protection systems rather than discrete cylinder purchases. Shanghai and Jiangsu province clusters dominate high-pressure vessel output for regional retrofit programs.
Germany
EN 3 certification requirements enforced by notified bodies dictate cylinder wall thickness and hydrostatic testing protocols. TÜV inspection regimes accelerate replacement demand in aging office and industrial stock. Bavaria and North Rhine-Westphalia anchor European aluminum alloy production for aviation applications.
India
BIS IS 15683 pressure equipment rules redirect procurement toward domestic manufacturing capacity. National Building Code amendments drive urban housing complex installations. Maharashtra and Gujarat industrial corridors expand local steel forming capacity under import substitution pressure.
Indonesia
Manufacturing zone development in Batam and Java creates first-mover positioning for localized cylinder assembly. Stricter industrial fire safety enforcement follows ASEAN regulatory harmonization trends. Domestic fabrication investments target cost-optimized welded steel variants for tropical corrosion environments.
Global Fire Extinguisher Cylinders Market Vendor Landscape
Integrated steel formers and specialized aluminum alloy producers split the market along weight-performance trade-offs. The structure tiers between volume-driven welded steel fabricators and premium seamless extrusion specialists. Two archetypes dominate: commodity-scale producers serving retrofit replacement cycles, and performance-tier suppliers capturing aviation and marine certification requirements. Competitive moves center on backward integration into hot-rolled coil supply and geographic licensing of hydrostatic testing protocols.
Among North American metal formers, Worthington Industries exemplifies the scale-driven archetype through long-term OEM contract structures. Luxfer Group anchors European premium positioning through specialized alloy production for weight-critical applications. Everest Kanto Cylinders occupies the cost-optimized tier serving South Asian tropical corrosion requirements. These three represent distinct strategic postures without overlapping segment focus.
| Leading Market Players |
|---|
| Luxfer Group |
| Worthington Industries |
| Valpro |
| Everest Kanto Cylinders |
| Beijing Tianhai Industry |
| Faber Industries |
| CIMC ENRIC |
| Rama Cylinders |
| Quantum Technologies |
| Others |
Supply Flow & Price Mechanics
Hot-rolled coil supply concentration in Chinese and Indian steel corridors determines where margin pools accumulate downstream, with integrated mills capturing value before cylinder fabricators face certification-driven cost absorption.
Pricing Analysis
NFPA 10 and EN 3 hydrostatic testing mandates dictate the pricing tier structure across the Global Fire Extinguisher Cylinders Market. Three-tier pricing separates aviation-grade aluminum alloys from commercial steel vessels and economy welded variants, with certification grade and volume scale as primary price differentiation drivers. Cost compression in steel-welded segments is intensifying because hot-rolled coil volatility passes through to non-integrated fabricators. Small commercial installers exhibit highest price sensitivity, while aviation maintenance providers show lowest sensitivity due to EASA continuing airworthiness requirements.
Supply Chain Analysis
Hot-rolled coil feedstock draws from integrated steel production in China, India, and the United States. Cylinder manufacturing sources aluminum billets from European extrusion specialists and carbon fiber from Japanese and South Korean suppliers. Single-source vulnerability concentrates in certified hydrostatic testing equipment, where German and Italian machinery providers dominate. Distribution runs through multinational safety equipment distributors consolidating procurement under integrated service contracts, bypassing fragmented regional fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Fire Extinguisher Cylinders Market sits in a cyclical recovery phase, with NFPA 10 retrofit mandates in aging US commercial stock driving replacement demand that will sustain through the mid-term.
For Market Incumbents: Harden backward integration into hot-rolled coil supply to insulate margins from steel price volatility. Expand hydrostatic testing certification capacity in India's Maharashtra and Gujarat corridors before BIS localization requirements tighten. Composite cylinder specialists threaten premium positioning; defend through exclusive aluminum alloy supply agreements with aviation OEMs. For New Entrants and Emerging Players: Pursue localized welded steel assembly in Indonesia's Batam and Java manufacturing zones, where ASEAN regulatory harmonization creates first-mover positioning before incumbent distributors consolidate. Target cost-optimized corrosion-resistant coatings for tropical industrial environments. Establish direct relationships with facility managers in China's Yangtze River Delta seeking bundled fire protection procurement. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap cylinder fabricators with captive hydrostatic testing protocols and established EN 3 or BIS certification pathways. Long-term viability hinges on positioning for clean-agent chemistry transitions as REACH PFAS restrictions force suppressant reformulation. Monitor aviation lightweight mandate adoption rates and marine SOLAS fleet replacement schedules as inflection indicators for premium segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Feedstock | Captive hot-rolled coil supply insulates margins from commodity volatility affecting welded cylinder producers. |
| Hydrostatic Testing Certification Investment | BIS and EN 3 testing capacity expansion accelerates product launch timelines in India and European markets. |
| Composite Cylinder Technology Licensing | Filament-wound carbon fiber over aluminum liner expertise unlocks aviation and data center premium segments. |
| Localized Assembly Joint Venture | Indonesian manufacturing zone partnerships capture ASEAN regulatory harmonization-driven procurement shifts. |
| Clean-Agent Compatibility Validation | PFAS-free suppressant testing protocols ensure cylinder-agent compatibility under evolving REACH restrictions. |
Methodological Framework
Operator-level perspectives from plant engineers at cylinder fabrication facilities, procurement leads at multinational safety equipment distributors, hydrostatic testing certification auditors, and facility managers in high-occupancy commercial buildings anchored the qualitative base. Primary interview insights combined with secondary validation from customs/trade databases, NFPA and BIS regulatory filings, SEC 10-K disclosures from integrated steel producers, and EASA continuing airworthiness documentation. Bottom-up unit economics modeling and top-down regional demand aggregation provided triangulation across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning pressure configuration, material specification, end-use environment, and regional regulatory cluster. CAGRs derived from replacement cycle analysis, retrofit mandate enforcement timelines, and industrial capacity expansion trajectories. Forecast inputs incorporated steel price volatility assumptions and clean-agent chemistry transition schedules.
Sensitivities concentrate around hot-rolled coil price trajectories, REACH PFAS restriction implementation timelines, and aviation lightweight mandate adoption rates. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity between material grades. Quarterly review of BIS certification backlog data, EASA airworthiness directive issuance, and ASEAN manufacturing zone fire safety enforcement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
China Thermal Protector Market
Fire Safety & Protection
Fire Suppression Equipment Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Africa Fire Suppression Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
US Fire Alarm and Detection Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
Global Fixed Firefighting Misting System Market
Fire Safety & Protection
GCC Firefighting Foam Market