
 Laser Smoke Detector Market | 2026-2036
Laser Smoke Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Smoke Detector Market Foresight
Modular detector configurations is expanding buyer choice across the laser smoke detector landscape. VESDA by Xtralis leverages its aspirating technology leadership to dominate high-sensitivity installations in critical infrastructure. Honeywell International Inc. sustains broad channel control through its integrated building management platforms. Siemens AG anchors European commercial demand with manufacturing scale across its fire safety division.
A laser smoke detector employs a focused light source and photoelectric sensor to detect particulate matter at concentrations as low as 0.005% obscuration per foot, providing early warning capability for slow-burning or smoldering fires. Its primary commercial purpose centers on protecting high-value assets and enabling evacuation in environments where conventional detectors respond too slowly. Optical detectors and multi-criteria detectors occupy the premium tier where sensitivity thresholds differentiate product positioning. Networked installations are capturing margin pools as building automation systems require centralized monitoring and predictive maintenance integration.
Underwriters Laboratories and NFPA standards in the United States, combined with CE marking and the EU Construction Products Regulation, establish baseline performance thresholds that shape product design and market access. China's GB standards and mandatory CCC certification create parallel compliance pathways for manufacturers seeking entry. Stakeholders must monitor evolving interoperability protocols between fire safety networks and smart building platforms as procurement criteria shift toward system-level integration.
Market Dynamics
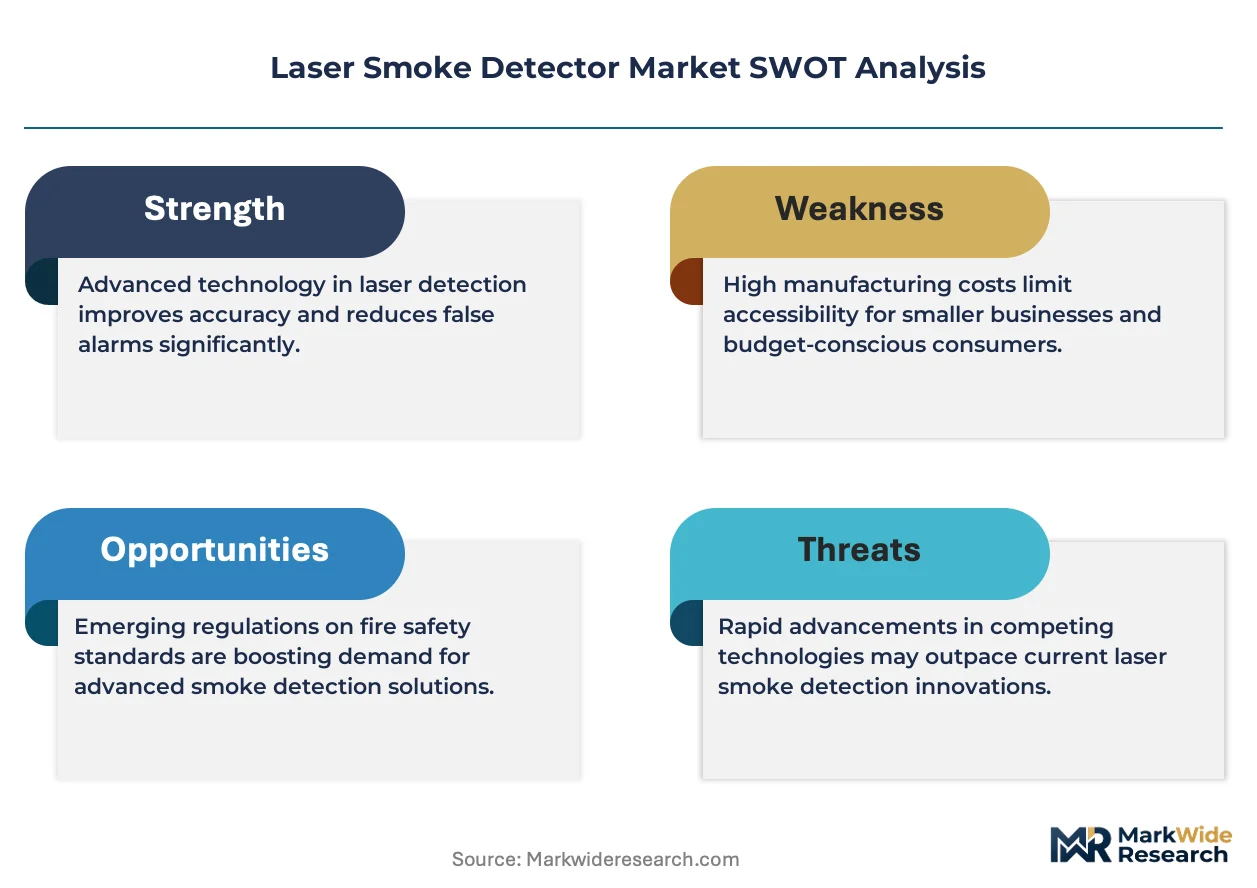
The laser smoke detector market is experiencing structural pressure from building automation convergence, as facility managers demand networked detector arrays that integrate with centralized monitoring platforms rather than standalone units.
Growth Catalysts
- EU F-Gas Regulation:Tightened safety equipment certification requirements under MDR frameworks are accelerating replacement cycles in European commercial real estate.
- Data center infrastructure:Hyperscale facility operators in Germany, the United States, and China are retrofitting aging buildings with high-sensitivity detector arrays to protect compute assets.
- Photoelectric sensitivity thresholds:Detection capabilities at 0.005% obscuration per foot are expanding addressable applications into slow-burning fire environments previously unserved.
Market Restraints
- Semiconductor input volatility:Photoelectric sensor component costs fluctuate with foundry capacity constraints, compressing margins on mid-tier detector configurations.
- Supply concentration in East Asian optics:Laser diode manufacturing clusters in specific manufacturing zones create single-source vulnerability for detector OEMs.
- Legacy installation base:Conventional ionization detectors in existing commercial buildings represent a substitution threat through incremental upgrade delays.
Strategic Opportunities
- Predictive maintenance integration:Building automation systems requiring centralized monitoring are creating white space for detector-embedded diagnostic modules.
- China's GB standards evolution:Mandatory CCC certification pathways are opening procurement channels for certified networked arrays in retrofit projects.
- Multi-criteria convergence:Integration of thermal and CO sensing with laser particulate detection is enabling premium positioning in critical infrastructure segments.
Industry Challenges
- Interoperability protocol fragmentation:Fire safety networks face integration complexity with proprietary smart building platforms from competing automation vendors.
- Certification timeline compression:Parallel UL, NFPA, CE marking, and CCC approval processes extend product launch cycles by 8-14 months for multi-region deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Smoke Detector Market |
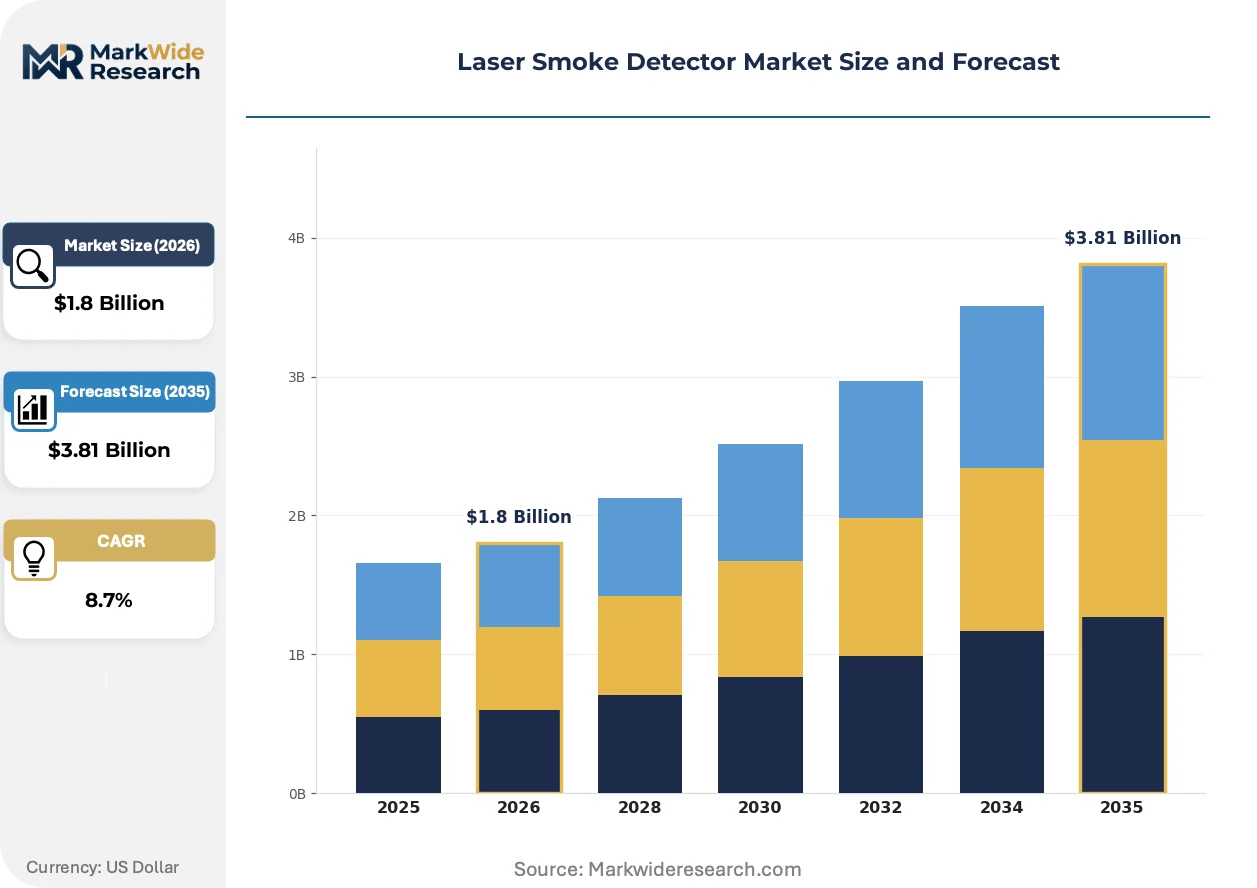
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Detectors, Ionization Detectors, Multi-Criteria Detectors, Thermal Detectors End User: Residential, Commercial, Industrial, Government Installation Type: Standalone, Networked, Integrated, Portable Signal Type: Analog, Digital, Visual, Audible |
| Companies Covered | Siemens AG, VESDA (by Xtralis), Honeywell International Inc., Panasonic Corporation, Fike Corporation, Johnson Controls International, ABB Ltd., Samsung Electronics Co., Ltd., Hochiki Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Smoke Detector Market Shifts & Advancements
Detector architecture is fragmenting into configurable subsystems, enabling buyers to match sensitivity specifications to asset protection requirements rather than accepting standardized performance tiers.
Multi-sensor fusion is modularizing around application-specific detection modules. Logistics facility operators in automated warehouses are deploying configurable arrays that combine laser particulate sensing with thermal imaging. This architecture is modularizing procurement decisions, allowing facility managers to upgrade individual sensing layers without full system replacement.
REACH chemical restrictions and EU Construction Products Regulation amendments are tightening material composition standards for detector housings and optical chambers. Manufacturers serving European commercial markets are reformulating polymer formulations to eliminate restricted flame retardants. Data center developers in Germany and the Netherlands are prioritizing certified low-emission detector housings in sustainability scoring frameworks.
Service contract unbundling is disrupting traditional detector procurement. Facility management firms are separating hardware acquisition from calibration and replacement services, compressing supplier margins on bundled offerings. This pattern is most visible in United States commercial real estate, where property management platforms are aggregating detector maintenance across multi-site portfolios and negotiating direct service relationships with regional calibration providers.
Laser Smoke Detector Market Segmentation
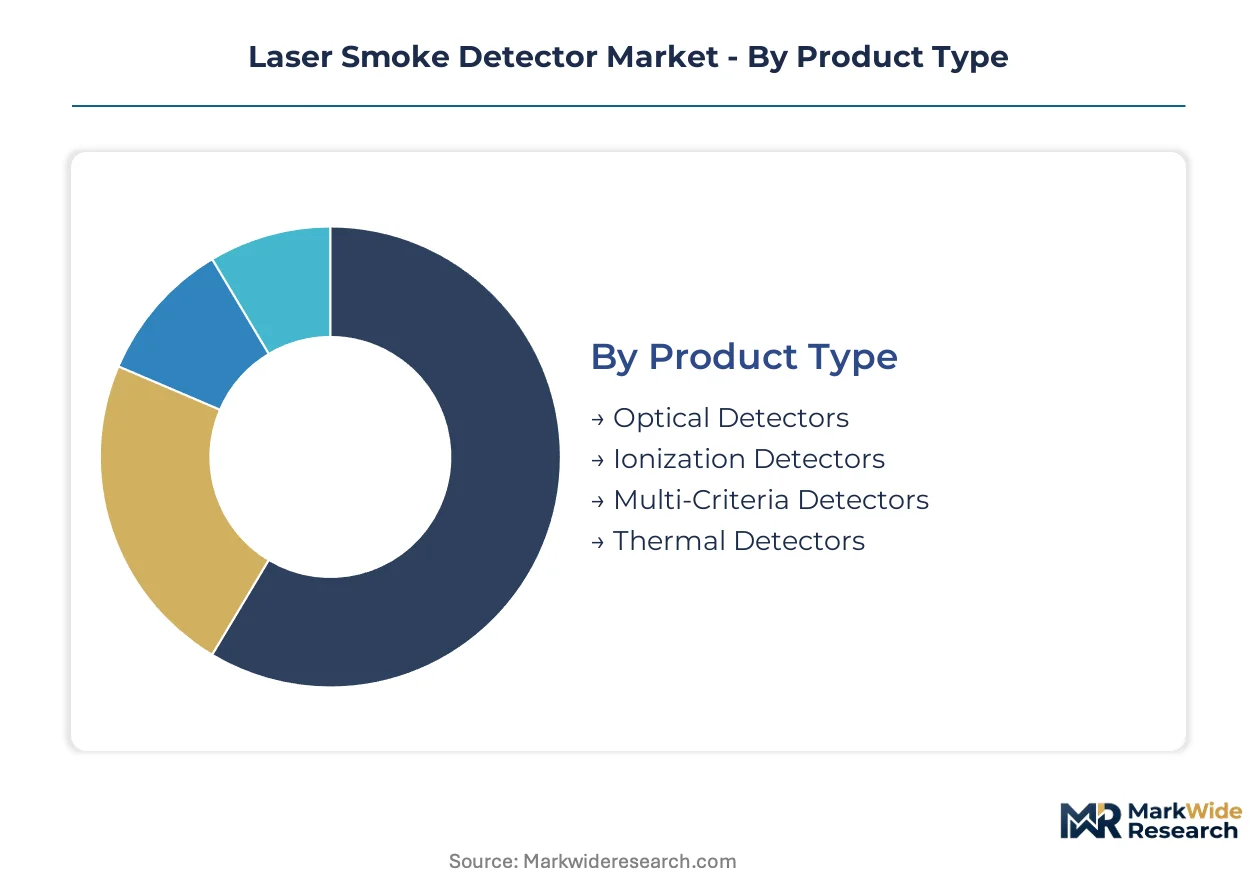
Segmentation in the laser smoke detector market reveals how procurement decisions split between sensitivity performance and system integration requirements. Buyers in critical infrastructure prioritize detection thresholds over cost, while facility management platforms drive convergence toward networked architectures.
Product Type:
Buyers differentiate primarily by obscuration sensitivity and false-alarm immunity when selecting detection technology.
- Optical Detectors:These units employ laser-photoelectric sensors to identify particulate concentrations at 0.005% obscuration per foot. Data center operators in Germany and the United States specify optical detectors for slow-burning fire protection in compute environments where asset density justifies premium sensitivity.
- Multi-Criteria Detectors:Modular architectures fuse laser particulate sensing with thermal and CO detection layers. Logistics facility operators in automated warehouses deploy these configurable arrays to match sensing depth to commodity value without full system replacement.
- Ionization Detectors:Legacy technology using radioactive americium-241 sources detects fast-flaming fires through ion current disruption.
- Thermal Detectors:Rate-of-rise and fixed-temperature triggers activate at heat thresholds rather than smoke concentration.
Optical detectors lead volumes today; multi-criteria configurations are gaining share fastest.
End User:
Application risk profiles and regulatory exposure shape procurement authority and budget allocation across buyer categories.
- Commercial:Real estate developers and facility management platforms command the largest procurement volumes. Networked detector arrays integrate with building automation systems in data centers, logistics hubs, and mixed-use developments across Germany, the United States, and China.
- Industrial:Manufacturing and process industries face combustible dust hazards and harsh environmental conditions. Detection specifications emphasize IP ratings and contamination resistance over sensitivity refinement.
- Government:Public infrastructure projects require UL, NFPA, CE marking, and CCC certification alignment for multi-region deployment eligibility.
- Residential:Single-family and multi-family housing installations prioritize cost minimization and battery backup over networked capabilities.
Commercial end users anchor revenue concentration; industrial applications are expanding most quickly.
Installation Type:
System architecture choices determine maintenance economics and interoperability with incumbent building infrastructure.
- Networked:Centralized monitoring platforms enable predictive maintenance integration and remote diagnostic polling. EU F-Gas Regulation and MDR framework compliance accelerates replacement of standalone units in European commercial retrofit cycles.
- Integrated:Direct embedding within fire suppression and HVAC control loops requires protocol compatibility with Siemens, Honeywell, and Johnson Controls automation stacks.
- Standalone:Battery-powered or hardwired units operate without external communication infrastructure.
- Portable:Temporary deployment for construction phases, event venues, and disaster response applications.
Networked installations dominate new construction; integrated systems show steepest expansion trajectory.
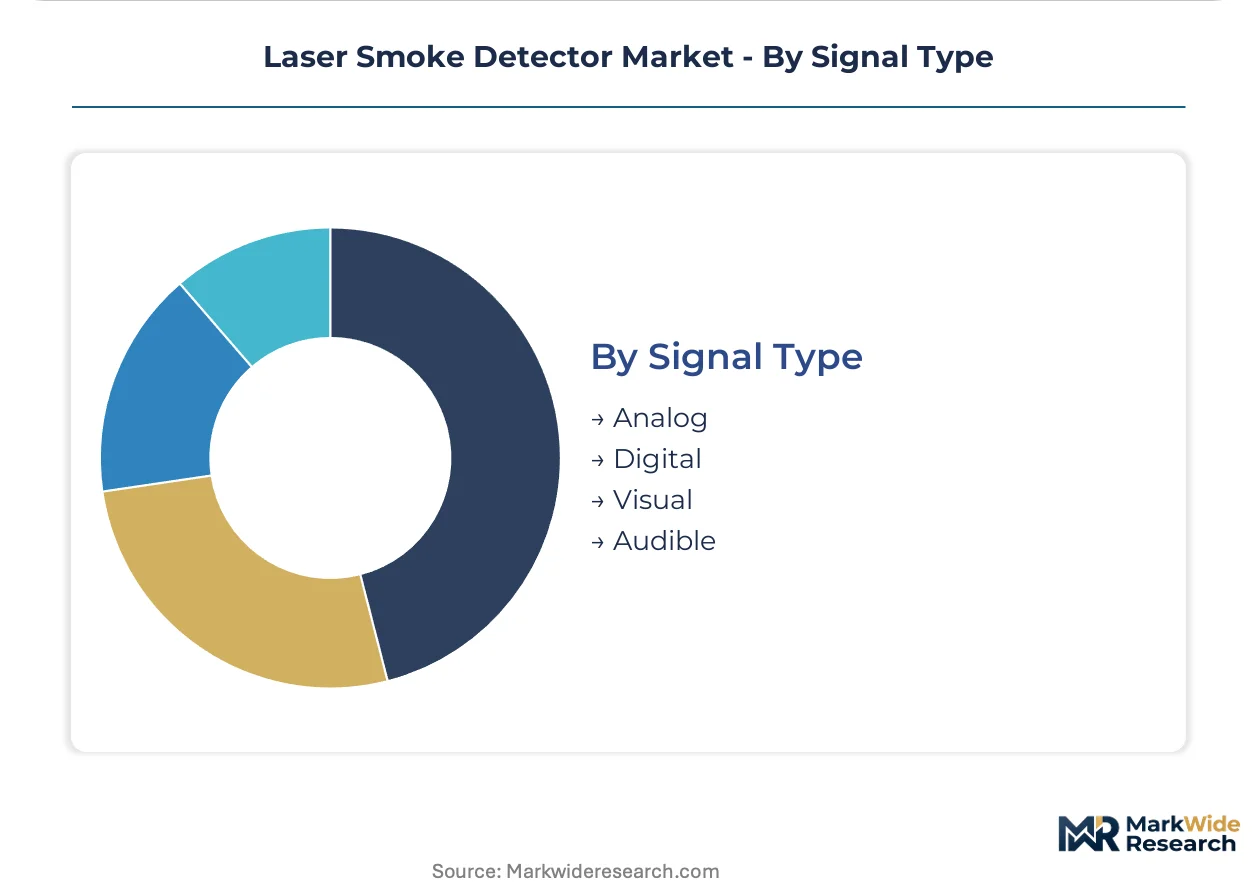
Signal Type:
Output modality selection reflects evacuation protocol requirements and accessibility compliance obligations.
- Digital:Addressable protocols transmit device status, contamination levels, and fault codes to central panels. Building automation convergence in United States commercial real estate drives specification of digital signaling for maintenance unbundling.
- Analog:Conventional zone-based wiring reduces installation cost in smaller facilities without centralized monitoring requirements.
- Audible:Synchronized evacuation tones and voice messaging systems meet NFPA 72 and EN 54-16 intelligibility standards.
- Visual:Strobe appliances serve hearing-impaired occupants and high-ambient-noise environments.
Digital signaling leads procurement volumes; visual notification appliances are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Laser smoke detector technology first achieved commercial scale in European industrial automation corridors during the 1980s, with German engineering firms pioneering aspirating detection systems for manufacturing facilities. This technical foundation subsequently transferred to North American data center markets and Asia-Pacific logistics infrastructure.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are retrofitting legacy facilities with networked detector arrays to protect server infrastructure. NFPA 72 and UL 268 standards mandate minimum sensitivity thresholds for commercial installations. Chicago and Phoenix industrial corridors are seeing concentrated procurement from logistics automation projects.
Germany
Frankfurt and Munich data center clusters are driving premium-tier detector specifications for financial services and cloud infrastructure protection. EU F-Gas Regulation and MDR frameworks are accelerating replacement cycles in commercial real estate portfolios. The Ruhr industrial belt is retrofitting manufacturing facilities with multi-criteria detection arrays.
China
GB standards evolution and mandatory CCC certification are opening procurement channels for networked detector systems in retrofit commercial projects. Yangtze River Delta logistics hubs in Shanghai and Suzhou are deploying high-sensitivity arrays for automated warehouse protection. Beijing-Tianjin-Hebei corridor data centers are upgrading fire safety infrastructure.
Japan
Tokyo-Osaka manufacturing belts are integrating laser detection with semiconductor cleanroom protocols. METI industrial safety guidelines are tightening certification requirements for critical infrastructure protection. Nagoya automotive clusters are specifying particulate detection systems for battery manufacturing facilities.
Netherlands
Amsterdam and Rotterdam data center markets are prioritizing certified low-emission detector housings under sustainability scoring frameworks. REACH chemical restrictions are reformulating polymer compositions for European market access. Eindhoven high-tech campus installations are driving networked system specifications.
Laser Smoke Detector Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sensitivity certification tiers, with detection threshold capabilities separating pricing bands. The vendor base organizes around three strategic archetypes: integrated building automation conglomerates, specialized fire safety divisions, and component-scale electronics manufacturers. Consolidation pressure is intensifying through technology licensing agreements and strategic partnerships with facility management platforms.
Within the integrated automation tier, Siemens AG and Honeywell International Inc. exemplify scale-driven positioning through building management platform control. VESDA by Xtralis occupies a specialist position representing high-sensitivity aspirating technology leadership. These three anchors illustrate how competitive positioning fragments between system-level integration and detection performance specialization.
| Leading Market Players |
|---|
| Siemens AG |
| VESDA (by Xtralis) |
| Honeywell International Inc. |
| Panasonic Corporation |
| Fike Corporation |
| Johnson Controls International |
| ABB Ltd. |
| Samsung Electronics Co., Ltd. |
| Hochiki Corporation |
| Others |
Supply & Pricing Matrix
Data center procurement teams in Northern Virginia and Frankfurt command substantial volume leverage, compressing supplier margins through multi-year service unbundling contracts that separate hardware acquisition from calibration lifecycle management.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates optical detectors with 0.005% obscuration sensitivity from multi-criteria configurations and legacy ionization units. Price differentiation hinges on UL 268 certification tier and after-sales service bundling. Cost compression in mid-tier configurations is intensifying because semiconductor input volatility feeds through photoelectric sensor component costs. Facility management platforms exhibit highest price sensitivity; critical infrastructure operators show lowest.
Supply Chain Analysis
Refurbishment flows for detector arrays in commercial retrofits create secondary parts markets that cannibalize new-unit demand in mature geographies. Laser diode manufacturing concentrates in China, Japan, and South Korea; optical chamber polymers source from German and Dutch specialty chemical suppliers. Single-source vulnerability in East Asian foundry capacity represents the dominant structural risk. Distribution runs through building automation OEM channel partners and direct facility management platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laser smoke detector market functions as a regulatory compounder where EU F-Gas Regulation and MDR framework tightening accelerates replacement cycles across European commercial real estate portfolios.
For Market Incumbents: Deepen backward integration into photoelectric sensor production to offset semiconductor foundry margin compression. Anchor channel control through predictive maintenance software modules that lock facility management platforms into recurring revenue relationships against emerging IoT-native entrants. For New Entrants and Emerging Players: E-commerce procurement platforms serving mid-tier commercial retrofit contractors offer the most penetrable route into fragmented United States regional markets. Target logistics automation projects in China's Yangtze River Delta where GB standards evolution creates certification parity windows for new certified entrants. For Investors and Strategic Acquirers: Building automation conglomerates are the most active acquirer in this space, seeking detector-embedded diagnostic capabilities to complete platform stacks. Over the medium-term horizon, vertically integrated aspirating detection specialists with proprietary optical chamber IP represent the prime acquisition archetype. Monitor CCC certification approval velocity for early signals of Chinese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | Parallel UL 268 and CE marking pathways unlock multi-region deployment eligibility for German data center projects. |
| Backward Integration | In-house production of laser diode subassemblies reduces single-source exposure to East Asian foundry concentration. |
| Predictive Maintenance Module Development | Diagnostic-embedded detectors capture service contract unbundling value from United States facility management platforms. |
| Multi-Criteria Sensor Fusion | Thermal and CO layer integration commands premium positioning in Netherlands sustainability-scored data center specifications. |
| Regional Calibration Network Buildout | Direct service relationships with regional providers defend margin pools against property management platform aggregation. |
Research Methodology
Bottom-up commercial end-use modeling reconciled against top-down detector OEM production tracking forms the analytical core of this study. Primary interviews with fire safety engineering directors, facility management platform procurement leads, building automation system integrators, and regional calibration service providers cross-validate demand assumptions. Secondary sources include UL certification databases, EU Construction Products Regulation filing records, CCC approval registries, and customs trade data on photoelectric sensor component flows. Triangulation between installation volume estimates and manufacturing output data ensures consistency across the analysis window.
Historical trendline analysis of detector replacement cycles in commercial real estate establishes baseline growth parameters. The forecast framework segments by product sensitivity tier, installation architecture, end-use risk profile, and regional regulatory cluster. CAGRs derive from fitted adoption curves calibrated against EU F-Gas Regulation implementation timelines and data center construction permit data. Model inputs incorporate semiconductor foundry capacity utilization indices and building automation platform integration penetration rates.
The model assumes a particular technology adoption path; alternative pathways for multi-sensor fusion architectures would alter the outlook if thermal imaging cost curves compress faster than projected. Forecasts reflect assumptions about certification timeline stability and foundry supply normalization. Practitioners should monitor GB standards amendment velocity and REACH chemical restriction expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Global Flame Arrestors Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
China Thermal Protector Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Marine Fire Extinguishing System Market