
 Fire Suppression Market | 2026-2036
Fire Suppression Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Suppression Market Analysis
China is rewriting the competitive map of fire suppression manufacturing as domestic capacity for gas-based and water-based systems scales rapidly. Johnson Controls International leverages its building automation integration to anchor premium commercial installations across Asia-Pacific. Honeywell International competes through advanced sensor-to-suppression connectivity that differentiates its integrated platform from conventional standalone systems. Siemens AG dominates industrial fire safety with its certified gas suppression protocols for energy and utility applications.
Fire suppression encompasses engineered systems designed to detect, control, and extinguish fires through chemical, gaseous, foam, or water-based agents, typically operating at discharge pressures between 60 and 360 bar depending on agent type and protected hazard classification. These systems serve to minimize asset damage, ensure personnel safety, and maintain operational continuity across facilities where fire events carry catastrophic financial or human consequences. Gas systems command premium positioning in data center and telecommunications applications where water damage poses equal risk to fire itself, while water-based systems sustain volume leadership across residential and standard commercial construction due to lower installed cost and simpler maintenance protocols. Foam systems retain specialized demand in petrochemical storage and aviation fuel handling where flammable liquid hazards dominate risk profiles.
The National Fire Protection Association publishes NFPA 2001 governing clean agent fire extinguishing systems in the United States, while the EU F-Gas Regulation restricts fluorinated greenhouse gases used in suppression applications, directly shaping product formulation roadmaps for manufacturers serving European data centers and industrial clients. China's Ministry of Emergency Management enforces GB 50370 for gas fire extinguishing system design, creating compliance-driven replacement cycles in existing building stock. Stakeholders must monitor regulatory divergence between fluorine-free mandates in Europe and transitional acceptance timelines elsewhere, as agent selection decisions made today will lock in service infrastructure for fifteen-to-twenty-year system lifecycles.
Market Dynamics
The EU F-Gas Regulation is compressing fluorinated gas availability across European data centers while China's GB 50370 enforcement triggers wholesale system replacements, creating divergent compliance-driven demand pulses across major installation bases.
Growth Catalysts
- Data center infrastructure expansion:Hyperscale facilities in Singapore, Germany, and Virginia are mandating gas-based suppression for server protection, creating sustained specification pull for clean agent systems.
- GB 50370 compliance cycles:China's Ministry of Emergency Management enforcement is forcing replacement of legacy halon and early FM-200 installations in commercial buildings across Shanghai, Beijing, and Shenzhen.
- Fluorine-free agent development:Novec 1230 and inert gas blends are capturing specification share in Nordic and German industrial applications where environmental performance ranks alongside fire safety.
Market Restraints
- Specialized steel cylinder supply:High-pressure containment fabrication concentrates among German and Japanese metalworkers, creating 14-18 week lead time volatility for 360-bar system components.
- F-Gas quota compression:The EU's phasedown schedule is constraining HFC-227ea and HFC-125 availability, forcing project delays or agent substitution in continental European installations.
- Water mist technical ceiling:Fine spray systems face discharge pressure limitations below 200 bar that exclude high-ceiling atrium protection in aviation hangars and turbine halls.
Strategic Opportunities
- India manufacturing plant mandates:State-level factory safety inspectorates in Maharashtra and Tamil Nadu are expanding fire suppression requirements under BIS standards for automotive and electronics production.
- Battery energy storage integration:Lithium-ion thermal runaway protocols are converging with gas suppression engineering, creating specification pull for combined detection-extinguishing platforms in utility-scale installations.
- Direct-to-facility-manger digital channels:Configuration tools and remote engineering support are compressing distributor layers in mid-market commercial projects across Australia and Southeast Asia.
Industry Challenges
- Cross-disciplinary system integration:Fire suppression contractors must coordinate with HVAC, electrical, and building automation trades where interface specification gaps cause commissioning failures and cost overruns.
- Agent transition certification timelines:UL and FM Global listing processes for fluorine-free alternatives extend 18-24 months, lagging regulatory deadlines and freezing specification decisions.
- Pressure vessel welder scarcity:Qualified ASME-certified technicians for 360-bar cylinder fabrication are concentrated in aging workforce pools across Pennsylvania and Osaka manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Suppression Market |
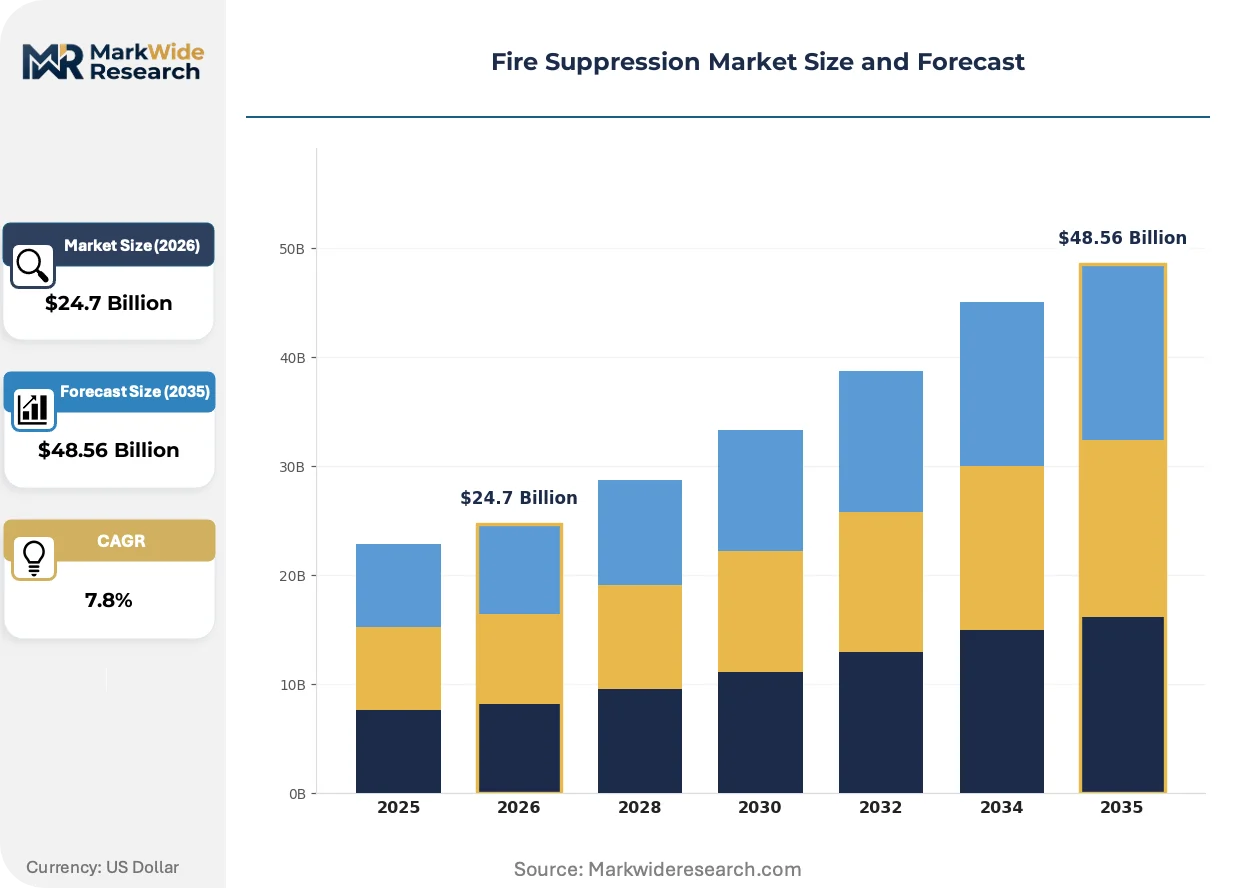
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $48.56 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based Systems, Foam Systems, Powder-based Systems, Gas Systems Application: Residential, Commercial, Industrial, Automotive End User: Fire Departments, Manufacturing Plants, Warehouses, Data Centers Installation Type: Fixed, Portable, Integrated, Modular |
| Companies Covered | Carrier Global Corporation, Halma plc, Johnson Controls International, Robert Bosch GmbH, Hochiki Corporation, Honeywell International, Minimax Viking Group, Gentex Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Suppression Market Emerging Trajectories
Agent chemistry, detection intelligence, and procurement models are undergoing simultaneous transformation as environmental regulations and digital infrastructure requirements reshape specification priorities across installation types.
Condensed aerosol generators using potassium-based solid compounds are rendering obsolete traditional halocarbon flooding in enclosed machinery spaces and electrical vaults. Marine classification societies and offshore platform operators are specifying these systems for engine rooms where weight and space constraints dominate. The technology is rendering obsolete conventional cylinder bank arrangements by eliminating pipe network complexity and reducing agent storage volume by 80 percent.
The EU F-Gas Regulation's phasedown schedule is forcing formulation shifts across suppression agent portfolios. Manufacturers serving European data centers are accelerating inert gas and fluorine-free liquid agent development to maintain specification eligibility. German and Dutch industrial clients are now requiring 20-year environmental impact documentation alongside fire performance certification in tender evaluations.
Integrated detection-to-suppression platforms with IoT-enabled pressure monitoring and predictive maintenance alerts are replacing standalone system architectures. Data center operators in Singapore and Sydney are specifying these connected platforms to reduce insurance premiums and satisfy uptime guarantees. Facility managers are unbundling traditional service contracts, purchasing hardware and remote monitoring separately while retaining local contractors for physical inspection compliance.
Fire Suppression Market Segmentation
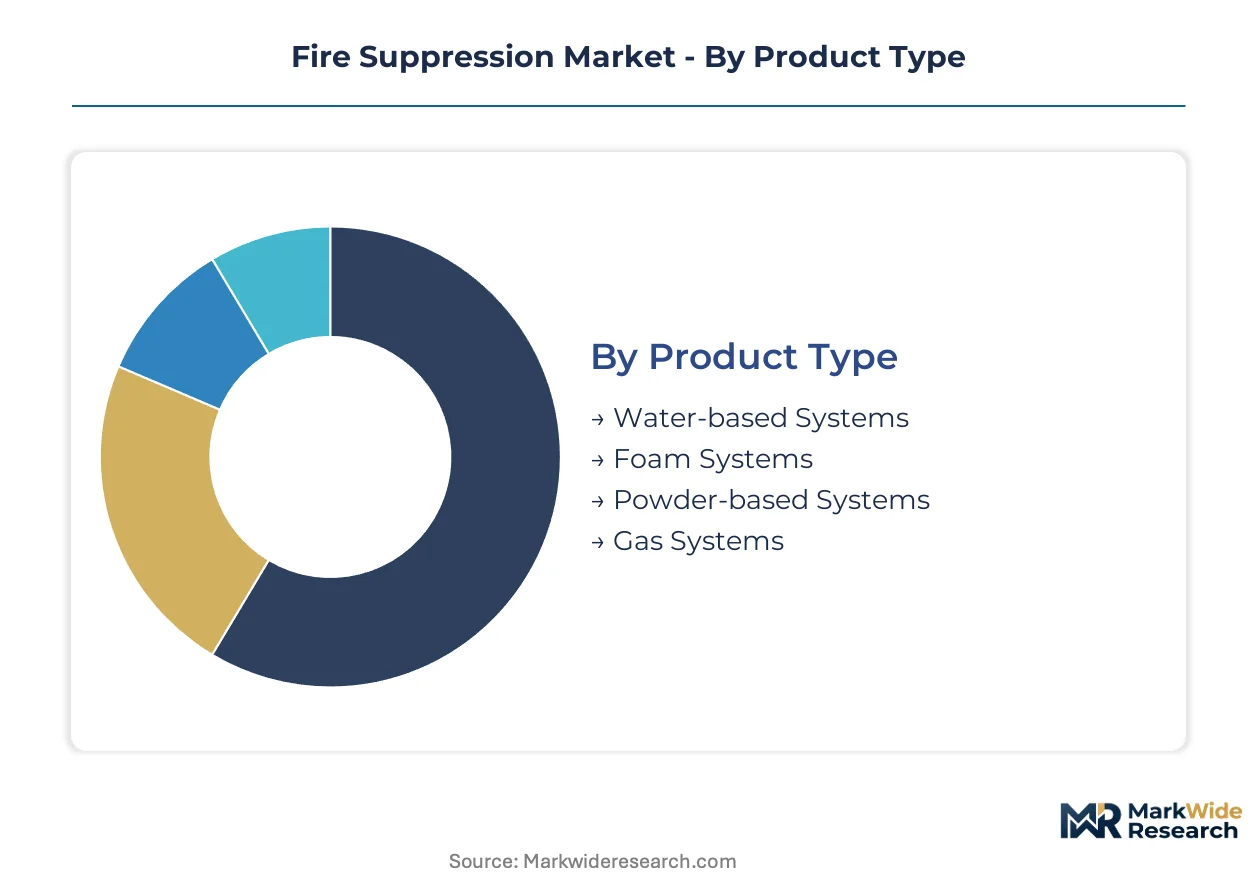
Agent chemistry, installation architecture, and end-use hazard profiles create distinct competitive arenas within fire suppression. Specification decisions cascade across fifteen-to-twenty-year system lifecycles, locking in maintenance infrastructure and replacement part supply chains.
Product Type:
Cost tier stratification separates premium gas systems from commoditized water infrastructure, with intermediate positions held by foam and powder technologies.
- Water-based Systems:Sprinkler and deluge configurations dominate residential and standard commercial construction through lower installed cost and simplified maintenance protocols. Demand concentrates in China's tier-two cities where GB 50370 enforcement is accelerating retrofit cycles in existing building stock.
- Gas Systems:Clean agent and inert gas configurations operate at discharge pressures between 60 and 360 bar for data center and telecommunications protection where water damage equals fire risk. Singapore and Virginia hyperscale facilities are mandating these systems for server protection, creating sustained specification pull despite premium positioning.
- Foam Systems:Aqueous film-forming foam retains specialized demand in petrochemical storage and aviation fuel handling where flammable liquid hazards dominate risk profiles.
- Powder-based Systems:Dry chemical agents serve mobile and temporary protection applications in manufacturing environments with rapid reconfiguration requirements.
Water-based systems hold installed capacity across residential and commercial building stock. Gas systems are rotating up the share rankings in data center and critical infrastructure specifications.
Application:
Application scope determines hazard classification protocols, agent selection constraints, and regulatory compliance frameworks governing system design.
- Industrial:Energy facilities, chemical processing plants, and manufacturing floors require certified gas suppression protocols with integrated detection-to-discharge automation. German and Dutch industrial clients now require 20-year environmental impact documentation alongside fire performance certification in tender evaluations.
- Commercial:Office complexes, retail centers, and hospitality venues balance occupancy safety with business continuity, driving specification toward water mist and pre-action sprinkler architectures. India's state-level factory safety inspectorates in Maharashtra and Tamil Nadu are expanding requirements under BIS standards for automotive and electronics production facilities.
- Residential:Single-family and multi-family dwellings sustain volume leadership through code-mandated sprinkler adoption in new construction across North American jurisdictions.
- Automotive:Electric vehicle battery compartments and charging infrastructure are converging lithium-ion thermal runaway protocols with gas suppression engineering.
Commercial applications sustain the broadest installer base. Industrial specifications are climbing the fastest as environmental compliance documentation becomes mandatory.
End User:
End user type dictates procurement authority, technical specification depth, and service contract structuring across installation lifecycles.
- Data Centers:Hyperscale and colocation operators specify integrated detection-to-suppression platforms with IoT-enabled pressure monitoring to reduce insurance premiums and satisfy uptime guarantees. Singapore and Sydney facilities are unbundling traditional service contracts, purchasing hardware and remote monitoring separately.
- Manufacturing Plants:Automotive, electronics, and chemical producers face expanding mandates under China's GB standards and India's BIS requirements, triggering wholesale system replacements in Shanghai, Beijing, and Shenzhen.
- Warehouses:E-commerce fulfillment and cold storage facilities balance commodity protection with high-bay clearance requirements, driving in-rack sprinkler and early suppression fast-response configurations.
- Fire Departments:Municipal agencies procure portable and vehicle-mounted systems for emergency response, with specification authority concentrated in procurement offices rather than operational units.
Data centers command the steepest expansion trajectory as digital infrastructure investment accelerates. Manufacturing plants retain the largest replacement cycle volume.
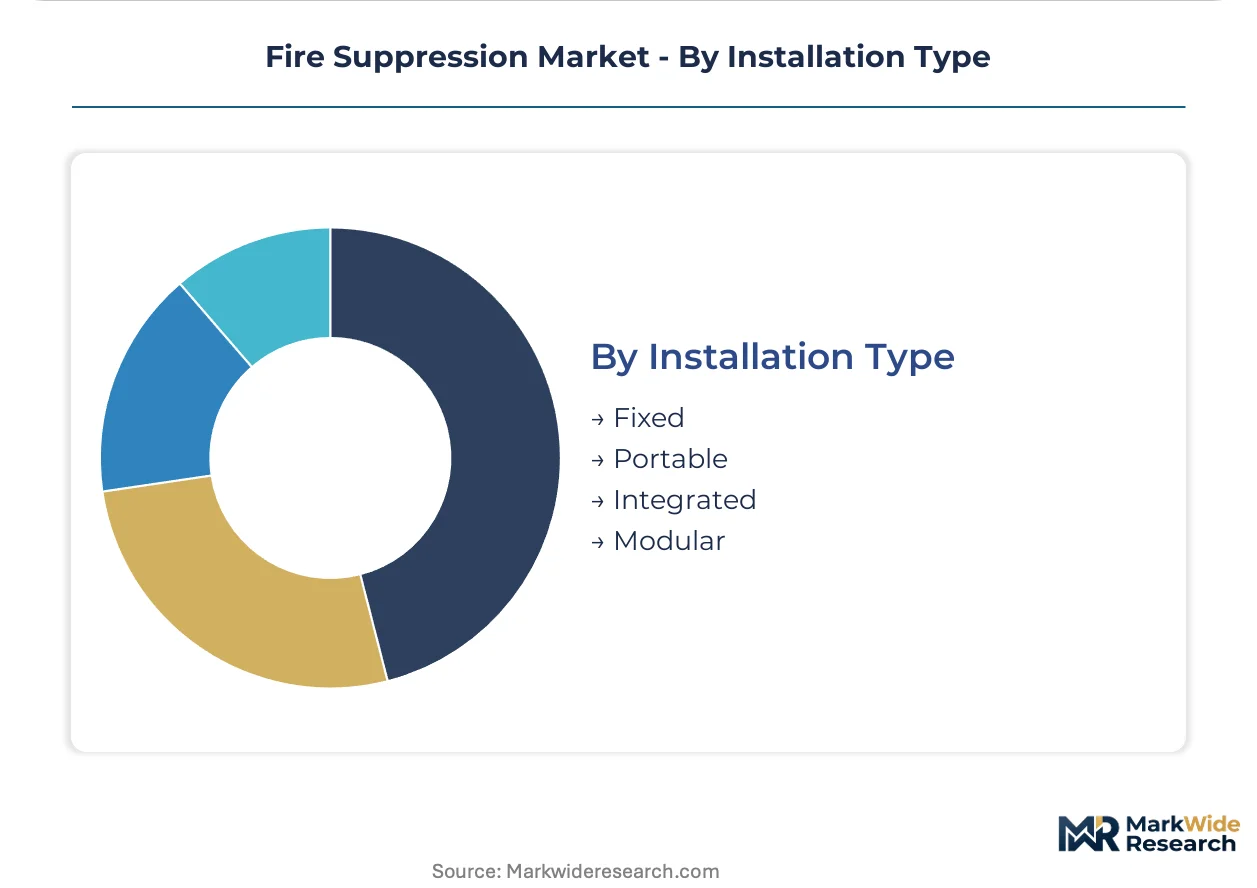
Installation Type:
Installation architecture determines capital deployment patterns, contractor specialization requirements, and flexibility for future hazard reconfiguration.
- Fixed:Permanent pipe networks and cylinder banks serve established hazard zones with predictable protection requirements, dominating data center and industrial specifications where discharge precision is critical.
- Modular:Pre-engineered skid-mounted and containerized systems compress deployment timelines for temporary facilities and rapid capacity expansion. Marine classification societies and offshore platform operators are specifying condensed aerosol generators in engine rooms where weight and space constraints dominate.
- Portable:Wheeled and handheld extinguishers serve mobile protection needs and regulatory compliance in commercial occupancies, with procurement concentrated through safety supply distributors.
- Integrated:Building automation system connectivity enables predictive maintenance alerts and remote monitoring, replacing standalone architectures in premium commercial installations across Asia-Pacific.
Fixed installations hold installed capacity across permanent facilities. Modular configurations are rotating up the share rankings in temporary and rapidly scaling operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys gas-based systems for manufacturing mandates while Germany and the United States prioritize fluorine-free agents for data center sustainability, creating divergent consumption patterns across installation bases.
China
GB 50370 enforcement by the Ministry of Emergency Management is forcing wholesale replacement of legacy halon and early FM-200 installations. Shanghai, Beijing, and Shenzhen commercial buildings are retrofitting fixed gas suppression networks under tightened compliance timelines. Yangtze River Delta manufacturing clusters are expanding water-based system capacity for automotive and electronics production facilities.
Germany
The EU F-Gas Regulation's phasedown schedule is constraining HFC-227ea and HFC-125 availability for continental data centers. German industrial clients now require 20-year environmental impact documentation alongside fire performance certification in tender evaluations. Bavarian hyperscale facilities are mandating inert gas and Novec 1230 specifications for server protection.
United States
Virginia hyperscale data centers are driving specification pull for clean agent systems with integrated IoT-enabled pressure monitoring. NFPA 2001 governs clean agent system design while OSHA maintains workplace safety protocols for high-pressure cylinder handling. Texas and Arizona cloud infrastructure clusters are unbundling traditional service contracts for remote monitoring platforms.
India
State-level factory safety inspectorates in Maharashtra and Tamil Nadu are expanding fire suppression requirements under BIS standards for automotive and electronics production. Mumbai and Chennai manufacturing corridors are retrofitting fixed-installation systems under expanded coverage mandates. Karnataka's Bengaluru tech corridor is emerging as a specification hub for integrated detection-to-suppression platforms.
Singapore
Hyperscale data center operators are mandating gas-based suppression for server protection to satisfy uptime guarantees and reduce insurance premiums. The city-state's building automation integration standards are accelerating demand for connected platforms with predictive maintenance alerts. Jurong and Tuas industrial zones are specifying modular condensed aerosol systems for marine and offshore applications.
Fire Suppression Market Vendor Landscape
Capability concentration sits with specialized gas suppression engineering firms; scale advantage sits with diversified building automation conglomerates. The market structures around three tiers: integrated platform providers, standalone system specialists, and regional cylinder fabricators. Two strategic archetypes dominate competitive positioning: sensor-to-suppression connectivity developers and fluorine-free agent formulation leaders. M&A activity concentrates on detection technology acquisition while capacity expansion targets high-pressure containment fabrication.
Among diversified building automation conglomerates, Johnson Controls International and Honeywell International occupy positions anchoring premium commercial installations across Asia-Pacific. Siemens AG exemplifies the industrial certification specialist archetype, with its protocols serving energy and utility applications. Hochiki Corporation and Minimax Viking Group represent standalone system specialists competing through focused fire safety engineering rather than broad building integration.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Halma plc |
| Johnson Controls International |
| Robert Bosch GmbH |
| Hochiki Corporation |
| Honeywell International |
| Minimax Viking Group |
| Gentex Corporation |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
EU F-Gas quota compression as a regulatory chokepoint determines both tiered pricing spreads across agent chemistries and supply chain restructuring toward fluorine-free alternatives. Buyers face extended procurement cycles as HFC-227ea availability tightens, forcing substitution economics that widen premiums for inert gas and Novec 1230 formulations against legacy halocarbon baselines.
Pricing Analysis
German data centers pay 40-60% premiums over Chinese manufacturing facilities for equivalent gas suppression capacity due to environmental compliance documentation requirements. Three-tier pricing structure across premium inert gas, standard fluorinated clean agent, and economy water-mist configurations reflects certification grade and after-sales service bundling. Pricing pressure stems from cylinder fabrication cost compression as qualified ASME welder scarcity tightens supply. Small commercial contractors exhibit highest price sensitivity, while hyperscale operators prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as German and Japanese cylinder fabricators absorb working capital pressure from high-pressure containment demand surges. Supply concentrates in Germany for 360-bar precision metalworking, China for agent formulation and mid-pressure assemblies, and Japan for specialized valve engineering. Raw material dependencies include specialty steel alloys, potassium-based solid compounds for condensed aerosol systems, and fluorine-free liquid agents. Single-source vulnerability runs through ASME-certified welding capacity concentrated in aging Pennsylvania and Osaka workforce pools. Distribution runs through regional fire safety distributors with certified installation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire suppression hardware margins are compressing while remote monitoring subscriptions and predictive maintenance contracts expand at double the rate of equipment sales, creating a service-attach opportunity that restructures customer lifetime value calculations.
For Market Incumbents: Entrench position through backward integration into high-pressure cylinder fabrication to secure supply against ASME welder scarcity, while accelerating fluorine-free agent certification investment ahead of EU F-Gas phasedown deadlines. Consolidate distributor relationships in Asia-Pacific where unbundled procurement models threaten traditional channel control. For New Entrants and Emerging Players: Pursue modular condensed aerosol configurations for marine and offshore applications where weight constraints and space limitations render traditional cylinder banks obsolete. Target India's Maharashtra and Tamil Nadu manufacturing corridors where BIS standard enforcement is expanding faster than incumbent service infrastructure can deploy. For Investors and Strategic Acquirers: The market sits at a substitution phase that favors detection technology specialists over standalone suppression fabricators, as integrated IoT-enabled platforms capture specification share. Long-term viability hinges on software-enabled service revenue attachment rates. Watch for inflection when UL and FM Global listing timelines for fluorine-free agents compress below 12 months, signaling regulatory alignment and demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Agent Certification Investment | Secures specification eligibility under EU F-Gas Regulation phasedown schedules for German data center tenders. |
| Backward Integration into Cylinder Fabrication | Captures ASME-certified welding capacity in Pennsylvania and Osaka against 14-18 week lead time volatility. |
| Remote Monitoring Platform Development | Enables unbundled service contracts that Singapore hyperscale operators now specify for insurance premium reduction. |
| Condensed Aerosol Product Line Expansion | Addresses marine classification society specifications for engine room applications where space constraints dominate. |
| India Distribution Channel Establishment | Positions for Maharashtra and Tamil Nadu BIS mandate enforcement in automotive and electronics manufacturing corridors. |
Methodological Framework
The analysis maps clean agent, water-based, foam, and condensed aerosol suppression systems, each validated through fire safety engineering directors, facility managers at hyperscale data centers, cylinder fabrication procurement leads, and marine classification surveyors. Primary interviews combined with secondary validation from NFPA 2001 documentation, EU F-Gas Regulation filings, GB 50370 enforcement notices, and SEC disclosures from listed building automation conglomerates. Bottom-up installation base modeling triangulated against top-down agent consumption estimates.
Assumptions held fixed include current EU F-Gas phasedown trajectory, GB 50370 enforcement timelines, and ASME certification workforce demographics, while agent substitution elasticities and IoT platform adoption rates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass agent chemistry, installation architecture, end-use hazard classification, and procurement authority type. CAGRs derived from agent demand forecasting tied to data center capex cycles and manufacturing safety mandate expansion. Industry-specific inputs included high-pressure cylinder lead time distributions and UL/FM Global listing pipeline status.
Sensitivities concentrate around EU regulatory acceleration, Chinese GB standard enforcement intensity, and condensed aerosol marine specification adoption. Forecasts reflect documented assumptions about substitution timelines and certification bottlenecks. Macroeconomic contraction in data center investment, regulatory deviation from announced phasedown schedules, or breakthrough water-mist pressure ceiling technologies would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire and Rescue Helmets Market
Fire Safety & Protection
Fire Alarm and Detection System Market
Fire Safety & Protection
US Fire Alarm and Detection Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Fire Hose Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Global Fixed Firefighting Misting System Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market