
 Smart Smoke Alarm Market | 2026-2036
Smart Smoke Alarm Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Smoke Alarm Market Insights
China's manufacturing corridor for IoT sensors is rewriting component economics for smart smoke alarm producers worldwide. Honeywell International Inc. leverages its building automation heritage to anchor premium integrated fire safety portfolios across commercial real estate. Johnson Controls International Plc sustains R&D intensity in multi-sensor fusion algorithms that reduce nuisance alarms. Robert Bosch GmbH competes through channel control in European distribution networks for professional installer segments.
A smart smoke alarm is a networked fire detection device incorporating photoelectric or ionization sensors with wireless connectivity protocols, typically operating at 2.4 GHz Wi-Fi or Bluetooth Low Energy frequencies, designed to transmit real-time alerts to mobile applications and central monitoring stations for rapid emergency response. Wi-Fi-connected units dominate residential retrofit channels where consumers prioritize smartphone integration without hub dependencies. Photoelectric technology leads new construction specifications due to superior smoldering-fire detection and reduced false-alarm rates versus legacy ionization designs. Multi-functional devices integrating carbon monoxide and air quality sensors capture expanding margin pools in premium residential and commercial installations.
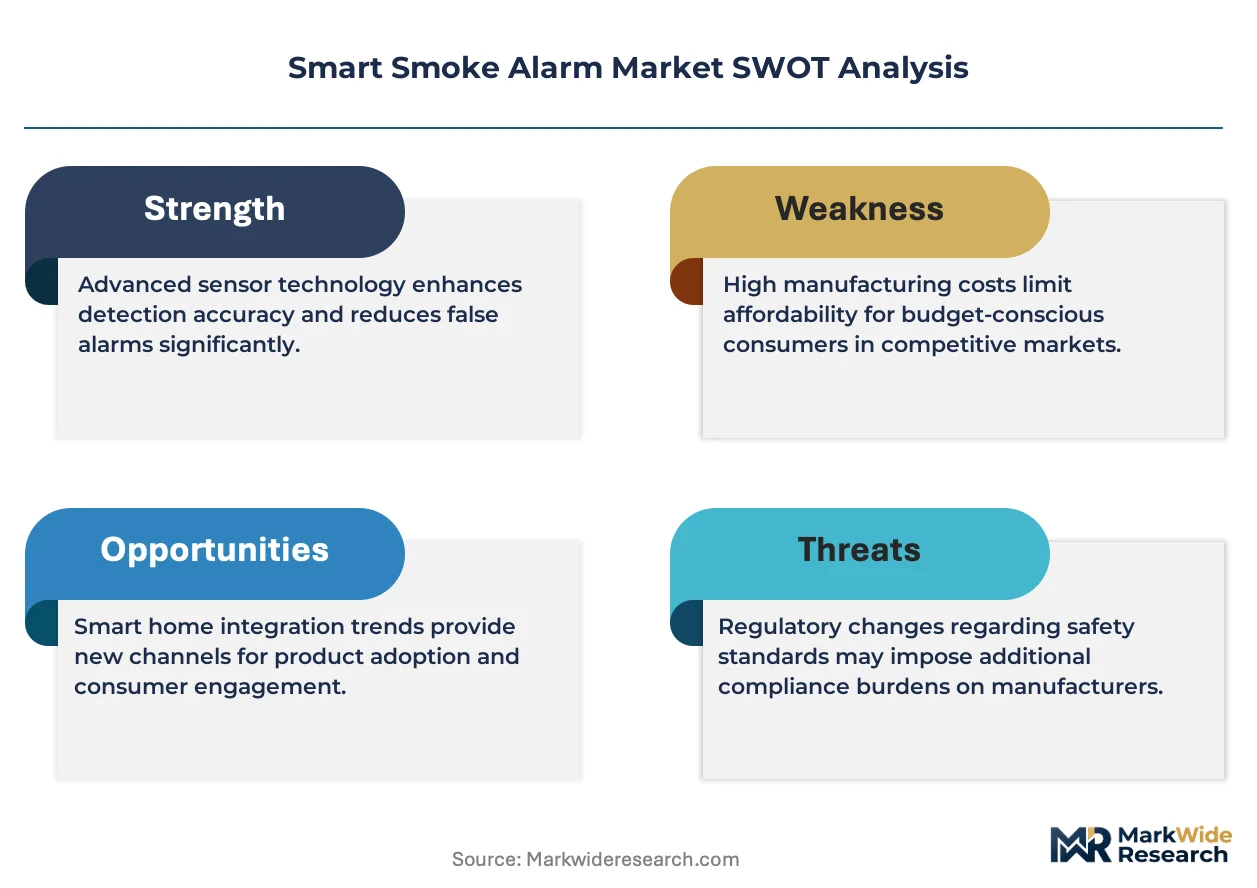
The NFPA 72 standard in the United States and the EU Construction Products Regulation collectively mandate interconnectivity requirements and response-time thresholds that elevate product compliance costs while disqualifying non-certified entrants. ETL and UL listings function as de facto market access gates for North American distribution, compelling manufacturers to maintain dual certification portfolios. Stakeholders must monitor evolving smart home protocol standards—specifically Matter interoperability specifications—as these will determine which device ecosystems achieve retail shelf placement and insurance partnership eligibility.
Market Dynamics
The residential retrofit wave is compressing replacement cycles as homeowners abandon legacy ionization units before end-of-life, creating a demand pull that outpaces new construction specifications and reshaping inventory planning across distribution channels.
Growth Catalysts
- NFPA 72 Interconnect Mandates:Updated US fire code requirements for wireless alarm interconnection are forcing replacement of standalone units in multi-story dwellings, accelerating upgrade velocity in the retrofit segment.
- Photoelectric Sensor Dominance:Superior smoldering-fire detection performance and reduced nuisance alarm rates are displacing ionization technology in new construction specifications across North America and Western Europe.
- Insurance Premium Incentives:German and Japanese property insurers now offer documented discounts for connected detection systems, converting cost-sensitive homeowners into smart device adopters.
Market Restraints
- Silicon Supply Concentration:Wi-Fi and Bluetooth Low Energy chipsets depend on foundry capacity concentrated in Taiwan, exposing producers to allocation volatility and extended lead times.
- Dual Certification Burden:ETL and UL listings for North American access require parallel testing protocols that add compliance costs and disqualify smaller regional manufacturers.
- Hub-Free Architecture Limitations:Direct-to-router Wi-Fi designs consume higher power than mesh alternatives, constraining battery life and increasing hardware costs for premium positioning.
Strategic Opportunities
- Multi-Sensor Convergence:Integration of carbon monoxide and particulate matter sensing is virtualizing standalone air quality monitors, capturing margin pools in premium residential installations.
- Professional Installer Channel:European electrical wholesalers and security integrators represent underdeveloped routes for connected fire safety, offering recurring monitoring revenue streams.
- Matter Protocol Alignment:Early certification against emerging interoperability standards will determine retail shelf placement and smart home ecosystem eligibility for the next product generation.
Industry Challenges
- RF Engineering Talent Scarcity:Embedded wireless firmware development for 2.4 GHz coexistence and mesh networking requires specialized skills that outpace available labor pools in mid-tier manufacturers.
- Legacy System Integration:Hardwired AC-powered installations demand electrical contractor involvement for retrofit, complicating consumer-direct sales models and inflating total project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Smoke Alarm Market |
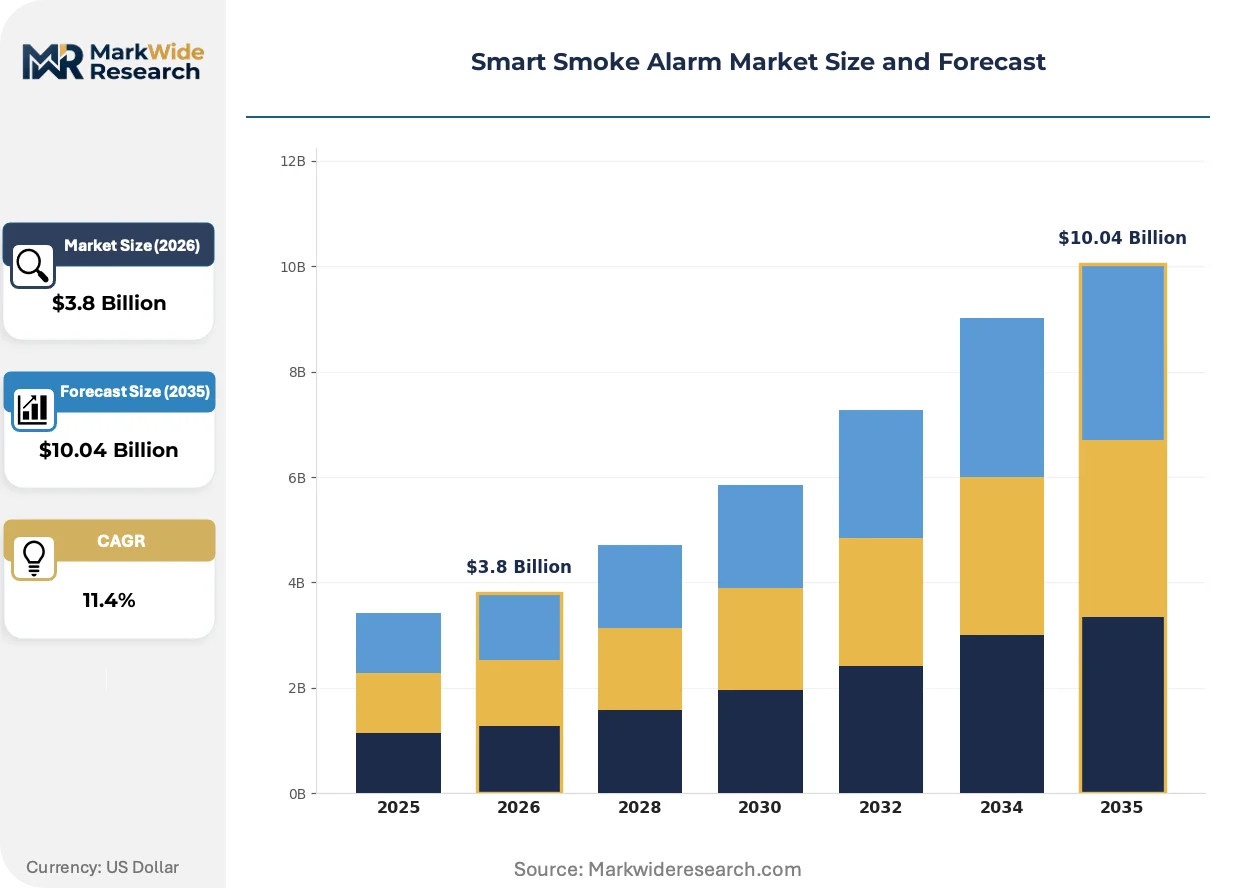
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery-Operated, Hardwired, Wi-Fi-Connected, Bluetooth-Enabled End User: Residential, Commercial, Industrial, Public Spaces Technology: Photoelectric, Ionization, Dual-Sensor, Multi-Functional Installation Type: Standalone, Integrated, Retrofit, New Construction |
| Companies Covered | Honeywell International Inc., Johnson Controls International Plc, Robert Bosch GmbH, Siemens AG, Hochiki Corporation, Nest Labs (Google/Alphabet), Schneider Electric SE, Resideo Technologies Inc., Samsung Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Smoke Alarm Market Trends and Innovations
Sensor fusion and connectivity protocol evolution are compressing device categories while regulatory pressure on false-alarm performance is accelerating algorithmic differentiation among established producers.
Photoelectric sensing arrays with machine-learning-based particle classification are virtualizing dual-sensor hardware configurations, enabling single-chamber designs to discriminate between smoldering and flaming combustion signatures. US multi-family housing developers are specifying these units to meet stringent NFPA 72 nuisance alarm thresholds. The technology is virtualizing cost structures for mid-market producers previously unable to justify dual-sensor BOM premiums.
REACH substance restrictions on halogenated flame retardants in polymer housings are forcing material transitions toward phosphorus-based alternatives across EU-bound product lines. German testing laboratories report extended certification timelines for revised housing compounds, compressing launch windows for seasonal retail cycles. Residential retrofit channels in France and the Netherlands are prioritizing inventory with pre-validated environmental compliance to avoid customs detention risk.
Homeowner purchasing patterns are gravitating toward bundled smart home security packages that subsume standalone smoke alarm sales into comprehensive monitoring subscriptions. US broadband providers and regional security dealers are capturing this demand shift through white-label hardware arrangements that displace traditional retail channels. The behavior is most pronounced in suburban markets where insurance broker referrals increasingly direct buyers toward monitored service contracts rather than self-installed devices.
Smart Smoke Alarm Market Segmentation
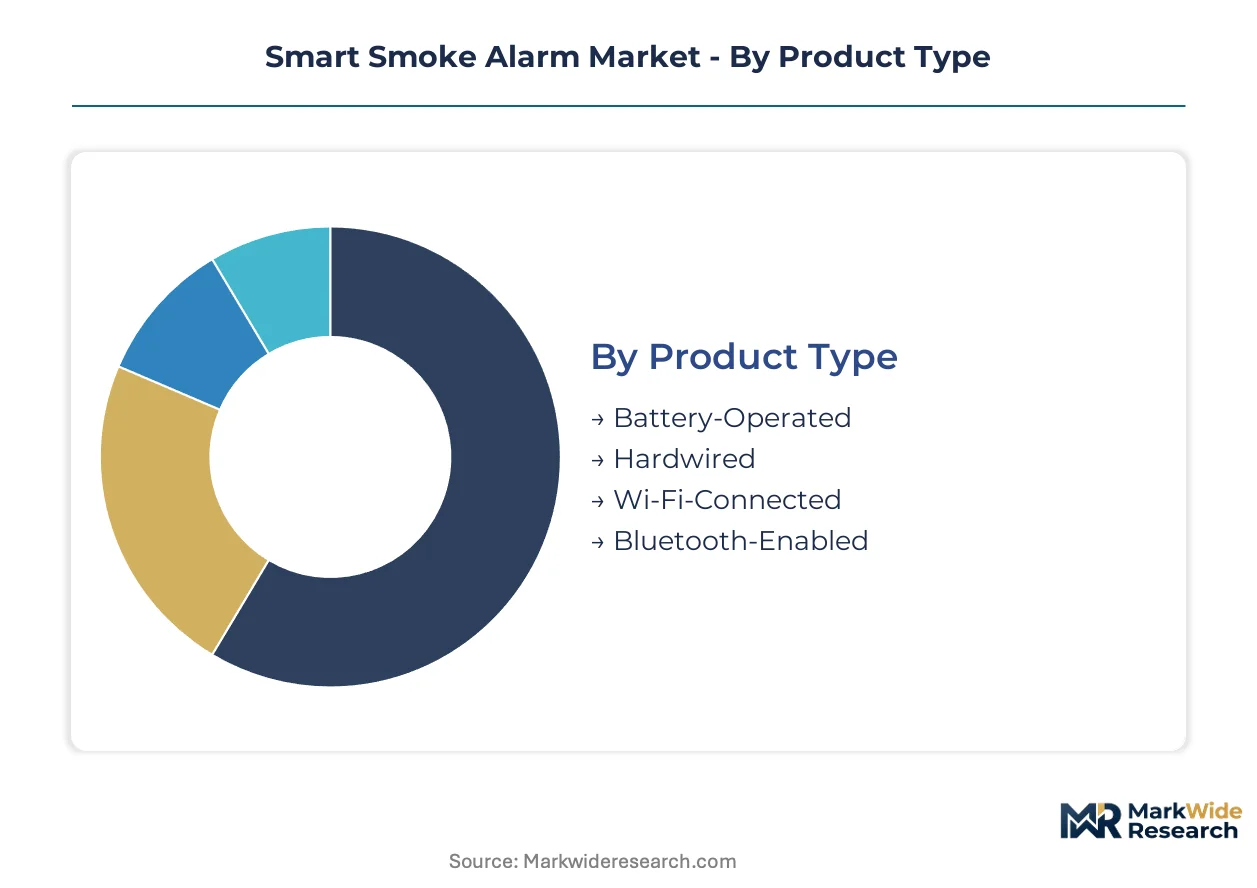
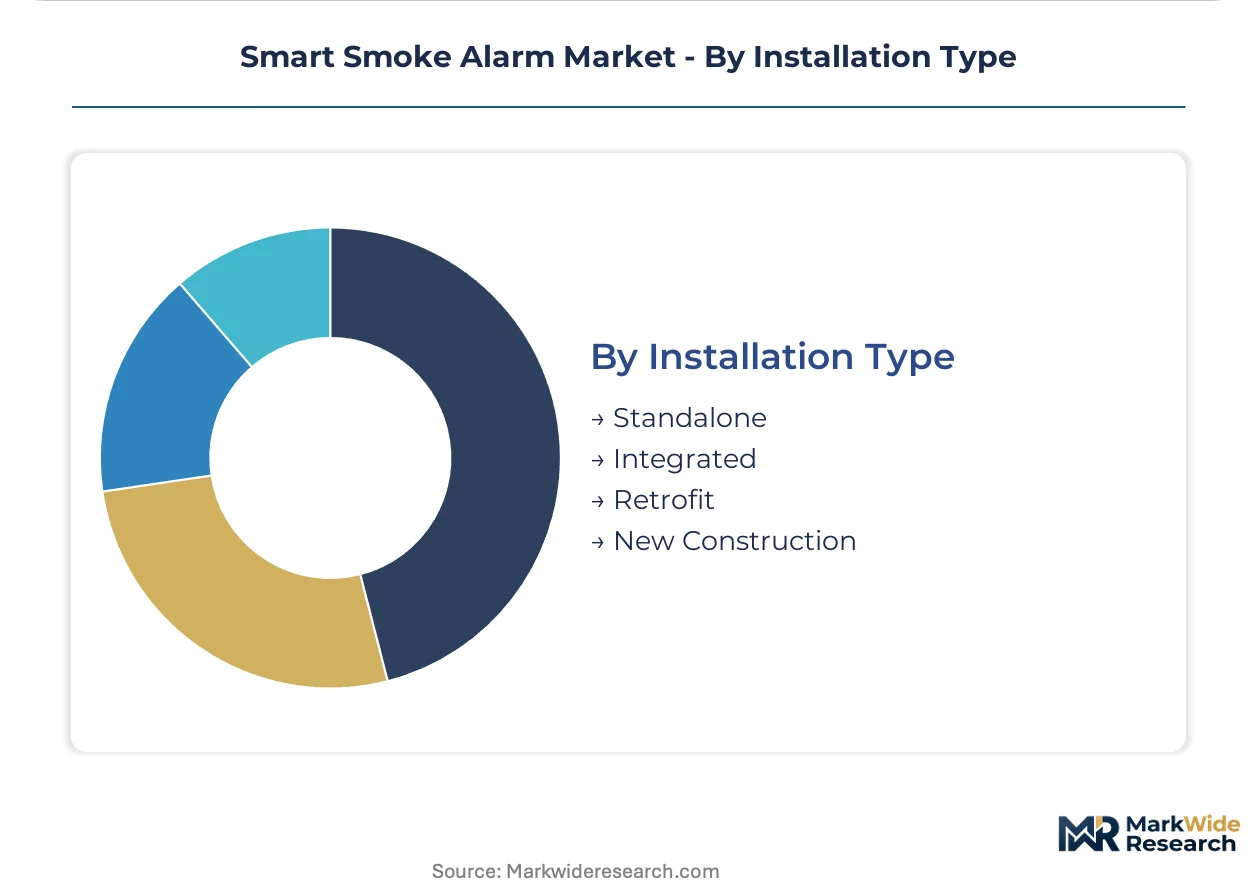
Smart smoke alarm segmentation reveals how installation constraints, connectivity preferences, and regulatory mandates reshape procurement patterns across residential and commercial channels. Product type and technology choices increasingly determine channel access and margin structure for manufacturers.
Product Type:
Mature hardwired configurations dominate commercial specifications while emerging connected architectures capture residential retrofit momentum.
- Wi-Fi-Connected:These units transmit alerts directly to mobile applications and central monitoring stations without hub dependencies. Demand concentrates in North American suburban markets where homeowners prioritize smartphone integration and insurance premium discounts drive replacement decisions.
- Hardwired:AC-powered installations with battery backup satisfy NFPA 72 interconnect mandates in multi-story dwellings. New construction specifications across the United States favor these units for compliance certainty and reduced long-term maintenance liability.
- Battery-Operated:Standalone units with 10-year sealed lithium batteries serve rental properties and legacy retrofit scenarios where electrical contractor involvement is impractical.
- Bluetooth-Enabled:Mesh-networked devices leverage smartphone proximity for localized alerts, finding niche adoption in European apartment configurations where Wi-Fi infrastructure is shared or unreliable.
Hardwired configurations retain volume leadership; Wi-Fi-connected units hold the steepest expansion curve.
End User:
Cost tier differentiation separates premium monitored services from self-installed economy alternatives across customer categories.
- Residential:Single-family homeowners and multi-family tenants constitute the primary demand pool, with retrofit replacement cycles accelerating as legacy ionization units reach obsolescence. German and Japanese insurance incentives are converting cost-sensitive households to connected detection systems.
- Commercial:Office buildings, retail establishments, and hospitality properties require centralized monitoring integration and documented compliance with local fire codes. These installations demand professional specification and recurring service contracts.
- Industrial:Manufacturing facilities and warehouse operations prioritize ruggedized housings and integration with building management systems for coordinated emergency response.
- Public Spaces:Schools, healthcare facilities, and transportation hubs face stringent nuisance-alarm thresholds that favor photoelectric and multi-sensor technologies with algorithmic false-alarm suppression.
Residential channels retain volume leadership; commercial applications hold the steepest expansion curve.
Technology:
Application requirements across smoldering versus flaming fire detection are displacing legacy sensor architectures.
- Photoelectric:Light-scattering detection arrays identify slow-burning, smoldering combustion with superior accuracy to ionization alternatives. New construction specifications in the United States and Western Europe now mandate this technology for reduced false-alarm liability.
- Dual-Sensor:Combined photoelectric and ionization chambers address both smoldering and fast-flaming fire signatures. Machine-learning-based particle classification is virtualizing this hardware configuration into single-chamber designs, compressing cost structures for mid-market producers.
- Ionization:Americium-241 based detection for fast-flaming fires is being phased out of residential specifications due to radioactive material handling concerns and inferior smoldering-fire performance.
- Multi-Functional:Integrated carbon monoxide and particulate matter sensing captures margin pools in premium installations by virtualizing standalone air quality monitors.
Photoelectric technology retains volume leadership; multi-functional devices hold the steepest expansion curve.
Installation Type:
Volume concentration in retrofit channels reflects compressed replacement cycles for aging ionization inventories.
- Retrofit:Replacement of standalone legacy units in existing structures dominates current demand, driven by NFPA 72 interconnect mandates and homeowner insurance incentives. Electrical contractor involvement for hardwired retrofits complicates consumer-direct sales models.
- New Construction:Pre-wire specifications during building development enable cost-effective hardwired and integrated system deployment. Developers prioritize photoelectric and dual-sensor units to meet stringent nuisance-alarm thresholds and reduce callback liability.
- Standalone:Battery-operated units without interconnect capability serve legacy installations and jurisdictions without updated fire codes, though regulatory pressure is eroding this segment.
- Integrated:Hardwired devices connected to broader building automation and security systems capture commercial and high-end residential specifications with recurring monitoring revenue potential.
Retrofit installations retain volume leadership; integrated systems hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach container complex underwrites North American distribution capacity for connected fire safety devices, while Shenzhen's Yantian port anchors component export flows to assembly operations worldwide.
United States
Retrofit replacement cycles accelerate as NFPA 72 interconnect mandates force multi-story dwelling upgrades. The EPA oversees flame retardant substance evaluations affecting polymer housing formulations. Installer networks concentrate in Dallas-Fort Worth and Atlanta metropolitan corridors where electrical contractor density supports hardwired retrofit demand.
Germany
Property insurers in Baden-Württemberg and Bavaria document premium discounts for connected detection systems, converting cost-sensitive households. ECHA administers REACH substance restrictions on halogenated flame retardants in polymer housings. Testing laboratories in Munich report extended certification timelines for revised housing compounds, compressing seasonal retail launch windows.
Japan
Smart home penetration and insurance premium incentives align to drive residential adoption in Greater Tokyo and Osaka metropolitan areas. METI oversees building equipment standards and IoT device interoperability frameworks. Manufacturing clusters in Aichi Prefecture supply photoelectric sensor arrays to regional assembly operations.
United Kingdom
Electrical wholesalers and security integrators develop underdeveloped routes for connected fire safety with recurring monitoring revenue potential. The Building Safety Regulator enforces updated fire safety standards for multi-occupancy residential structures. Installer certification programs concentrate in Manchester and Birmingham logistics corridors.
China
The IoT sensor manufacturing corridor in Shenzhen and Dongguan rewrites component economics for smart smoke alarm producers worldwide. MIIT governs wireless device certification for 2.4 GHz Wi-Fi and Bluetooth Low Energy frequencies. Yangtze River Delta assembly operations supply photoelectric sensing modules to branded device manufacturers across export markets.
Smart Smoke Alarm Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensing and connectivity modules. The vendor base organizes around three strategic archetypes: building automation conglomerates with fire safety heritage, consumer electronics platforms leveraging smart home ecosystems, and regional electrical equipment specialists with installer channel control. Consolidation pressure operates through vertical acquisition of sensing technology and strategic partnerships for Matter protocol certification.
Among building automation conglomerates, Honeywell International Inc., Johnson Controls International Plc, and Robert Bosch GmbH occupy positions that exemplify divergent competitive approaches to channel architecture and technology integration. These entities represent the established tier where building automation heritage and professional installer relationships anchor market presence.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Johnson Controls International Plc |
| Robert Bosch GmbH |
| Siemens AG |
| Hochiki Corporation |
| Nest Labs (Google/Alphabet) |
| Schneider Electric SE |
| Resideo Technologies Inc. |
| Samsung Electronics Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's Yantian port and Dongguan manufacturing corridor anchor photoelectric sensor module production, concentrating component supply leverage among tier-one device assemblers while compressing margin pools for mid-market brands dependent on spot-market Wi-Fi chipset procurement.
Pricing Analysis
NFPA 72 and EU Construction Products Regulation dictate the pricing tier structure by mandating dual ETL-UL certification for North American market access, separating premium integrated-system vendors from economy battery-operated competitors. Three-tier pricing structure across premium monitored-service, standard Wi-Fi-connected, and economy standalone battery units reflects certification burden and after-sales bundling intensity. Cost compression in the mid-tier is intensifying because REACH substance restrictions on halogenated flame retardants force housing reformulation and extended laboratory validation. Residential retrofit buyers exhibit highest price sensitivity, while commercial property managers prioritize compliance certainty over unit economics.
Supply Chain Analysis
Photoelectric sensing arrays and 2.4 GHz connectivity chipsets feed from Taiwan foundry capacity, Chinese polymer compounding operations, and Japanese precision optical component specialists. Wi-Fi and Bluetooth Low Energy semiconductor fabrication concentrates in Taiwan, with Yangtze River Delta packaging and testing operations completing module assembly. Single-source vulnerability in Taiwan foundry allocation exposes producers to extended lead time volatility during demand spikes. Distribution runs through electrical wholesaler networks in Europe and security integrator channels in North America, with direct-to-consumer e-commerce capturing residential retrofit volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as NFPA 72 retrofit mandates force replacement waves across multi-story residential stock, compressing replacement cycles that typically span ten to fifteen years into accelerated five-to-seven-year windows.
For Market Incumbents: Harden certification portfolios against evolving Matter interoperability specifications to defend retail shelf placement against consumer electronics platforms entering through white-label broadband provider arrangements. Deepen backward integration into photoelectric sensor module production to reduce exposure to Taiwan foundry allocation volatility and capture margin compression from Chinese component specialists.
For New Entrants and Emerging Players: European electrical wholesaler channels in France and the Netherlands offer underpenetrated routes for connected fire safety with recurring monitoring revenue potential, bypassing saturated North American retail and e-commerce concentration. Target professional installer segments through pre-certified REACH-compliant housing inventories to exploit extended German laboratory validation timelines that disadvantage seasonal launch cycles of established competitors.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because fire code interconnect mandates create non-discretionary replacement demand insulated from discretionary consumer spending volatility. Acquisition candidates with Matter protocol certification progress and established European wholesaler relationships command strategic premium. Monitor ECHA substance restriction expansion timelines as inflection signals for housing material transition capex requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Retail shelf placement and smart home ecosystem eligibility hinge on interoperability validation against emerging standards. |
| Backward Integration into Sensor Modules | Captive photoelectric array production reduces Taiwan foundry dependency and stabilizes margin structure against allocation volatility. |
| Professional Installer Channel Development | European electrical wholesaler relationships unlock recurring monitoring revenue streams absent in consumer-direct models. |
| REACH-Compliant Housing Pre-Validation | Pre-certified phosphorus-based polymer compounds accelerate launch timelines against German laboratory bottlenecks. |
| Multi-Sensor Convergence R&D | Carbon monoxide and particulate matter integration captures premium residential margin pools by virtualizing standalone air quality monitors. |
Research Methodology
Initial hypotheses were tested against primary input from fire safety product managers, electrical contractor network heads, property insurance risk assessors, and smart home platform engineers, and refined through secondary validation against NFPA technical documentation, ECHA substance restriction databases, UL certification registries, and customs trade flow records. Bottom-up demand modeling triangulated against top-down macroeconomic drivers.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning connectivity architecture, sensor technology type, installation scenario, and end-user category. CAGRs were derived from replacement cycle velocity analysis and regulatory mandate implementation schedules. Forecast inputs incorporated insurance premium incentive diffusion rates and Matter protocol adoption curves.
Practitioners should monitor Taiwan semiconductor foundry utilization rates and ECHA halogenated flame retardant restriction expansion timelines for early signals of supply constraint or material transition cost spikes. Cross-checking against UL certification database growth rates and property insurance connected-device discount program rollouts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Global Fixed Firefighting Misting System Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Portable Fire Extinguisher Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market