
 Fire Fighting Foam Market | 2026-2036
Fire Fighting Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Fighting Foam Market Intelligence
Aftermarket foam testing and re-certification services is rewriting profit pools away from bulk concentrate sales. Johnson Controls International leverages its installed base of fire suppression systems to capture recurring inspection revenue. Perimeter Solutions anchors its position through backward integration into fluorosurfactant chemistry. Angus Fire competes on geographic reach across Commonwealth port authorities and offshore platforms.
Fire fighting foam comprises stabilized aqueous solutions containing hydrocarbon surfactants, fluorosurfactants, or protein hydrolysates that reduce water surface tension to form vapor-suppressing blankets over flammable liquid pools; formulations typically achieve expansion ratios of 6:1 to 20:1 depending on proportioning system design. Fluorine-free foam represents the fastest-growing product category as military and aviation end users phase out legacy AFFF stocks under emerging PFAS restrictions. Synthetic foam dominates industrial firefighting applications where hydrocarbon fuel fires require rapid knockdown. Oil and gas applications sustain premium pricing due to offshore platform certification requirements and specialized marine delivery systems.
The U.S. EPA has issued health advisories for PFOA and PFOS in drinking water that compel Department of Defense facilities and municipal fire departments to inventory and replace legacy AFFF stocks. The EU REACH regulation and forthcoming PFAS restriction proposal are accelerating fluorine-free formulation adoption across European airports and chemical plants. Military procurement through NATO standardization agreements is shifting specifications toward C6-based or fluorine-free alternatives. Stakeholders must monitor regulatory divergence between jurisdictions where compliance timelines and allowable chemistries differ, as this will determine which product portfolios retain market access and which require reformulation investment.
Market Dynamics
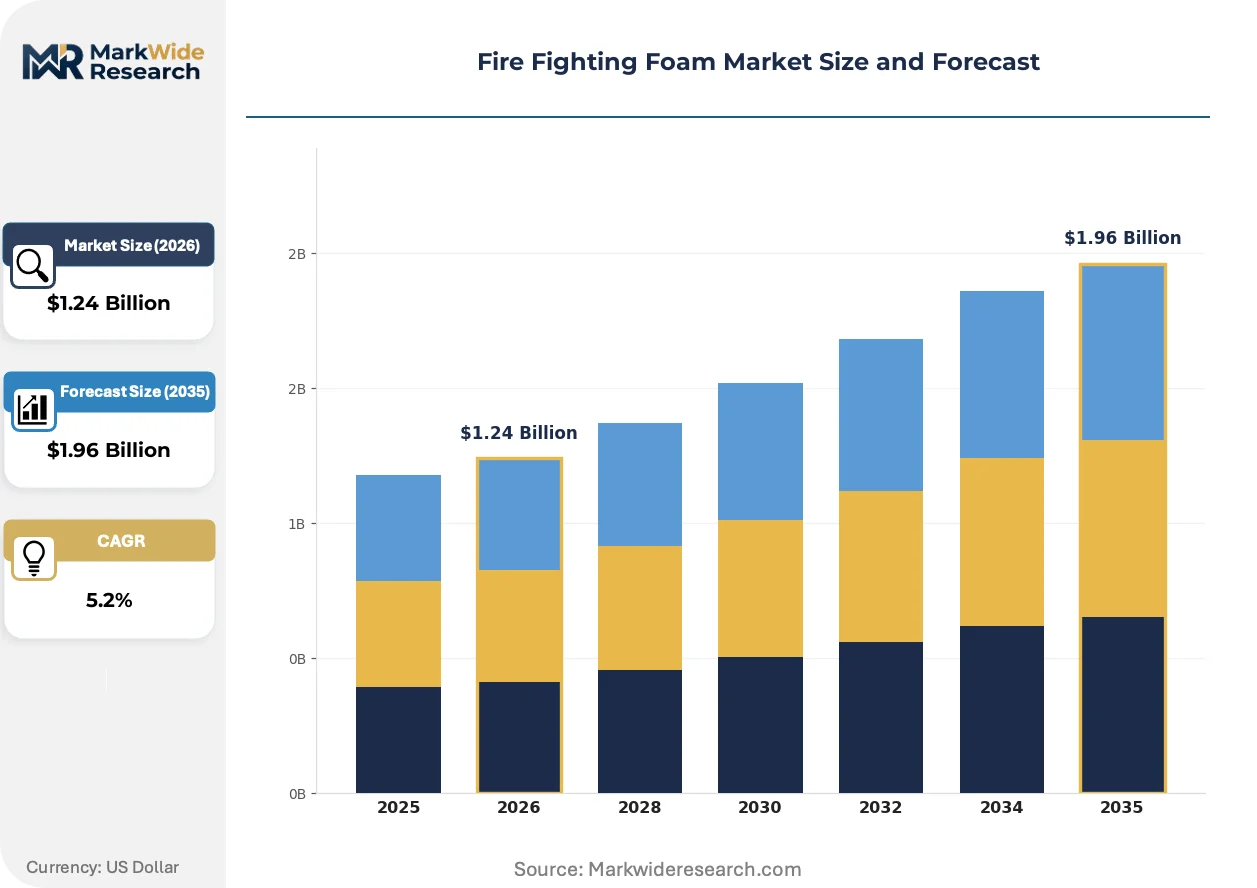
The fire fighting foam market is undergoing forced formulation turnover as PFAS restrictions eliminate legacy AFFF chemistries and military aviation buyers accelerate fluorine-free procurement timelines.
Growth Catalysts
- EU REACH PFAS restriction:The European Chemicals Agency's proposed ban on per- and polyfluoroalkyl substances is compelling airport fire departments across Germany, France, and the Netherlands to replace existing foam stocks with fluorine-free alternatives.
- Military aviation:NATO standardization agreements are rewriting procurement specifications to favor C6-based and fluorine-free formulations, creating immediate demand at air force bases and naval installations.
- Protein hydrolysate innovation:Advances in synthetic protein foam chemistry are closing performance gaps with fluorinated products in hydrocarbon fire suppression applications.
Market Restraints
- Fluorosurfactant supply concentration:Three chemical manufacturers control the majority of long-chain fluorosurfactant production, creating input vulnerability as regulations phase out these compounds.
- Reformulation capex burden:Foam producers must rebuild R&D pipelines and retool manufacturing lines to achieve equivalent vapor suppression without PFAS chemistry.
- Certification timeline friction:UL and EN standards for fluorine-free foams require extended fire testing protocols that delay product commercialization by 18-24 months versus legacy approvals.
Strategic Opportunities
- India aviation infrastructure:Greenfield airport construction under the country's regional connectivity scheme is creating first-mover advantage for fluorine-free foam specification.
- Offshore wind platforms:Emerging marine renewable energy installations require specialized fire suppression for transformer fluids and hydraulic oils in salt-air environments.
- Digital testing platforms:Remote foam proportioning verification and cloud-based certification tracking are opening recurring revenue streams independent of concentrate volume sales.
Industry Challenges
- PFAS remediation liability:Fire departments and military facilities face soil and groundwater cleanup obligations at training sites where legacy AFFF was discharged for decades.
- Formulation performance parity:Fluorine-free alternatives struggle to match the rapid knockdown and burnback resistance of AFFF on polar solvent fires without additive complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Fighting Foam Market |
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $1.96 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Foam, Fluorine-Free Foam, Aqueous Film-Forming Foam, Synthetic Foam Application: Industrial Firefighting, Aviation, Marine, Oil & Gas End User: Fire Departments, Military, Oil Refineries, Airports Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Dafo Fomtec AB, Dr. Sthamer, Johnson Controls International, Kerr Fire, Chemguard, Perimeter Solutions, National Foam, SFFECO Global, Angus Fire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Fighting Foam Market Strategic Shifts & Innovations
Formulation chemistry, regulatory compliance architecture, and service delivery models are converging to restructure how fire suppression capabilities are procured and maintained.
Smart proportioning systems are digitizing foam delivery accuracy through real-time flow monitoring and automated concentration adjustment. Major aviation hubs in the United States and United Arab Emirates are deploying these systems to reduce foam waste and ensure regulatory compliance during emergency response. This digitizing of proportioning control is compressing the aftermarket service window from annual calibration to continuous remote diagnostics.
The U.S. EPA's drinking water health advisories for PFOA and PFOS are forcing Department of Defense facilities to inventory and replace legacy AFFF stocks ahead of formal mandate schedules. Military procurement officers are now requiring C6-based or fluorine-free alternatives in all new specifications. This regulatory pressure is most acute at U.S. Air Force installations where training exercises previously consumed millions of gallons of legacy foam annually.
Aviation fire departments are unbundling foam testing and re-certification from concentrate purchase agreements, treating these as separate procurement line items. This shift is displacing bundled supply contracts with multi-vendor service arrangements at major hubs including London Heathrow and Singapore Changi. German airport authorities have been earliest adopters, mandating third-party verification of foam performance regardless of original supplier.
Fire Fighting Foam Market Segmentation
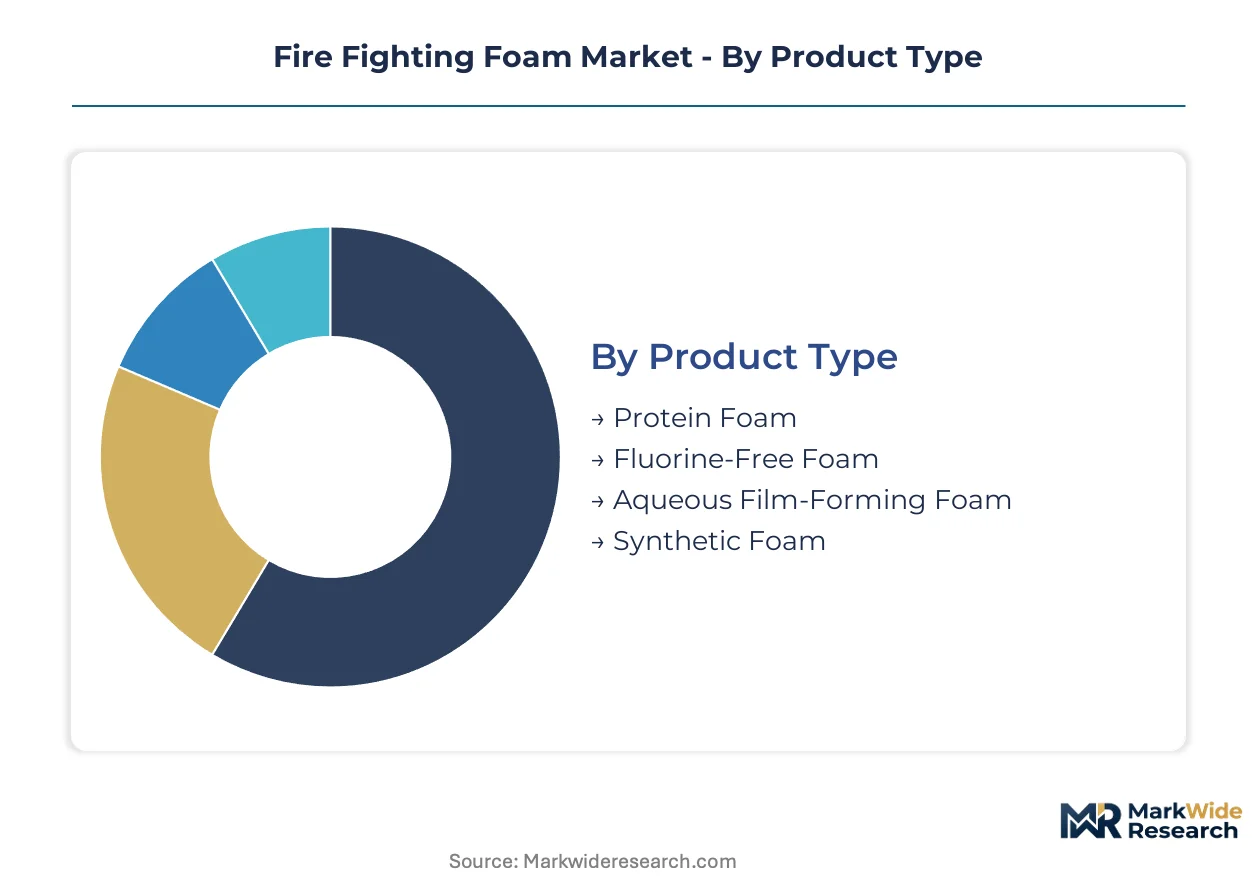
Fire fighting foam procurement patterns diverge sharply across product chemistry, deployment environment, and buyer sophistication. Understanding these segment boundaries reveals where formulation premiums hold and where commoditization pressures concentrate.
Product Type:
Mature fluorinated chemistries now compete with emerging fluorine-free alternatives as regulatory deadlines force portfolio restructuring across manufacturers.
- Fluorine-Free Foam:Formulations rely on hydrocarbon surfactants and synthetic protein hydrolysates to achieve vapor suppression without PFAS chemistry. Aviation hubs in Germany and France are mandating these alternatives under ECHA restriction timelines, though polar solvent performance gaps persist against legacy products.
- Aqueous Film-Forming Foam:Legacy AFFF utilizes fluorosurfactants to create thin aqueous films that spread rapidly across hydrocarbon surfaces. Military installations face accelerated stockpile phase-outs as EPA drinking water advisories tighten liability exposure at training sites.
- Protein Foam:Derived from hydrolyzed protein sources with natural foam stabilizers; excels in deep-seated fuel fires through radiant heat resistance. Preferred at industrial facilities with established protein foam infrastructure.
- Synthetic Foam:Engineered hydrocarbon surfactant blends delivering rapid knockdown for hydrocarbon pool fires without fluorine content. Dominates industrial firefighting where fuel type predictability reduces formulation complexity requirements.
Aqueous Film-Forming Foam handles the majority of installed base volume; Fluorine-Free Foam is expanding most quickly as procurement specifications rewrite.
Application:
Application segmentation tracks hazard severity gradients and certification burden intensity across deployment environments.
- Aviation:ARFF operations demand ICAO Level B foam performance with rapid extinguishment of jet fuel fires. NATO standardization agreements are rewriting military aviation specifications toward C6-based or fluorine-free alternatives, creating immediate specification churn at air force bases.
- Oil & Gas:Offshore platforms and refineries require specialized marine delivery systems and sub-surface injection capability. Premium pricing sustains here due to UL/FM certification requirements and salt-air corrosion resistance specifications.
- Industrial Firefighting:Manufacturing facilities and chemical plants deploy foam for hydrocarbon storage protection and process area coverage. Procurement emphasizes bulk concentrate value and proportioning system compatibility over specialized performance metrics.
- Marine:Port authorities and vessel operators face SOLAS compliance requirements with foam systems integrated into deck-mounted monitors. Commonwealth port authorities maintain distinct specification traditions influencing supplier selection.
Oil & Gas commands the steepest premium tier; Aviation is gaining share fastest on regulatory-forced replacement cycles.
End User:
End user segmentation reflects divergent procurement sophistication, with military and aviation buyers driving specification standards that cascade to municipal and industrial adopters.
- Military:Department of Defense facilities operate under congressional mandate timelines for AFFF elimination, with procurement officers now requiring C6 or fluorine-free in all new specifications. Training site remediation liabilities are accelerating inventory audits ahead of formal deadlines.
- Airports:ARFF departments at major hubs unbundle foam testing from concentrate purchase agreements, treating certification as separate procurement line items. German airport authorities mandate third-party verification regardless of original supplier.
- Fire Departments:Municipal responders face budget constraints that slow fluorine-free transition despite EPA advisory pressure. Consolidated procurement through state cooperative contracts dominates volume acquisition.
- Oil Refineries:Downstream operators prioritize foam compatibility with existing proportioning infrastructure and storage tank specifications. Turnaround maintenance windows drive concentrated demand spikes.
Fire Departments represent the largest addressable population; Military is climbing the fastest on accelerated compliance investment.
Distribution Channel:
Channel structure varies with buyer scale and technical service requirements, with direct relationships dominating specification-sensitive accounts.
- Direct Sales:Manufacturers maintain field engineering relationships with major aviation hubs, military installations, and integrated oil companies. Technical consultation on proportioning system integration and certification compliance anchors these partnerships.
- Distributors:Regional chemical and safety distributors serve mid-size industrial accounts and municipal fire departments with consolidated product portfolios. Inventory positioning near major metropolitan areas supports emergency replenishment requirements.
- Resellers:Specialized fire protection contractors resell foam as component of system installation and maintenance contracts. Value-add concentrates on proportioning system calibration and annual certification services.
- Online Retail:E-commerce channels capture small-volume replacement orders and training foam purchases for academies and demonstration facilities. Limited to standardized formulations without custom blending requirements.
Direct Sales captures the highest-value specification-driven transactions; Distributors maintains broadest geographic coverage density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluorosurfactant manufacturing clusters in Germany and the United States anchor upstream supply, while airport procurement mandates in France and the Netherlands accelerate downstream formulation turnover. Military aviation compliance timelines and EPA drinking water advisories are rewriting inventory replacement schedules across NATO installations.
United States
Department of Defense facilities face congressional mandate timelines for AFFF elimination, with procurement officers requiring C6 or fluorine-free alternatives in all new specifications. EPA drinking water health advisories for PFOA and PFOS compel municipal fire departments to inventory legacy stocks. U.S. Air Force installations in Florida and California accelerate training site remediation ahead of formal deadlines.
Germany
Airport fire departments across Frankfurt, Munich, and Hamburg mandate fluorine-free foam specifications under ECHA restriction timelines. The country's national chemical regulator advances PFAS assessment protocols that compress product approval windows. Industrial clusters along the Rhine corridor retrofit storage tank protection systems to accommodate synthetic protein formulations.
France
Roissy-Charles de Gaulle and Orly airports unbundle foam testing from concentrate purchase agreements, treating certification as separate procurement line items. ECHA REACH restrictions on per- and polyfluoroalkyl substances eliminate legacy AFFF chemistries from aviation specifications. Marseille-Fos port authorities maintain distinct Commonwealth specification traditions influencing supplier selection for marine applications.
United Arab Emirates
Dubai International and Abu Dhabi airports deploy smart proportioning systems with real-time flow monitoring to reduce foam waste during emergency response. The country's civil aviation regulator aligns with ICAO Level B performance standards while evaluating fluorine-free alternatives. Offshore platform operators in the Arabian Gulf sustain premium pricing for specialized marine delivery systems.
India
Greenfield airport construction under the regional connectivity scheme creates first-mover advantage for fluorine-free foam specification at aviation hubs. The Bureau of Indian Standards develops domestic certification protocols for synthetic protein formulations. Industrial corridors in Gujarat and Maharashtra retrofit chemical plant fire suppression infrastructure to accommodate hydrocarbon surfactant blends.
Fire Fighting Foam Market Key Industry Players
Integrated fire protection conglomerates and specialized chemical manufacturers split the market between system-level service bundling and formulation chemistry expertise. Three strategic archetypes dominate: diversified industrial conglomerates leveraging installed base relationships, fluorosurfactant specialists with backward integration into raw material supply, and regional distributors capturing municipal procurement through cooperative contracts. Competitive moves concentrate on geographic expansion into aviation hub markets and portfolio diversification toward fluorine-free alternatives.
Within the diversified conglomerate tier, Johnson Controls International occupies a position anchored by fire suppression system integration and recurring inspection revenue capture. Among European formulation specialists, Dafo Fomtec AB and Dr. Sthamer exemplify the geographic reach archetype across Commonwealth port authorities and North Sea offshore platforms. Perimeter Solutions represents the upstream-integrated model through captive fluorosurfactant chemistry capabilities.
| Leading Market Players |
|---|
| Dafo Fomtec AB |
| Dr. Sthamer |
| Johnson Controls International |
| Kerr Fire |
| Chemguard |
| Perimeter Solutions |
| National Foam |
| SFFECO Global |
| Angus Fire |
| Others |
Cost & Logistics Intelligence
Rhineland chemical clusters in Germany anchor fluorosurfactant production capacity, and their regulatory-driven phase-out timelines compress pricing power into synthetic protein and hydrocarbon surfactant alternatives. Buyers at NATO military installations and German airport fire departments face accelerated cost absorption as ECHA restrictions eliminate legacy supply options.
Pricing Analysis
EU REACH PFAS restrictions dictate the pricing tier structure across the fire fighting foam market. Three-tier pricing structure across aviation-certified premium, industrial-standard, and municipal-economy levels separates products by UL/FM certification grade and polar solvent performance capability. Price differentiation hinges on vapor suppression speed and burnback resistance metrics. Cost compression in municipal procurement tiers is intensifying because state cooperative contracts consolidate volume leverage. Fire departments represent the most price-sensitive segment, while offshore oil and gas operators accept premium positioning for marine delivery system compatibility.
Supply Chain Analysis
Export-control scrutiny on fluorinated chemistry feeds from concentrated fluorosurfactant manufacturing in Germany, the United States, and China. Raw material dependencies center on perfluoroalkyl acid precursors, synthetic protein hydrolysates, and specialized hydrocarbon surfactant blends. Supply chain risk rests on single-source vulnerability as three chemical manufacturers control long-chain fluorosurfactant production. Distribution runs through direct field engineering relationships with aviation hubs and military installations, supplemented by regional chemical distributors serving municipal fire departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fire fighting foam market operates as a defensive-moat industry where regulatory entrenchment creates high switching costs for certified formulations at aviation and military installations.
For Market Incumbents: Harden certification portfolio breadth by accelerating UL and EN standard approvals for fluorine-free alternatives before 18-24 month testing protocols delay commercialization. Secure backward integration into synthetic protein hydrolysate chemistry to offset fluorosurfactant supply concentration. Channel control through installed base fire suppression systems at major aviation hubs anchors recurring inspection revenue against concentrate commoditization. For New Entrants and Emerging Players: Greenfield airport construction across India's regional connectivity scheme represents the most penetrable entry point for fluorine-free specification without legacy infrastructure lock-in. Offshore wind transformer platforms in the North Sea offer white-space demand for salt-air corrosion-resistant marine delivery systems. Go-to-market execution should anchor on third-party testing and re-certification service unbundling, treating certification as separate procurement line items rather than bundled concentrate sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with captive synthetic surfactant chemistry capabilities over diversified conglomerates dependent on fluorosurfactant feedstock. Long-term viability across the next decade rests on R&D pipeline depth for polar solvent fire performance parity. The signal to monitor is NATO standardization agreement adoption velocity for C6-based and fluorine-free specifications at air force bases and naval installations.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Formulation R&D | Closes performance gaps with AFFF under ECHA REACH restriction timelines at European aviation hubs. |
| Backward Integration into Surfactant Chemistry | Captive supply of synthetic protein hydrolysates insulates margins from fluorosurfactant input volatility. |
| Smart Proportioning System Deployment | Real-time flow monitoring at Dubai International and Abu Dhabi airports reduces foam waste and ensures regulatory compliance. |
| Third-Party Certification Service Launch | Unbundled testing revenue at London Heathrow and Singapore Changi displaces bundled supply contract economics. |
| Offshore Wind Platform Specialization | Salt-air corrosion resistance specifications for North Sea transformer fluid suppression command premium pricing tiers. |
Research Approach
Initial hypotheses were tested against primary input from fire protection system engineers, airport procurement officers, military aviation logistics directors, and fluorosurfactant chemists and refined through secondary validation. Trade data from customs authorities, ECHA regulatory filings, NATO standardization agreement documentation, and SEC filings from diversified fire protection conglomerates anchored supply-side assessment. Bottom-up triangulation across foam concentrate volume flows and top-down reconciliation against aviation infrastructure investment databases ensured cross-verification.
Demand-supply-balance modeling across the projection horizon segmented by product chemistry, application environment, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from installation base replacement cycles, greenfield aviation infrastructure pipelines, and military compliance investment schedules. Forecast inputs incorporated ECHA restriction timeline phasing, EPA drinking water advisory enforcement intensity, and ICAO Level B performance standard adoption curves.
Stress conditions across PFAS regulatory acceleration, fluorosurfactant supply disruption, and aviation traffic recovery trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification timeline friction and reformulation capex burden. Material shifts in NATO procurement specification velocity or ECHA restriction implementation timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Africa Fire Suppression Market
Fire Safety & Protection
Passive Fire Proofing System Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
GCC Firefighting Foam Market
Fire Safety & Protection
Fire Protection Systems Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Global Fixed Firefighting Misting System Market