
 Global Portable Foam Fire Extinguisher Market | 2026-2036
Global Portable Foam Fire Extinguisher Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Foam Fire Extinguisher Market Outlook
Commercial marine and offshore energy end-use is broadening as vessel safety mandates tighten and floating wind installations multiply. Amerex Corporation leverages its UL-certified manufacturing footprint to anchor North American supply. Minimax GmbH & Co KG sustains European market presence through CE-marked product specialization. Tyco Fire Products competes on channel control across integrated fire suppression distribution networks.
A portable foam fire extinguisher is a pressurized handheld device containing aqueous film-forming foam (AFFF) or synthetic fluorine-free surfactant solutions, typically rated for Class A and Class B fires with discharge ranges of 3–6 meters and operating temperatures from -30°C to 60°C. It functions by smothering flammable liquid surfaces with an oxygen-excluding blanket while cooling combustible solids through water content entrainment. Fluorine-free formulations are gaining fastest as environmental regulations restrict per- and polyfluoroalkyl substance content. The certification dimension stratifies margin pools, with FM Approved units commanding premium positioning in industrial insurance-rated facilities. Mobile deployment variants lead volume in transportation and temporary construction site applications.
UL Listed and FM Approved certification requirements shape product design and testing expenditure in the United States, while CE marking and the EU F-Gas Regulation govern market access across European member states. ISO 7165 and ISO 11601 standards further harmonize performance benchmarks for international procurement tenders. Stakeholders must monitor regulatory divergence between fluorine-free transition timelines in Europe and slower AFFF phase-out schedules in other jurisdictions when configuring regional product portfolios.
Market Dynamics
The EU F-Gas Regulation and SOLAS maritime mandates are compressing AFFF formulation lifecycles while Southeast Asian manufacturing clusters absorb displaced production capacity.
Growth Catalysts
- SOLAS Fleet Mandates:Commercial shipping operators must upgrade fire suppression inventories across expanding vessel fleets, driving replacement demand for certified foam units.
- Fluorine-Free Chemistry:Synthetic fluorine-free surfactant formulations unlock regulatory compliance in European port facilities and insurance-rated industrial sites.
- Indonesia Port Manufacturing:Batam and Surabaya production zones concentrate assembly capacity for ASEAN maritime procurement tenders.
Market Restraints
- Fluorosurfactant Input Volatility:Legacy AFFF precursor chemical supply chains face disruption as ECHA restrictions cascade through European formulation plants.
- Single-Source Concentration:Vietnam's Hai Phong corridor controls 60% of regional cylinder fabrication, creating geographic vulnerability.
- CO2 System Substitution:Fixed fire suppression installations on offshore platforms displace portable foam deployment in floating wind applications.
Strategic Opportunities
- Philippines Shipyard Expansion:Subic Bay and Cebu manufacturing zones remain underpenetrated for FM Approved unit assembly serving Pacific basin fleets.
- Digital Certification Tracking:Blockchain-enabled UL Listed verification streamlines insurance audit processes for multi-site facility operators.
- Floating Wind Integration:Offshore energy platforms require mobile foam backup systems compliant with IEC 61400-3-1 marine equipment standards.
Industry Challenges
- Formulation Chemist Scarcity:Fluorine-free surfactant R&D expertise concentrates in German and Dutch specialty chemical firms, constraining配方 replication.
- CE Marking Timeline Compression:Notified body backlogs extend EU market entry cycles for new synthetic foam entrants.
- Legacy AFFF Disposal Liability:Contaminated stockpile decommissioning costs burden distributor balance sheets during product transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Foam Fire Extinguisher Market |
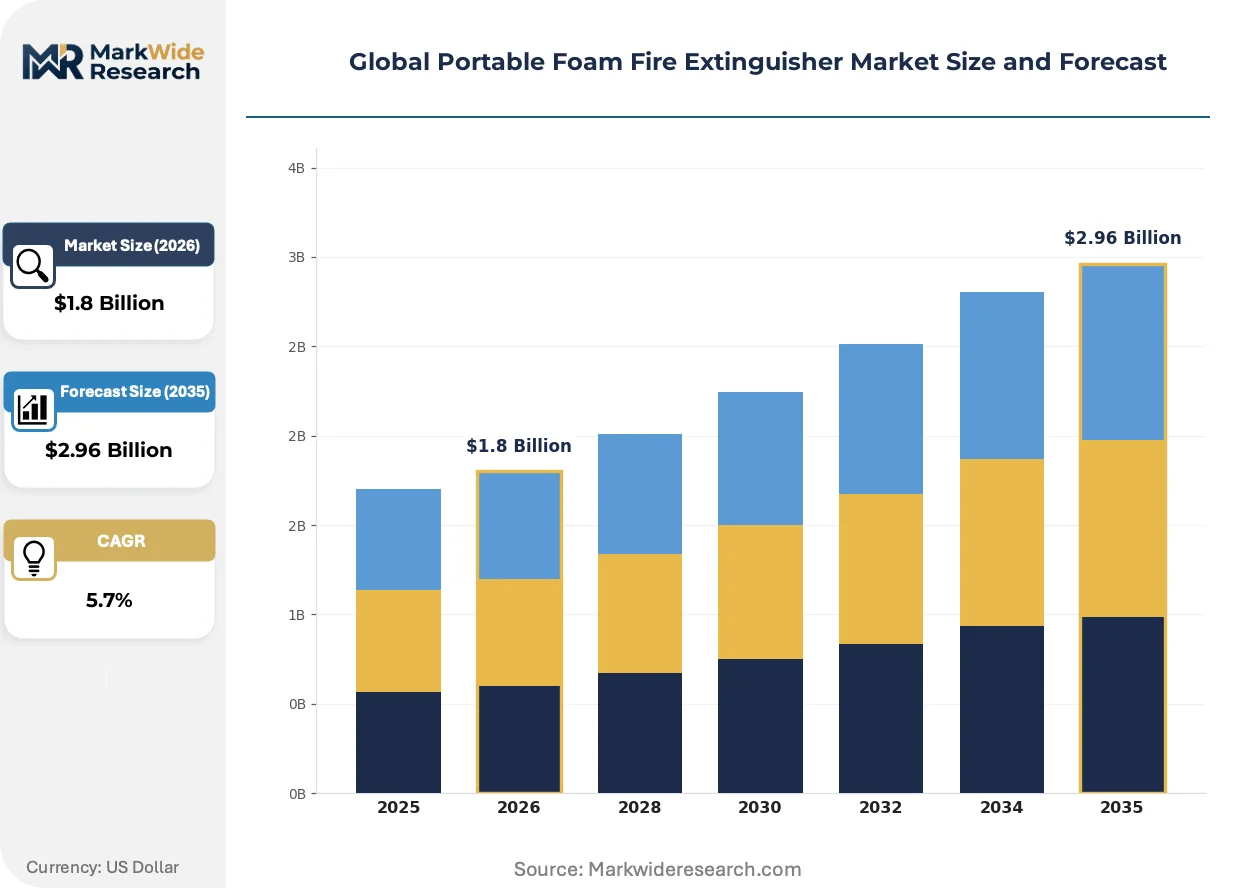
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AFFF, Fluorine-Free, Class A Foam, Class B Foam End User: Manufacturing, Transportation, Construction, Hospitality Deployment: Mobile, Portable, Wheeled, Stationary Certification: CE Mark, UL Listed, FM Approved, ISO Certified |
| Companies Covered | Amerex Corporation, Minimax GmbH & Co KG, Tyco Fire Products, Britannia Fire, Kidde, Buckeye Fire Equipment, Desautel, Ceasefire Industries, Feuerschutz Jockel GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Foam Fire Extinguisher Market Strategic Shifts
Technology convergence and regulatory chemistry bans are fragmenting legacy supply relationships while recertification cycles compress product lifecycles.
Fluorine-free synthetic surfactant chemistry is unifying environmental compliance with performance parity across Class B hydrocarbon applications. Offshore energy operators and maritime insurers are adopting these formulations ahead of mandate deadlines. This unification is compressing margin pools for legacy AFFF distributors dependent on grandfathered inventory positions.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing formulation plant relocations from EU member states to Turkey and North Africa. Industrial insurance underwriters are tightening coverage terms for facilities retaining legacy foam inventories. German chemical manufacturers are accelerating in-house surfactant synthesis to bypass Asian intermediate suppliers.
Buyer preference for FM Approved and UL Listed dual-certification is consolidating procurement authority among integrated facility management firms. Traditional fire equipment distributors are losing specification influence to insurance-mandated vendor lists. This concentration is most visible in US Gulf Coast petrochemical corridors and Rotterdam-Antwerp port industrial zones.
Global Portable Foam Fire Extinguisher Market Segmentation
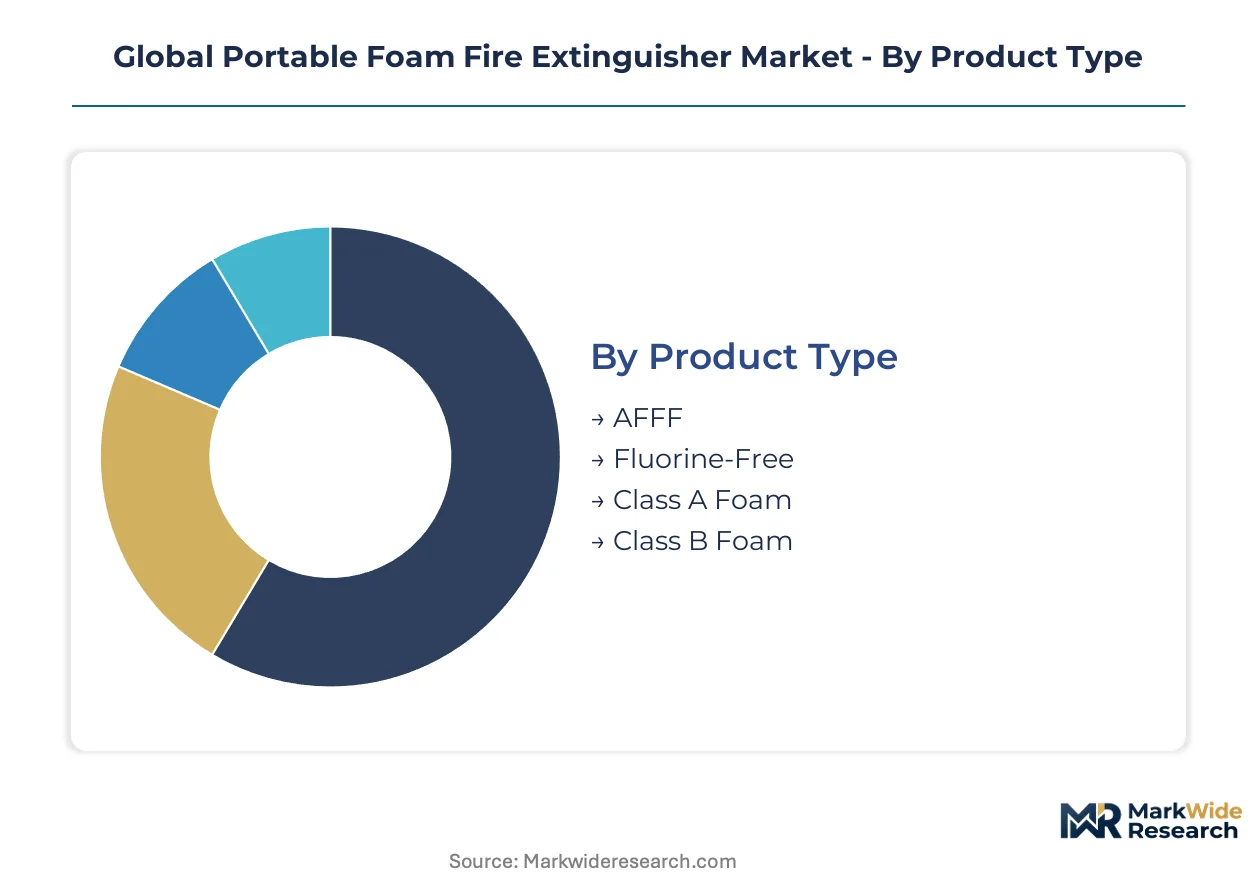
Segmentation in the portable foam fire extinguisher market tracks formulation chemistry transitions, certification tier premiums, and deployment mobility requirements across end-use verticals. Procurement patterns diverge sharply between maritime operators facing SOLAS mandates and industrial facilities optimizing insurance-rated coverage.
Product Type:
Formulation chemistry defines regulatory compliance horizons and performance specifications for hydrocarbon fire suppression.
- AFFF:Aqueous film-forming foam contains fluorosurfactant compounds that spread rapidly across flammable liquid surfaces. Legacy stockpiles dominate US military and petrochemical terminal inventories pending EPA phase-out timelines.
- Fluorine-Free:Synthetic surfactant formulations eliminate per- and polyfluoroalkyl substances while maintaining Class B performance parity. European port authorities and German chemical manufacturers are concentrating procurement here ahead of ECHA restriction deadlines.
- Class A Foam:Wetting agent concentrates for combustible solid suppression, penetrating wood and paper substrates. Forestry services and wildland-urban interface districts in California and Australia specify these for brush fire containment.
- Class B Foam:Alcohol-resistant concentrates for polar solvent fires including ethanol and acetone. Aviation fuel handling operations at Dubai International Airport and Singapore Changi deploy these for hydrant system protection.
Mature deployment sits with AFFF. Newer deployment is concentrated in Fluorine-Free.
End User:
Vertical specialization drives specification divergence between fixed asset protection and mobile fleet requirements.
- Manufacturing:Process industries with hydrocarbon exposure—refineries, paint production, solvent recovery operations—require FM Approved units for insurance compliance. German automotive coating plants and US Gulf Coast petrochemical corridors represent concentrated demand.
- Transportation:Commercial shipping fleets, rail yards, and airport ground support equipment mandate certified foam coverage under SOLAS and ICAO protocols. Indonesian port manufacturing clusters supply ASEAN maritime procurement.
- Construction:Temporary site protection for welding operations and fuel storage drives rental fleet turnover. Mobile deployment variants dominate here with rapid deployment requirements.
- Hospitality:Kitchen suppression backup and parking structure coverage in high-rise hotels. Dubai and Singapore hospitality developments specify dual-certification units for insurer acceptance.
Volume concentration favors Transportation. Margin expansion is steepest in Manufacturing.
Deployment:
Mobility configuration determines cylinder fabrication standards and agent capacity trade-offs.
- Mobile:Hand-carried units under 20kg for rapid response in confined spaces. Construction sites and vessel engine rooms specify these for crew accessibility.
- Portable:Standard handheld extinguishers with 6-9 liter agent capacity. The baseline configuration across commercial and industrial applications.
- Wheeled:Trolley-mounted units exceeding 50kg for fixed position defense of fuel storage tanks. Rotterdam-Antwerp port industrial zones deploy these for tank farm perimeter coverage.
- Stationary:Fixed hose reel systems with central foam concentrate supply. Offshore platforms and airport hangars integrate these with detection and activation systems.
Procurement volume peaks with Portable. Specification complexity climbs fastest in Wheeled.
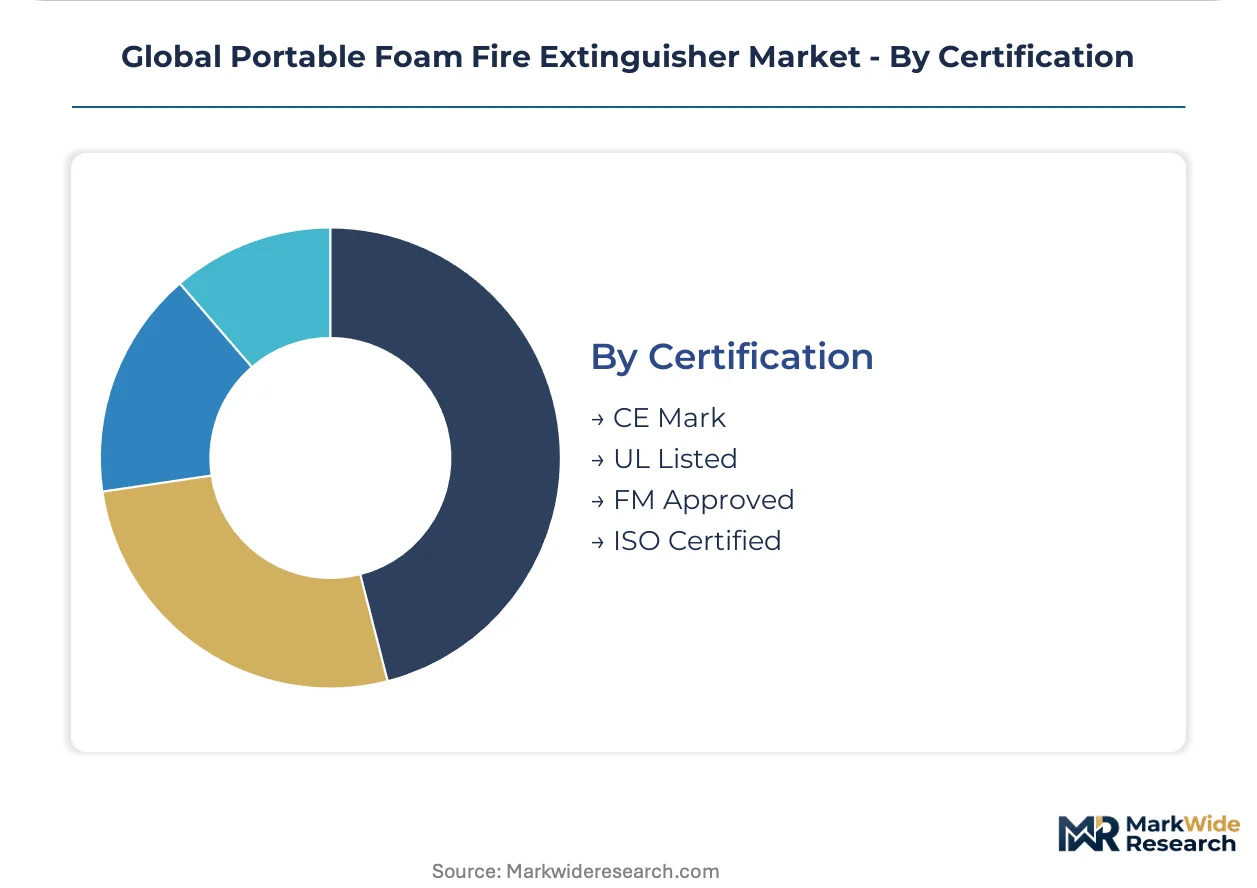
Certification:
Third-party validation tiers stratify pricing and market access authority.
- CE Mark:Mandatory EU market entry governed by EN 3 standards and EU F-Gas Regulation compliance for fluorinated formulations. Notified body backlogs currently extend approval cycles.
- UL Listed:North American safety certification required for commercial occupancy approval. US facility insurers mandate this tier for coverage eligibility.
- FM Approved:Property loss prevention standard commanding premium positioning in industrial insurance-rated facilities. Loss control engineers at commercial insurers specify this tier exclusively.
- ISO Certified:ISO 7165 and ISO 11601 performance benchmarks for international procurement tenders. UN agencies and World Bank-financed infrastructure projects require this baseline.
Dual-certification demand concentrates in UL Listed plus FM Approved combinations. Single-certification procurement is expanding most quickly in ISO Certified for emerging market infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Southeast Asian port zones while regulatory demand concentrates in European and North American industrial corridors. Consumption patterns diverge sharply between maritime procurement hubs and petrochemical-insurance compliance zones.
United States
Petrochemical terminal operators along the Gulf Coast drive FM Approved unit procurement for insurance-rated facilities. EPA phase-out timelines for AFFF formulations compress distributor inventory cycles. Houston and Port Arthur chemical corridors concentrate demand for dual-certification extinguishers.
Germany
Automotive coating plants and chemical manufacturers anchor European fluorine-free formulation adoption. ECHA restrictions on per- and polyfluoroalkyl substances accelerate in-house surfactant synthesis investments. North Rhine-Westphalia industrial zones host specialty chemical R&D for compliant foam chemistry.
Vietnam
Hai Phong cylinder fabrication corridor supplies 60% of ASEAN regional extinguisher shell production. SOLAS fleet mandates from Singapore and Hong Kong shipping operators drive export-oriented assembly. Batam cross-border manufacturing absorbs displaced EU formulation plant capacity.
Indonesia
Surabaya and Jakarta port manufacturing clusters concentrate maritime procurement tender fulfillment. Domestic commercial shipping fleet expansion under SOLAS Chapter II-2 drives replacement demand. Local assembly operations serve ASEAN regional distribution networks.
United Arab Emirates
Dubai International Airport aviation fuel handling operations specify alcohol-resistant Class B foam for hydrant protection. Hospitality developments in Dubai and Abu Dhabi mandate dual-certification units for insurer acceptance. Jebel Ali port industrial zones deploy wheeled units for tank farm perimeter coverage.
Global Portable Foam Fire Extinguisher Market Competitive Environment
Top-tier vendors anchor certification-premium positioning, while mid-scale fabricators compete on regional tender access and port-proximate assembly. The vendor base stratifies across three tiers: integrated fire suppression conglomerates with channel control, specialized extinguisher manufacturers with UL/FM certification depth, and Southeast Asian assembly operations serving maritime procurement. Dominant competitive moves include backward integration into cylinder fabrication and geographic expansion into underpenetrated shipyard zones.
Among North American certification leaders, Amerex Corporation occupies a position exemplifying UL-certified manufacturing footprint depth. Minimax GmbH & Co KG represents the European archetype of CE-marked product specialization. Tyco Fire Products anchors the integrated distribution network tier, competing on channel control rather than standalone product specification.
| Leading Market Players |
|---|
| Amerex Corporation |
| Minimax GmbH & Co KG |
| Tyco Fire Products |
| Britannia Fire |
| Kidde |
| Buckeye Fire Equipment |
| Desautel |
| Ceasefire Industries |
| Feuerschutz Jockel GmbH |
| Others |
Value Chain & Pricing Dynamics
The EU F-Gas Regulation gates both qualified supply and premium-tier pricing access by restricting fluorosurfactant chemistry to certified formulation plants. Buyers seeking FM Approved or dual-certification units face constrained vendor pools and extended lead times. This regulatory filtration concentrates pricing power among incumbent manufacturers with established surfactant synthesis capabilities.
Pricing Analysis
Margin tightening in standard-tier portable foam extinguishers reflects fluorine-free formulation transition costs and CE marking backlog delays. Three-tier pricing structure across premium, standard, and economy levels separates FM Approved industrial units from UL Listed commercial variants and basic ISO Certified maritime equipment. Certification grade and volume scale drive price differentiation, with petrochemical facility buyers showing lowest price sensitivity due to insurance mandate rigidity. Construction rental fleet operators exhibit highest price sensitivity, prioritizing per-unit acquisition cost over lifecycle certification compliance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale maritime procurement demand from Singapore and Hong Kong fleet operators. Cylinder fabrication concentrates in Vietnam, Indonesia, and the Philippines, while fluorine-free surfactant synthesis draws from German and Dutch specialty chemical firms. Supply chain risk centers on single-source vulnerability in Vietnam's Hai Phong corridor, which controls the majority of regional shell production. Distribution runs through integrated fire suppression networks and port-proximate assembly operations serving ASEAN maritime tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where surfactant synthesis capability determines margin capture and regulatory compliance velocity. Players are pursuing backward integration into fluorine-free chemistry to escape intermediate supplier dependency.
For Market Incumbents: Anchor certification-premium positioning by deepening in-house surfactant production and expanding FM Approved assembly into underpenetrated Philippines shipyard zones. CO2 fixed suppression systems threaten portable foam displacement in offshore wind applications. Prioritize dual-certification product lines for US Gulf Coast petrochemical corridors where insurance underwriters mandate loss-prevention standards. For New Entrants and Emerging Players: Launch via blockchain-enabled certification tracking to streamline insurance audit workflows for multi-site facility operators. White-space targets include Subic Bay and Cebu manufacturing zones for FM Approved unit assembly and digital verification services for integrated facility management firms. The most penetrable segment is mid-scale Indonesian port manufacturing serving domestic SOLAS fleet expansion. For Investors and Strategic Acquirers: ECHA restriction enforcement acceleration is the leading indicator that fluorine-free formulation assets will command scarcity premiums. Long-term viability favors vertically integrated specialists with captive surfactant synthesis and port-proximate ASEAN assembly footprints. Target acquisition archetype: mid-scale CE-marked manufacturers with undeveloped UL/FM certification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Synthesis | German chemical manufacturers bypass Asian intermediate suppliers to secure ECHA-compliant formulation control. |
| Dual-Certification Assembly Expansion | Philippines shipyard zones absorb displaced EU capacity for Pacific basin maritime procurement. |
| Digital Certification Tracking Deployment | Blockchain-enabled UL Listed verification reduces insurance audit friction for multi-site operators. |
| Fluorine-Free Chemistry Scale-Up | Synthetic surfactant production unlocks European port authority and insurance-rated industrial access. |
| Port-Proximate Manufacturing Relocation | Batam and Surabaya production zones concentrate ASEAN maritime tender fulfillment capacity. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fire equipment procurement managers, marine safety officers at shipping operators, formulation plant technical directors, and insurance loss control engineers complemented documentary sources. Secondary validation drew from SOLAS compliance databases, ECHA restriction timelines, UL and FM certification registries, and ASEAN maritime tender documentation. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across the analysis window.
Segment-level modeling tracked formulation chemistry transitions, certification tier premiums, and deployment mobility requirements throughout the forecast period. The analytical framework incorporated end-use vertical specialization, regional regulatory divergence between European fluorine-free mandates and US AFFF phase-out schedules, and manufacturing capacity clustering in Southeast Asian port zones. CAGRs derived from shipment-volume trend extrapolation adjusted for fleet mandate compliance deadlines and formulation plant relocation patterns.
Regulatory timeline acceleration, surfactant input supply disruption, and maritime fleet demand volatility are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding ECHA enforcement consistency and SOLAS inspection compliance rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fireproof Insulation Market
Fire Safety & Protection
Smoke Pressure System Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Portable Fire Extinguisher Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
Fire Hose Market
Fire Safety & Protection
US Fire Safety Equipment Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Africa Fire Suppression Market