
 Global Fire Barrier Sealant Market | 2026-2036
Global Fire Barrier Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fire Barrier Sealant Market Intelligence
The EU Green Deal's focus on sustainable building renovation is broadening the application scope for advanced fire barrier sealants, especially those with low volatile organic compound content. Sika AG leverages its extensive portfolio in construction chemicals to meet this evolving demand across Europe. In parallel, 3M Company differentiates through its material science leadership, developing high-performance silicone and intumescent formulations that meet complex fire-stop requirements in critical infrastructure projects. Hilti sustains its strong market position via its direct sales model and system-based approach for construction professionals.
Fire barrier sealants are specialized materials designed to restore the fire-resistance rating of walls, floors, and ceilings compromised by penetrations or joints. These products, often based on silicone, acrylic, or intumescent chemistry, prevent the passage of fire, smoke, and hot gases for a specified duration. Intumescent sealants, which expand significantly when exposed to heat, represent a critical and high-value technology segment. While the commercial buildings application drives significant volume, demand from industrial facilities for sealants with specific chemical and temperature resistance is creating new growth opportunities.
Compliance with stringent fire testing standards, including ASTM E814 in the United States and EN 1366-4 in Europe, is mandatory for market access and dictates product design. International standards from the ISO further harmonize testing protocols, facilitating trade. Concurrently, environmental bodies like the U.S. EPA and Europe's ECHA regulate chemical inputs, pushing manufacturers toward developing safer, halogen-free formulations. The primary challenge for suppliers is navigating the trade-off between superior fire performance and the increasing pressure to eliminate certain chemical components.
Market Dynamics
The fire barrier sealant market is defined by the structural tension between advancing fire safety mandates for urban densification and the simultaneous regulatory pressure to remove hazardous chemicals from building materials. This dual demand forces innovation in material science, pushing for formulations that meet higher performance benchmarks under standards like ASTM E814 while complying with environmental health rules from bodies such as ECHA.
Growth Catalysts
- Stringent Building Codes:The expansion of high-rise commercial and residential buildings, especially in China and India, necessitates the use of certified firestop systems to meet updated national fire safety regulations.
- Infrastructure Modernization:Government initiatives, including the EU Green Deal's Renovation Wave, stimulate demand for advanced, low-VOC sealants in retrofitting projects to improve both fire safety and energy efficiency.
- Data Center Expansion:The proliferation of data centers, which have zero tolerance for fire-related downtime, creates a specific and high-value demand for intumescent sealants that protect critical cable and pipe penetrations.
Market Restraints
- Raw Material Volatility:Price fluctuations and supply constraints for key precursors, particularly for silicones and specialty polymers, directly impact production costs and compress profit margins for manufacturers.
- Substitution by Firestop Devices:In certain applications, pre-fabricated mechanical firestop devices, such as collars and sleeves, present a substitute for sealant-based solutions, limiting market penetration in joint and large-opening applications.
- Complex Certification Pathways:The lengthy and expensive process of testing and certifying products to multiple international standards, such as UL and EN, creates a significant barrier to entry for smaller players.
Strategic Opportunities
- Electric Vehicle Sector:The need for thermal runaway protection in electric vehicle battery packs opens a new, high-performance application for specialized intumescent sealants beyond traditional construction.
- Emerging Market Adoption:As countries in Southeast Asia and Latin America, such as Brazil and Indonesia, progressively upgrade their building codes, significant white space emerges for introducing established firestop solutions.
- Bio-Based Formulations:Developing sealants from renewable or recycled feedstocks that meet fire-resistance ratings offers a path to capture demand from green building projects certified under LEED or BREEAM frameworks.
Industry Challenges
- Installation Skill Gap:Incorrect application of fire barrier sealants is a major failure point, and a persistent shortage of certified, trained installers compromises the effectiveness of firestop systems and increases liability.
- Harmonization of Standards:Despite efforts by ISO, significant differences between North American (ASTM) and European (EN) testing protocols force manufacturers to maintain costly, parallel product development and certification programs.
- Chemical De-selection Pressure:Navigating the trade-off between fire performance and environmental safety is a constant challenge, as regulators like the U.S. EPA phase out chemicals that may be critical to sealant efficacy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fire Barrier Sealant Market |
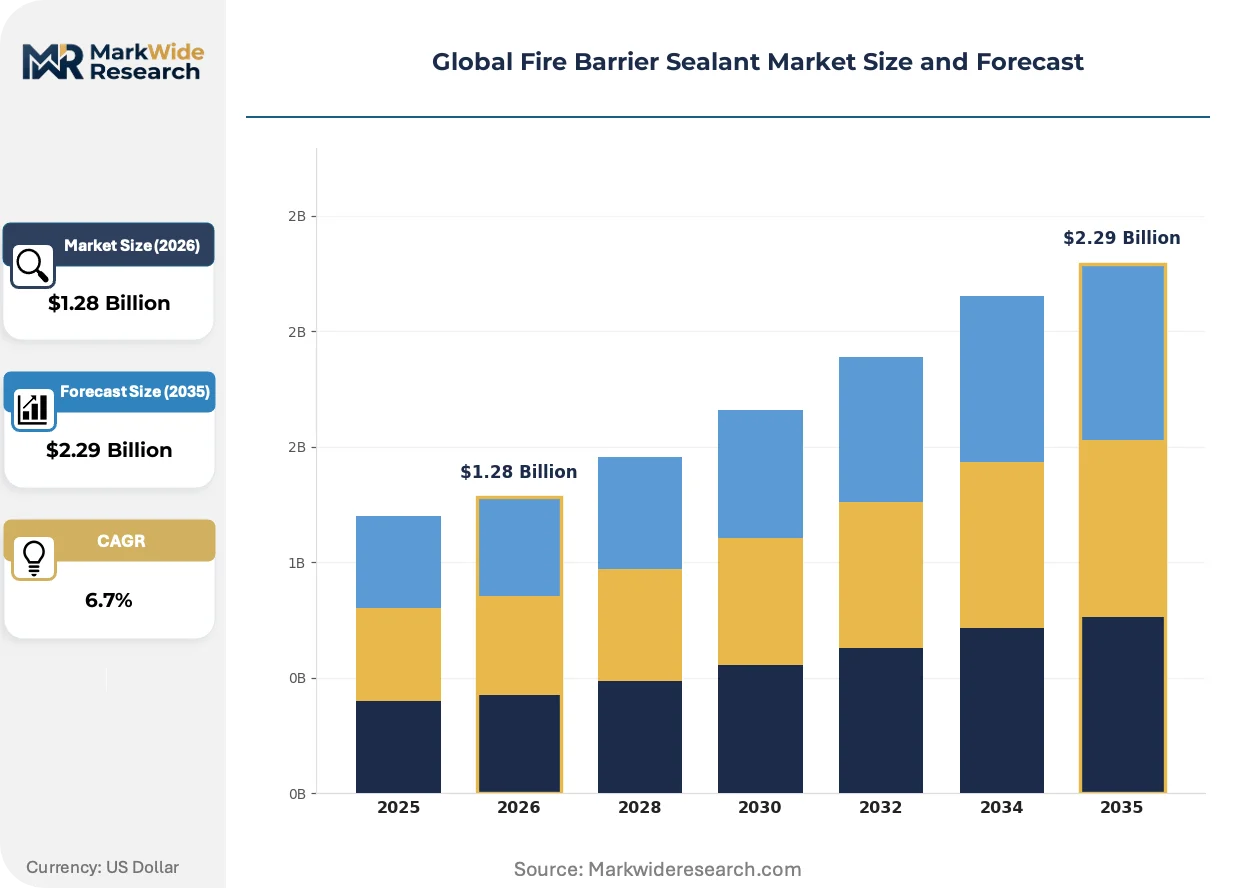
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.29 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Sealants, Silicone Sealants, Intumescent Sealants, Polyurethane Sealants, Hybrid Sealants Application: Commercial Buildings, Industrial Facilities, Tunnels, Power Plants, Transportation Infrastructure End User: Construction Contractors, Fire Protection Specialists, Facility Managers, Safety Inspectors, Maintenance Providers Distribution Channel: Direct Sales, Specialized Distributors, E-commerce, Wholesale Suppliers, Retail Outlets |
| Companies Covered | 3M Company, Hilti, Sika AG, H.B. Fuller Company, Tremco, Specified Technologies, RectorSeal, Promat International, Bostik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fire Barrier Sealant Market Strategic Shifts & Innovations
Product development is increasingly focused on multi-functional materials that combine fire resistance with other properties like acoustic insulation and air tightness. This evolution is a direct response to holistic building performance standards and stricter environmental health regulations that are reshaping material selection criteria in construction.
Hybrid sealant formulations that blend the properties of silicone and modified polymers are gaining traction. These products deliver superior flexibility, adhesion, and weather resistance compared to single-chemistry alternatives. The commercial construction sector, particularly for exterior joints and curtain wall systems, is adopting these advanced hybrids to ensure long-term building envelope integrity. This multi-functional capability is overtaking traditional sealants by offering a more durable and versatile solution for complex architectural designs.
Europe's REACH regulation continues to exert significant influence on sealant chemistry, restricting the use of certain plasticizers, solvents, and flame retardants. This regulatory action compels a shift toward water-based acrylic and safer, halogen-free intumescent technologies. The segments most affected are public buildings, including schools and hospitals across countries like Germany and France, which now frequently specify products that comply with the most stringent indoor air quality and material health standards.
A clear behavioral shift toward system-based specification is altering procurement patterns for firestop products. This model moves away from purchasing individual components, favoring integrated and tested assemblies from a single supplier. The direct sales channels of specialized manufacturers are better positioned to capture this demand than traditional distributors. This trend is most visible in critical infrastructure projects like airports and industrial facilities in the United States and the Middle East, where performance assurance is paramount.
Global Fire Barrier Sealant Market Segmentation
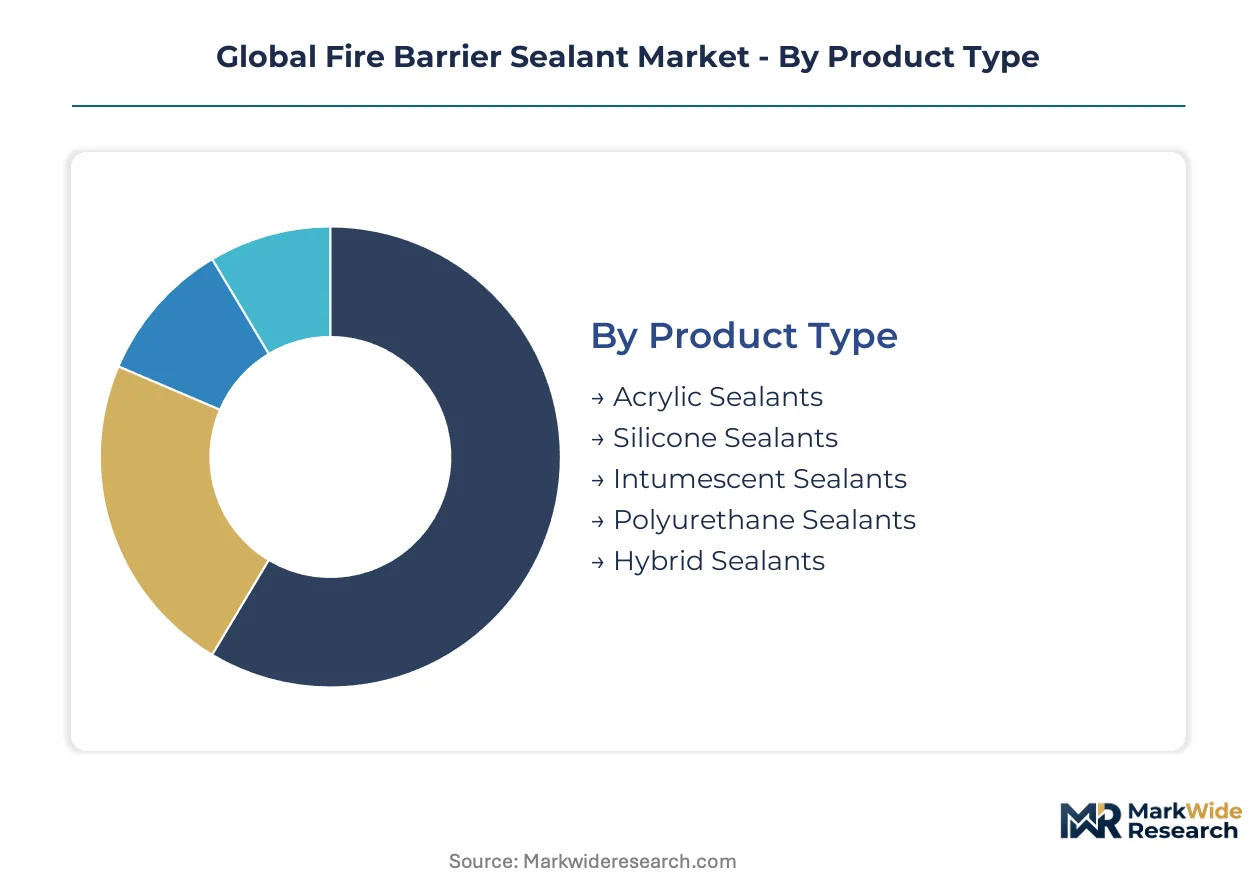
The fire barrier sealant market's segmentation reveals the diverse material science and application requirements driving product development and procurement. Understanding these distinct segments allows manufacturers to tailor formulations, distribution strategies, and market messaging for optimal penetration across varied end-use environments.
Product Type:
The supply of fire barrier sealants by product type is highly concentrated among specialized chemical manufacturers, each focusing on distinct material properties and performance characteristics.
- Intumescent Sealants:These formulations expand significantly when exposed to high temperatures, forming a char that insulates and blocks fire, smoke, and hot gases. Demand concentrates in critical infrastructure projects and data centers due to their zero-tolerance for fire-related downtime and need for robust passive fire protection.
- Acrylic Sealants:Composed of water-based polymers, these sealants offer good fire resistance and are often preferred for their low volatile organic compound content and ease of application. The EU Green Deal's focus on sustainable building renovation in Europe drives their specification in commercial projects.
- Silicone Sealants:Known for their excellent flexibility, weather resistance, and wide operating temperature range, silicone sealants find application in exterior joints and curtain wall systems.
- Polyurethane Sealants:These sealants provide strong adhesion and durability, often used in applications requiring robust mechanical properties and chemical resistance in industrial facilities.
- Hybrid Sealants:Blending properties of different chemistries, hybrid sealants deliver superior flexibility and adhesion, particularly in complex architectural designs in commercial construction.
Today's leader: Acrylic Sealants. Tomorrow's challenger: Intumescent Sealants.
Application:
The application landscape for fire barrier sealants shows distinct needs across various infrastructure types, each presenting unique challenges for fire safety and material performance.
- Commercial Buildings:This segment includes high-rise offices, retail spaces, and educational institutions, requiring extensive firestop systems for occupant safety and regulatory compliance. Stringent building codes in China and India necessitate certified solutions for new construction and renovation projects.
- Industrial Facilities:These sites, including manufacturing plants and chemical processing units, demand sealants with specific chemical resistance and temperature stability beyond standard fire protection. Growth opportunities emerge from new plant construction and modernization initiatives in Southeast Asia.
- Tunnels:Fire barrier sealants in tunnels provide critical protection against fire spread, ensuring structural integrity and safe evacuation routes in underground transportation networks.
- Power Plants:These facilities utilize specialized sealants to protect critical electrical and mechanical penetrations from fire, maintaining operational continuity and safety standards.
- Transportation Infrastructure:Airports, train stations, and port facilities employ fire barrier sealants for compartmentation and protection of vital systems against fire hazards.
Commercial Buildings command the largest volume, while Industrial Facilities are expanding most quickly.
End User:
Procurement patterns for fire barrier sealants vary significantly among different end-user groups, reflecting their distinct roles in construction, maintenance, and safety compliance.
- Construction Contractors:These professionals integrate fire barrier sealants into new building projects and major renovations, often specifying products based on project requirements and regulatory compliance. They prioritize ease of application and adherence to local building codes, especially in large urban developments.
- Fire Protection Specialists:Focused exclusively on firestop systems, these experts design and install comprehensive solutions, often favoring system-based specifications and products with extensive certifications. Their expertise is critical in complex projects like data centers and critical infrastructure in the United States and the Middle East.
- Facility Managers:Responsible for ongoing building maintenance and safety, facility managers procure sealants for repairs and upgrades to ensure continuous compliance with fire safety regulations.
- Safety Inspectors:While not direct purchasers, safety inspectors enforce compliance, influencing material selection and installation quality across commercial and industrial sites.
- Maintenance Providers:These service companies apply fire barrier sealants during routine maintenance and emergency repairs, ensuring the integrity of fire-rated assemblies in existing structures.
Construction Contractors represent the primary purchasing volume, while Fire Protection Specialists exert significant influence on product specification.
Distribution Channel:
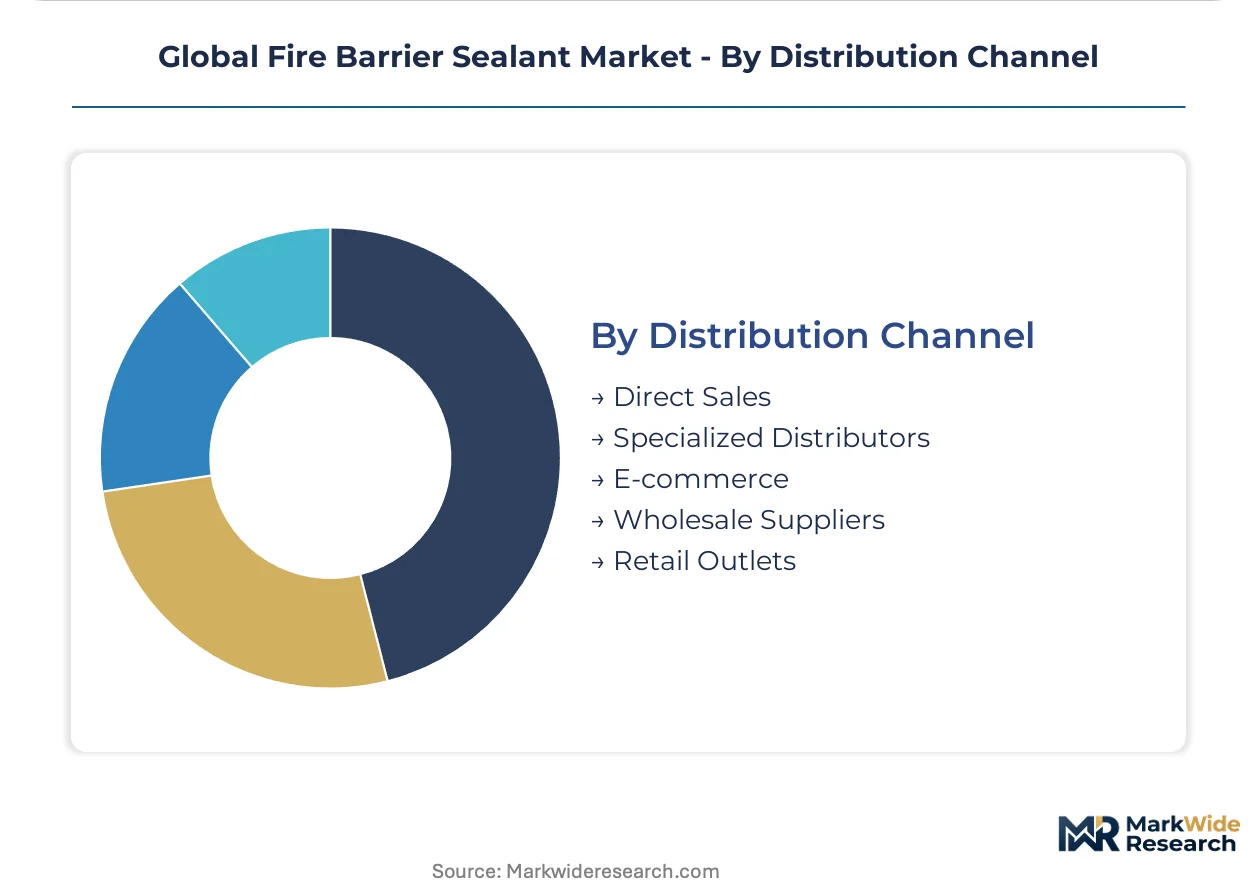
Market access for fire barrier sealants is shaped by the efficiency and reach of diverse distribution channels, each catering to different customer segments and project scales.
- Direct Sales:Manufacturers engage directly with large construction firms and critical infrastructure projects, offering technical support, system-based solutions, and customized product specifications. This channel is crucial for establishing long-term relationships and ensuring proper installation in complex applications.
- Specialized Distributors:These entities focus on specific construction chemical products, providing technical expertise, localized inventory, and logistical support to contractors and fire protection specialists. They serve as a vital link for accessing regional markets and smaller project sites across Europe and North America.
- E-commerce:Online platforms increasingly offer fire barrier sealants, catering to smaller contractors and DIY segments seeking convenience and competitive pricing for standard products.
- Wholesale Suppliers:These suppliers provide bulk quantities of standard fire barrier sealants to general contractors and large-scale construction projects, often prioritizing volume and cost-effectiveness.
- Retail Outlets:Hardware stores and building material retailers offer basic fire barrier sealant products for smaller renovation projects and maintenance tasks, appealing to a broad customer base.
Direct Sales remain dominant for complex projects, yet E-commerce shows a steep expansion trajectory for standard products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The fire barrier sealant industry originated and scaled significantly within developed economies, driven by early advancements in construction techniques and the establishment of comprehensive fire safety regulations. These foundational markets continue to influence product development and compliance standards. The market has since expanded globally, propelled by rapid urbanization and infrastructure modernization across diverse geographies.
United States
Commercial building expansion and the proliferation of data centers drive substantial demand for fire barrier sealants in the United States. ASTM E814 standards are mandatory for firestop systems, ensuring product efficacy in critical applications. Major metropolitan areas like New York City and Chicago consistently implement advanced fire safety solutions in high-rise construction projects.
Germany
Germany's focus on sustainable building renovation and stringent fire safety requirements stimulates demand for advanced fire barrier sealants. EN 1366-4 standards dictate product design and testing protocols across the country. Industrial zones in Bavaria and North Rhine-Westphalia prioritize high-performance sealants for their extensive manufacturing facilities.
China
China's rapid urbanization and extensive industrial and infrastructure projects necessitate a high volume of fire barrier sealants. National fire safety regulations, including GB standards, mandate certified firestop systems for new developments. Coastal economic hubs like Shanghai and Shenzhen drive substantial demand for advanced fire protection in their burgeoning commercial sectors.
India
High-rise commercial and residential construction, coupled with ongoing infrastructure modernization, fuels significant demand for fire barrier sealants in India. BIS standards for building materials are increasingly enforced to enhance public safety. Major cities such as Mumbai and Delhi are seeing rapid adoption of advanced fire barrier solutions in new construction projects.
United Arab Emirates
The United Arab Emirates' commitment to mega-projects and critical infrastructure development generates specific demand for high-performance fire barrier sealants. Local civil defense codes often exceed international fire safety benchmarks, requiring superior product performance. Dubai and Abu Dhabi lead in specifying advanced fire barrier sealants for their iconic architectural structures and essential facilities.
Global Fire Barrier Sealant Market Key Industry Players
Capital-heavy producers of base chemical polymers compete with asset-light formulators specializing in end-use applications within the fire barrier sealant market. The market exhibits a tiered structure, encompassing large chemical conglomerates and specialized firestop solution providers. Strategic archetypes include diversified construction chemical giants and niche material science innovators. Companies pursue portfolio diversification and strategic partnerships to expand their market reach.
Within the premium-tier segment, 3M Company exemplifies material science leadership, leveraging its extensive research capabilities for high-performance formulations. Hilti occupies a position as a specialized system provider, focusing on direct sales and integrated firestop solutions for construction professionals. Sika AG, a Swiss-based chemical company, represents the diversified construction chemical giant archetype, offering an extensive portfolio across various building applications. These entities often anchor innovation in the fire barrier sealant market.
| Leading Market Players |
|---|
| 3M Company |
| Hilti |
| Sika AG |
| H.B. Fuller Company |
| Tremco |
| Specified Technologies |
| RectorSeal |
| Promat International |
| Bostik |
| Others |
Cost & Logistics Intelligence
Vertical integration into raw material sourcing anchors manufacturers' supply positions, directly influencing their pricing power in the fire barrier sealant market. This strategy mitigates raw material volatility and supports stable product pricing.
Pricing Analysis
Project-based pricing dominates the fire barrier sealant market, where solutions are tailored to specific infrastructure requirements. Price differentiation stems from certification levels, such as ASTM E814 or EN 1366-4, and the inclusion of after-sales technical support. Pricing softness stems from intense competition among suppliers for large commercial building projects. Construction contractors exhibit high price sensitivity, while fire protection specialists prioritize certified performance and system integrity.
Supply Chain Analysis
Logistics costs for specialty chemicals significantly impact the fire barrier sealant supply chain, particularly for imports to Asia. Supply concentrates in Germany, the United States, and China, which host major chemical producers and raw material sources like silicone polymers and acrylic resins. Raw material volatility for these precursors presents a structural supply chain risk. Direct sales channels and specialized distributors manage downstream distribution for complex projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fire barrier sealant market presents a margin-expansion story, driven by the increasing demand for high-performance, certified solutions. Shifting toward advanced intumescent and hybrid formulations enables premium-tier pricing.
For Market Incumbents: Deepen backward integration into specialized polymer production to mitigate raw material volatility. This strategy insulates against pricing pressure from commodity chemical suppliers. Invest in certification for halogen-free formulations to counter regulatory shifts like Europe's ECHA restrictions. Expand direct sales channels in emerging markets to protect against substitution by mechanical firestop devices.
For New Entrants and Emerging Players: Launch via e-commerce platforms to target smaller contractors and maintenance providers seeking standard acrylic sealants. The underpenetrated Southeast Asian market, particularly industrial facilities, offers white space for advanced solutions. Focus on developing bio-based formulations for green building projects certified under LEED. This provides a clear go-to-market angle against established chemical players.
For Investors and Strategic Acquirers: Roll-up economics work for specialized firestop solution providers because of fragmented regional distribution and varied certification requirements. The market exhibits long-term viability over the next decade, driven by urban densification and evolving safety mandates. Target mid-sized formulators with strong intellectual property in intumescent or hybrid chemistries. The signal to watch is the increasing enforcement of advanced fire codes in Latin America.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Supports growing demand from China's high-rise construction and industrial projects. |
| Green Manufacturing Transition | Addresses EU Green Deal requirements for low-VOC and sustainable building materials. |
| Product Portfolio Diversification | Captures new demand in the electric vehicle battery thermal runaway protection segment. |
| Advanced Certification Investment | Ensures compliance with stringent standards like ASTM E814 for critical infrastructure projects. |
| Digital Sales Channel Development | Expands market reach to smaller contractors and maintenance providers for standard products. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the analysis. This involved interviews with construction contractors, fire protection specialists, R&D directors at chemical companies, and facility managers. Secondary validation drew from national building codes, ECHA regulatory documents, ASTM standards, and company financial reports. The analysis employs both bottom-up and top-down triangulation to ensure data accuracy.
Granularity of modeling extends across product types, applications, and end-user segments, alongside regional adoption patterns. The analytical framework integrates historical market performance with macroeconomic indicators over the projection horizon. Compound Annual Growth Rates were derived through regression analysis of market drivers and restraints. Forecast inputs included projected construction spending and regulatory enforcement trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen raw material supply disruptions or significant regulatory shifts. All forecasts reflect assumptions regarding market dynamics and technological advancements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
US Fire Alarm and Detection Market
Fire Safety & Protection
Fire Protection Systems Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
US Fire Safety Equipment Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Fire Suppression Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Fire Hose Market
Fire Safety & Protection
Smoke Pressure System Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
China Thermal Protector Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
Fire Pump Market