
 Fire Protection Valves and Fittings Market | 2026-2036
Fire Protection Valves and Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Protection Valves and Fittings Market Intelligence
The integration of IoT sensors and remote diagnostic capabilities into valve assemblies is fragmenting the traditional hardware-centric market. This creates a new competitive layer where software and data analytics become critical. Tyco Fire Products leverages its global distribution network to offer integrated smart systems. Minimax Viking GmbH competes by specializing in high-performance solutions for complex industrial environments like chemical plants.
Fire protection valves and fittings are mechanical devices engineered to control, direct, or regulate the flow of fire suppressants like water, foam, or gas. Constructed from materials such as ductile iron or bronze, they must meet stringent pressure ratings and durability standards for emergency use. Water-based systems remain the dominant application, but gas suppression systems for sensitive environments like data centers represent a key growth segment. Gate valves and butterfly valves hold significant share due to their widespread use in sprinkler and hydrant lines.
Product design and market access are heavily governed by certification bodies like the US-based UL and Europe's CE marking requirements. National fire codes, such as those enforced by authorities in China and India, further dictate specific performance criteria and installation protocols for commercial and industrial buildings. Navigating this complex web of regional certifications versus achieving a single global standard remains a key strategic decision for manufacturers.
Market Dynamics
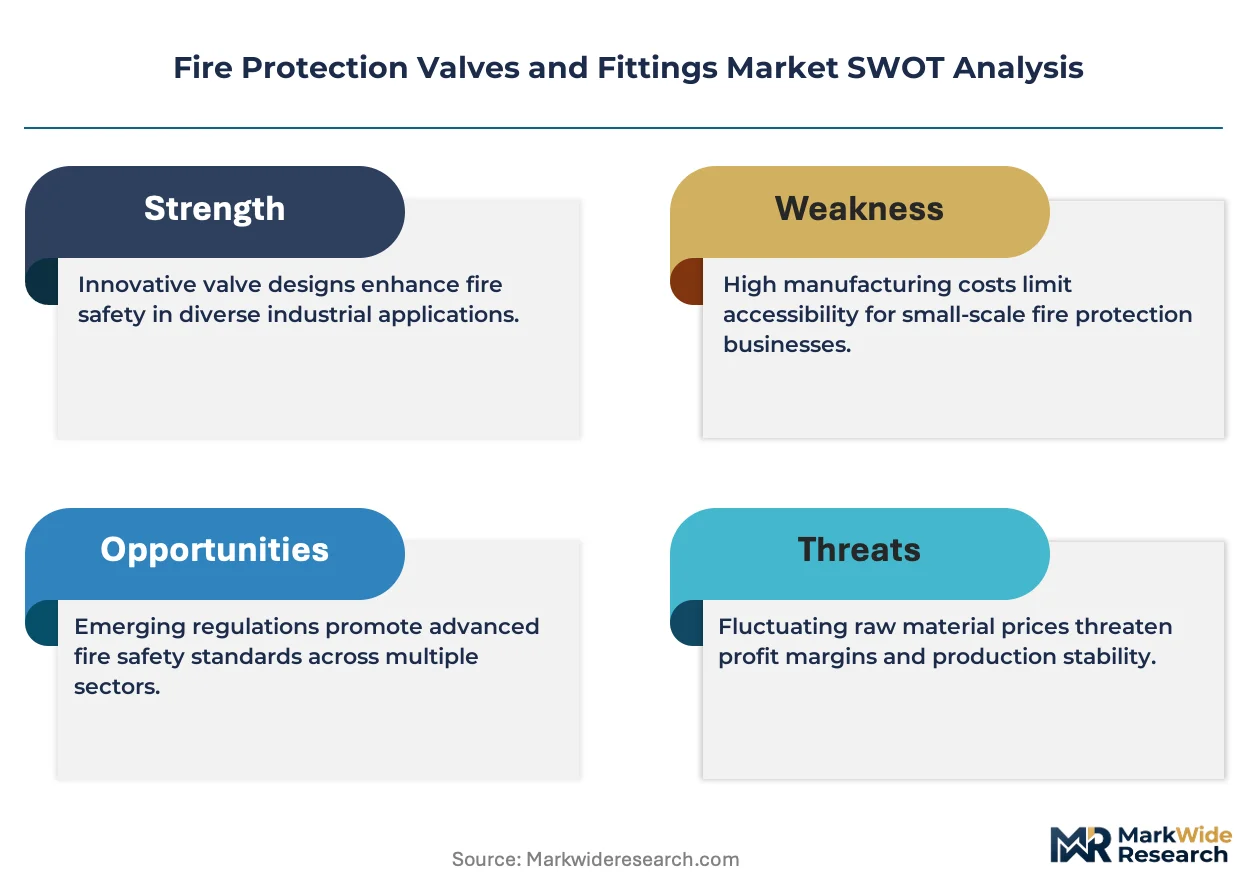
The fire protection valves and fittings market is fundamentally shaped by the escalating stringency of global building codes and fire safety regulations. This regulatory pressure, particularly for high-risk environments like data centers and industrial facilities, is compelling mandatory system upgrades and driving new installations.
Growth Catalysts
- Industrial and Urban Expansion:Rapid urbanization in Southeast Asian economies is creating sustained demand for fire protection systems in new commercial and residential construction projects, directly boosting valve and fitting sales.
- Data Center Proliferation:The global build-out of data centers requires specialized gas and water mist suppression systems, opening a high-value segment for advanced, fast-acting control valves designed for sensitive electronic environments.
- Regulatory Modernization:The enforcement of updated fire codes, such as India's National Building Code and China's GB standards, mandates the retrofitting of older buildings and the installation of certified equipment in all new structures.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of key metals like ductile iron, steel, and bronze directly impact manufacturer margins and can lead to pricing instability for end-users, complicating long-term project budgeting.
- Certification Complexity:The lack of a single global standard forces manufacturers to navigate a costly and time-consuming web of regional certifications, such as UL in the United States and CE marking in Europe, acting as a barrier to market entry.
- High Capital Costs:The initial investment required for installing or completely overhauling comprehensive fire sprinkler or suppression systems remains a significant financial hurdle for many small to medium-sized enterprises.
Strategic Opportunities
- Aftermarket and Retrofit Services:A substantial opportunity exists in servicing, upgrading, and replacing aging fire protection infrastructure in developed markets, particularly in commercial buildings constructed decades ago.
- IoT-Enabled Smart Systems:Integrating sensors and connectivity into valve assemblies for remote monitoring and predictive maintenance opens new revenue streams through data services and system health analytics.
- Expansion in Emerging Economies:Underpenetrated markets across Africa and Latin America present long-term growth potential as their industrial bases expand and regulatory frameworks for building safety mature.
Industry Challenges
- Skilled Labor Shortage:The industry faces a deficit of technicians qualified to install, inspect, and maintain increasingly complex, software-integrated fire protection systems, potentially leading to installation delays and quality issues.
- Legacy System Integration:Ensuring new, technologically advanced valves and smart controls are compatible with existing, older fire suppression infrastructure during retrofit projects presents a significant technical and logistical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Protection Valves and Fittings Market |
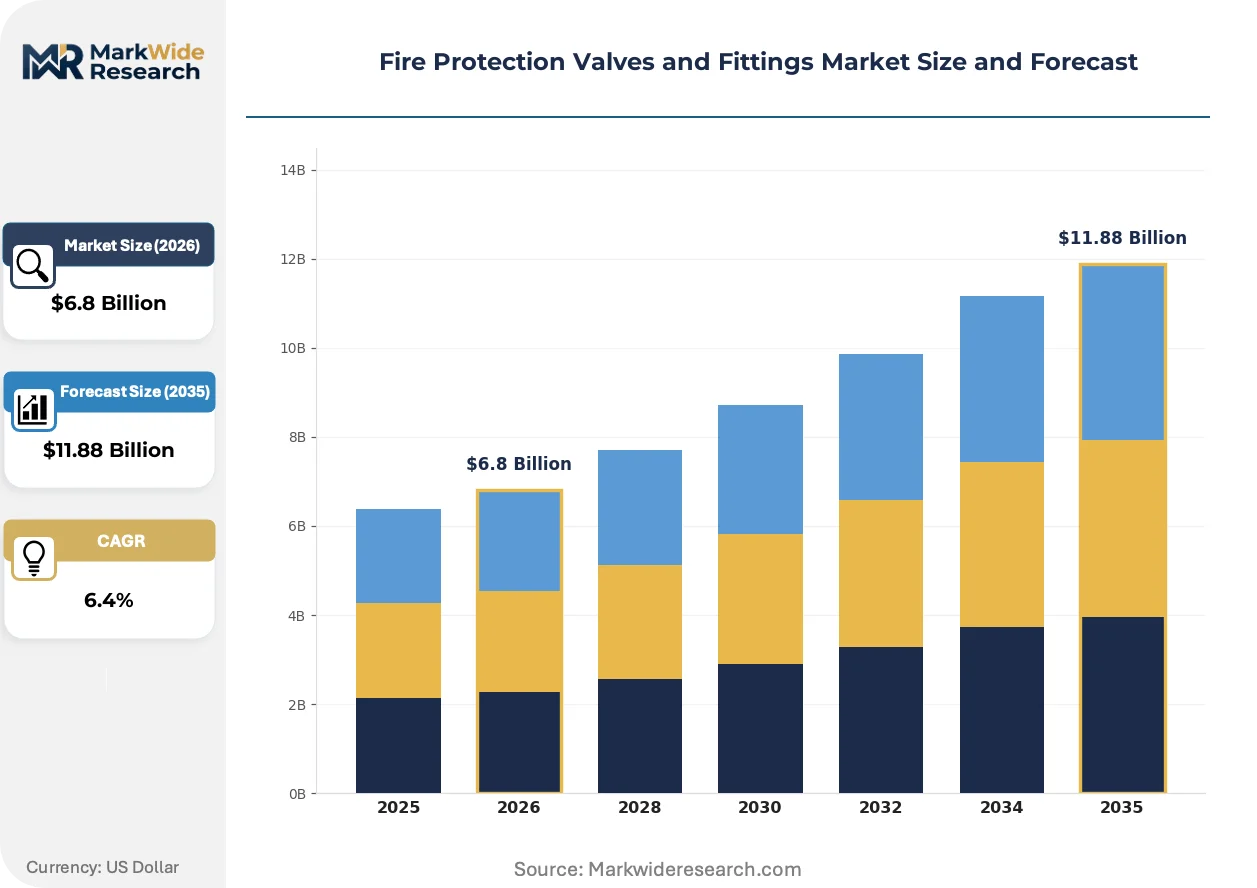
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gate Valves, Globe Valves, Check Valves, Ball Valves, Butterfly Valves, Pressure Relief Valves Application: Water-Based Systems, Foam-Based Systems, Gas Suppression Systems, Dry Chemical Systems, Dust Cloud Suppression, Fire Hydrants End User Industry: Commercial Complexes, Industrial Plants, Data Centers, Educational Institutes, Transportation Facilities, Energy Plants Installation Type: New Construction, Retrofit Projects, Modular Installations, Mobile Units, Fixed Systems, Temporary Setups |
| Companies Covered | Rapidrop Global Ltd., Raphael Valves Industries Ltd., HD Fire Protect Pvt Ltd., Reliable Automatic Sprinkler Co., Inc., Tyco Fire Products, Anvil International LLC, Global Fire Sprinkler Corporation, Minimax Viking GmbH, Cla-Val Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Protection Valves and Fittings Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from standalone mechanical components to interconnected, intelligent systems. This shift places a new premium on software, data analytics, and system-level integration, altering competitive dynamics and product value propositions away from pure hardware performance.
Wireless sensor networks embedded directly within valve assemblies provide real-time data on system pressure, flow status, and potential leaks. Facility managers in critical infrastructure sectors are adopting this technology to enable predictive maintenance and reduce manual inspection costs. The integration of sensing and control into a single device is collapsing the traditional divide between hardware, monitoring services, and analytics platforms.
Stringent updates to Europe's F-Gas Regulation are accelerating the phase-out of certain chemical fire suppressants. This regulatory action directly increases demand for alternative systems, including high-pressure water mist and inert gas solutions. Consequently, the market for valves and fittings engineered to handle the specific pressure and flow characteristics of these alternative agents is expanding significantly.
A notable behavioral shift involves end-users specifying complete, pre-engineered fire suppression kits from a single source. This model disrupts the traditional channel where contractors procure individual components from various distributors. The preference for turnkey solutions is most apparent in fast-track construction projects like logistics warehouses and prefabricated buildings, where system-level certification and speed are paramount.
Fire Protection Valves and Fittings Market Segmentation
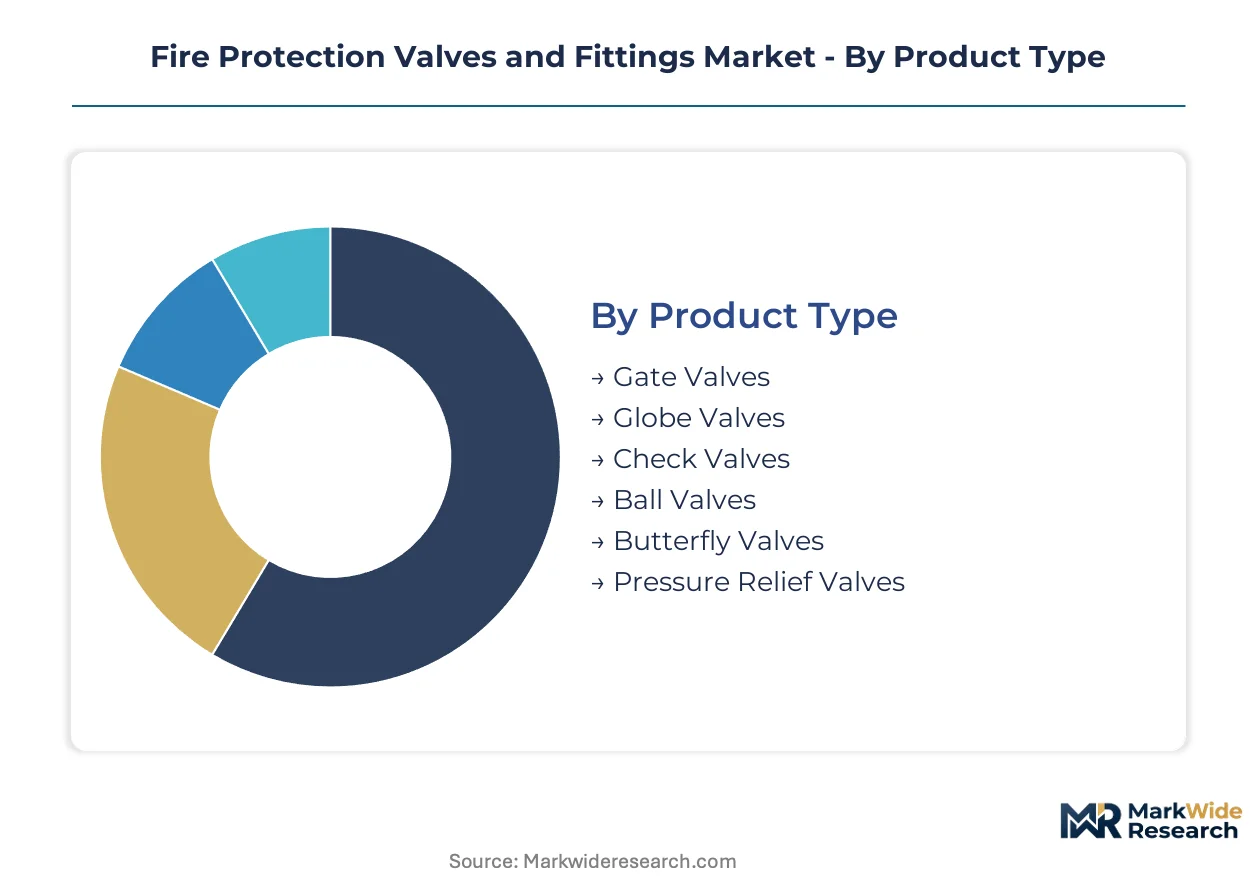
The fire protection valves and fittings market is highly diversified, driven by varying operational requirements, regulatory environments, and end-user demands across different sectors. Understanding these distinct segments is critical for manufacturers to tailor product development and market penetration strategies effectively.
Product Type:
Product types exhibit varied replacement cycles, with some components requiring more frequent maintenance or upgrades than others. This influences both initial sales and long-term aftermarket revenue streams.
- Gate Valves:These full-flow valves offer minimal pressure drop and are designed for isolation, requiring several turns to open or close. Demand concentrates in large diameter sprinkler and hydrant lines for new commercial and industrial construction, mandated by fire codes.
- Butterfly Valves:Compact and lightweight, these quarter-turn valves provide quick shut-off and are suitable for large pipe sizes and space-constrained installations. They see demand in modern industrial facilities and logistics warehouses requiring rapid system response and efficient space utilization.
- Globe Valves:Engineered for throttling or regulating flow, these valves introduce a significant pressure drop. They are utilized in applications requiring precise flow control within fire suppression systems.
- Check Valves:These mechanical devices prevent backflow in a pipeline, ensuring one-way flow of fire suppressants. They are essential for maintaining system integrity and pump protection.
- Ball Valves:Offering quick, tight shut-off with a quarter-turn, ball valves are frequently used for isolation in smaller lines within fire protection systems.
- Pressure Relief Valves:Designed to protect systems from overpressure, these safety-critical valves release excess pressure to prevent equipment damage. They are vital in high-pressure gas suppression systems.
Gate Valves anchors the volume base while Butterfly Valves gains share at the steepest rate.
Application:
The cost tier for fire suppression applications varies significantly, with some systems requiring highly specialized and expensive components for sensitive environments, while others rely on more standardized, cost-effective solutions.
- Water-Based Systems:This dominant application includes sprinklers, standpipes, and hydrants, using water as the primary suppressant. Demand is widespread across commercial, residential, and industrial sectors, driven by universal building codes.
- Gas Suppression Systems:Utilizing inert gases or chemical agents, these systems protect sensitive environments from fire without water damage. Data centers, server rooms, and telecommunication facilities represent a significant growth segment due to high-value asset protection.
- Foam-Based Systems:These systems are designed to suppress fires involving flammable liquids, often found in petrochemical plants and aviation hangars. They require specialized valves capable of handling foam concentrates.
- Dry Chemical Systems:Employing fine powder agents, these systems provide rapid fire knockdown for specific hazards like kitchens and vehicle engine compartments.
- Dust Cloud Suppression:Critical in industries handling combustible dust, these systems mitigate explosion risks by rapidly suppressing dust clouds.
- Fire Hydrants:Essential components of municipal and industrial fire protection, providing external water access for firefighting operations.
Regulatory mandates heavily influence the demand profile for Water-Based Systems, while technological advancements drive adoption in Gas Suppression Systems applications.
End User Industry:
Different end-user industries represent distinct customer types, each with unique procurement patterns, risk profiles, and regulatory compliance requirements for fire protection systems.
- Industrial Plants:These facilities, including manufacturing, chemical, and power generation, require robust and often customized fire protection due to complex processes and hazardous materials. Stringent safety protocols in these environments drive demand for high-performance valves and fittings.
- Data Centers:Mission-critical facilities housing sensitive electronic equipment demand specialized, non-damaging fire suppression, primarily gas or water mist systems. Their continuous expansion globally fuels demand for advanced control valves.
- Commercial Complexes:This segment includes office buildings, retail spaces, and hotels, relying on standard sprinkler and standpipe systems for occupant safety.
- Educational Institutes:Schools, universities, and research facilities require comprehensive fire protection to ensure the safety of students and staff.
- Transportation Facilities:Airports, train stations, and tunnels necessitate specialized fire suppression solutions tailored to their unique layouts and high traffic volumes.
- Energy Plants:Power generation facilities, including nuclear, fossil fuel, and renewable energy sites, require durable fire protection for critical infrastructure.
The Commercial Complexes sector consistently drives consistent baseline demand, whereas the Data Centers sector exhibits the steepest expansion trajectory.
Installation Type:
The maturity of installation types ranges from long-established practices like new construction to emerging methods tailored for speed and efficiency, impacting product design and distribution channels.
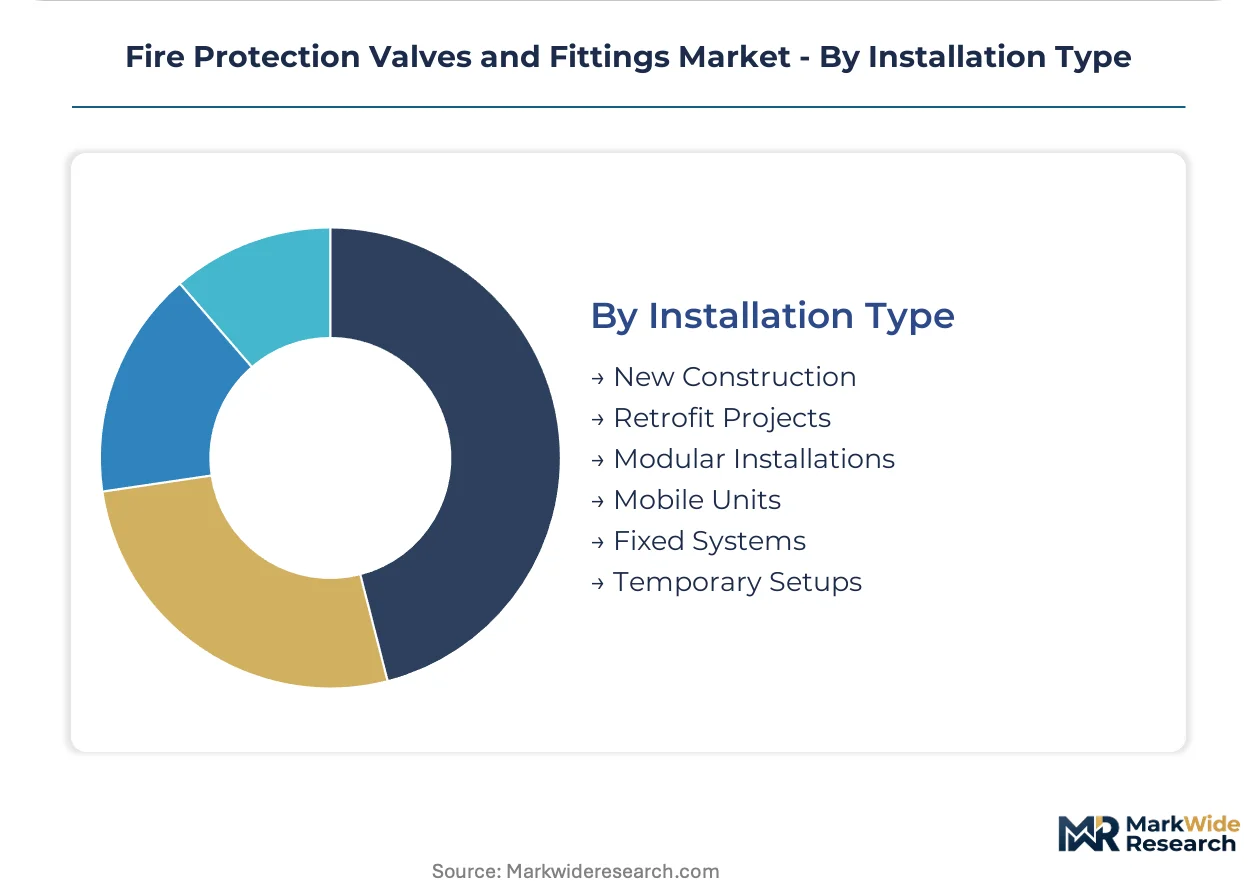
- New Construction:Valves and fittings are integrated into the initial building design and infrastructure of new commercial, industrial, and residential projects. Urbanization in Southeast Asian economies sustains this foundational demand.
- Retrofit Projects:These involve upgrading or replacing aging fire protection systems in existing buildings, particularly older commercial structures in developed markets. This segment represents a significant aftermarket opportunity.
- Modular Installations:Pre-engineered and pre-assembled fire suppression units offer rapid deployment and reduced on-site labor. Logistics warehouses and prefabricated buildings increasingly adopt these solutions.
- Mobile Units:Portable fire suppression systems are used for specialized vehicles, remote operations, or temporary hazard protection.
- Fixed Systems:Permanent installations are designed for specific fire zones within a facility, providing continuous protection for critical assets or processes.
- Temporary Setups:Short-term fire protection solutions are deployed for events, construction sites, or during maintenance of permanent systems.
New Construction installations represent a stable and predictable segment, while the increasing complexity of Retrofit Projects drives specialized product innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers for fire protection valves and fittings concentrate in regions undergoing significant industrial expansion and urban development. Data centers and large commercial complexes in rapidly growing economies represent primary demand centers. Developed markets also sustain demand through infrastructure upgrades and stringent safety mandates.
China
Demand for fire protection valves in China is substantial due to extensive commercial and industrial construction projects. The enforcement of GB standards mandates certified equipment in new structures, driving sales. Major urban centers like the Yangtze River Delta are experiencing continuous development, requiring advanced fire suppression systems for high-rise buildings.
India
India's burgeoning infrastructure and manufacturing sectors create sustained demand for fire protection systems. The National Building Code of India dictates specific performance criteria for commercial and industrial installations. Cities such as Mumbai and Bangalore are seeing significant investment in data centers and commercial complexes, necessitating modern fire safety solutions.
United States
Upgrades to aging commercial infrastructure and the proliferation of data centers drive demand for fire protection valves in the United States. UL certification requirements ensure compliance and quality for all installed systems. Technology hubs like Silicon Valley and major metropolitan areas are investing in advanced gas suppression systems for sensitive electronic environments.
Germany
Stringent industrial safety regulations and a focus on high-performance solutions characterize the German market for fire protection valves. CE marking requirements govern product design and market access across the country. Industrial regions such as North Rhine-Westphalia demand specialized systems for chemical plants and manufacturing facilities.
Brazil
Construction in Brazil's industrial and commercial sectors generates demand for robust fire protection equipment. National building codes are evolving, compelling businesses to adopt more sophisticated safety measures. Major cities like São Paulo are experiencing growth in logistics and manufacturing, requiring comprehensive fire suppression for new facilities.
Fire Protection Valves and Fittings Market Key Industry Players
Channel-controlling players compete with product-specialist players across the fire protection valves and fittings market. The market exhibits a tiered structure, with global manufacturers offering integrated smart systems alongside niche providers focusing on high-performance solutions for complex environments. Strategic archetypes include full-suite system integrators, specialized component manufacturers, and regional distribution networks. Portfolio diversification, often through M&A, and strategic partnerships represent dominant competitive moves among these entities.
Specialists in integrated solutions and high-performance applications include Tyco Fire Products, which represents global distribution capabilities and smart system integration. Minimax Viking GmbH, a German entity, exemplifies expertise in specialized solutions for demanding industrial environments, particularly for gas suppression. Reliable Automatic Sprinkler Co., Inc., a US-based firm, anchors the segment focused on traditional water-based sprinkler system components and their associated fittings. These players operate within a market where product design and access are heavily governed by certification bodies like UL and CE marking, influencing their strategic market positioning. Navigating this complex web of regional certifications versus achieving a single global standard remains a key strategic decision for manufacturers.
| Leading Market Players |
|---|
| Rapidrop Global Ltd. |
| Raphael Valves Industries Ltd. |
| HD Fire Protect Pvt Ltd. |
| Reliable Automatic Sprinkler Co., Inc. |
| Tyco Fire Products |
| Anvil International LLC |
| Global Fire Sprinkler Corporation |
| Minimax Viking GmbH |
| Cla-Val Co. |
| Others |
Cost & Logistics Intelligence
Raw material price volatility significantly impacts pricing tier spreads for fire protection valves and fittings, simultaneously shaping global supply chain strategies as manufacturers seek stable, cost-effective material sources.
Pricing Analysis
Cost-plus contracts, often indexed to metal commodities, define much of the pricing for fire protection valves and fittings. Price differentiation stems from stringent certification levels like UL and CE marking, alongside customization required for complex industrial applications. Pricing softness reflects fluctuations in ductile iron and bronze costs, impacting manufacturer margins. Small to medium enterprises exhibit high price sensitivity for basic systems, while data centers prioritize performance and reliability over initial cost.
Supply Chain Analysis
Specialized foundries and component manufacturers, particularly in China and India, concentrate significant capacity for fire protection valve production, with Germany focusing on high-performance solutions. The supply chain draws heavily from ductile iron, steel, and bronze. Certification complexity represents a structural risk, as manufacturers navigate regional standards like UL and CE marking. Distribution runs through a dual model, balancing traditional component suppliers with a growing preference for complete, pre-engineered kits from single sources.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the integration of IoT sensors and remote diagnostic capabilities into valve assemblies. This shift creates distinct niches for software-centric solutions and data analytics providers.
For Market Incumbents: Insulate core hardware revenues by accelerating investment in IoT-enabled smart systems and remote diagnostic capabilities. Expand integrated service offerings to counter software-driven entrants and maintain channel control. Deepen certification investment across multiple geographies to mitigate regulatory chokepoints. Strategic acquisitions of specialized software firms can further secure market positioning.
For New Entrants and Emerging Players: Aftermarket and retrofit services in developed markets, particularly for aging commercial buildings, represent a highly penetrable entry point. Focus on providing IoT-enabled upgrade kits that integrate seamlessly with existing fire suppression infrastructure. Specialize in advanced gas suppression systems for burgeoning data center construction, offering rapid deployment and system-level certification. A go-to-market angle emphasizing technical support and simplified compliance can gain traction.
For Investors and Strategic Acquirers: The market sits at a modernization phase that favors technology-forward specialists capable of integrating software and hardware. Long-term viability remains strong over the next decade, driven by escalating global safety requirements. Acquisition targets include niche manufacturers with proprietary IoT valve technology or strong regional distribution networks in high-growth areas. The signal to watch is accelerated adoption rates for complete, pre-engineered fire suppression kits in new construction projects.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Valve Development | This initiative captures new revenue streams through data services and predictive maintenance for critical infrastructure. |
| Multi-Regional Certification Pursuit | Achieving UL, CE, and GB standards broadens market access and strengthens compliance for global manufacturers. |
| Expansion in Southeast Asian Economies | Underpenetrated markets offer significant long-term growth as urbanization and industrialization accelerate. |
| Turnkey Solution Bundling | Offering complete, pre-engineered fire suppression kits simplifies procurement for fast-track construction projects. |
| Aftermarket Service Enhancement | Upgrading and maintaining aging fire protection infrastructure in developed markets secures recurring revenue. |
Research Approach
A spread of perspectives from fire safety engineers, facility managers, and procurement officers converged on the working assumptions for this analysis. Primary interviews with industry stakeholders were triangulated with secondary validation from UL standards, CE marking guidelines, and national building codes. A bottom-up data collection approach was integrated with top-down market sizing to ensure robust estimates.
Demand-supply balance informed the quantitative framework, projecting market evolution across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, and installation type, alongside regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected market drivers like urbanization rates and data center build-out forecasts.
Practitioners should monitor raw material price volatility and significant shifts in global trade policies for early signals of forecast revision. This analysis reflects assumptions regarding regulatory enforcement and technological adoption. Quarterly review of new building code adoptions and major industrial project announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Europe Fire-Resistant Glass Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Fire Suppression Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
Fire Safety Equipment Market