
 Fire Protection Coating Market | 2026-2036
Fire Protection Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Protection Coating Market Analysis
Chinese specialty chemical producers is restructuring domestic supply for intumescent resin precursors, tightening feedstock availability for formulators elsewhere. Sherwin-Williams Company leverages its architectural coatings distribution network to cross-sell fire protection systems into commercial building specifications. Akzo Nobel N.V. anchors its position through marine-certified epoxy-intumescent hybrids that satisfy IMO SOLAS requirements for steel deck fire ratings. PPG Industries, Inc. competes on thin-film technology leadership, sustaining R&D intensity in waterborne intumescent platforms that reduce volatile organic compound exposure during application.
Fire protection coatings are reactive polymer systems, typically epoxy or acrylic-based, that expand under heat exposure to form an insulating char layer measuring 25 to 50 times original thickness, thereby extending structural steel load-bearing capacity during fire events. Intumescent coatings command premium positioning due to their aesthetic compatibility with exposed steel architecture and thinner applied film builds compared to cementitious alternatives. Spray-applied technology dominates industrial facility deployments where speed and labor efficiency outweigh finish quality, while brush-applied systems occupy maintenance and retrofit segments requiring precision around complex geometries. Cementitious coatings retain volume leadership in petrochemical and power generation facilities where thick-film durability against mechanical damage supersedes architectural appearance.
NFPA 251 and ASTM E119 testing protocols in the United States govern hourly fire-resistance ratings that directly determine coating specification thickness and material selection. ECHA REACH restrictions on halogenated flame retardants and EU Construction Products Regulation CPR 305/2011 CE marking requirements are redirecting European formulation toward phosphorus-nitrogen intumescent chemistry. China's GB 14907 standard mandates fireproofing performance classes for steel structural elements in high-rise construction, compelling domestic and imported coating compliance. Stakeholders must monitor evolving test protocol harmonization between regional certification bodies, as divergent char-thickness measurement methodologies create technical barriers to cross-border product registration and project bidding.
Market Dynamics
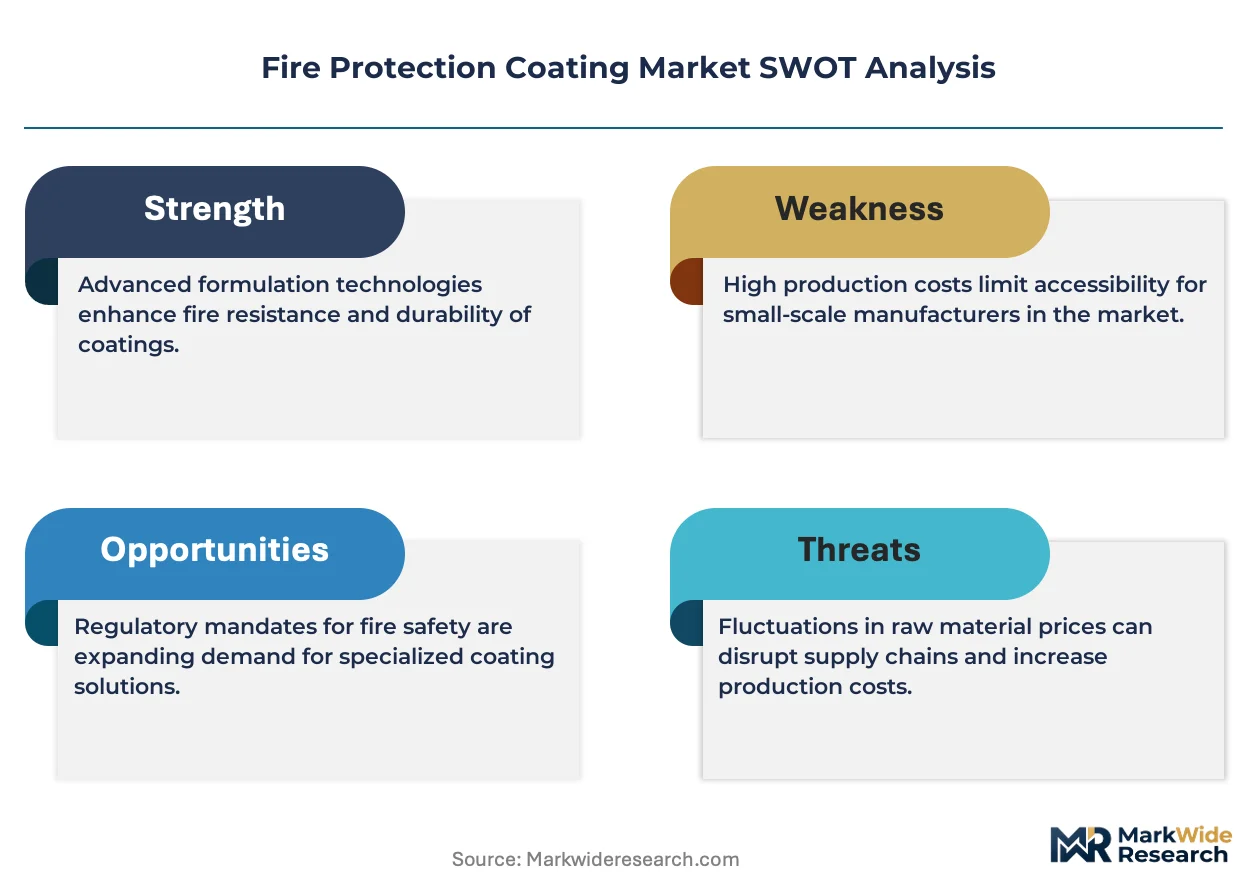
Steel-intensive urban construction across Asia-Pacific is tightening certification requirements for intumescent systems, while feedstock concentration among Chinese resin producers constrains formulation flexibility for Western manufacturers.
Growth Catalysts
- GB 14907 compliance mandates:China's updated fireproofing standard for structural steel in high-rise buildings accelerates specification of certified intumescent coatings among domestic developers.
- Epoxy-intumescent hybrid platforms:Marine and offshore sectors adopt these systems to satisfy IMO SOLAS fire-rating requirements for steel decks without cementitious bulk.
- Urban density premiums:Commercial building developers in Shanghai, Mumbai, and Jakarta specify thin-film intumescent systems to preserve architectural steel aesthetics in constrained floor plates.
Market Restraints
- Phosphorus-nitrogen precursor concentration:Chinese specialty chemical producers control domestic supply of intumescent resin feedstocks, creating import dependency for European and North American formulators.
- Cementitious substitution in heavy industrial:Petrochemical facilities favor thick-film cementitious coatings for mechanical durability against impact and abrasion in process environments.
- ECHA REACH transition costs:Halogenated flame retardant phase-outs force reformulation investments without immediate price recovery mechanisms in competitive tendering.
Strategic Opportunities
- Waterborne platform penetration:Waterborne intumescent chemistry addresses VOC exposure limits in occupied building retrofits where solvent-based application faces occupational health restrictions.
- Brush-applied maintenance channels:Complex geometry retrofits in existing commercial portfolios favor precision brush application over spray systems, opening specialized contractor networks.
- ASTM E119 harmonization:Convergence between US hourly fire-resistance testing and European char-thickness protocols would streamline cross-border product registration for multinational projects.
Industry Challenges
- Certification timeline compression:Divergent char-thickness measurement methodologies between NFPA 251 and EN 13381-4 testing protocols delay project-specific product approvals.
- Applicator skill stratification:Thin-film intumescent systems demand precise mil-thickness control that spray contractors in industrial markets rarely maintain without retraining investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Protection Coating Market |
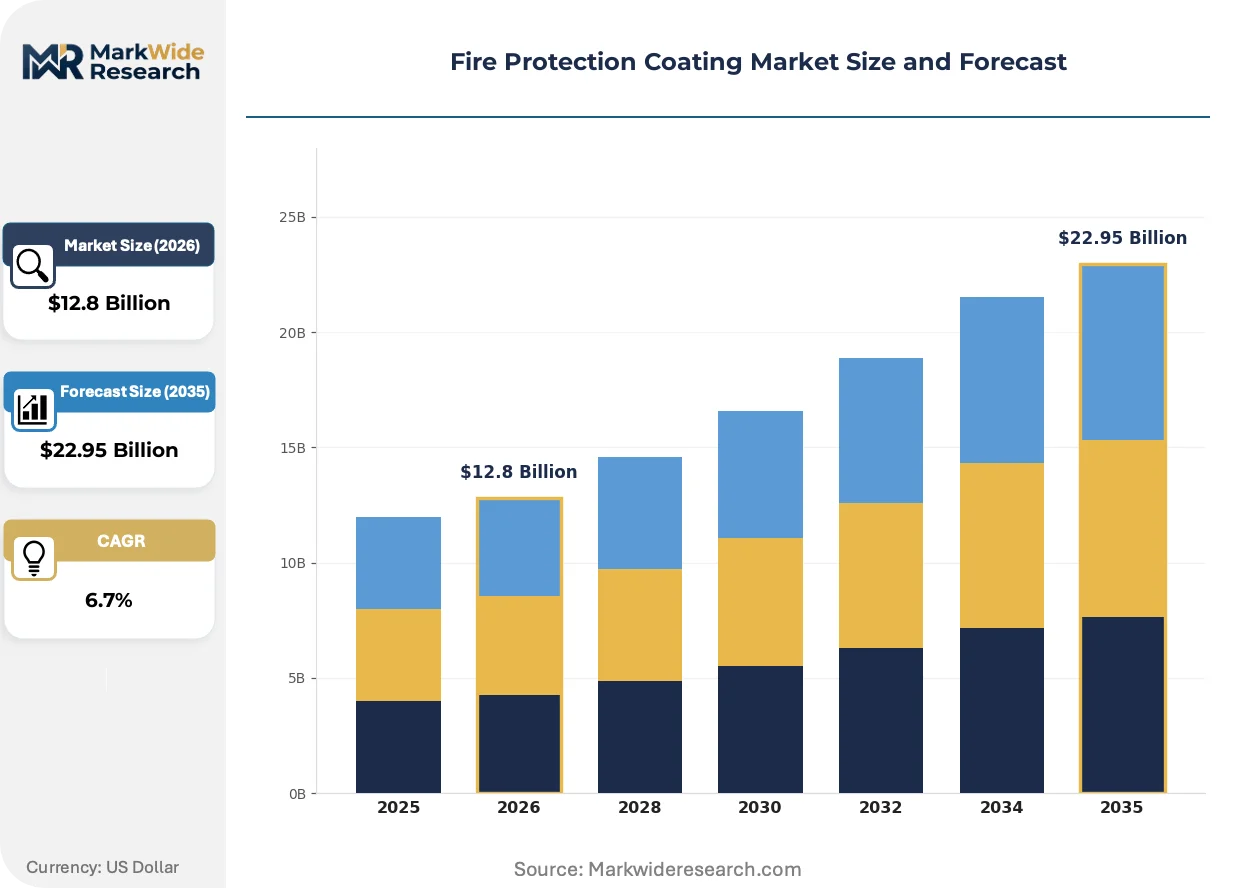
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intumescent Coatings, Cementitious Coatings, Thin Film Coatings, Fire Retardant Paints Technology: Spray Applied, Brush Applied, Roll Applied, Electrostatic End User: Commercial Buildings, Residential Structures, Industrial Facilities, Marine Applications Application: Passive Fire Protection, Active Fire Protection, Surface Protection, Fireproofing |
| Companies Covered | Sherwin-Williams Company, Akzo Nobel N.V., PPG Industries, Inc., Jotun, Hempel A/S, RPM International Inc., Kansai Paint Co., Ltd., Sika AG, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Protection Coating Market Emerging Trajectories
Formulation chemistry and application methodology are converging around environmental compliance and architectural visibility, compressing the performance gap between aesthetic and industrial fire protection systems.
Waterborne intumescent technology is consolidating its position in commercial building specifications where VOC exposure during application triggers regulatory scrutiny and tenant safety concerns. Architects and developers in mixed-use towers specify these platforms for exposed steel atrium structures where finish quality must satisfy visual inspection. The shift is compressing demand for solvent-based systems in premium commercial segments while forcing incumbent suppliers to reconfigure manufacturing assets.
EU Construction Products Regulation CPR 305/2011 CE marking requirements are redirecting European formulation toward phosphorus-nitrogen intumescent chemistry as halogenated alternatives face ECHA REACH restriction proceedings. Coatings manufacturers serving German and French infrastructure markets must demonstrate char stability and smoke toxicity compliance through notified body assessment. The regulatory pressure most affects small and mid-sized formulators lacking in-house toxicology and fire-testing capabilities.
Specification authority is migrating from general contractors to fire protection engineering consultants who control substrate certification packages for complex commercial developments. These consultants bundle coating selection with structural fire engineering calculations, displacing traditional distributor relationships in high-value project segments. The pattern is most visible in London, Singapore, and Dubai where design-build contracts concentrate technical decision-making with specialist fire engineers.
Fire Protection Coating Market Segmentation
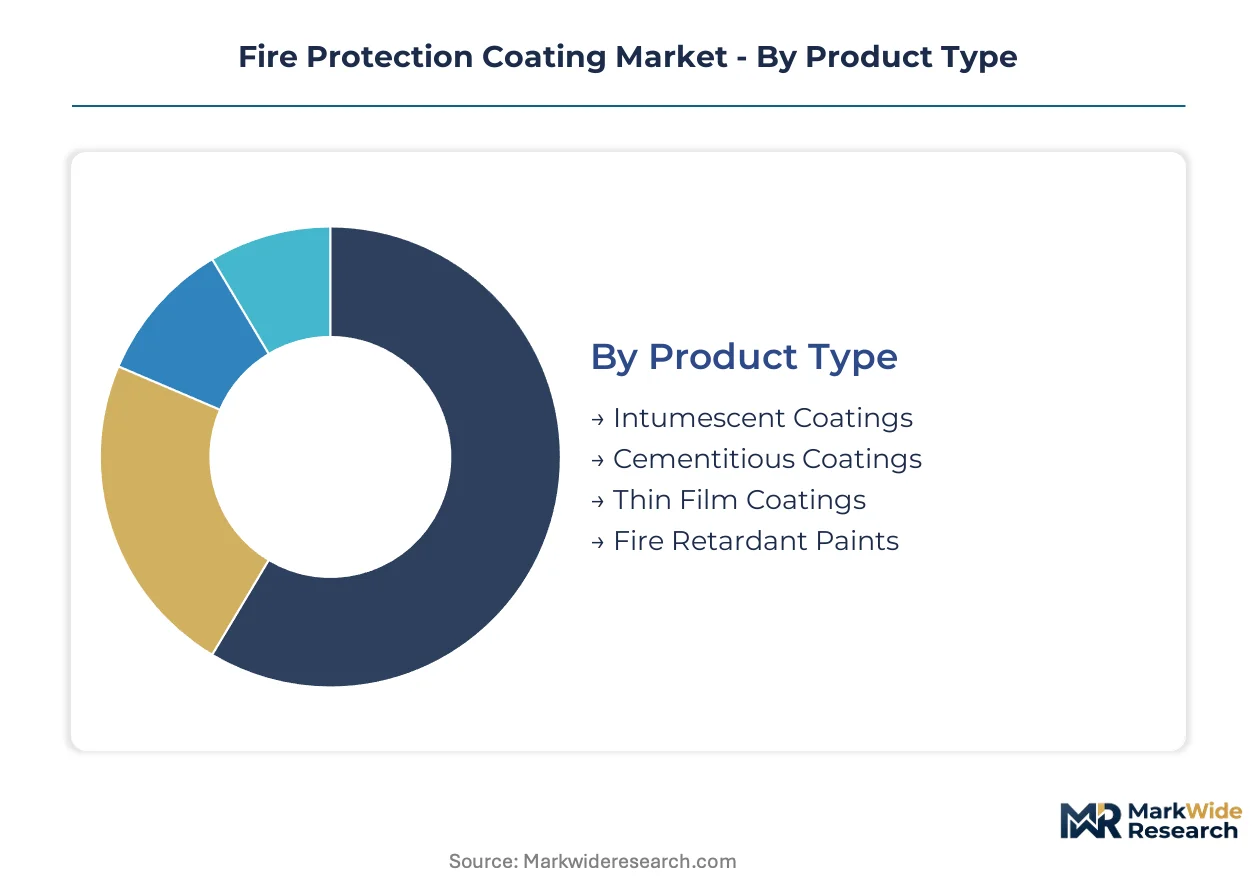
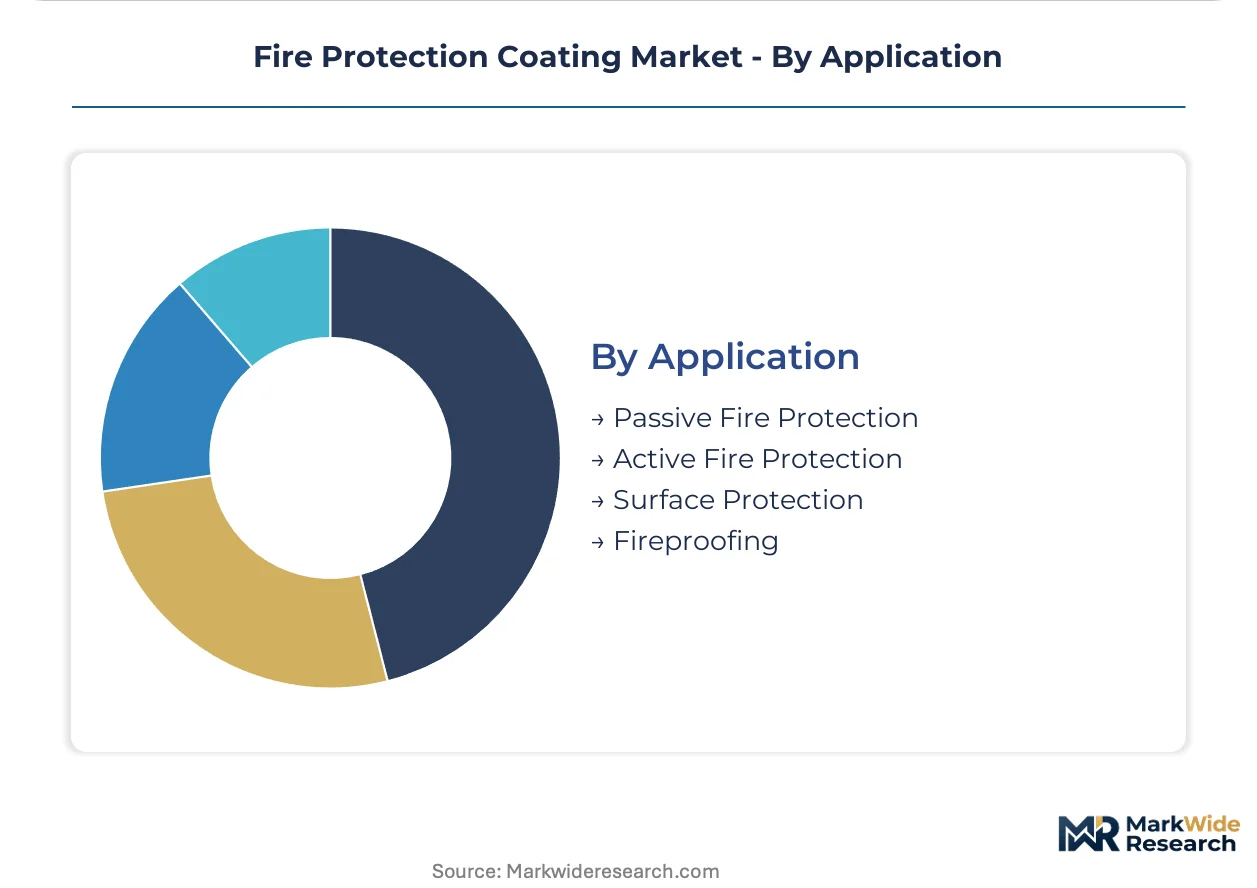
Fire protection coating procurement hinges on substrate type, application constraints, and regulatory compliance tier. Specification authority varies sharply across end-use contexts, with industrial buyers prioritizing certified performance and commercial developers weighing aesthetic finish against hourly fire ratings.
Product Type:
Buyers select coating chemistry based on fire-resistance duration requirements and architectural exposure decisions.
- Intumescent Coatings:Epoxy or acrylic-based systems that expand 25-50 times original thickness under heat to form insulating char. Demand concentrates in China's high-rise steel construction where GB 14907 compliance mandates drive specification of thin-film certified systems for exposed structural elements.
- Cementitious Coatings:Thick-film mineral-based formulations applied in heavy layers for mechanical durability. Petrochemical facilities in the US Gulf Coast and Rotterdam harbor favor these systems for impact resistance in process environments where cementitious bulk supersedes appearance.
- Thin Film Coatings:Low-build aesthetic systems for visible steel in atrium and lobby structures.
- Fire Retardant Paints:Surface-level flame spread inhibitors for wood and drywall substrates in residential retrofits.
Volume sits with cementitious systems in heavy industrial; growth tilts toward intumescent chemistry in commercial steel construction.
Technology:
Application method selection tracks project scale, geometry complexity, and labor cost structure.
- Spray Applied:High-throughput pneumatic or airless systems dominating new construction where speed offsets equipment mobilization costs. Industrial facility deployments across Germany's chemical corridor and Texas petrochemical clusters rely on spray contractors for rapid coverage of large steel inventories.
- Brush Applied:Precision manual application for complex geometries and maintenance retrofits. London and Singapore commercial portfolios specify brush systems for atrium steel where finish quality demands mil-thickness control around connection details.
- Roll Applied:Intermediate coverage method for flat steel surfaces in warehouse and logistics construction.
- Electrostatic:Automated powder deposition for standardized structural components in prefabricated building systems.
Spray systems capture the largest project throughput; brush application is climbing the fastest in retrofit-dense urban markets.
End User:
End-use context dictates certification tier, aesthetic requirements, and procurement channel.
- Commercial Buildings:Mixed-use towers and office complexes specifying thin-film intumescent for exposed steel aesthetics. Developers in Shanghai, Mumbai, and Jakarta drive demand as urban density constraints elevate fire-rated steel visibility in constrained floor plates.
- Industrial Facilities:Petrochemical, power generation, and manufacturing plants prioritizing thick-film durability. US OSHA process safety management requirements and EU Seveso III directives compel certified passive fire protection in high-hazard operations.
- Residential Structures:Low-rise and mid-rise housing with basic fire retardant treatment for wood framing.
- Marine Applications:Offshore platforms and vessel construction requiring IMO SOLAS-compliant epoxy-intumescent hybrids for steel deck fire ratings.
Industrial facilities generate the highest coating volume per project; commercial buildings are gaining share fastest in specification-driven markets.
Application:
Functional purpose determines testing protocol, material thickness, and inspector sign-off requirements.
- Passive Fire Protection:Structural steel coatings that extend load-bearing capacity during fire events through insulation. ASTM E119 and EN 13381-4 testing protocols govern hourly ratings that directly determine coating thickness specification in US and European commercial construction.
- Active Fire Protection:Coatings integrated with detection and suppression systems in smart building designs.
- Surface Protection:Dual-purpose formulations combining fire resistance with corrosion inhibition for marine and coastal steel.
- Fireproofing:Generic thermal barrier applications across building envelopes and structural assemblies.
Passive fire protection commands the specification premium; active system integration represents the steepest expansion trajectory in intelligent building deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphorus-nitrogen resin precursor production concentrates in Chinese chemical manufacturing zones, creating feedstock dependencies that reshape procurement patterns across construction-intensive economies.
China
Steel-intensive high-rise construction in Shanghai and Shenzhen drives GB 14907 compliance mandates for structural steel fireproofing. MIIT oversight of specialty chemical production tightens domestic control over intumescent resin feedstocks. Yangtze River Delta coating formulators face raw material allocation pressures as state-directed supply restructuring prioritizes local manufacturers.
United States
Commercial tower development in Manhattan and Chicago elevates specification of thin-film intumescent systems for exposed architectural steel. OSHA process safety management requirements enforce certified passive fire protection in Gulf Coast petrochemical clusters. Houston-area industrial facilities favor spray-applied cementitious coatings for mechanical durability in process environments.
Germany
Chemical corridor infrastructure investments across North Rhine-Westphalia sustain demand for heavy industrial fire protection systems. ECHA REACH restrictions on halogenated flame retardants redirect formulation toward phosphorus-nitrogen chemistry. BASF-Ludwigshafen and Bayer-Leverkusen facility maintenance cycles generate recurring coating procurement for process steel protection.
United Kingdom
London design-build contracts concentrate specification authority with fire protection engineering consultants bundling coating selection with structural calculations. CE marking under EU Construction Products Regulation CPR 305/2011 governs char stability and smoke toxicity compliance. Canary Wharf and City of London commercial portfolios specify brush-applied systems for atrium steel requiring mil-thickness precision.
India
Mumbai and Delhi-NCR commercial developers specify intumescent coatings as urban density constraints elevate fire-rated steel visibility in constrained floor plates. BIS fire safety standards for high-rise construction tighten substrate certification requirements. Maharashtra industrial zones sustain cementitious coating demand for power generation and manufacturing facility durability.
Fire Protection Coating Market Vendor Landscape
Global majors compete with regional champions across formulation technology and distribution reach, producing a tiered structure where scale-driven players anchor premium commercial segments while specialized fabricators serve industrial maintenance channels. Three archetypes dominate: diversified coatings conglomerates with architectural distribution networks, marine-certified specialists leveraging IMO compliance credentials, and waterborne technology leaders addressing VOC regulatory pressure. Consolidation through manufacturing asset reconfiguration and cross-regional certification partnerships represents the primary competitive vector.
Within the diversified coatings tier, Sherwin-Williams Company and PPG Industries, Inc. occupy positions defined by architectural channel penetration and thin-film technology development respectively. Akzo Nobel N.V. exemplifies the marine-specialist archetype through epoxy-intumescent hybrid positioning. These three anchors illustrate how competitive differentiation tracks regulatory compliance geography rather than product functionality alone.
| Leading Market Players |
|---|
| Sherwin-Williams Company |
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| Jotun |
| Hempel A/S |
| RPM International Inc. |
| Kansai Paint Co., Ltd. |
| Sika AG |
| 3M |
| Others |
Supply Flow & Price Mechanics
Commercial building developers in Shanghai, Mumbai, and Jakarta concentrate procurement authority for thin-film intumescent systems, creating project-based pricing that bundles certified performance with applicator warranty coverage. This buyer concentration enables tiered pricing structures where GB 14907 compliance grade and ASTM E119 hourly rating certification separate premium specifications from standard industrial offerings.
Pricing Analysis
Warranty bundling distinguishes pricing tiers across the fire protection coating market, with premium commercial specifications including applicator certification guarantees and char-performance warranties that standard industrial tenders exclude. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity, with UL-listed and CE-marked systems commanding substantial premiums over basic BIS-compliant alternatives. Pricing pressure stems from phosphorus-nitrogen precursor cost volatility as Chinese resin producers tighten domestic allocation. Cementitious coating buyers in Gulf Coast petrochemical facilities exhibit highest price sensitivity due to commoditized specification standards, while London and Singapore commercial developers prioritize finish quality over unit cost.
Supply Chain Analysis
Certification gating restricts supply chain participation to formulators with notified body relationships for ASTM E119, EN 13381-4, and GB 14907 testing protocols. Manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta chemical zones supplying intumescent resin precursors that European and North American formulators draw from under allocation constraints. Epoxy resin, expandable graphite, and phosphorus-based flame retardants constitute critical input dependencies. Single-source vulnerability runs through Chinese specialty chemical producers controlling phosphorus-nitrogen feedstock synthesis. Distribution runs through architectural coatings distributors serving commercial specifications and industrial maintenance contractors for petrochemical facility retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where ECHA REACH restriction proceedings on halogenated flame retardants erect formulation barriers that favor incumbents with in-house toxicology and fire-testing capabilities.
For Market Incumbents: Deepen backward integration into phosphorus-nitrogen resin precursor production to offset Chinese feedstock allocation constraints, while expanding certified applicator training networks to defend against emerging waterborne technology specialists. Cementitious substitution threats in heavy industrial segments necessitate durability-focused R&D investment. Certification portfolio breadth serves as the primary defensive lever against regional champions. For New Entrants and Emerging Players: Fire protection engineering consultants represent the critical channel partner for penetrating specification-driven commercial developments in London, Singapore, and Dubai. Waterborne intumescent retrofits in occupied mixed-use towers offer the most penetrable white space, given occupational health restrictions on solvent-based application. Brush-applied maintenance channels in existing commercial portfolios enable specialized contractor network entry without confronting spray-applied incumbents directly. For Investors and Strategic Acquirers: Distressed-cycle entries favor waterborne technology specialists with GB 14907 certification progress in China, where state-directed supply restructuring creates acquisition opportunities among domestic formulators facing raw material pressures. Long-term viability hinges on regulatory compliance moats widening across multiple jurisdictions. The signal to watch is ASTM E119 and EN 13381-4 protocol harmonization progress, which would trigger cross-border product registration acceleration and consolidate multinational project specification authority.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Precursors | Captive supply of phosphorus-nitrogen chemistry reduces Chinese allocation dependency for Western formulators. |
| Waterborne Platform Scale-Up | Manufacturing asset reconfiguration captures VOC-compliant commercial specifications in occupied building retrofits. |
| Certified Applicator Network Expansion | Mil-thickness precision training addresses skill stratification constraining thin-film intumescent deployment. |
| Cross-Regional Certification Partnerships | Notified body relationships streamline ASTM E119 and EN 13381-4 dual compliance for multinational projects. |
| Fire Protection Engineering Consultant Engagement | Specification authority migration favors bundling coating selection with structural fire engineering calculations. |
Methodological Framework
Multi-period observation of GB 14907 implementation timelines, ECHA REACH restriction proceedings, and IMO SOLAS compliance patterns anchored the trend analysis, supplemented by interviews with coating formulator R&D directors, fire protection engineering consultants, commercial building developers, certified applicator contractors, and specialty chemical procurement managers. Secondary validation drew from MIIT production data, ECHA regulatory filings, ASTM and EN testing protocol documentation, and SEC 10-K disclosures from diversified coatings manufacturers. Bottom-up project pipeline tracking across Shanghai, Mumbai, Jakarta, London, and Dubai commercial developments triangulated with top-down chemical production data.
Input-output matrices modeled coating demand across product type, application technology, end-use vertical, and regional regulatory framework dimensions throughout the forecast period. CAGRs were derived from segment-level volume build-ups incorporating steel construction intensity indices and fire safety standard adoption curves. Industry-specific forecast inputs included high-rise construction permit data and process safety management enforcement patterns.
Caveats apply where ECHA REACH transition timelines or GB 14907 enforcement consistency could materially shift the outlook, as regulatory implementation gaps affect near-term specification momentum. Forecasts reflect modeling assumptions about protocol harmonization progress and feedstock allocation stability. A model refresh is warranted upon material change in Chinese specialty chemical export policy or ASTM-EN testing standard convergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Portable Fire Extinguisher Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fireproof Insulation Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
GCC Firefighting Foam Market