
 Architecture Smart Glass Market | 2026-2036
Architecture Smart Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Architecture Smart Glass Market Insights
The EU Green Deal's building renovation mandate is pivoting commercial real estate toward dynamic glazing systems. Saint-Gobain leverages its integrated float-to-coating footprint to supply electrochromic substrates across European retrofit pipelines. AGC anchors Asian project development through its proprietary light-control interlayer technology. View competes on full-system installation, bundling glazing with cloud-based tint management for U.S. Class A office towers.
Architecture smart glass encompasses electrically active glazing that modulates light transmission, thermal transmittance, or opacity through applied voltage, thermal stimulus, or electromagnetic fields, typically achieving visible light transmittance swings between 3% and 62% depending on technology. Electrochromic layers dominate premium facade applications where precise solar heat gain coefficient management offsets HVAC loads. Suspended particle device variants occupy the fastest-growing hospitality segment, enabling instant privacy transitions in hotel guest rooms and conference suites. Liquid crystal installations sustain margin pools in healthcare partitions where sterility and visual isolation converge.
REACH compliance governs chemical constituents in electrochromic tungsten oxide layers across European supply chains, while CE marking certifies structural performance for curtain wall integration. The U.S. EPA Energy Star program shapes procurement criteria for federal building retrofits, and California's Title 24 building code mandates automated daylighting controls that smart glass satisfies natively. Stakeholders must monitor evolving embodied carbon accounting rules that threaten to recast the environmental advantage of electrochromic manufacturing against simpler thermochromic alternatives.
Market Dynamics
Electrochromic manufacturing scale-up is compressing unit economics while EU Green Deal retrofit mandates pull demand toward dynamic facade systems that offset embodied carbon penalties against operational savings.
Growth Catalysts
- EU Green Deal renovation mandate:Operational carbon limits on existing commercial buildings in Germany, France, and the Netherlands are accelerating electrochromic retrofits in 1970s office towers.
- Hotel guest experience premium:Suspended particle device installations in hospitality suites command rate premiums through instant privacy transitions that differentiate luxury properties.
- California Title 24 automation requirement:Automated daylighting controls in new construction natively favor electrochromic glazing over external shading systems.
Market Restraints
- Tungsten oxide supply concentration:Electrochromic layer production depends on refined tungsten feedstock where Chinese processors control intermediate chemical supply.
- REACH compliance burden:ECHA chemical registration requirements for tungsten oxide and lithium salts add 18-24 month certification timelines for new electrochromic formulations.
- Thermochromic substitution threat:Passive vanadium dioxide coatings offer lower first-cost solar modulation without electrical infrastructure, capturing budget-constrained retrofit segments.
Strategic Opportunities
- Healthcare sterile partition expansion:Liquid crystal privacy glass in surgical suites and patient observation rooms merges infection control with visual monitoring flexibility.
- Cloud-based tint management bundling:Full-system providers can capture recurring software revenue through building management system integration and predictive maintenance algorithms.
- Indian commercial real estate pipeline:LEED Platinum certification targets in Mumbai and Bangalore premium office developments create specification openings for dynamic glazing.
Industry Challenges
- Curtain wall integration complexity:Electrochromic IGU replacement requires structural engineering recertification and facade contractor coordination that extends project timelines.
- Electrical systems commissioning:Low-voltage wiring, transformer placement, and BMS protocol compatibility create multi-trade coordination failures in fast-track construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Architecture Smart Glass Market |
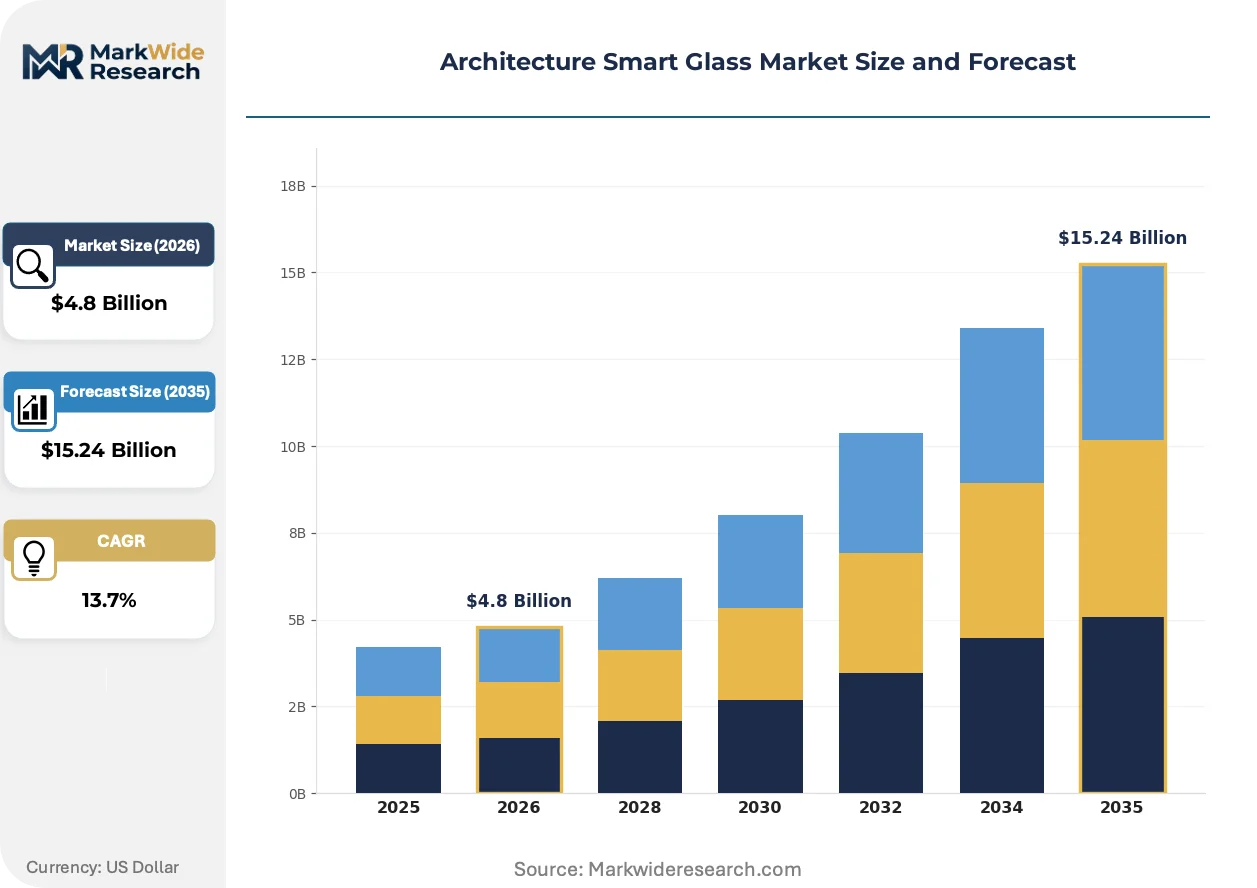
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochromic, Suspended Particle Device, Liquid Crystal, Thermochromic, Photochromic Application: Skylights, Facades, Curtain Walls, Windows, Partitions Installation Type: New Construction, Retrofit Projects, Commercial Complexes, Institutional Buildings, Entertainment Venues End User: Office Complexes, Educational Facilities, Hospitality Establishments, Government Structures, Cultural Centers |
| Companies Covered | Saint-Gobain, AGC, Gentex Corporation, Corning Incorporated, PPG Industries, Polytronix, Gauzy, View, Research Frontiers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Architecture Smart Glass Market Trends and Innovations
Process innovation in thin-film deposition is collapsing electrochromic production costs while regulatory pressure on building energy intensity accelerates specification migration from static high-performance glazing toward active solar control.
Multi-layer sputtered tungsten oxide-nickel oxide electrochromic stacks are consolidating market share in premium facade applications. Class A office developers in Manhattan and Chicago specify these systems for LEED v4.1 energy performance credits. The technology is consolidating supplier margins by displacing complex mechanical shading systems and their maintenance burden.
REACH Annex XIV authorization requirements for chromium compounds in electrochromic manufacturing are forcing reformulation toward nickel-based counter-electrodes. German coating facilities face 2026 deadlines for alternative chemistry validation. Curtain wall fabricators are accelerating qualification testing to maintain CE marking continuity across European project pipelines.
Building owners now specify performance-guaranteed energy savings contracts rather than component procurement for facade retrofits. Third-party energy service companies assume technology risk and capture verified HVAC load reductions through measurement and verification protocols. This model dominates U.S. federal building modernization programs under Energy Star procurement guidelines.
Architecture Smart Glass Market Segmentation
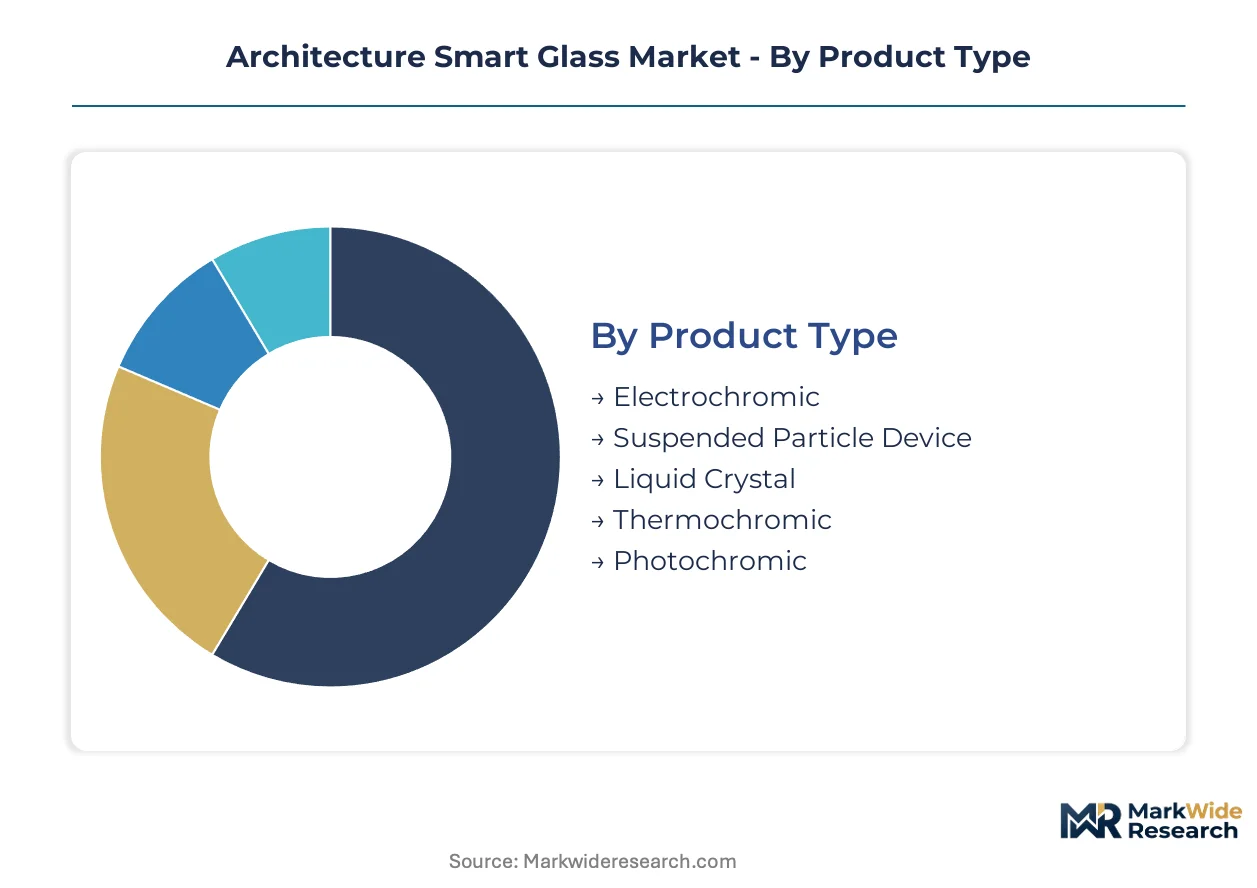
Technology selection in architecture smart glass hinges on balancing electrical infrastructure requirements against performance precision. End-use specifications vary sharply across climate zones, building codes, and operational priorities, fragmenting procurement patterns across the value chain.
Product Type:
Customization intensity spans from fully programmable electrochromic systems to passive photochromic coatings requiring zero electrical integration.
- Electrochromic:Multi-layer tungsten oxide-nickel oxide stacks enable precise solar heat gain coefficient modulation through applied voltage. Demand concentrates in German office tower retrofits where EU Green Deal operational carbon limits mandate dynamic facade upgrades.
- Suspended Particle Device:Polymer-dispersed particle films deliver instant opacity transitions via electrical orientation. Hospitality suites in Dubai and Singapore deploy these systems to command rate premiums through on-demand privacy functionality.
- Liquid Crystal:Nematic crystal alignment enables rapid switching between transparent and frosted states for controlled visual access. Healthcare sterile partitions in U.S. surgical suites merge infection control with observation flexibility.
- Thermochromic:Vanadium dioxide coatings passively modulate infrared transmission based on surface temperature without electrical infrastructure. Budget-constrained retrofits in Indian commercial developments favor this lower first-cost alternative.
- Photochromic:Silver halide-embedded substrates darken under ultraviolet exposure for basic glare reduction. Residential skylight applications in Australia leverage this maintenance-free solar control option.
Most installed capacity flows through electrochromic facades. Expansion is steepest in suspended particle device hospitality installations.
Application:
Surface area exposure and structural load requirements differentiate specification criteria across building envelope positions.
- Facades:Large-format curtain wall integration demands electrochromic insulated glass units with structural silicone compatibility. Manhattan and Chicago Class A office developments specify these systems for LEED v4.1 energy performance credits.
- Curtain Walls:Unitized system replacement requires recertification of wind load and thermal performance. North American commercial retrofits face extended timelines due to facade contractor coordination complexity.
- Windows:Operable sash integration limits glazing thickness and electrical routing options. Residential and light commercial segments prioritize thermochromic simplicity over active control systems.
- Skylights:Overhead exposure maximizes solar gain reduction potential while demanding impact resistance and condensation management. Atrium installations in Scandinavian institutional buildings combine electrochromic tinting with snow load engineering.
- Partitions:Interior division applications prioritize privacy switching speed over thermal performance. Liquid crystal dominates healthcare and corporate meeting room deployments.
Facade and curtain wall applications absorb the majority of project value. Partitions are gaining share fastest in healthcare and hospitality fit-outs.
Installation Type:
Project delivery mode determines technology risk allocation and commissioning complexity across the building lifecycle.
- Retrofit Projects:Existing facade replacement requires structural engineering reassessment and electrical infrastructure retrofit. EU Green Deal renovation mandates in Germany, France, and Netherlands accelerate 1970s office tower electrochromic upgrades.
- New Construction:Integrated design enables optimized low-voltage routing and building management system compatibility. California Title 24 automated daylighting requirements natively favor electrochromic specification over external shading.
- Commercial Complexes:Multi-tenant ownership structures complicate performance guarantee allocation and maintenance responsibility. Energy service company contracting models assume technology risk through verified HVAC savings.
- Institutional Buildings:Public procurement protocols prioritize lifecycle cost analysis and warranty duration. Federal building modernization programs under U.S. EPA Energy Star guidelines dominate specification volume.
- Entertainment Venues:Spectacle-driven environments demand rapid opacity transitions and custom tint programming. Suspended particle device installations in Las Vegas and Macau integrated resorts enable dramatic spatial transformations.
Retrofit project pipelines command premium pricing due to engineering complexity. New construction offers the steepest volume expansion trajectory as automated building codes proliferate.
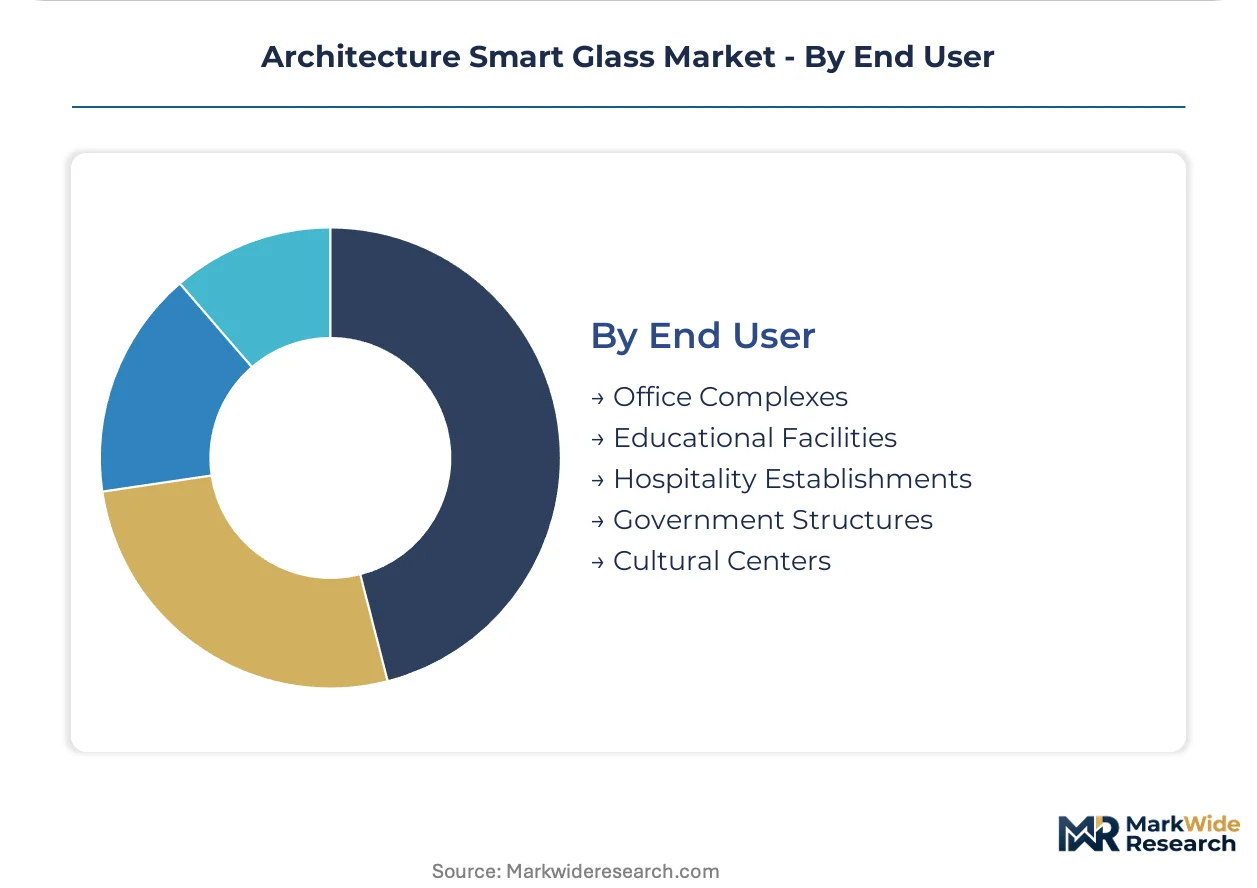
End User:
Operational priorities range from energy compliance to guest experience differentiation across facility types.
- Office Complexes:Tenant comfort and energy cost reduction drive electrochromic facade investment. Manhattan and Chicago Class A developments specify performance-guaranteed installations.
- Hospitality Establishments:Guest room privacy and common area ambiance command suspended particle device premiums. Dubai luxury properties monetize instant tint transitions through rate positioning.
- Educational Facilities:Daylighting optimization for student performance competes with capital budget constraints. University laboratory buildings in Germany prioritize electrochromic precision for glare-sensitive research environments.
- Government Structures:Procurement mandates under U.S. federal Energy Star programs and EU public procurement directives shape specification criteria. Security considerations in certain facilities limit cloud-connected tint management.
- Cultural Centers:Artifact protection and visitor comfort require precise ultraviolet and thermal control. Museum atriums deploy electrochromic skylights to balance natural illumination with conservation requirements.
Office complexes represent the largest installed base. Hospitality establishments are climbing the fastest as experience differentiation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochromic technology first achieved commercial scale in German automotive and aerospace applications before migrating to building facades. German coating facilities established the process engineering templates that now dominate European retrofit pipelines. The industry's geographic footprint now spans five distinct national markets with divergent regulatory drivers.
United States
Federal building modernization programs under EPA Energy Star guidelines drive institutional demand for performance-guaranteed electrochromic installations. California's Title 24 building code mandates automated daylighting controls that smart glass satisfies natively. Manhattan and Chicago Class A office developments specify these systems for LEED v4.1 energy performance credits.
Germany
Bauhaus-inspired institutional projects pair heritage aesthetics with electrochromic upgrades across 1970s office tower retrofits. The EU Green Deal's operational carbon limits on existing buildings accelerate facade renovation mandates. Coating facilities in North Rhine-Westphalia face 2026 REACH Annex XIV deadlines for chromium-free counter-electrode reformulation.
China
Dual carbon goals under MEE directives push commercial real estate toward low-carbon envelope solutions in Shanghai and Shenzhen premium developments. Refined tungsten feedstock processors control intermediate chemical supply for electrochromic layer production. Yangtze River Delta glass fabricators integrate upstream coating capacity to capture margin from European retrofit demand.
United Arab Emirates
Hospitality-driven suspended particle device installations in Dubai luxury properties monetize instant privacy transitions through rate positioning. MOHAP building efficiency guidelines shape procurement for healthcare facility expansions. Integrated resorts in Las Vegas and Macau deploy similar spectacle-driven spatial transformation systems.
India
LEED Platinum certification targets in Mumbai and Bangalore premium office developments create specification openings for dynamic glazing. Budget-constrained retrofits favor thermochromic vanadium dioxide coatings without electrical infrastructure. Central Electricity Authority efficiency mandates accelerate code adoption for automated envelope controls in commercial construction.
Architecture Smart Glass Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and full-system bundling capability. The vendor base organizes into three tiers: integrated float-to-coating conglomerates, specialized electrochromic technology developers, and regional glass fabricators licensing core patents. Dominant competitive moves include backward integration into tungsten oxide deposition capacity and cloud-based tint management software bundling to capture recurring revenue streams.
Among integrated materials conglomerates, Saint-Gobain and AGC exemplify the float-glass-to-coating archetype with captive substrate supply. View occupies a position on the full-system installation vector, bundling glazing with building management integration. Gentex Corporation represents the automotive-heritage technology migration pattern, transferring dimming expertise from rear-view mirrors to architectural applications.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC |
| Gentex Corporation |
| Corning Incorporated |
| PPG Industries |
| Polytronix |
| Gauzy |
| View |
| Research Frontiers |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap glass fabricators in Germany and Italy anchor regional supply clusters, translating heritage coating expertise into pricing discipline that resists commoditization pressure from Asian volume producers. Their captive relationships with institutional project developers sustain premium realization even as raw material volatility transmits through tungsten oxide feedstock markets.
Pricing Analysis
Project-based contracting with performance-guaranteed energy savings dominates premium facade procurement, separating electrochromic system providers from commodity glazing vendors. Price differentiation rests on CE marking tier and cloud-based tint management bundling, with federal Energy Star procurement guidelines in the United States enforcing stringent qualification thresholds. Cost compression in standard-grade thermochromic alternatives is intensifying because passive vanadium dioxide coatings require zero electrical infrastructure. Budget-constrained retrofit segments in Indian commercial developments exhibit the highest price sensitivity, while German institutional clients prioritize lifecycle cost analysis over first-cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Chinese refined tungsten processors who control intermediate chemical supply for electrochromic layer deposition. Manufacturing gravity centers on Germany, China, and Japan, with Yangtze River Delta fabricators integrating upstream coating capacity to capture margin from European retrofit demand. Raw material dependencies encompass tungsten oxide, lithium salts, and nickel oxide counter-electrode formulations. Tariff exposure on Chinese-processed tungsten intermediates threatens margin stability for European coating facilities. Distribution runs through curtain wall system integrators and facade contractors who assume commissioning risk and BMS protocol compatibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The architecture smart glass market functions as a regulatory compounder where EU Green Deal operational carbon limits on existing buildings generate durable retrofit demand. California Title 24 automated daylighting mandates and federal Energy Star procurement guidelines create parallel specification pipelines across distinct regulatory jurisdictions.
For Market Incumbents: Extend cloud-based tint management software bundling to capture recurring revenue streams and deepen switching costs for Class A office developers. Backward integration into tungsten oxide deposition capacity defends margin position against Chinese feedstock price volatility. Accelerate REACH Annex XIV-compliant nickel-based counter-electrode qualification to maintain CE marking continuity across European project pipelines.
For New Entrants and Emerging Players: Begin with liquid crystal sterile partition applications in U.S. surgical suites and patient observation rooms, where infection control requirements create specification stickiness absent from commodity glazing. Target Indian LEED Platinum premium office developments in Mumbai and Bangalore through thermochromic vanadium dioxide offerings that circumvent electrical infrastructure barriers. Pursue energy service company partnerships to assume technology risk through verified HVAC load reduction contracts.
For Investors and Strategic Acquirers: Building materials conglomerates with float-to-coating footprints represent the most active acquirer in this space, seeking electrochromic technology to complete facade system portfolios. The five-to-ten year viability window favors targets with validated chromium-free formulations and established curtain wall integration protocols. Monitor REACH Annex XIV authorization timelines as an inflection indicator for competitive repositioning among European coating facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Oxide Deposition | German coating facilities secure captive feedstock supply against Chinese processor concentration. |
| Cloud-Based Tint Management Platform Launch | Full-system providers capture recurring software revenue through BMS integration and predictive maintenance algorithms. |
| REACH Annex XIV Nickel-Based Counter-Electrode Validation | Coating facilities maintain CE marking continuity ahead of chromium compound authorization deadlines. |
| Energy Service Company Contracting Model Expansion | Third-party ESCOs assume technology risk through verified HVAC load reduction and measurement protocols. |
| Healthcare Sterile Partition Specialization | Liquid crystal providers merge infection control with observation flexibility in U.S. surgical suite deployments. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged facade contractors, curtain wall system integrators, building management system engineers, and electrochromic coating facility technical directors. Secondary sources encompassed EU Green Deal regulatory filings, EPA Energy Star procurement guidelines, California Title 24 building code documentation, and SEC filings from publicly traded glass manufacturers. Bottom-up project pipeline assessment triangulated against top-down regulatory mandate quantification.
Rate-of-change decomposition anchored the analytical framework across the projection horizon, disaggregating volume expansion by technology type, application surface area, and installation mode. Segmentation dimensions modeled encompassed product technology, building envelope position, project delivery mode, and end-use facility type. CAGRs derived from installed base growth, replacement cycle acceleration, and specification penetration rates. Industry-specific forecast inputs included EU Green Deal renovation mandate implementation timelines and California Title 24 code adoption patterns.
Several conditions sit outside the modeled scope, including geopolitical disruption to tungsten oxide feedstock flows, unanticipated REACH regulatory scope expansion, and breakthrough thermochromic performance parity with electrochromic systems. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and construction activity levels. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
AEC Market
Building Automation Systems
Global Building Information Modeling (BIM) Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Europe Commercial Refrigeration Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
China Revolving Doors Market