
 Europe Commercial Refrigeration Market | 2026-2036
Europe Commercial Refrigeration Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Refrigeration Market Insights
Quick-service restaurant chains are redrawing procurement priorities across Europe's commercial refrigeration landscape. Epta Group leverages its integrated manufacturing footprint to dominate display case supply for major retail banners. Liebherr International AG anchors premium freezer demand through specialized engineering for pharmacy and laboratory cold chains. Carrier Global Corp. competes on service network density, sustaining aftermarket revenue across fragmented foodservice accounts.
Europe commercial refrigeration encompasses engineered cooling systems maintaining precise temperature bands between minus twenty-five and positive fifteen degrees Celsius for perishable inventory preservation. Equipment integrates hermetic compressors, multi-layer insulation panels, and electronic expansion valves to achieve energy efficiency ratios exceeding two point five in retail deployments. Display cases generate the largest revenue pool among product types, reflecting supermarket renovation cycles across mature Western European markets. Cascade refrigeration systems are gaining fastest within technology categories, driven by carbon dioxide adoption under tightening fluorinated gas restrictions. Restaurant end users present concentrated upgrade demand, particularly in Southern Europe where aging installed bases face compliance deadlines.
The European Commission's F-Gas Regulation and Ecodesign Directive jointly mandate refrigerant phase-down and minimum energy performance standards, forcing equipment replacement timelines. ECHA oversees chemical restrictions affecting insulation foam blowing agents, while CE marking requirements govern market access for imported components. Stakeholders must monitor delegated act revisions on natural refrigerant safety standards and assess manufacturing localization against potential carbon border adjustment implications.
Market Dynamics
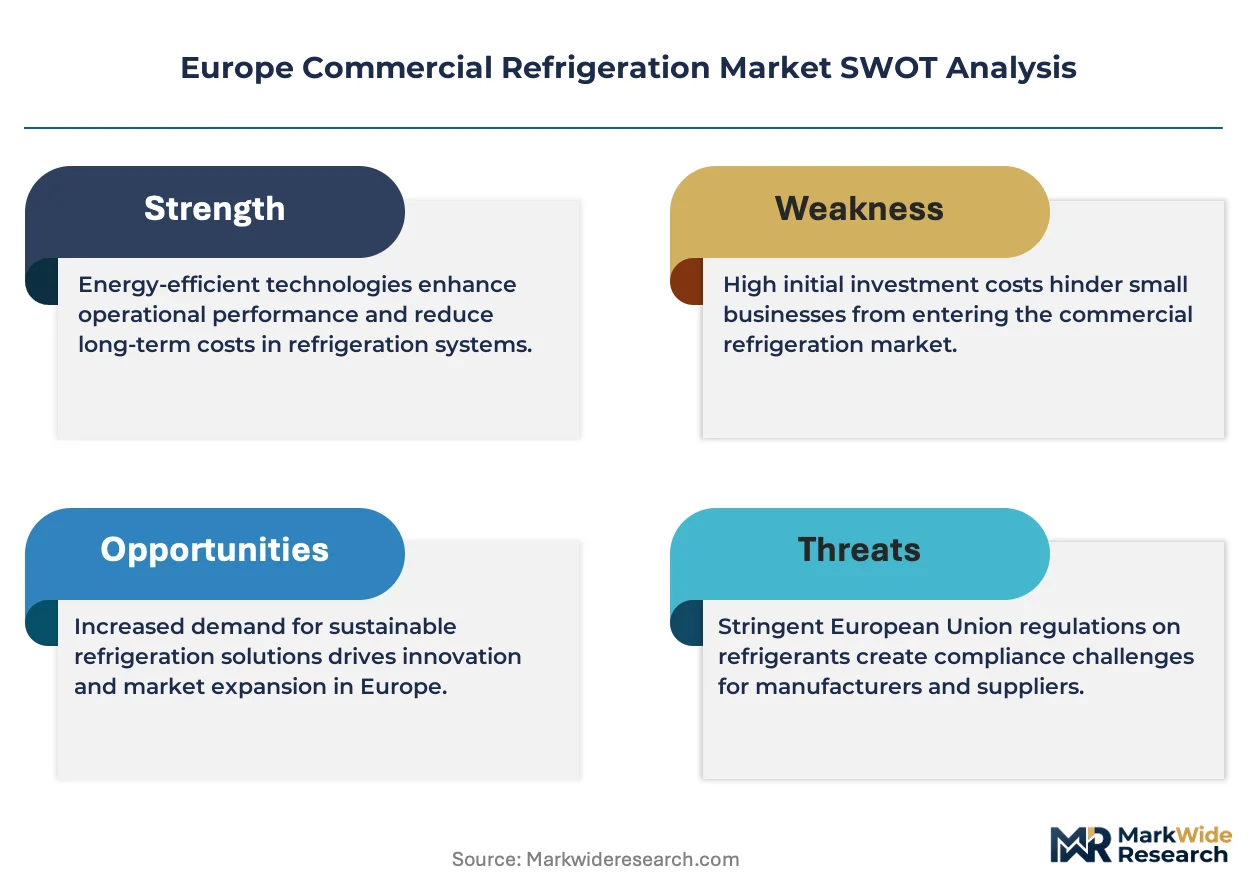
The EU F-Gas Regulation is compressing equipment replacement timelines across Europe's commercial refrigeration base, forcing simultaneous upgrades to natural refrigerant architectures and energy-efficient insulation systems. This regulatory pressure intersects with supermarket renovation cycles and quick-service restaurant expansion to create concentrated demand windows in Germany, France, and Southern Europe.
Growth Catalysts
- Regulatory Phase-Down Mandates:The EU F-Gas Regulation mandates an eighty percent reduction in hydrofluorocarbon emissions by 2030, compelling supermarket operators to accelerate retrofit programs.
- Quick-Service Restaurant Expansion:Chains across Germany and France are enlarging cold storage footprints to support delivery-optimized kitchen layouts and extended holding capacity.
- Cascade System Technology:Carbon dioxide-based cascade refrigeration is capturing retrofit share as operators seek compliance pathways that avoid synthetic refrigerant supply constraints.
Market Restraints
- Copper and Aluminum Input Volatility:Compressor manufacturing and heat exchanger fabrication face margin pressure from base metal price swings tied to energy-intensive smelting economics.
- Specialized Component Concentration:Electronic expansion valves and natural refrigerant-rated safety controls concentrate among a narrow supplier base in Germany and Northern Italy.
- Technical Integration Complexity:Carbon dioxide systems operate at substantially higher pressures than legacy hydrofluorocarbon equipment, requiring redesigned piping specifications and technician retraining.
Strategic Opportunities
- Pharmacy Cold Chain Expansion:Vaccine distribution infrastructure and biologics storage requirements are extending demand for precision temperature control into community pharmacy networks.
- Service Revenue Unbundling:Predictive maintenance contracts and remote monitoring subscriptions offer recurring revenue streams distinct from equipment sales cycles.
- Southern Europe Retrofit Backlog:Aging installed bases in Italy and Spain face simultaneous compliance deadlines, creating concentrated demand for turnkey replacement solutions.
Industry Challenges
- Natural Refrigerant Technician Scarcity:Carbon dioxide and hydrocarbon system installation and servicing require specialized certification pathways that training institutions have not yet scaled to match demand velocity.
- CE Marking Revision Cycles:Evolving harmonized standards for natural refrigerant safety and energy performance create documentation lag risks for imported equipment.
- Legacy Control Integration:Building management system interoperability gaps complicate fleet-wide monitoring deployments across mixed-vendor installed bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Refrigeration Market |
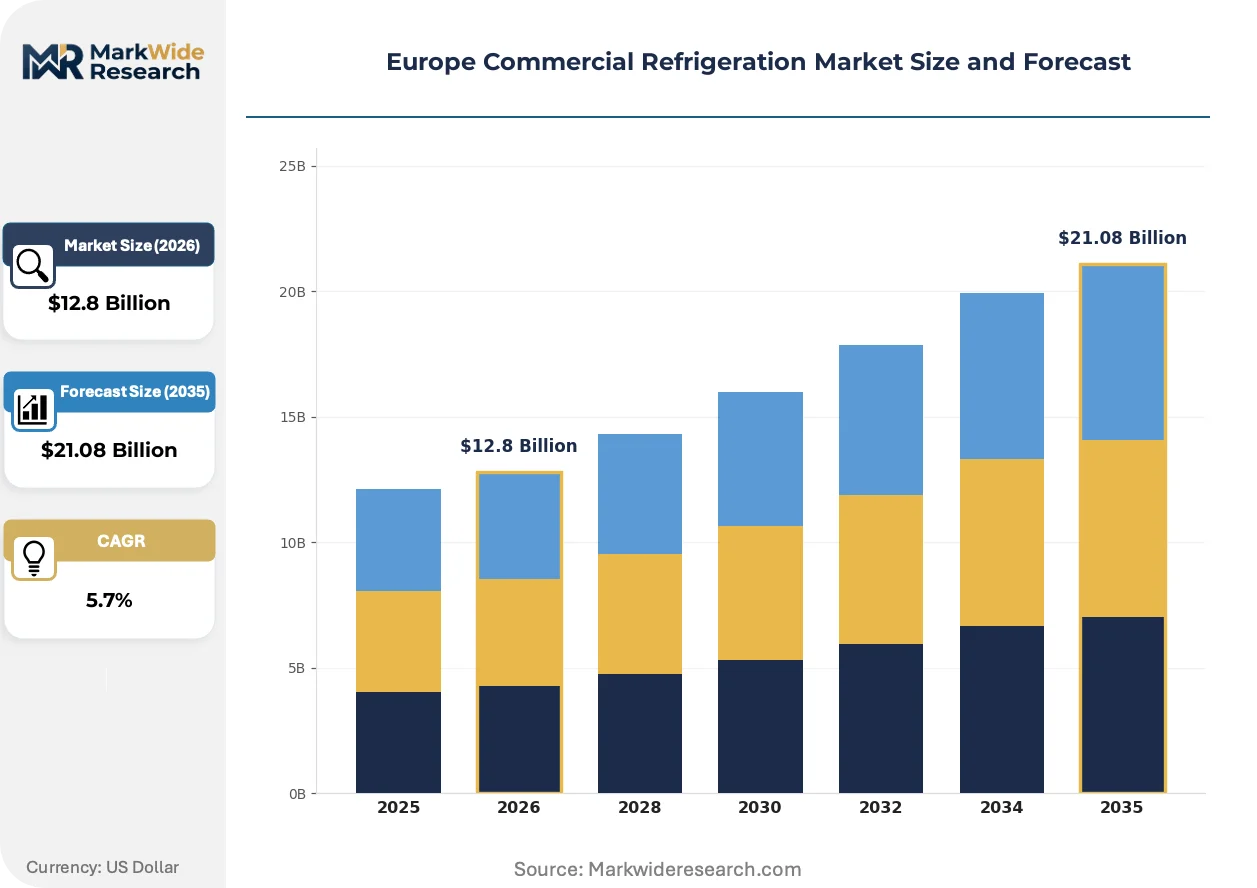
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Freezers, Ice Makers, Display Cases Application: Retail, Foodservice, Healthcare, Industrial Technology: Recompressor, Cascade, Absorption, Thermoelectric End User: Supermarkets, Restaurants, Pharmacies, Warehouses |
| Companies Covered | Epta Group, Liebherr International AG, ARNEG SPA, Illinois Tool Works Inc., HOSHIZAKI Europe BV, Daikin Industries Ltd., Carrier Global Corp., Viessmann Climate Solutions SE, Electrolux Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Refrigeration Market Trends and Innovations
Refrigeration architecture is fragmenting into modular, refrigerant-specific subsystems as operators seek compliance flexibility without full equipment replacement. This technical decomposition is redrawing supplier relationships and service delivery models across the European market.
Transcritical carbon dioxide booster systems are decomposing the traditional centralized plant model in large-format retail. German supermarket operators are deploying these architectures in new-build and deep-renovation projects. The technology is decomposing incumbent rack system market share by enabling zoned temperature management with reduced refrigerant charge volumes.
The EU Ecodesign Directive's delegated acts on refrigerating appliances are tightening minimum energy performance thresholds for display cases and storage cabinets. Manufacturers must redesign insulation profiles and compressor efficiency maps to maintain market access. Southern European retrofit programs are most exposed to these requirements, as aging equipment fails to meet the revised index benchmarks.
Leasing and performance-based equipment provision are displacing outright purchase in fragmented foodservice accounts. Independent restaurant operators in France and Spain are adopting subscription models that bundle installation, maintenance, and compliance monitoring. This shift is most visible in urban clusters where capital constraints and technical staffing gaps concentrate among small-format operators.
Europe Commercial Refrigeration Market Segmentation
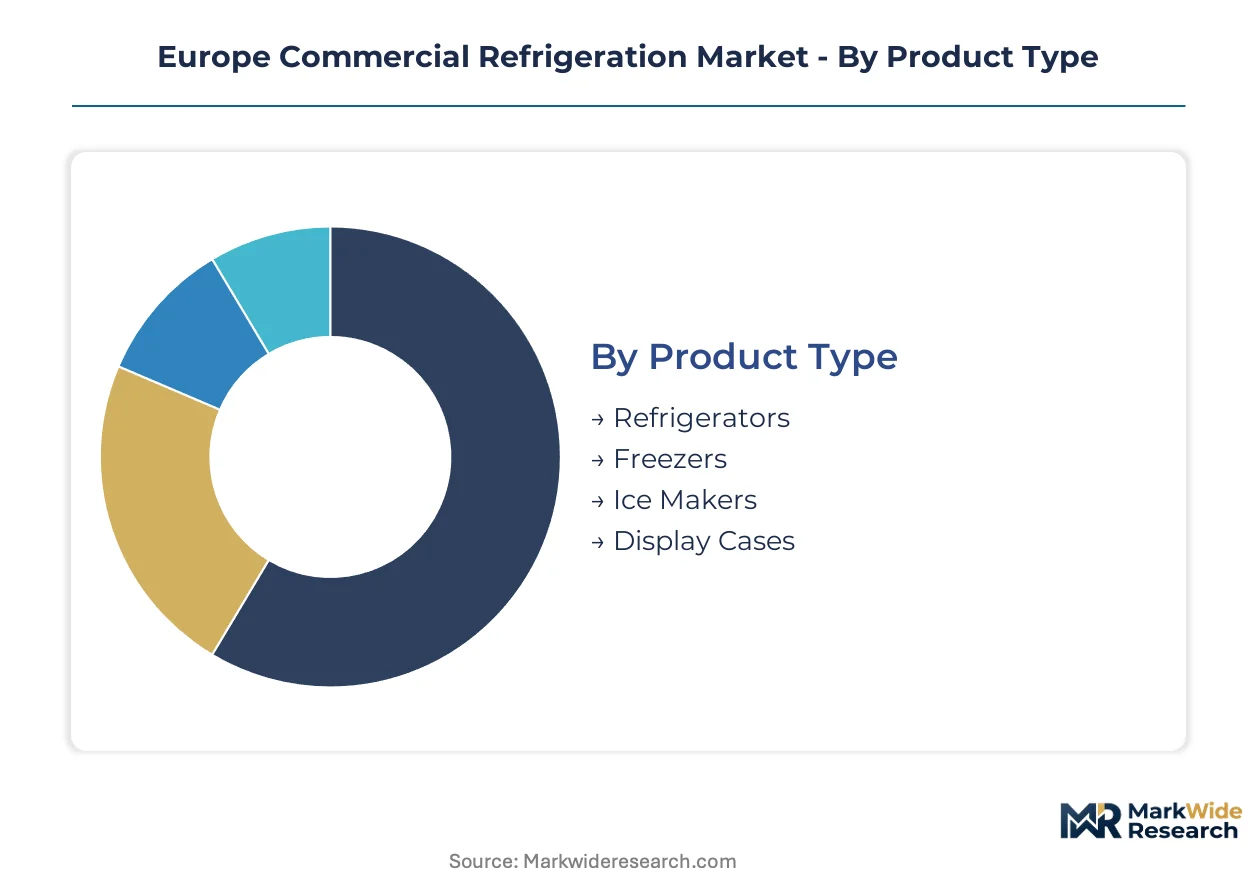
Equipment segmentation in Europe's commercial refrigeration market tracks divergent compliance timelines and retrofit economics across member states. Product architecture, application intensity, and technology maturity create distinct investment profiles that suppliers must navigate under the EU F-Gas Regulation's phasedown mandates.
Product Type:
Regulatory differentiation separates display cases and refrigerators from freezers and ice makers under Ecodesign Directive energy performance thresholds, with CE marking requirements tightening fastest for high-volume retail equipment categories.
- Display Cases:Multi-deck and island configurations integrate hermetic compressors with low-emissivity glass and LED lighting to meet revised energy efficiency ratios. German supermarket renovation cycles and French hypermarket retrofit programs concentrate demand for these units as operators face simultaneous F-Gas and Ecodesign compliance deadlines.
- Refrigerators:Reach-in and walk-in cold rooms employ polyurethane foam insulation and electronic expansion valves to maintain temperature bands between two and eight degrees Celsius. Italian foodservice distributors and Spanish restaurant chains are expanding procurement of these systems to replace hydrofluorocarbon-based installed bases before regulatory phase-down milestones.
- Freezers:Ultra-low temperature cabinets and blast freezers maintain minus eighteen to minus twenty-five degrees Celsius for frozen inventory preservation.
- Ice Makers:Modular and self-contained units produce flake, nugget, and cube ice for beverage and food display applications.
Display cases handle the majority of throughput; ice makers are expanding most quickly on share as quick-service restaurant chains enlarge cold storage footprints.
Application:
Cost tier separation between retail and foodservice drives divergent equipment specifications, with healthcare and industrial segments commanding premium pricing for precision temperature control and redundant cooling architectures.
- Retail:Supermarkets and convenience stores deploy centralized rack systems and distributed display cases across selling floors and back-of-house storage. Epta Group and Carrier Global Corp. compete intensely for banner contracts in France and Germany where renovation cycles align with regulatory deadlines.
- Foodservice:Restaurants, cafeterias, and catering operations utilize undercounter units, prep tables, and walk-in coolers optimized for high-access frequency and kitchen workflow integration. Southern European independent operators in Spain and Italy face capital constraints that accelerate leasing and subscription model adoption.
- Healthcare:Hospital pharmacies, blood banks, and clinical laboratories require validated cold chain equipment with continuous temperature monitoring and alarm systems.
- Industrial:Food processing facilities and cold storage warehouses employ large-capacity ammonia and carbon dioxide systems for bulk inventory preservation.
Retail commands the largest equipment volume; healthcare is climbing the fastest as vaccine distribution infrastructure extends into community pharmacy networks.
Technology:
Volume concentration in recompressor systems is giving way to cascade architectures as natural refrigerant adoption accelerates under fluorinated gas restrictions, with thermoelectric and absorption technologies serving niche applications.
- Cascade:Carbon dioxide-based systems operating in transcritical or subcritical configurations enable zoned temperature management with reduced refrigerant charge volumes. German operators are deploying these architectures in new-build and deep-renovation projects to avoid synthetic refrigerant supply constraints.
- Recompressor:Traditional hermetic and semi-hermetic compressor racks using hydrofluorocarbon refrigerants dominate legacy installed bases across Southern Europe. These systems face accelerated replacement timelines as the EU F-Gas Regulation mandates eighty percent emission reductions, compelling operators in Italy and Spain to evaluate natural refrigerant retrofits.
- Absorption:Heat-driven cooling cycles utilizing ammonia-water or lithium bromide pairs serve industrial cogeneration and waste heat recovery applications.
- Thermoelectric:Solid-state Peltier modules provide compact, vibration-free cooling for portable medical transport and small-format beverage units.
Recompressor systems retain the deepest installed base; cascade configurations are gaining share fastest as carbon dioxide adoption decomposes incumbent rack system market positions.
End User:
Customer type determines procurement sophistication, with supermarkets and warehouses executing centralized fleet replacements while restaurants and pharmacies fragment demand across decentralized decision-making units.
- Supermarkets:Large-format grocery operators manage enterprise-wide refrigeration fleets with standardized specifications and centralized maintenance contracts. Epta Group leverages integrated manufacturing to dominate display case supply for major retail banners across Germany, France, and Italy.
- Restaurants:Quick-service chains and independent foodservice operators prioritize equipment reliability and service network density over capital cost minimization. French and Spanish urban clusters show concentrated subscription model adoption as small-format operators face technical staffing gaps.
- Pharmacies:Community and hospital pharmacy networks require precision temperature control for vaccine storage and biologics preservation.
- Warehouses:Cold storage and distribution centers employ large-scale ammonia and carbon dioxide systems for bulk frozen and chilled inventory.
Supermarkets drive the bulk of replacement volume; pharmacies are expanding most steeply as cold chain infrastructure extends beyond hospital networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket procurement teams and quick-service restaurant chains concentrate upgrade demand across distinct national compliance calendars. Each member state presents unique retrofit economics shaped by F-Gas Regulation phase-down velocity and domestic renovation cycles.
Germany
Hypermarket operators and discount grocery chains drive display case replacement volumes. The F-Gas Regulation's delegated acts on refrigeration compress manufacturing standards accelerate equipment turnover. Bavaria's industrial refrigeration clusters supply transcritical carbon dioxide components to retail renovation projects nationwide.
France
Quick-service restaurant expansion and bakery chain cold storage upgrades dominate equipment procurement. ECHA oversight of foam blowing agent restrictions forces insulation system redesigns. The Paris metropolitan area concentrates subscription-based equipment leasing among independent foodservice operators facing capital constraints.
Italy
Independent supermarket cooperatives and regional foodservice distributors manage fragmented retrofit programs. CE marking revisions for natural refrigerant safety controls create documentation bottlenecks for imported components. Lombardy's commercial kitchen equipment fabricators scale production of hydrocarbon-compatible prep tables and undercounter units.
Spain
Aging installed bases in hospitality and tourism-dependent foodservice face simultaneous compliance deadlines. The EU Ecodesign Directive's minimum energy performance thresholds disqualify legacy equipment from continued operation. Catalonia's refrigeration service networks expand technician certification programs for carbon dioxide system maintenance.
United Kingdom
Pharmacy cold chain infrastructure and convenience store format expansion sustain equipment demand post-regulatory divergence. MHRA guidelines on medicinal product storage temperature validation extend precision control requirements into community pharmacy networks. The Midlands manufacturing corridor supplies modular cold room panels to retail and healthcare installations.
Europe Commercial Refrigeration Market Competitive Landscape
Player mix skews toward integrated manufacturing conglomerates with captive component supply and specialized engineering houses serving premium temperature-control segments. Market structure concentrates around three strategic archetypes: full-system integrators controlling display case through compressor value chains, precision cold chain specialists targeting pharmacy and laboratory verticals, and service-network operators monetizing aftermarket maintenance contracts. Dominant competitive moves include backward integration into compressor manufacturing and geographic expansion of technical service footprints.
Among Italy-based integrated manufacturers, Epta Group and ARNEG SPA occupy positions as full-system architects for retail banner contracts. Liebherr International AG anchors the precision-engineering tier with specialized freezer architectures. Carrier Global Corp. exemplifies the service-density model, leveraging maintenance network scale across fragmented foodservice accounts. These three archetypes—integrated manufacturing, precision engineering, and service-network scale—define competitive positioning across European procurement cycles.
| Leading Market Players |
|---|
| Epta Group |
| Liebherr International AG |
| ARNEG SPA |
| Illinois Tool Works Inc. |
| HOSHIZAKI Europe BV |
| Daikin Industries Ltd. |
| Carrier Global Corp. |
| Viessmann Climate Solutions SE |
| Electrolux Group |
| Others |
Pricing and Supply Chain Analysis
Ninety-day compressor lead times from German suppliers compress procurement windows for supermarket retrofit programs, concentrating pricing power among integrated manufacturers with captive component production while forcing foodservice operators toward subscription models that externalize capital risk.
Pricing Analysis
The carbon dioxide cascade-to-hydrofluorocarbon recompressor pricing gap spans three technology generations, with transcritical systems commanding project-based premiums against legacy rack equipment while hydrocarbon-compatible units occupy a contracting mid-market. Pricing stratifies across premium, standard, and economy tiers keyed to energy efficiency certification grade and after-sales service bundling. Cost compression in standard-tier display cases intensifies as Chinese component imports displace Southern European fabrication. Quick-service restaurant chains exhibit lowest price sensitivity due to compliance-driven replacement timelines, while independent Italian operators face acute capital constraints.
Supply Chain Analysis
Germany and Northern Italy anchor electronic expansion valve and natural refrigerant safety control production, while Bavarian industrial clusters supply transcritical carbon dioxide compressor racks. Copper and aluminum draw from energy-intensive smelting operations in Spain and Eastern Europe, exposing heat exchanger fabrication to electricity price volatility. Single-source vulnerability concentrates in specialized safety control assemblies from Lombardy-based suppliers. Distribution runs through banner-level procurement contracts for retail chains and fragmented dealer networks serving foodservice accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's eighty percent hydrofluorocarbon phase-down mandate positions Europe's commercial refrigeration market as a high-growth disruption, with natural refrigerant retrofit cycles compressing decade-long replacement windows into concentrated demand surges.
For Market Incumbents: Shield installed base relationships by embedding predictive maintenance subscriptions that lock out independent service competitors, while accelerating backward integration into compressor manufacturing to offset margin pressure from copper and aluminum volatility. Prioritize certification investment for carbon dioxide system safety controls before CE marking revisions tighten documentation requirements. For New Entrants and Emerging Players: Anchor in Southern European foodservice leasing models where capital-constrained Spanish and Italian operators seek subscription alternatives to outright purchase. Target pharmacy cold chain expansion as vaccine distribution infrastructure extends into community networks, deploying remote monitoring capabilities as the primary go-to-market wedge against established service networks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because the F-Gas Regulation's phasedown timeline creates non-discretionary replacement demand insulated from cyclical downturns. Target acquisition profiles center on regional service networks with technician certification pipelines for natural refrigerant systems. The signal to watch is delegated act revisions on carbon dioxide safety standards that would accelerate equipment obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Epta Group's captive supply of hermetic compressors insulates margin position against base metal volatility. |
| Remote Monitoring Platform Deployment | Carrier Global Corp.'s predictive maintenance subscriptions convert transactional equipment sales into recurring revenue streams. |
| Pharmacy Cold Chain Certification Investment | Liebherr International AG's precision freezer architectures capture vaccine distribution infrastructure expansion. |
| Technician Certification Program Scaling | Catalonia's refrigeration service networks address carbon dioxide system maintenance scarcity before compliance deadlines. |
| Subscription Model Expansion in Foodservice | French urban clusters demonstrate capital-constrained operator preference for bundled installation and compliance monitoring. |
Research Methodology
Desk research of EU regulatory filings, ECHA chemical restriction databases, and national customs trade data preceded structured interviews with supermarket procurement directors, foodservice equipment distributors, compressor manufacturing plant managers, and refrigeration service network operators. Primary fieldwork across Germany, France, Italy, and Spain validated secondary estimates of retrofit program timelines and natural refrigerant adoption rates. Bottom-up equipment shipment analysis triangulated against top-down energy consumption projections for commercial refrigeration stock.
Variance decomposition across product type, application intensity, technology generation, and end-user procurement sophistication shaped the analytical framework over the projection horizon. CAGRs derived from segmented replacement cycle modeling incorporated F-Gas Regulation phase-down velocity, Ecodesign Directive energy performance threshold tightening, and supermarket renovation cycle alignment. Forecast inputs included technician certification pipeline capacity and copper price futures curves.
Material uncertainties — regulatory delegated act timing, carbon border adjustment implementation, and natural refrigerant supply chain scaling — sit outside the modeled envelope. Forecasts reflect assumptions about compliance deadline adherence and substitution technology cost trajectories. Recalibration cycles align with material shifts in F-Gas Regulation enforcement intensity and Ecodesign Directive threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Architecture Smart Glass Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
North America Building Automation System Market
Building Automation Systems
Escalator Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Vinyl Strip Door and Curtains Market
Building Automation Systems
United States Smart Windows Market
Building Automation Systems
Building Management System Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Asia-Pacific Building Automation System Market
Building Automation Systems
Zero Energy Buildings Market