
 Integrated Building Management Systems Market | 2026-2036
Integrated Building Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Building Management Systems Market Outlook
Healthcare facility adoption is expanding as hospitals retrofit aging infrastructure with unified control platforms that consolidate HVAC, lighting, and security into single-dashboard operations. Siemens leverages deep vertical integration across European hospital networks to sustain project margins on large-scale deployments. Johnson Controls anchors North American healthcare infrastructure through service contracts that extend across decades of equipment lifecycle management. Honeywell competes on wireless protocol leadership, positioning its IoT sensor arrays for rapid retrofit installations in aging medical campuses.
Integrated Building Management Systems coordinate mechanical, electrical, and digital subsystems through centralized software architectures that execute setpoint optimization, fault detection, and energy load balancing across facility portfolios. These platforms typically deploy BACnet or Modbus communication protocols to enable interoperability between proprietary equipment from disparate manufacturers, with cloud-based middleware now enabling remote diagnostics and predictive maintenance scheduling. HVAC Control dominates current procurement volumes as thermal regulation accounts for the largest share of building energy consumption and offers the most quantifiable return on investment metrics for facility operators. Cloud-Based Solutions represent the fastest-expanding technology segment as building owners shift capital expenditure toward subscription operational models that reduce on-premise server maintenance burdens.
The EU Energy Performance of Buildings Directive mandates systematic deployment of building automation and control systems across commercial stock above specific floor-area thresholds, directly stimulating retrofit demand across Germany, France, and Italy. The US Department of Energy enforces ANSI/ASHRAE/IES Standard 90.1 efficiency benchmarks that compel new construction to specify BMS-enabled equipment for code compliance. China's GB standards for intelligent building design, administered by MIIT, require integrated monitoring infrastructure in new municipal and transportation facilities. Stakeholders must monitor regulatory tightening on embodied carbon disclosure, as emerging frameworks will likely extend BMS scope from operational energy into materials tracking and supply chain emissions accounting.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for building automation, displacing on-premise server installations with subscription-based middleware that reduces capital intensity for facility operators.
Growth Catalysts
- EU Energy Performance of Buildings Directive:Mandates real-time monitoring infrastructure across commercial buildings above specified floor-area thresholds, directly stimulating retrofit procurement cycles in Germany, France, and Italy.
- Hospital infrastructure modernization:Healthcare facilities retrofit aging HVAC, lighting, and security systems through unified control platforms that consolidate operations into single-dashboard environments.
- Wireless BACnet protocols:Eliminate rewiring costs in aging building stock, enabling rapid sensor deployment without structural disruption to occupied facilities.
Market Restraints
- Semiconductor supply concentration:IoT sensor and controller production depends on fabrication capacity concentrated in East Asian foundries, creating procurement volatility for system integrators.
- Legacy protocol fragmentation:Proprietary communication standards from incumbent equipment manufacturers impede seamless interoperability between disparate subsystem vendors.
- Skilled technician scarcity:Commissioning of integrated BMS installations requires certified professionals in building automation, HVAC controls, and cybersecurity simultaneously.
Strategic Opportunities
- India's smart cities mission:Municipal infrastructure digitization programs create procurement pipelines for integrated monitoring platforms across transportation hubs and government facilities.
- Edge-AI convergence:On-device analytics for fault detection and predictive maintenance reduce cloud data transmission costs while enabling sub-second response times for critical building systems.
- Performance-based energy service contracts:Energy savings guarantees shift vendor compensation from equipment sales to verified operational outcomes, aligning incentives with facility owner ROI requirements.
Industry Challenges
- Cybersecurity certification timelines:IEC 62443 compliance for industrial control systems extends product development cycles and requires ongoing vulnerability management across deployed sensor networks.
- Retrofit integration complexity:Brownfield installations must reconcile incompatible vintage equipment with modern IP-based architectures without disrupting 24/7 facility operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Building Management Systems Market |
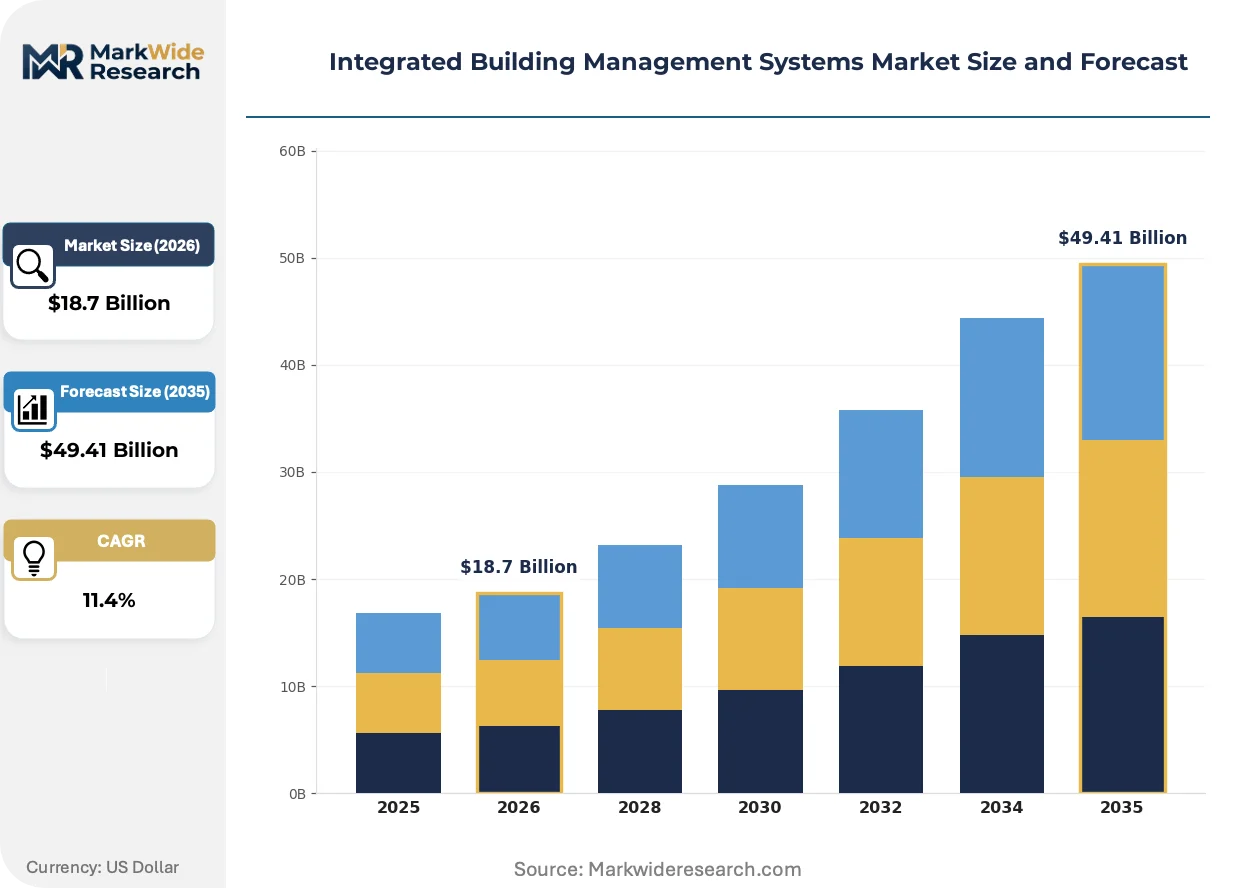
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Management Systems, Security Systems, HVAC Control, Lighting Control Technology: Wireless Technologies, Wired Technologies, Cloud-Based Solutions, IoT Integration End User: Commercial Buildings, Residential Buildings, Industrial Facilities, Educational Institutions Application: Smart Homes, Energy Efficiency, Security Management, Facility Management |
| Companies Covered | Siemens, Bosch, Johnson Controls, Legrand, ABB, Schneider Electric, Carrier, Lutron Electronics, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Building Management Systems Market Strategic Shifts
Digital twin technology is compressing commissioning cycles and enabling continuous optimization of building performance through virtual-physical synchronization.
Digital twin platforms are unifying mechanical, electrical, and operational data streams into persistent virtual replicas of physical facilities. Commercial real estate portfolios in Germany and Singapore are deploying these systems to simulate energy scenarios before physical implementation. This convergence is unifying previously siloed engineering disciplines into continuous feedback loops that compress retrofit planning from months to weeks.
REACH restrictions on fluorinated greenhouse gases are accelerating heat pump adoption and refrigerant monitoring requirements across European building stock. The F-Gas Regulation mandates leak detection systems for commercial refrigeration and HVAC above specific charge thresholds. Equipment manufacturers are responding with integrated refrigerant sensors that feed directly into centralized BMS dashboards for compliance documentation.
Facility managers are consolidating vendor relationships around full-lifecycle service agreements that bundle equipment, software, and maintenance into single-contract structures. This pattern displaces fragmented procurement of discrete subsystems through separate HVAC, lighting, and security contractors. The shift is most visible in US healthcare networks seeking to reduce administrative overhead and standardize response protocols across distributed campuses.
Integrated Building Management Systems Market Segmentation
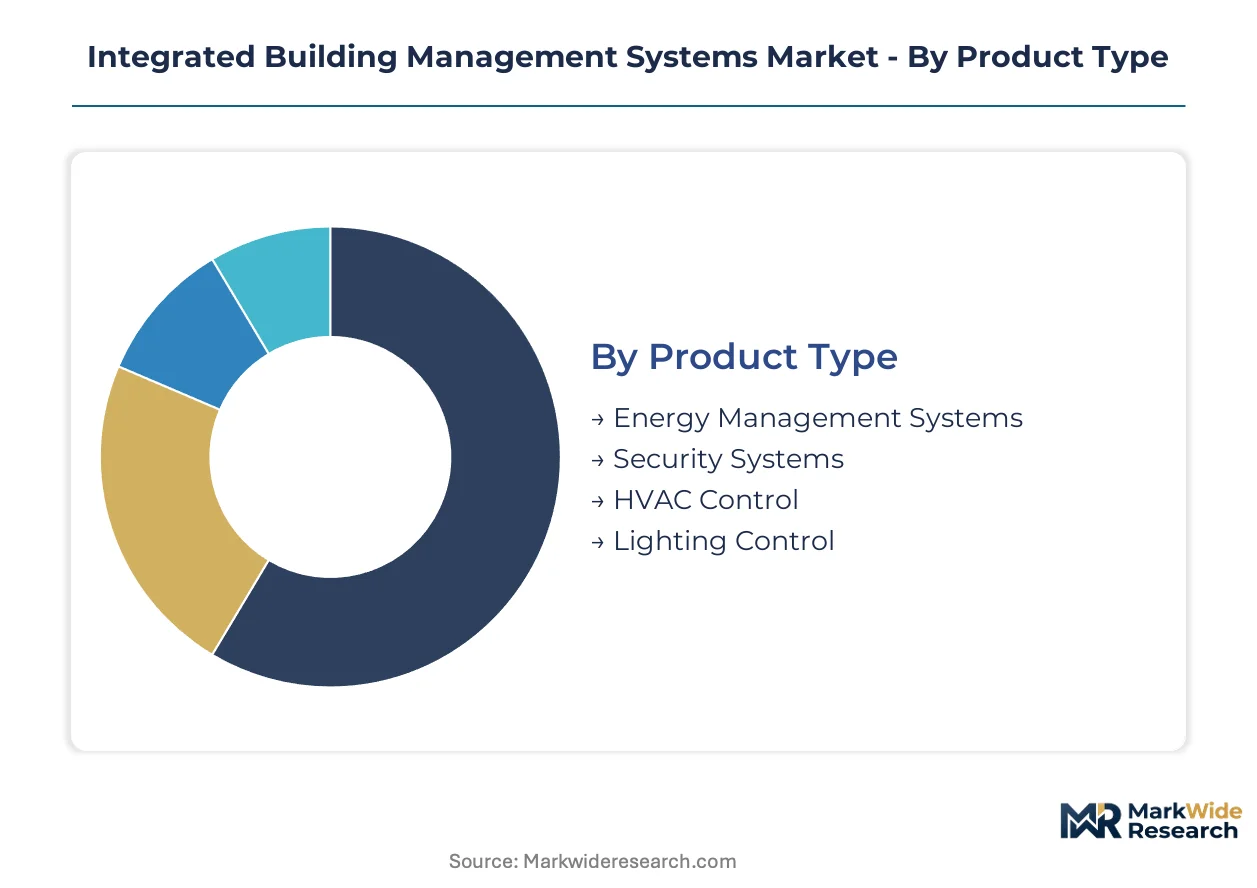
Segmentation in building management systems reveals how procurement priorities diverge across infrastructure vintages. Facility operators select technology bundles based on retrofit complexity, regulatory deadlines, and operational criticality rather than uniform specifications.
Product Type:
Replacement cycles vary sharply across building subsystems, with thermal infrastructure demanding the most frequent overhaul due to refrigerant phase-outs and efficiency mandates.
- HVAC Control:Thermal regulation platforms coordinate chillers, boilers, and air handling units through programmable logic controllers. Hospital networks in Germany and France prioritize these upgrades first, as the EU F-Gas Regulation mandates leak detection integration for systems above specific refrigerant charge thresholds.
- Energy Management Systems:These platforms aggregate consumption data across electrical, thermal, and water systems to identify load anomalies and peak demand reduction opportunities. Commercial real estate portfolios in Singapore and Germany deploy these for continuous commissioning, driven by corporate net-zero disclosure requirements under CSRD.
- Security Systems:Access control and surveillance integration with BMS dashboards enables unified emergency response protocols.
- Lighting Control:Daylight harvesting and occupancy-based dimming reduce electrical loads in commercial stock.
Volume placements concentrate in HVAC Control; the faster expansion belongs to Energy Management Systems.
Technology:
Deployment architecture selection hinges on existing building wiring conditions and IT governance policies rather than performance specifications alone.
- Cloud-Based Solutions:Subscription middleware eliminates on-premise server maintenance and enables remote diagnostics across distributed portfolios. Facility operators in the US healthcare sector favor these models to convert capital expenditure into operational budgets aligned with annual reimbursement cycles.
- Wireless Technologies:BACnet/IP and Zigbee protocols eliminate rewiring costs in occupied buildings. Aging educational campuses in Italy and Spain adopt these for rapid sensor deployment without disrupting semester operations.
- IoT Integration:Sensor networks enable predictive maintenance through vibration, temperature, and current signature analysis.
- Wired Technologies:Ethernet and RS-485 connections persist in new construction where infrastructure can be designed concurrently.
Procurement volume tilts toward Wireless Technologies for retrofit applications; Cloud-Based Solutions are climbing the fastest as building owners prioritize operational expenditure models.
End User:
Facility complexity and regulatory exposure determine integration depth, with 24/7 operations demanding the most sophisticated fault tolerance.
- Commercial Buildings:Office towers and retail complexes require tenant submetering and after-hours scheduling flexibility. Germany's building stock digitization programs accelerate municipal procurement for these assets, with energy performance certificates driving automation investment.
- Healthcare Facilities:Operating rooms and pharmaceutical storage mandate precise environmental control with redundant monitoring. US hospital networks consolidate vendor relationships around full-lifecycle service agreements to reduce administrative overhead across distributed campuses.
- Educational Institutions:K-12 and university buildings prioritize occupancy-based controls for intermittent use patterns.
- Industrial Facilities:Manufacturing plants integrate BMS with process control systems for coordinated energy management.
Commercial Buildings absorb the highest deployment volumes; Healthcare Facilities show the steepest expansion trajectory as aging infrastructure meets infection control modernization.
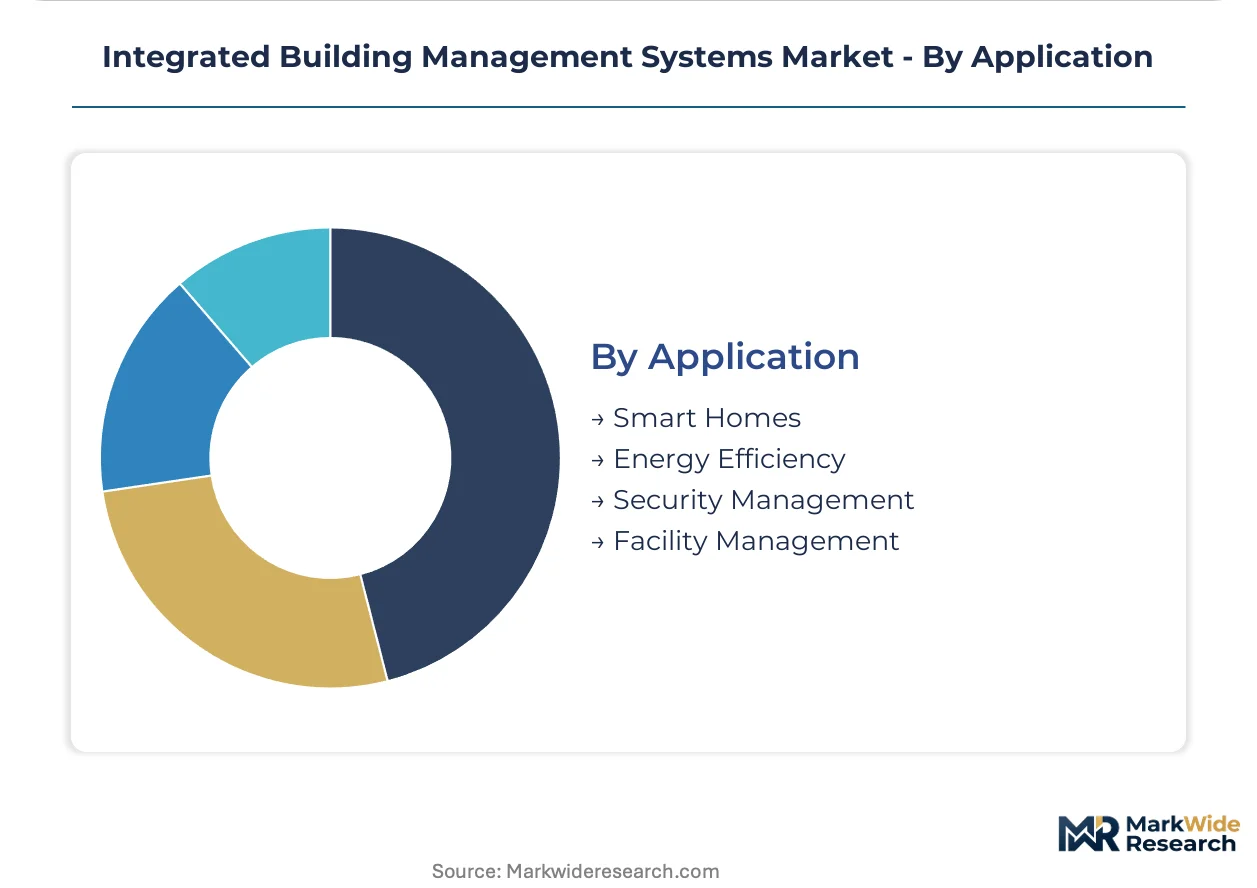
Application:
Use-case prioritization reflects whether the primary objective is operational cost reduction, regulatory compliance, or risk mitigation.
- Energy Efficiency:Load balancing, demand response, and setpoint optimization deliver quantifiable utility cost reductions. Singapore's Green Mark certification and Germany's Energy Performance of Buildings Directive both mandate systematic automation for commercial stock above specified floor areas.
- Facility Management:Unified dashboards consolidate work order tracking, asset lifecycle data, and space utilization analytics. US commercial real estate investment trusts deploy these for portfolio-wide standardization across properties acquired through rolling consolidation.
- Security Management:Integrated access, video, and intrusion detection enable coordinated emergency response.
- Smart Homes:Residential automation concentrates on convenience features with limited BMS-grade integration.
Energy Efficiency captures the dominant share of current investment; Facility Management is gaining share fastest as owners seek operational standardization across dispersed assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Singapore and Dubai concentrate procurement headquarters for multinational facility operators seeking unified control platforms across distributed portfolios.
Germany
Municipal building stock digitization programs accelerate automation procurement cycles across commercial real estate portfolios. The EU Energy Performance of Buildings Directive mandates real-time monitoring infrastructure for commercial stock above specified floor-area thresholds. Frankfurt and Munich clusters dominate deployment volumes as property owners retrofit aging HVAC systems to meet F-Gas Regulation leak detection requirements.
United States
Hospital networks consolidate vendor relationships around full-lifecycle service agreements spanning decades of equipment management. The Department of Energy enforces ANSI/ASHRAE/IES Standard 90.1 efficiency benchmarks that compel BMS-enabled equipment specification for new construction code compliance. Texas and California healthcare systems lead retrofit volumes as aging medical campuses seek unified control platforms.
China
New municipal and transportation facilities require integrated monitoring infrastructure under GB standards for intelligent building design administered by MIIT. Dual carbon goals accelerate procurement of energy management platforms across commercial and government building stock. Yangtze River Delta and Pearl River Delta clusters concentrate deployment as megacity governments mandate smart infrastructure in new construction.
India
Smart cities mission programs create procurement pipelines for integrated monitoring platforms across transportation hubs and government facilities. Bureau of Indian Standards certification requirements shape equipment specifications for public infrastructure projects. Maharashtra and Karnataka urban clusters drive adoption as municipal corporations digitize building operations in Mumbai and Bengaluru.
Singapore
Green Mark certification mandates systematic automation for commercial stock above specified floor areas, directly stimulating BMS procurement. The Building and Construction Authority enforces energy performance benchmarks that require centralized monitoring and control systems. The city-state's free trade zone status attracts regional headquarters of multinational facility operators seeking portfolio-wide standardization.
Integrated Building Management Systems Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with full-stack platform providers commanding premium positioning in healthcare and critical infrastructure verticals while component specialists capture volume in retrofit wireless sensor deployments. The vendor base organizes into three strategic archetypes: European industrial conglomerates with deep vertical integration across building subsystems, North American controls specialists anchoring long-term service relationships, and Asian electronics fabricators supplying cost-optimized sensor hardware. Consolidation pressure intensifies through strategic partnerships between software platform developers and hardware OEMs, alongside geographic expansion into municipal digitization programs across India and Southeast Asia.
Within the industrial conglomerate tier, Siemens and ABB exemplify full-stack platform providers leveraging deep integration across European hospital networks and commercial real estate portfolios. Schneider Electric occupies a comparable position with particular concentration in energy management and power distribution integration. Among North American specialists, Johnson Controls anchors decades-long service contracts in healthcare infrastructure, while Honeywell represents wireless protocol leadership positioning for rapid retrofit installations. Bosch and Legrand sit within the European component specialist archetype, supplying interoperable hardware for system integrators assembling multi-vendor deployments.
| Leading Market Players |
|---|
| Siemens |
| Bosch |
| Johnson Controls |
| Legrand |
| ABB |
| Schneider Electric |
| Carrier |
| Lutron Electronics |
| Honeywell |
| Others |
Value Chain & Pricing Dynamics
Copper futures volatility on the London Metal Exchange cascades through sensor and controller manufacturing into three distinct pricing tiers for system integrators and end-users.
Pricing Analysis
Lead-time compression commands premium positioning: 48-hour fulfillment windows for BACnet controllers and wireless sensor arrays attract 15-25% markups over standard 4-week delivery schedules. Subscription-based SaaS tiers for cloud middleware stratify across enterprise, professional, and essential levels, with price differentiation anchored in API call volumes and predictive analytics module inclusion. Cost compression in the economy tier intensifies as Asian electronics fabricators expand production of Zigbee and LoRaWAN endpoints. Healthcare networks demonstrate lowest price sensitivity due to regulatory compliance imperatives, while municipal procurement in India's smart cities mission exhibits acute budget constraint responsiveness.
Supply Chain Analysis
Reverse-logistics networks for controller refurbishment and sensor recalibration are expanding as sustainability mandates extend equipment lifecycles across European commercial portfolios. Manufacturing concentration rests on China for IoT sensor assembly, Taiwan for microcontroller fabrication, and Germany for precision HVAC actuators. Semiconductor wafer supply, copper wiring, and lithium-ion backup batteries constitute critical input dependencies. Single-source vulnerability in 28nm chip fabrication creates exposure to geopolitical disruption. Distribution runs through authorized system integrator channels in developed markets and direct OEM relationships in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native middleware architectures are displacing legacy on-premise server installations, compressing deployment timelines and shifting vendor compensation models from capital equipment to recurring subscription revenue.
For Market Incumbents: Acquire edge-AI software development capabilities to counter emerging platform-native entrants threatening service contract renewals. Deepen backward integration into wireless protocol chipsets to secure supply continuity against East Asian foundry concentration. Prioritize IEC 62443 cybersecurity certification investment to extend product development lead times into defensive moats. For New Entrants and Emerging Players: Aging educational campuses in Southern Europe represent underserved buyer archetypes seeking rapid wireless retrofit without semester disruption. Municipal transportation hubs under India's smart cities mission offer lowest competitive density for integrated monitoring platforms. Pursue outcome-based energy service contracting to bypass incumbent equipment procurement relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap building automation specialists with established BACnet interoperability libraries in Germany and Singapore. Long-term viability hinges on software recurring revenue ratios exceeding 40% of total bookings. Monitor F-Gas Regulation enforcement intensity as inflection indicator for refrigerant monitoring hardware demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Platform Integration | On-device analytics reduce cloud transmission costs for Siemens and Honeywell deployments in hospital networks. |
| Wireless Protocol Certification | BACnet/IP compliance enables rapid retrofit penetration in Italy's aging educational infrastructure. |
| Full-Lifecycle Service Agreements | Johnson Controls anchors decades-long relationships across US healthcare campus consolidation waves. |
| Cybersecurity Compliance Investment | IEC 62443 certification extends product development cycles for industrial control system vendors. |
| Smart City Municipal Partnership | Schneider Electric leverages energy management expertise in Singapore Green Mark certification pipelines. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with facility managers, building automation system integrators, HVAC controls engineers, and cybersecurity compliance officers combined with secondary validation from EU Energy Performance of Buildings Directive implementation reports, US Department of Energy efficiency standard databases, and MIIT GB standards documentation. Bottom-up sensor deployment estimates and top-down construction spending projections were triangulated to establish market sizing.
Granularity-level modeling operated at product-type, technology-deployment, end-user-vertical, and application-use-case dimensions across the analysis window. CAGRs were derived from regression analysis against construction permitting data and regulatory compliance deadline clustering. Forecast inputs included hospital infrastructure modernization pipeline tracking, smart city procurement announcement monitoring, and refrigerant phase-out schedule acceleration scenarios.
Revisions become necessary when semiconductor fabrication capacity constraints intensify, EU building efficiency mandates tighten beyond current directive specifications, or wireless protocol standardization fragments further. Forecasts reflect assumptions about regulatory enforcement consistency and supply chain normalization trajectories. Practitioners should monitor East Asian foundry utilization rates and EU member state transposition timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Signage Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Europe Commercial Refrigeration Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Infrastructure Monitoring Market
Building Automation Systems
Rotary Sprinkler System Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Asia-Pacific Building Automation System Market