
 Vinyl Strip Door and Curtains Market | 2026-2036
Vinyl Strip Door and Curtains Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Strip Door and Curtains Market Insights
Polyvinyl chloride is decoupling from legacy phthalate plasticizer formulations as bio-based and DINCH alternatives reshape product economics. AmCraft Manufacturing leverages captive extrusion capabilities to control compound consistency across its strip curtain lines. Berner International anchors its position through engineered mounting hardware that reduces field installation labor. ThermaFlex sustains margin pools by specializing in low-temperature flex formulations for freezer-grade applications.
Vinyl strip doors and curtains consist of extruded polyvinyl chloride strips, typically 0.08 to 0.12 inches thick, hung in overlapping configurations to create flexible thermal and particulate barriers for industrial openings. The extrusion process calibrates strip width, overlap geometry, and durometer to match door height, traffic frequency, and temperature differential requirements. Strip curtains lead product type volume due to retrofit compatibility with existing dock and partition openings, while welded curtains capture premium positioning through seamless construction that eliminates particulate harboring points in pharmaceutical manufacturing. Food Grade PVC commands the material grade margin pool as FDA and EFSA compliance requirements harden across cold chain and processing environments.
OSHA workplace safety standards, FDA food contact regulations, and EU REACH chemical restrictions collectively shape product specifications and market access thresholds for vinyl strip barrier systems. The EPA's evolving stance on PVC additive chemistry and the EU Green Deal's circular economy mandates are pressuring compounders to reformulate without legacy stabilizers and plasticizers. Stakeholders must monitor regulatory divergence between North American and European chemical compliance frameworks when configuring product portfolios for cross-border industrial customers.
Market Dynamics
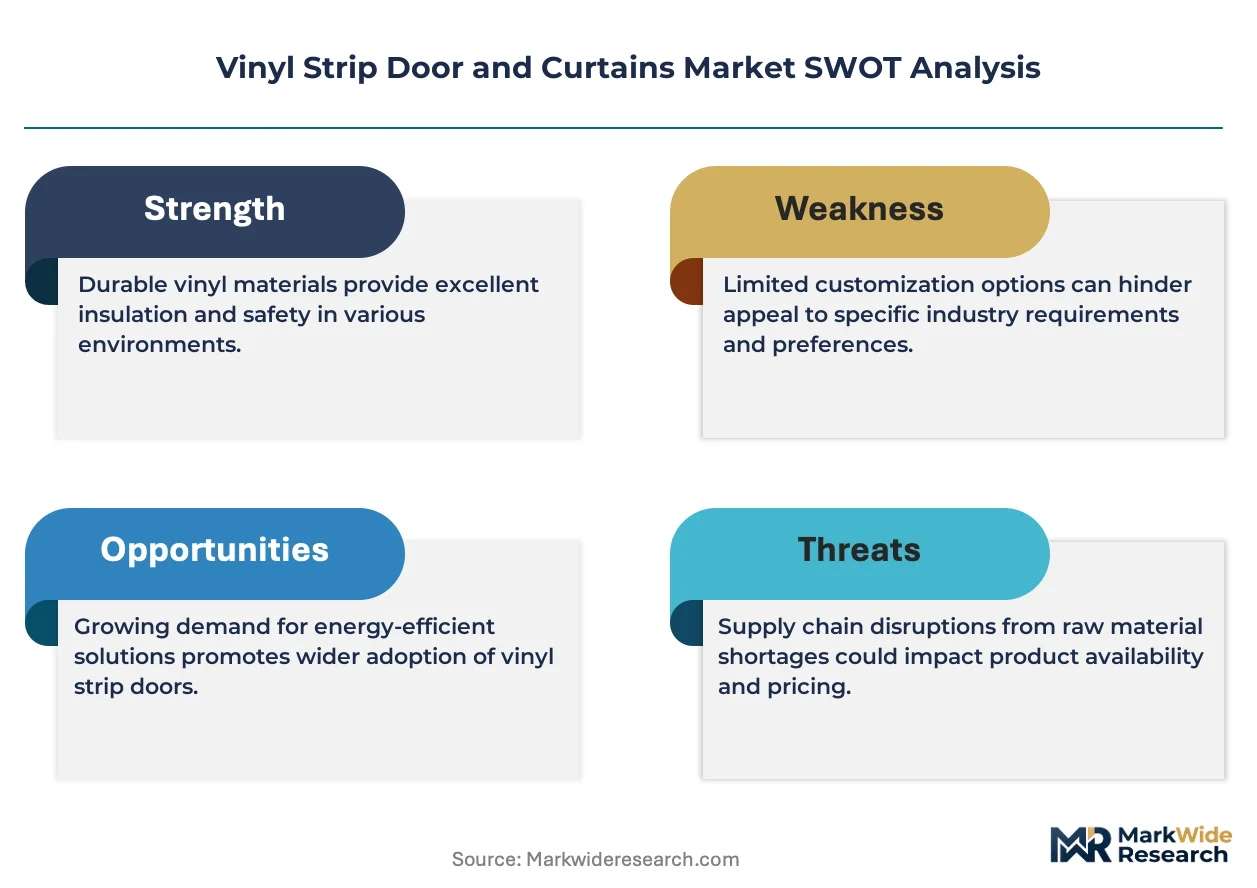
Food safety mandates and energy efficiency codes are compressing specification cycles for vinyl strip barriers, forcing compounders to validate new plasticizer chemistries against divergent FDA and EFSA frameworks before products reach cold storage and pharmaceutical cleanroom installations.
Growth Catalysts
- REACH chemical restrictions:Legacy phthalate displacement is accelerating demand for DINCH and bio-based plasticizer formulations in European pharmaceutical manufacturing environments.
- Cold storage infrastructure:FDA food safety mandate enforcement across US distribution networks is mandating strip curtain retrofits at existing dock and processing openings.
- Extrusion process refinements:Advanced die calibration technology enables tighter durometer control for freezer-grade applications below negative twenty degrees Celsius.
Market Restraints
- Petrochemical feedstock volatility:PVC resin pricing fluctuates with ethylene and chlorine input costs, compressing compounder margins during energy price spikes.
- Regulatory fragmentation:Divergent EPA and ECHA stances on organotin stabilizers force dual formulation tracks for cross-border industrial customers.
- Polyurethane substitute encroachment:Thermoplastic polyurethane roll-up doors capture high-traffic openings with faster cycle speeds and integrated automation.
Strategic Opportunities
- Indian cold chain buildout:FSSAI enforcement of food safety standards at warehouse and retail distribution points creates first-mover positioning for compliant strip curtain suppliers.
- Welded curtain seamless construction:Elimination of particulate harboring points addresses pharmaceutical cleanroom contamination control requirements.
- EU Green Deal circular economy mandates:Mechanical recycling infrastructure for post-industrial PVC scrap creates closed-loop service offerings for large-format logistics operators.
Industry Challenges
- Compound formulation chemistry expertise:Shortage of polymer scientists capable of balancing low-temperature flexibility against plasticizer migration limits in freezer applications.
- Multi-jurisdiction certification timelines:Parallel FDA food contact and EFSA compliance testing extends product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Strip Door and Curtains Market |
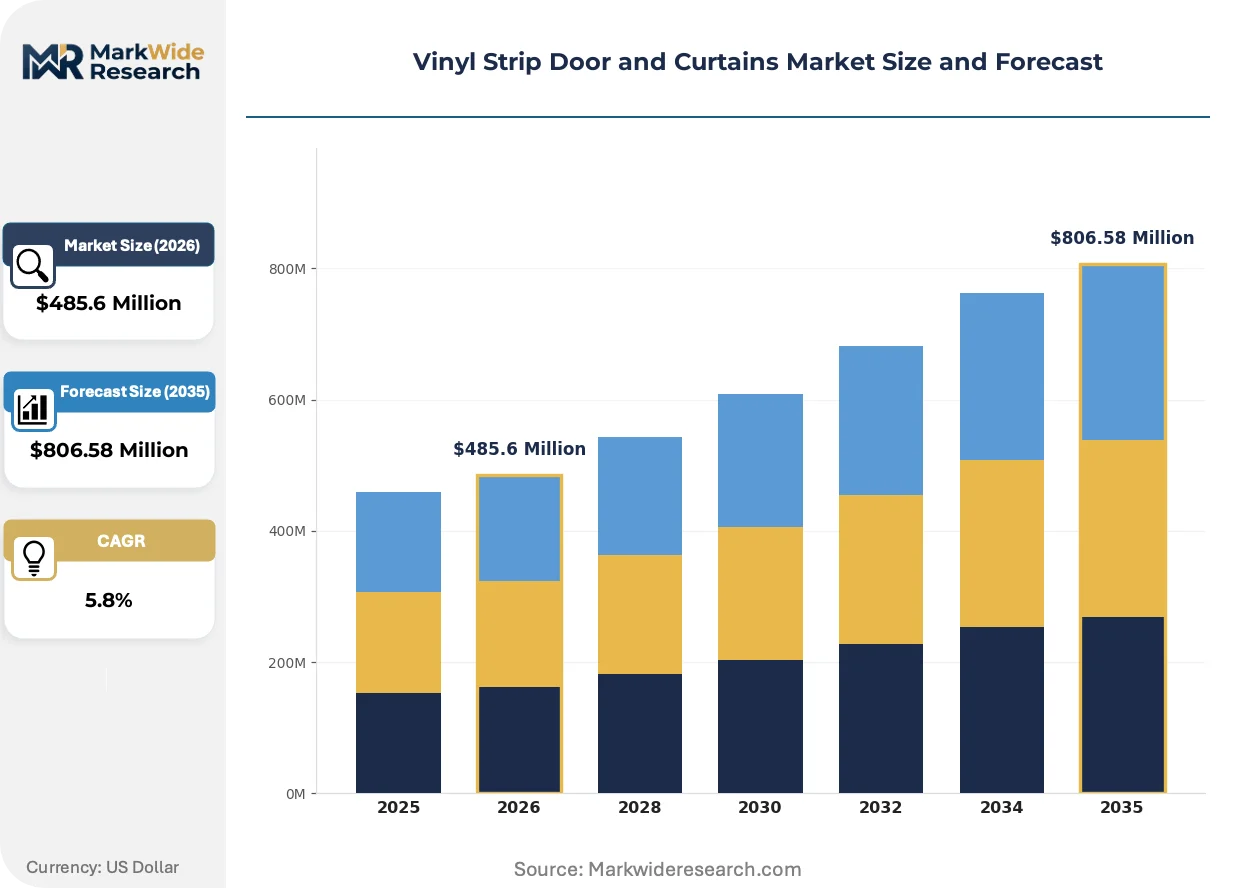
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $806.58 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strip Curtains, Strip Doors, Welded Curtains, Reinforced Curtains, Embossed Curtains Material Grade: Standard PVC, Food Grade PVC, Anti-Static PVC, Fire Retardant PVC, UV Resistant PVC End User Industry: Cold Storage Facilities, Food Processing Plants, Pharmaceutical Manufacturing, Automotive Assembly Lines, Warehousing Facilities Installation Type: Wall Mounted, Ceiling Mounted, Free Standing, Portable Mounting |
| Companies Covered | AmCraft Manufacturing, Berner International, ThermaFlex, Strip-Curtains.com, Industrial Strip Curtains, Mattr Corp, Rayflex, Heroen Plastics, Fortune Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Strip Door and Curtains Market Trends and Innovations
Material science advances and regulatory chemistry constraints are rewriting how vinyl strip barriers are formulated, specified, and deployed across temperature-controlled industrial environments.
DINCH plasticizer chemistry is rewriting the competitive map for food-contact applications. Pharmaceutical manufacturers and cold storage operators in Germany and the United States are specifying DINCH-formulated strips ahead of formal regulatory deadlines. This shift compresses demand for legacy phthalate compounds while rewarding early compounders with validated alternative chemistries.
EU REACH restrictions on organotin stabilizers are forcing reformulation of outdoor and high-UV exposure strip grades. Compounders serving cross-border industrial customers must maintain parallel inventory positions or absorb retooling costs for unified product lines. German logistics operators are accelerating specification reviews to lock in compliant formulations before sunset dates.
Buyer consolidation among third-party cold storage operators is compressing procurement cycles and unbundling installation from hardware supply. Large warehouse developers in the United States now specify strip curtains through national framework agreements rather than regional distributor relationships. This shift favors suppliers with captive extrusion and direct installation service capabilities.
Vinyl Strip Door and Curtains Market Segmentation
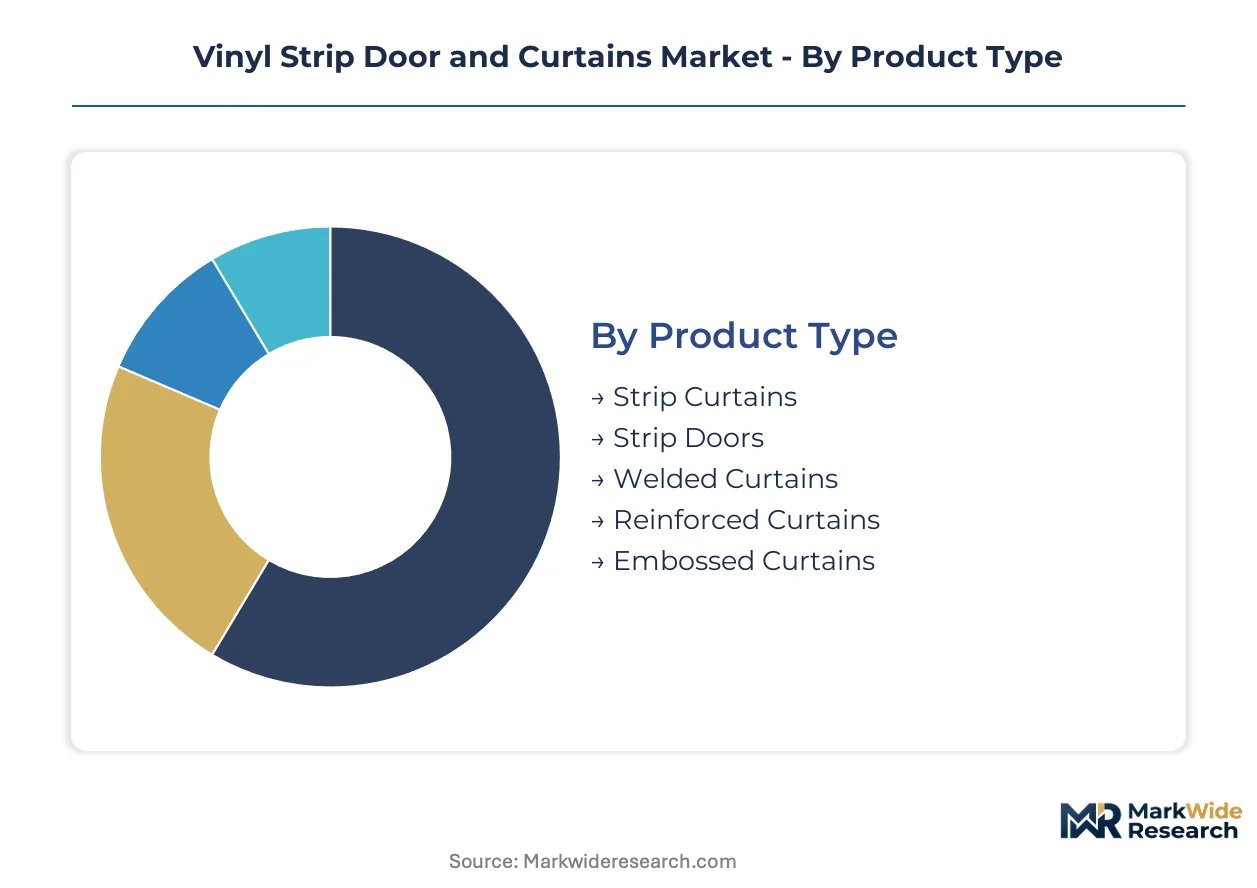
Vinyl strip barrier systems fragment across four structural dimensions that determine specification complexity and procurement economics. Product geometry and material chemistry dominate capital allocation decisions, while end-use application and mounting configuration shape installation labor and lifecycle performance.
Product Type:
Capital intensity varies sharply across extrusion tooling, welding equipment, and reinforcement lamination lines required for each product category.
- Strip Curtains:Overlapping extruded PVC strips hung from mounting hardware create flexible thermal barriers. Cold storage facilities in the United States specify these for dock door retrofits where FDA food safety mandates demand rapid deployment without structural modification.
- Welded Curtains:Seamless RF-welded construction eliminates particulate harboring points critical for pharmaceutical cleanroom compliance. German manufacturers specify these ahead of ECHA REACH enforcement timelines for organotin stabilizer restrictions.
- Strip Doors:Pre-hung framed assemblies reduce field installation labor for high-traffic warehouse openings.
- Reinforced Curtains:Polyester mesh or fiberglass scrim embedded between PVC layers resists forklift impact in automotive assembly environments.
- Embossed Curtains:Surface texturing reduces light transmission and improves visual recognition in food processing corridors.
Strip curtains absorb the bulk of installed capacity; welded curtains are expanding most quickly.
Material Grade:
Compound formulation costs stratify across plasticizer chemistry, stabilizer packages, and certification testing burdens.
- Food Grade PVC:DINCH and bio-based plasticizer formulations replace legacy phthalates for FDA and EFSA food contact compliance. Cold chain operators in Germany and the United States specify these ahead of regulatory deadlines.
- Standard PVC:General-purpose di-2-ethylhexyl phthalate formulations serve non-contact industrial partitioning where regulatory pressure remains muted.
- Anti-Static PVC:Conductive additive packages dissipate static charge for electronics manufacturing cleanrooms.
- Fire Retardant PVC:Halogenated or phosphorus-based flame suppressants meet building code requirements for warehouse egress corridors.
- UV Resistant PVC:Hindered amine light stabilizers extend outdoor service life for loading dock exposure.
Food Grade PVC commands the steepest expansion trajectory as compliance deadlines harden across jurisdictions.
End User Industry:
Application-specific performance requirements drive specification divergence in temperature rating, chemical resistance, and contamination control.
- Cold Storage Facilities:Negative twenty degrees Celsius flex requirements demand specialized low-temperature plasticizer packages. US distribution networks retrofit strip curtains to meet updated FDA food safety mandates.
- Pharmaceutical Manufacturing:Particulate control and cleanroom classification requirements specify welded seamless construction. EMA and national regulators enforce stricter contamination thresholds.
- Food Processing Plants:USDA and FDA sanitation protocols mandate smooth surfaces resistant to chemical washdown cycles.
- Automotive Assembly Lines:Weld spark and abrasion resistance prioritize reinforced curtain constructions.
- Warehousing Facilities:High-cycle traffic durability drives specification toward thicker gauge strips with rapid replacement protocols.
Cold storage facilities absorb the bulk of installed capacity; pharmaceutical manufacturing is expanding most quickly.
Installation Type:
Mounting configuration determines structural load requirements, labor content, and relocation flexibility across facility types.
- Wall Mounted:Header rail attachment to existing masonry or steel framing dominates permanent installations. US warehouse developers specify these through national framework agreements that unbundle hardware from installation services.
- Ceiling Mounted:Suspended chain or rod systems accommodate wide openings without lateral wall support. German logistics operators favor these for flexible bay reconfiguration.
- Free Standing:Self-supporting frame assemblies serve leased facilities where structural modification is prohibited.
- Portable Mounting:Castor-based or modular frame systems enable rapid redeployment for seasonal demand surges.
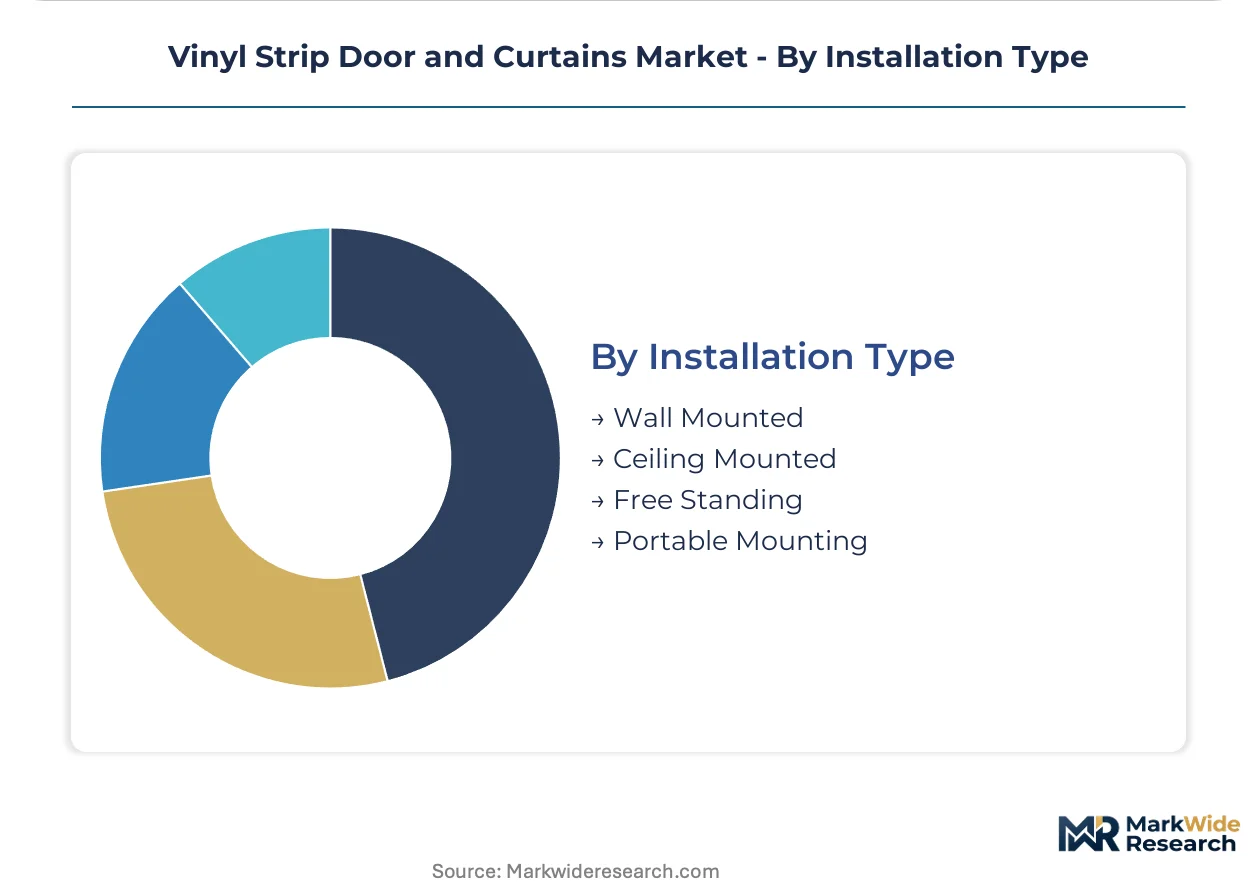
Wall mounted systems absorb the bulk of installed capacity; portable mounting configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for vinyl strip door and curtain systems concentrates in industrial corridors where cold chain infrastructure, pharmaceutical manufacturing, and logistics modernization intersect with tightening energy codes and food safety enforcement.
United States
FDA food safety mandate enforcement across distribution networks drives retrofit installations at dock and processing openings. OSHA workplace safety standards and EPA evolving guidance on PVC additive chemistry shape product specifications. Chicago and Dallas-Fort Worth logistics clusters see accelerated specification cycles as third-party cold storage operators consolidate procurement through national framework agreements.
Germany
EMA and EFSA compliance requirements for pharmaceutical cleanrooms specify seamless welded curtain constructions. EU REACH restrictions on organotin stabilizers and DINCH plasticizer adoption timelines force compound reformulation ahead of sunset dates. The Rhine-Ruhr industrial belt anchors demand as logistics operators accelerate specification reviews to lock in compliant formulations.
China
SAMR enforcement of GB standards for industrial door systems and cold chain infrastructure expansion create specification pressure. NMPA pharmaceutical manufacturing regulations and MIIT industrial efficiency mandates reshape product requirements. Yangtze River Delta manufacturing clusters specify strip curtains for high-traffic warehouse openings as e-commerce logistics capacity expands.
India
FSSAI enforcement of food safety standards at warehouse and retail distribution points generates first-mover positioning opportunities for compliant suppliers. CDSCO pharmaceutical manufacturing regulations and BIS industrial standards adoption create multi-jurisdiction certification requirements. Maharashtra and Gujarat industrial corridors see cold chain buildout as organized retail penetration deepens.
United Kingdom
EMA-aligned pharmaceutical contamination control standards and building code energy efficiency requirements drive specification upgrades. Health and Safety Executive workplace safety enforcement maintains demand for impact-resistant strip barriers. Midlands logistics hubs and Greater London distribution centers retrofit existing dock openings with compliant strip curtain systems.
Vinyl Strip Door and Curtains Market Competitive Landscape
Capacity expansion dominates the current landscape as compounders invest in captive extrusion lines to control plasticizer formulation consistency and reduce feedstock cost exposure. The vendor base spans integrated material producers, specialized fabricators, and installation service providers. Three archetypes define competitive positioning: compounders with in-house resin processing, hardware-integrated system suppliers, and regional installation specialists. M&A activity concentrates on captive supply chain integration and geographic service footprint extension.
Among North American fabricators, AmCraft Manufacturing and Berner International occupy positions within the integrated production tier, while ThermaFlex exemplifies specialization in low-temperature formulation chemistry. These three companies represent distinct strategic vectors: extrusion capability control, engineered mounting hardware differentiation, and application-specific material science expertise. Their collective positioning illustrates how competitive advantage in this market derives from upstream process control rather than downstream distribution scale.
| Leading Market Players |
|---|
| AmCraft Manufacturing |
| Berner International |
| ThermaFlex |
| Strip-Curtains.com |
| Industrial Strip Curtains |
| Mattr Corp |
| Rayflex |
| Heroen Plastics |
| Fortune Industrial |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap compounders with multi-decade operating histories anchor supply-side discipline in vinyl strip barrier manufacturing, translating captive extrusion capabilities into pricing power that resists commoditization despite feedstock volatility. Their refusal to absorb ethylene and chlorine cost swings into contract pricing sustains margin pools while forcing buyer consolidation toward national framework agreements.
Pricing Analysis
Volume concentrates in standard-grade strip curtains while margin pools accrue to food-grade DINCH formulations and welded seamless constructions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified food-contact grades from general-purpose phthalate formulations and uncertified industrial partitioning. Pricing pressure stems from petrochemical feedstock volatility compressing compounder margins during energy price spikes. Third-party cold storage operators exhibit highest price sensitivity through unbundled procurement, while pharmaceutical cleanroom buyers prioritize contamination control over unit economics.
Supply Chain Analysis
Post-industrial PVC scrap recovery and mechanical recycling infrastructure create reverse-logistics value streams for large-format logistics operators seeking closed-loop service offerings. Manufacturing concentration centers on the United States, Germany, and China where cold chain infrastructure expansion and regulatory enforcement drive specification demand. Raw material dependencies include PVC resin, DINCH plasticizers, and organotin stabilizer alternatives. Single-source vulnerability in specialized low-temperature flex formulations creates supply risk for freezer-grade applications. Distribution runs through national framework agreements with direct installation service capabilities displacing regional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU REACH chemical restrictions and FDA food contact mandates erect formulation barriers that reward early DINCH and bio-based plasticizer adopters with durable competitive moats.
For Market Incumbents: Extend captive extrusion capabilities into welded curtain production to capture pharmaceutical cleanroom premium positioning ahead of ECHA organotin stabilizer sunset dates. Deepen backward integration into bio-based plasticizer sourcing to insulate margin pools from petrochemical volatility. Consolidate installation service footprints through regional specialist acquisitions as buyer procurement shifts toward national framework agreements. For New Entrants and Emerging Players: Mid-sized Indian cold storage operators underserved by multinational suppliers present first-mover positioning opportunities ahead of FSSAI enforcement acceleration. Target FSSAI-compliant food-grade formulations for Maharashtra and Gujarat warehouse buildouts. Pursue joint-venture structures with established compounders to bypass eight-to-fourteen-month multi-jurisdiction certification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor compounders with validated DINCH formulations and captive extrusion infrastructure in Germany and the United States during feedstock volatility windows. Long-term viability hinges on mechanical recycling service integration and circular economy mandate compliance. Monitor EPA guidance evolution on PVC additive chemistry as inflection indicator for reformulation capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Plasticizers | DINCH and bio-based formulation control insulates margins from ethylene cost volatility and REACH compliance deadlines. |
| Welded Curtain Capacity Expansion | Seamless RF-welded construction addresses pharmaceutical cleanroom particulate control requirements ahead of ECHA enforcement. |
| Mechanical Recycling Infrastructure Buildout | Closed-loop post-industrial PVC scrap recovery aligns with EU Green Deal circular economy mandates for logistics operators. |
| Direct Installation Service Acquisition | National framework agreement positioning captures procurement consolidation among third-party cold storage operators. |
| Indian Cold Chain Joint Venture | FSSAI-compliant production localization captures warehouse and retail distribution point buildout ahead of enforcement acceleration. |
Research Methodology
Trade association filings, customs and import-export databases, and regulatory submission records formed the secondary backbone, supplemented by SEC 10-K disclosures and energy agency feedstock pricing data. Primary fieldwork encompassed interviews with plant managers at extrusion facilities, procurement leads at third-party cold storage operators, distribution channel partners, and technical R&D directors at compounder operations. Bottom-up installed base estimates were cross-validated against top-down demand projections derived from cold chain infrastructure spending and pharmaceutical manufacturing capacity data.
Historical trendline analysis of cold storage construction permits, pharmaceutical cleanroom certifications, and industrial door system specifications established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product geometry, material chemistry grade, end-use application, and mounting configuration dimensions. CAGRs were derived from elasticity-adjusted demand curves reflecting regulatory enforcement timelines and energy code adoption schedules. Forecast inputs included ethylene and chlorine price volatility scenarios and DINCH plasticizer capacity expansion announcements.
Revisions become necessary when EPA guidance on PVC additive chemistry diverges from ECHA REACH frameworks, or when FSSAI enforcement timelines accelerate beyond modeled assumptions. Forecasts reflect documented assumptions regarding regulatory harmonization and feedstock price stabilization. Practitioners should monitor EPA additive chemistry bulletins and Indian cold chain subsidy allocations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Infrastructure Monitoring Market
Building Automation Systems
AEC Market
Building Automation Systems
Europe Commercial Refrigeration Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Architecture Smart Glass Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Smart Window Film Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Underfloor Heating Actuator Market