
 Commercial Laundry Machines Market | 2026-2036
Commercial Laundry Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Laundry Machines Market Outlook
Direct-to-laundromat distribution is reshaping how equipment manufacturers reach independent operators. Alliance Laundry Systems leverages its North American dealer network to sustain broad geographic coverage. GIRBAU competes through specialized tunnel washer systems for large-scale industrial laundries. Miele & Cie anchors premium positioning in European hospitality markets through precision-engineered washer-extractors.
Commercial laundry machines encompass industrial-grade washing, drying, finishing, and material handling equipment engineered for continuous operation in high-throughput environments, with washer-extractors typically rated from 20 to 450 pounds capacity and constructed from 304-grade stainless steel drums to withstand alkaline detergents and thermal cycling. These systems serve on-premise laundry facilities, central commercial plants, and coin-operated self-service operations where equipment uptime directly affects revenue or patient care outcomes. Washing machines and dryers together constitute the core revenue base, though margin pools increasingly concentrate in smart technology integrations that enable remote diagnostics and utility optimization. Energy-efficient systems represent the fastest-expanding technology dimension as operators face escalating electricity and water costs across European and North American installations.
The US Department of Energy sets minimum efficiency standards for commercial clothes washers, while the EU Ecodesign Directive and F-Gas Regulation constrain refrigerant choices in heat-pump dryer configurations across European markets. ISO 10472 safety standards for industrial laundry machinery further shape product design and market access requirements for manufacturers exporting to multiple jurisdictions. Stakeholders must monitor how efficiency mandates and refrigerant phase-down schedules alter total cost-of-ownership calculations and equipment replacement timelines.
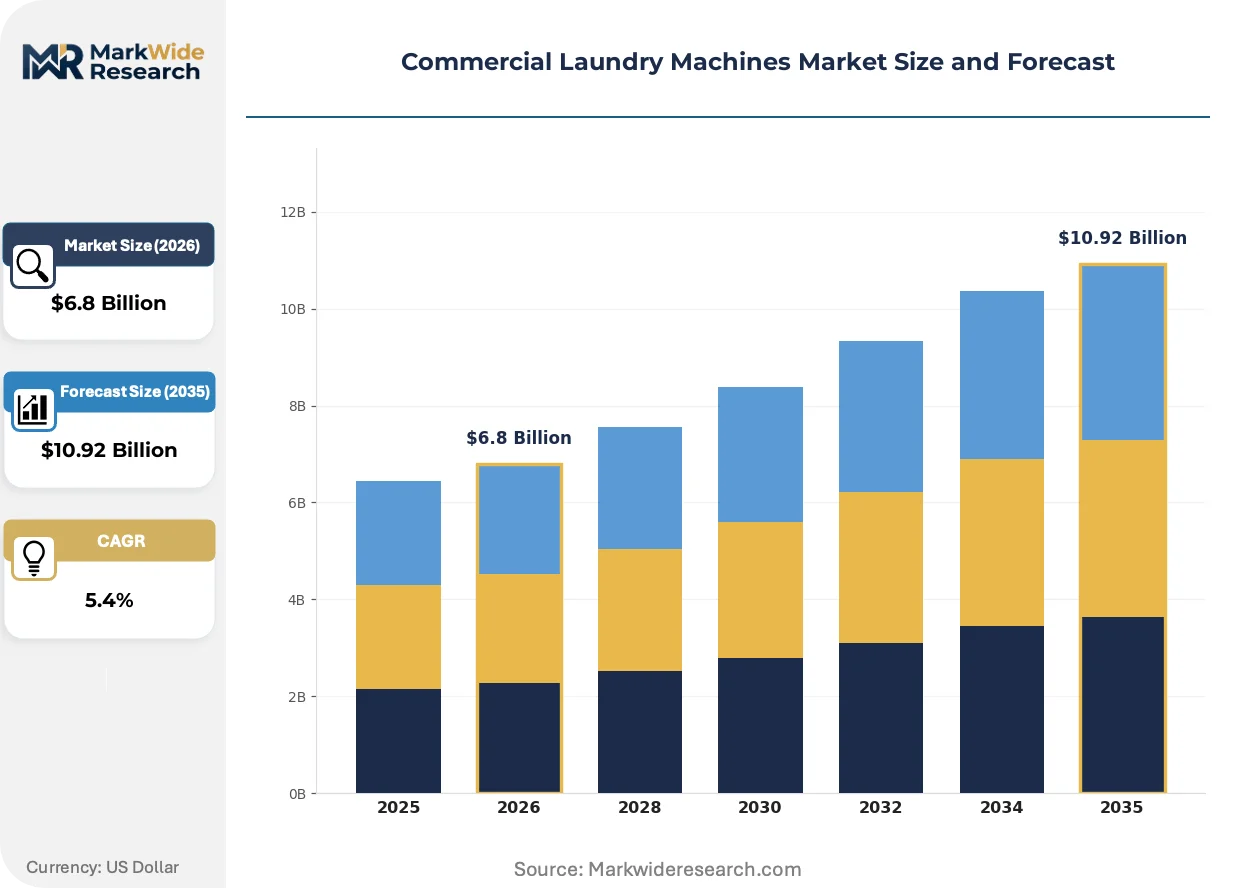
Market Dynamics
Hospital infection control mandates and the US Department of Energy's efficiency standards are compressing replacement cycles while forcing simultaneous capital outlays for compliance and capacity expansion.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency benchmarks for commercial washers accelerate equipment turnover in German industrial laundries serving hospitality chains.
- Heat-pump dryer adoption:Refrigerant constraints under the F-Gas Regulation drive retrofit demand across European central commercial plants seeking lower operational expenditure.
- On-premise healthcare laundry:US hospital systems prioritize captive processing to meet Joint Commission infection control protocols, bypassing third-party vendors.
Market Restraints
- Stainless steel input volatility:304-grade drum material costs fluctuate with nickel pricing, compressing manufacturer margins on washer-extractor production.
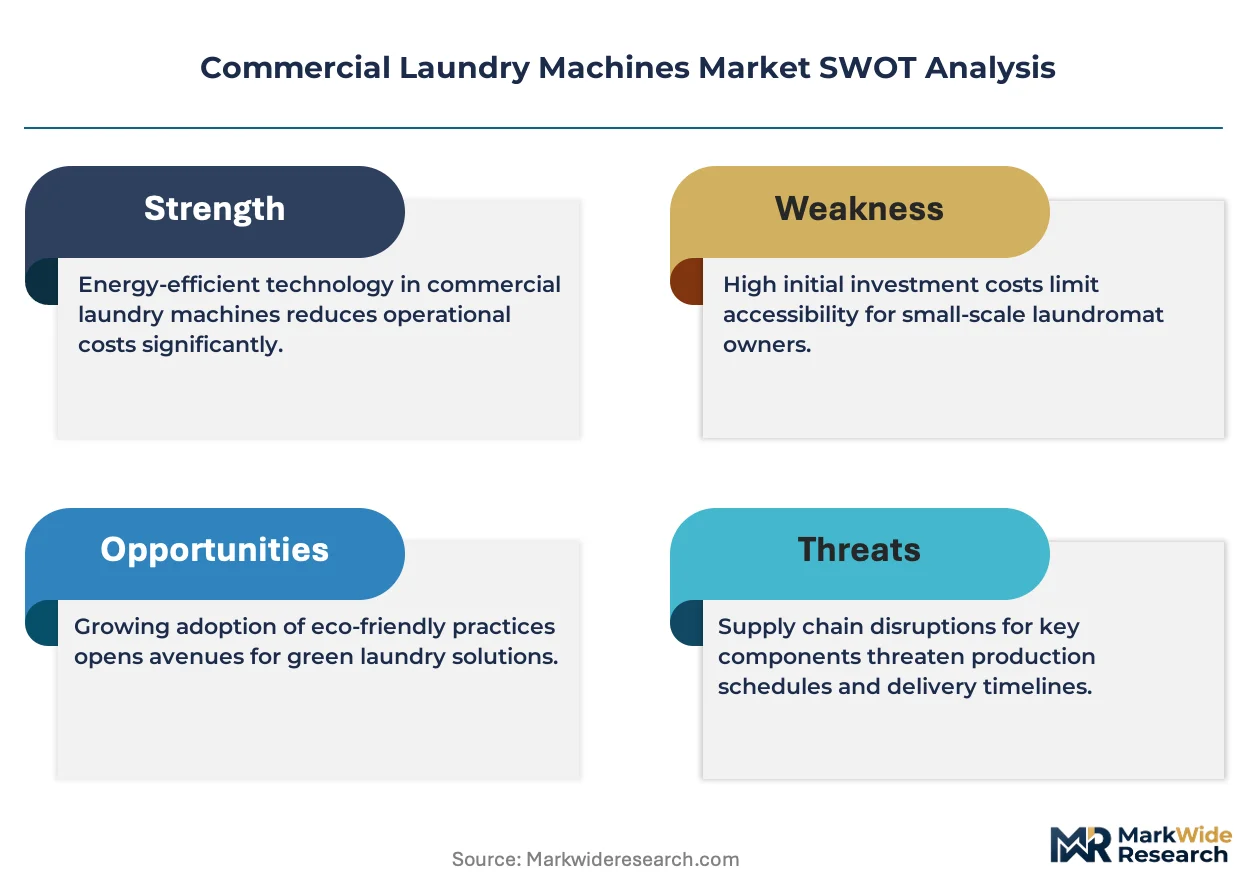
- Supply concentration in drive motors:High-torque industrial motor production clusters in Chinese manufacturing zones, creating single-source vulnerability for European OEMs.
- Technical ceiling on tunnel washer throughput:Continuous-batch systems face physical limits on water extraction efficiency that batch designs have already optimized.
Strategic Opportunities
- India hospitality expansion:Underpenetrated branded hotel chains in secondary cities require scalable on-premise systems as international operators enter the market.
- Remote diagnostics convergence:IoT sensor networks married to predictive maintenance algorithms create recurring revenue streams for equipment vendors.
- US Inflation Reduction Act efficiency credits:Tax incentives for energy-reducing capital equipment lower net ownership costs for laundromat operators replacing aging washers.
Industry Challenges
- Mechatronics technician scarcity:Servicing smart washer-extractors requires combined mechanical-electrical-software skills that vocational programs have not scaled to match equipment complexity.
- ISO 10472 certification timelines:Multi-jurisdiction safety testing delays product launches by 8-14 months for manufacturers targeting both North American and European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Laundry Machines Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Ironers, Folded Systems End User: Hotels, Hospitals, Laundromats, Restaurants Technology: Smart Technology, Steam Technology, Energy-Efficient Systems, Industrial Controllers Service Type: Lease, Buy, Maintenance, Repair |
| Companies Covered | JENSEN-GROUP, Pellerin Milnor Corporation, Alliance Laundry Systems, Herbert Kannegiesser, Dexter Laundry, Electrolux Professional, GIRBAU, American Dryer Corporation, Miele & Cie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Laundry Machines Market Strategic Shifts
Equipment intelligence and thermal efficiency are converging to redefine competitive advantage, with vendors racing to embed predictive capabilities while navigating refrigerant transitions and compressed buyer decision cycles.
Heat-pump drying technology is hybridizing vapor-compression and thermal storage architectures to achieve sub-100°F drying temperatures. Industrial laundries serving healthcare and hospitality sectors in Germany and the Netherlands are piloting these configurations to eliminate fabric damage while satisfying F-Gas refrigerant phase-down schedules. The technology is hybridizing traditional gas-fired and conventional electric resistance models into unified platforms that operators can reconfigure based on local utility tariffs.
The US Department of Energy's revised commercial clothes washer test procedure now incorporates cold-water cleaning performance metrics alongside traditional hot-cycle efficiency. This regulatory recalibration forces manufacturers to optimize enzyme-detergent compatibility and mechanical action profiles rather than relying solely on thermal energy reduction. On-premise laundry facilities in US hospitals and nursing homes face the steepest compliance curve, as their infection control protocols historically depended on high-temperature thermal disinfection cycles.
Equipment-as-a-service contracting is displacing traditional capital purchase arrangements among mid-scale independent laundromats. Under this model, distributors retain ownership and bundle maintenance, chemical supply, and utility optimization into per-pound processed fees. The shift is most visible in North American metropolitan markets where operators lack technical staff and face volatile utility rate structures that vendors can hedge through fleet-scale energy procurement.
Commercial Laundry Machines Market Segmentation
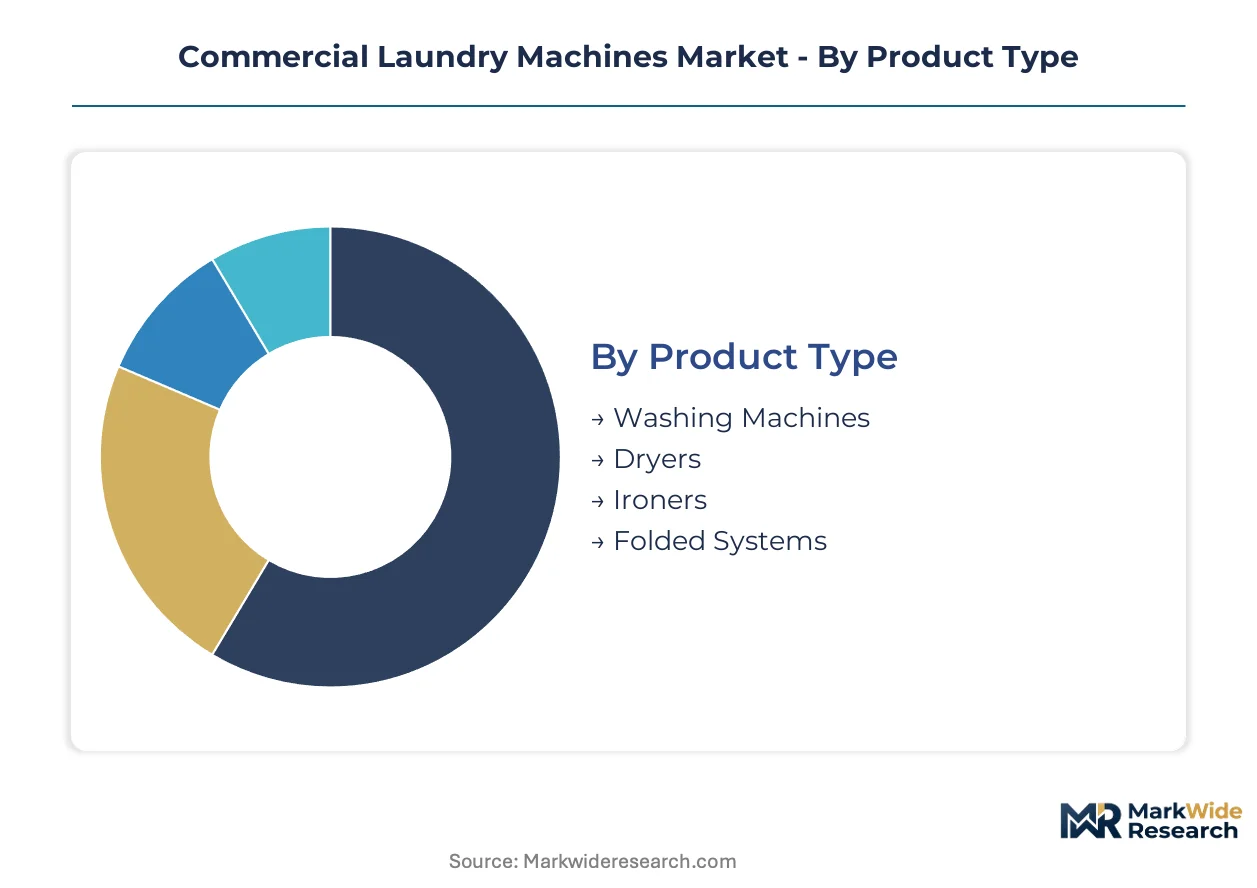
Segmentation in commercial laundry machines reflects divergent capital intensity, regulatory exposure, and operational complexity across buyer types. Equipment specifications vary sharply between healthcare thermal disinfection requirements and hospitality throughput optimization.
Product Type:
Mature hardware categories dominate installed base volumes while emerging system integrations capture replacement premiums.
- Washing Machines:Washer-extractors rated from 20 to 450 pounds capacity form the core revenue foundation, with 304-grade stainless steel drums engineered for alkaline detergent exposure and thermal cycling. Demand concentrates in German industrial laundries serving hospitality chains, where EU Ecodesign Directive efficiency benchmarks accelerate replacement cycles for aging batch equipment.
- Dryers:Heat-pump configurations utilizing hybrid vapor-compression and thermal storage architectures achieve sub-100°F drying temperatures to eliminate fabric damage. Netherlands and German healthcare laundries pilot these systems to satisfy F-Gas Regulation refrigerant phase-down schedules while reducing operational expenditure.
- Ironers:Roller-based finishing equipment with heated chest designs processes flatwork at continuous feed rates for hotel and hospital linen operations.
- Folded Systems:Automated material handling equipment integrates with tunnel washers to reduce labor costs in high-volume central commercial plants.
Washing machines retain volume leadership; folded systems hold the steepest expansion curve.
End User:
Application-specific compliance requirements fragment procurement specifications across verticals.
- Hotels:On-premise laundry facilities in branded properties prioritize throughput consistency and fabric finish quality to maintain linen lifecycle economics. India hospitality expansion drives demand as international operators enter underpenetrated secondary cities requiring scalable systems.
- Hospitals:US hospital systems prioritize captive processing to meet Joint Commission infection control protocols, bypassing third-party vendors. The US Department of Energy's revised test procedure incorporating cold-water cleaning performance metrics forces recalibration of thermal disinfection-dependent equipment specifications.
- Laundromats:Independent operators face volatile utility rate structures that equipment-as-a-service contracting models address through bundled maintenance and chemical supply.
- Restaurants:Compact washer-extractors with rapid cycle times address space-constrained back-of-house operations with high linen turnover.
Hospitals anchor premium pricing power; laundromats drive volume through fleet standardization.
Technology:
Intelligence layers and thermal efficiency architectures are concentrating margin pools away from mechanical hardware.
- Smart Technology:IoT sensor networks enable remote diagnostics and predictive maintenance algorithms that create recurring revenue streams for equipment vendors. North American metropolitan markets show fastest uptake where operators lack in-house technical staff.
- Steam Technology:Direct steam injection systems accelerate heating cycles in industrial configurations, though infrastructure requirements limit deployment to facilities with existing boiler capacity.
- Energy-Efficient Systems:Heat-pump dryers and optimized mechanical action profiles reduce utility consumption as electricity and water costs escalate across European and North American installations.
- Industrial Controllers:Programmable logic systems manage tunnel washer sequencing and water extraction optimization in continuous-batch operations.
Smart technology captures margin expansion; energy-efficient systems face regulatory tailwinds.
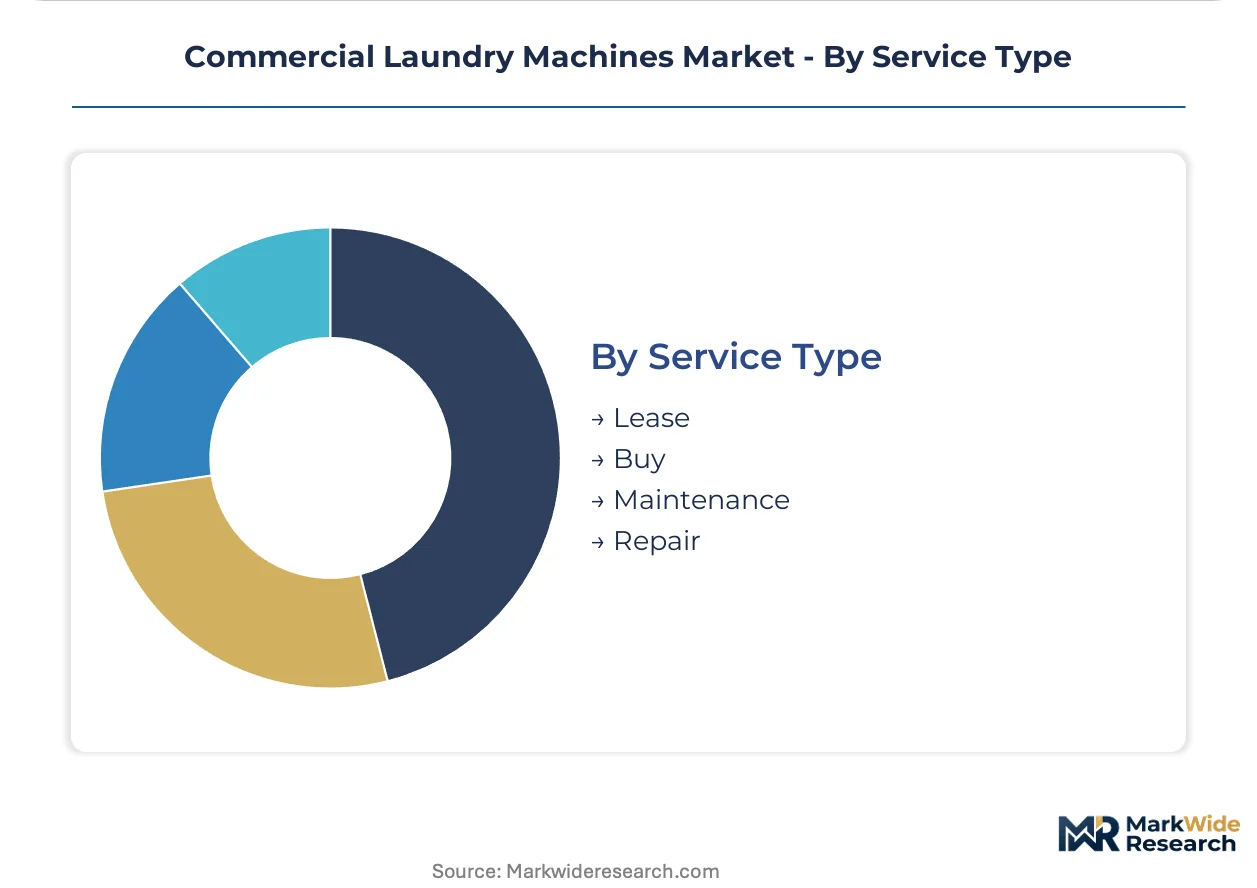
Service Type:
Procurement model diversification reflects working capital constraints and technical capability gaps among buyer segments.
- Lease:Equipment-as-a-service contracting displaces capital purchases among mid-scale operators, with distributors retaining ownership and bundling maintenance into per-pound processed fees.
- Buy:Direct acquisition persists among large hospital systems and industrial laundries with dedicated technical staff and predictable volume profiles.
- Maintenance:Service contracts address mechatronics technician scarcity by outsourcing combined mechanical-electrical-software servicing requirements.
- Repair:Break-fix services concentrate in aging installed base segments where replacement economics remain unfavorable.
Buy transactions dominate absolute value; lease arrangements expand most quickly among capital-constrained operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial laundry corridor while cost-sensitive procurement dominates India's emerging hospitality belt. This asymmetry fragments manufacturer margin structures across geographies. Equipment specifications diverge sharply between EU regulatory compliance and developing-market volume scaling.
United States
Hospital systems in Texas and Florida drive on-premise laundry expansion as Joint Commission infection protocols tighten. The US Department of Energy's revised commercial washer test procedure forces cold-water performance optimization alongside thermal disinfection capability. Chicago and Atlanta clusters host distributor networks bundling equipment-as-a-service contracts for independent laundromat operators.
Germany
Industrial laundries serving hospitality chains in North Rhine-Westphalia accelerate replacement cycles under EU Ecodesign Directive benchmarks. The F-Gas Regulation constrains refrigerant choices for heat-pump dryer configurations across Baden-Württemberg manufacturing zones. Munich and Hamburg anchor premium equipment demand where precision-engineered washer-extractors command specification loyalty from healthcare procurement teams.
India
Branded hotel chains entering secondary cities in Maharashtra and Karnataka require scalable on-premise systems with rapid installation timelines. The Bureau of Indian Standards efficiency labeling program creates compliance thresholds for imported equipment. Delhi-NCR and Bengaluru concentrate distributor activity where international operators negotiate fleet-standardization contracts.
Netherlands
Healthcare laundries in Randstad cities pilot hybrid vapor-compression dryers to satisfy F-Gas phase-down schedules while reducing fabric damage. National carbon reduction targets accelerate utility optimization investments across central commercial plants. Eindhoven's equipment testing facilities validate heat-pump thermal storage architectures for export certification.
Japan
Compact washer-extractor designs address space-constrained urban hotels in Tokyo and Osaka where footprint efficiency determines procurement decisions. METI energy efficiency standards tighten operational expenditure calculations for replacement equipment. Nagoya's industrial machinery cluster supplies precision drive components to regional OEM assembly operations.
Commercial Laundry Machines Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in motor, control, and drum fabrication. The vendor base organizes around three functional layers: full-system providers bundling installation and service, equipment fabricators focusing on batch or continuous configurations, and subsystem suppliers delivering programmable logic and sensor networks. Consolidation pressure operates selectively—hospital and industrial laundry segments favor established service infrastructures while laundromat channels accommodate fragmented distributor relationships. Dominant competitive moves include geographic expansion through dealer network acquisition and technology licensing for smart diagnostics integration.
Among European-headquartered platform providers, JENSEN-GROUP and GIRBAU occupy positions emphasizing tunnel washer and continuous-batch system architectures. Alliance Laundry Systems anchors the North American distribution-intensive model through captive dealer relationships spanning metropolitan and secondary markets. These three exemplify divergent strategic postures: European engineering specialization versus American geographic coverage density versus Iberian industrial laundry focus.
| Leading Market Players |
|---|
| JENSEN-GROUP |
| Pellerin Milnor Corporation |
| Alliance Laundry Systems |
| Herbert Kannegiesser |
| Dexter Laundry |
| Electrolux Professional |
| GIRBAU |
| American Dryer Corporation |
| Miele & Cie |
| Others |
Value Chain & Pricing Dynamics
North Rhine-Westphalia's industrial laundry corridor concentrates washer-extractor fabrication capacity, feeding pricing power downstream to German OEMs serving hospitality chains under EU Ecodesign compliance pressure. Stainless steel drum input costs from Chinese mills and motor assemblies from Nagoya suppliers compress margin flexibility for equipment fabricators facing buyer consolidation.
Pricing Analysis
Configured-to-order pricing for tunnel washer systems commands substantial premiums over standard washer-extractor configurations. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because nickel price volatility on 304-grade stainless steel drums squeezes fabricator margins. Laundromat operators exhibit highest price sensitivity, while hospital procurement teams prioritize infection control compliance over unit economics.
Supply Chain Analysis
Supplier-financing facilities from Chinese motor manufacturers extend payment terms for European OEMs assembling drive systems. Component sourcing draws from China for high-torque industrial motors, Japan for precision drive components, and Germany for programmable logic controllers. Single-source vulnerability clusters in Chinese manufacturing zones for motor production. Distribution runs through captive dealer networks in North America and direct-to-plant relationships in European industrial laundry corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracting represents a substitution threat that incumbent manufacturers must neutralize before capital-light models capture mid-scale laundromat volume.
For Market Incumbents: Entrench service infrastructure density in metropolitan hospital clusters where Joint Commission compliance requirements lock in captive processing relationships. Deepen backward integration into 304-grade stainless steel drum fabrication to buffer nickel price volatility. Prioritize ISO 10472 multi-jurisdiction certification investment to compress 8-14 month product launch timelines.
For New Entrants and Emerging Players: Establish a beachhead in India's secondary city hospitality expansion where international hotel operators require rapid-install on-premise systems with localized service support. Target equipment-as-a-service partnerships with regional distributors lacking technical staff. Deploy IoT-enabled remote diagnostics as a differentiated go-to-market angle against legacy capital-sale incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized laundry equipment divisions lacking smart technology integration. Long-term viability hinges on recurring revenue conversion from predictive maintenance platforms rather than transactional hardware sales. Monitor heat-pump dryer adoption velocity in German healthcare laundries as an inflection signal for refrigerant transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Technology Integration | IoT sensor networks enable predictive maintenance revenue streams for North American distributors. |
| Backward Integration | In-house production of 304-grade stainless drums buffers nickel price volatility for washer-extractor manufacturers. |
| Service Contract Expansion | Per-pound processing fees address mechatronics technician scarcity among mid-scale laundromat operators. |
| Heat-Pump Dryer Development | Hybrid vapor-compression architectures satisfy F-Gas Regulation phase-down schedules in EU markets. |
| Geographic Dealer Acquisition | Metropolitan network density captures equipment-as-a-service demand from capital-constrained independent operators. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed equipment manufacturers, and EU regulatory filings. Conversations with maintenance directors at hospital systems, procurement leads at industrial laundries, aftermarket service heads at distributor networks, and plant engineers at central commercial facilities informed demand-side validation. Bottom-up equipment shipment data triangulates against top-down capital expenditure surveys across the analysis window.
Forecast inputs incorporate washer-extractor replacement cycles, heat-pump dryer adoption curves, and equipment-as-a-service penetration rates across the projection horizon. Segmentation dimensions model product type, end-user vertical, technology tier, and service procurement model. CAGRs derive from installed base aging analysis and regulatory compliance-driven turnover acceleration. Industry-specific inputs include F-Gas Regulation phase-down schedules and US Department of Energy test procedure revisions.
Stress conditions across nickel price bands, motor supply disruption scenarios, and tariff exposure thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on replacement cycle compression and efficiency mandate timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Winch Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Global Industrial Parts Washer Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Compact Excavator Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Europe Forklift Rental Market
Construction Equipment
Log Splitters Rental Market